
 US Glass Curtain Wall Market | 2026-2036
US Glass Curtain Wall Market Size, Share, and Industry Trends Forecast 2026-2036
US Glass Curtain Wall Market Insights
Aluminum composite panels is realigning cost structures across mid-rise commercial projects, displacing solid aluminum plate in spandrel zones. Enclos Corp. dominates complex geometric facade engineering for signature towers, while Harmon Inc. leverages its national installation footprint to control project timelines. New Hudson Facades specializes in custom unitized systems for premium residential towers, anchoring its position in the Northeast corridor.
A glass curtain wall is a non-structural outer building envelope comprising aluminum or steel framing, infill glass panels, and pressure-equalized gaskets, engineered to resist wind loads while managing thermal and moisture transfer. Its primary purpose is to maximize natural daylight penetration and create visual transparency without bearing the building's dead load. Unitized systems capture the fastest growth trajectory in the commercial buildings segment, driven by factory-controlled quality and compressed field installation schedules. Stick-built approaches retain share in renovation and retrofitting applications where existing structural constraints preclude prefabricated module delivery.
The Department of Energy's building energy codes and ASHRAE Standard 90.1 mandate progressively lower U-factors for envelope assemblies, compelling manufacturers to invest in triple-glazed and vacuum-insulated configurations. OSHA fall-protection regulations and local facade inspection ordinances in New York, Chicago, and Boston shape maintenance-access design and liability exposure for installation contractors. Stakeholders must weigh capital cost premiums against operational energy savings as electrification mandates tighten performance thresholds across jurisdictions.
Market Dynamics
The Inflation Reduction Act's building performance incentives are compressing procurement cycles for thermally broken curtain wall systems across US commercial construction, forcing developers to front-load envelope specification decisions.
Growth Catalysts
- Inflation Reduction Act incentives:Federal tax credits for high-performance building envelopes are accelerating specification of triple-glazed unitized systems in mixed-use developments.
- Texas and Florida construction clusters:Sunbelt migration patterns are concentrating demand for integrated glazing solutions in Dallas, Houston, Miami, and Tampa metro corridors.
- OSHA fall-protection mandates:Stricter maintenance-access regulations are driving replacement demand for older stick-built facades lacking integrated anchor points.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot cost swings disrupt project budgeting for unitized system fabricators serving mid-rise commercial segments.
- Spandrel zone substitution:Aluminum composite panels are capturing specification share from solid aluminum plate in non-vision areas, compressing margin pools for specialty metal fabricators.
- Skilled installer scarcity:Journeyman glazier shortages in Northeast and Midwest markets extend field installation timelines beyond developer hold periods.
Strategic Opportunities
- Vacuum-insulated glazing convergence:Integration of vacuum-insulated panels with conventional unitized framing creates ultra-low U-factor assemblies for net-zero commercial towers.
- Retrofit channel expansion:Deep energy retrofit mandates in New York, Chicago, and Boston are opening stick-built replacement workflows for aging 1970s-1980s curtain wall stock.
- Factory-controlled quality positioning:Off-site fabrication of unitized modules addresses labor scarcity while compressing critical path schedules for general contractors.
Industry Challenges
- ASHRAE 90.1 compliance timelines:Progressive U-factor mandates require concurrent engineering of glazing, framing, and thermal break systems within compressed design windows.
- Facade inspection ordinance fragmentation:New York, Chicago, and Boston each maintain distinct periodic inspection regimes, multiplying compliance overhead for national installation contractors.
- Legacy system integration:Renovation projects face structural constraint mismatches when inserting prefabricated modules into existing steel or concrete frame buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Glass Curtain Wall Market |
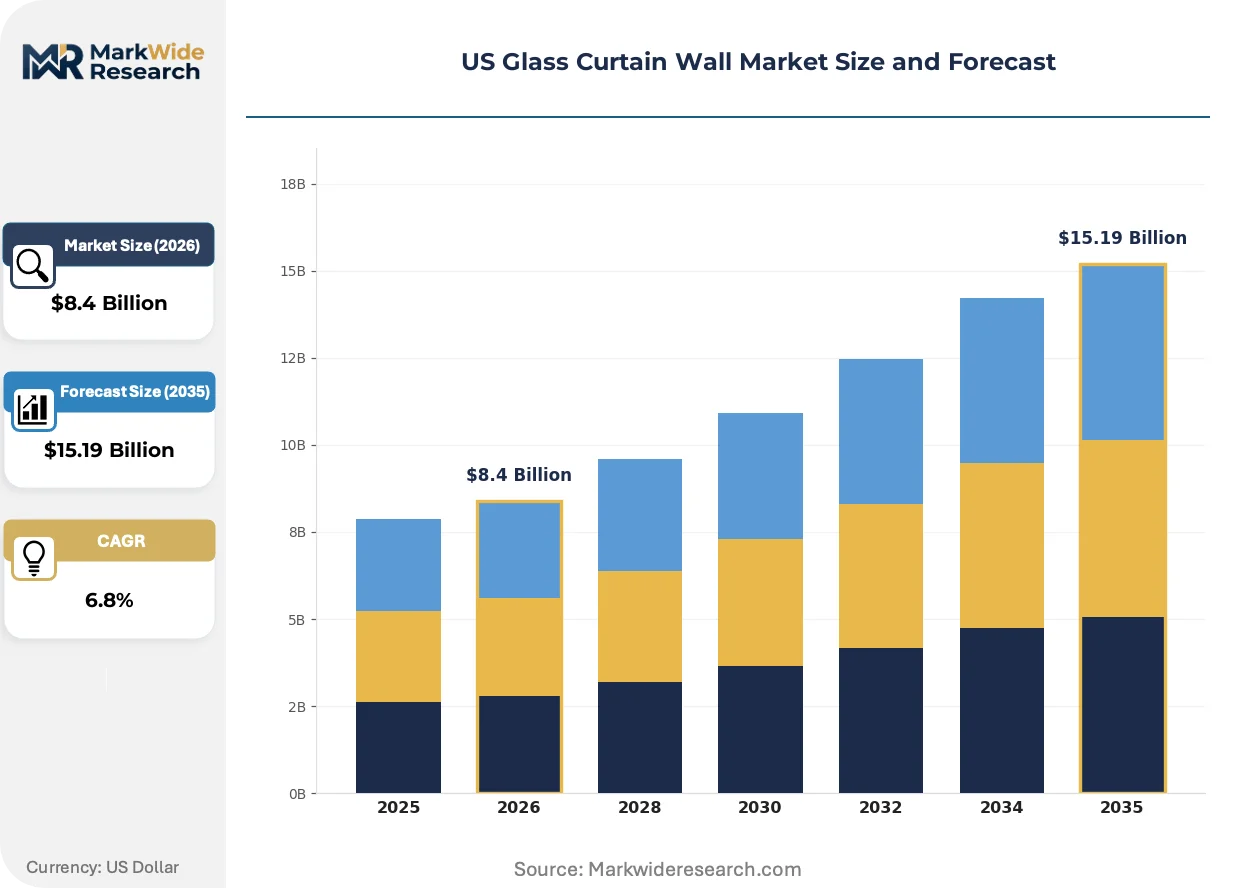
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unitized, Stick Built, Semi-Unitized, Hybrid End Use: Commercial Buildings, Residential Buildings, Institutional Buildings, Mixed-Use Developments Material: Aluminum, Glass, Steel, Composite Installation Type: New Construction, Renovation, Retrofitting, Expansion |
| Companies Covered | W&W Glass LLC, Flynn Group of Companies, Harmon Inc., Permasteelisa, Crown Corr Inc., New Hudson Facades, Enclos Corp., Architectural Glass and Aluminum Co., Reflection Window + Wall, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Glass Curtain Wall Market Trends and Innovations
Envelope engineering is pivoting toward factory-integrated performance systems that compress field labor dependency while meeting tightening thermal mandates across US jurisdictions.
Vacuum-insulated glazing is consolidating specification share in premium commercial towers seeking sub-U-0.20 performance without triple-pane weight penalties. Manhattan and Chicago developers are embedding these assemblies into unitized modules during pre-construction phases. The technology is consolidating supplier relationships around vertically integrated fabricators capable of coordinating vacuum seal integrity with aluminum extrusion tolerances.
The Department of Energy's building energy codes and ASHRAE Standard 90.1 mandate progressively lower U-factors for envelope assemblies. These requirements are compelling manufacturers to invest in triple-glazed and vacuum-insulated configurations ahead of code adoption cycles. Commercial high-rise construction in Manhattan and Chicago is accelerating adoption of thermally broken systems to preempt compliance deadlines.
Developers in Texas and Florida are prioritizing integrated glazing solutions that bundle envelope performance with accelerated construction schedules. General contractors are unbundling traditional design-bid-build workflows in favor of design-assist contracts with specialized facade engineers. This pattern concentrates most visibly in mixed-use developments where lease-up timing determines project financing viability.
US Glass Curtain Wall Market Segmentation
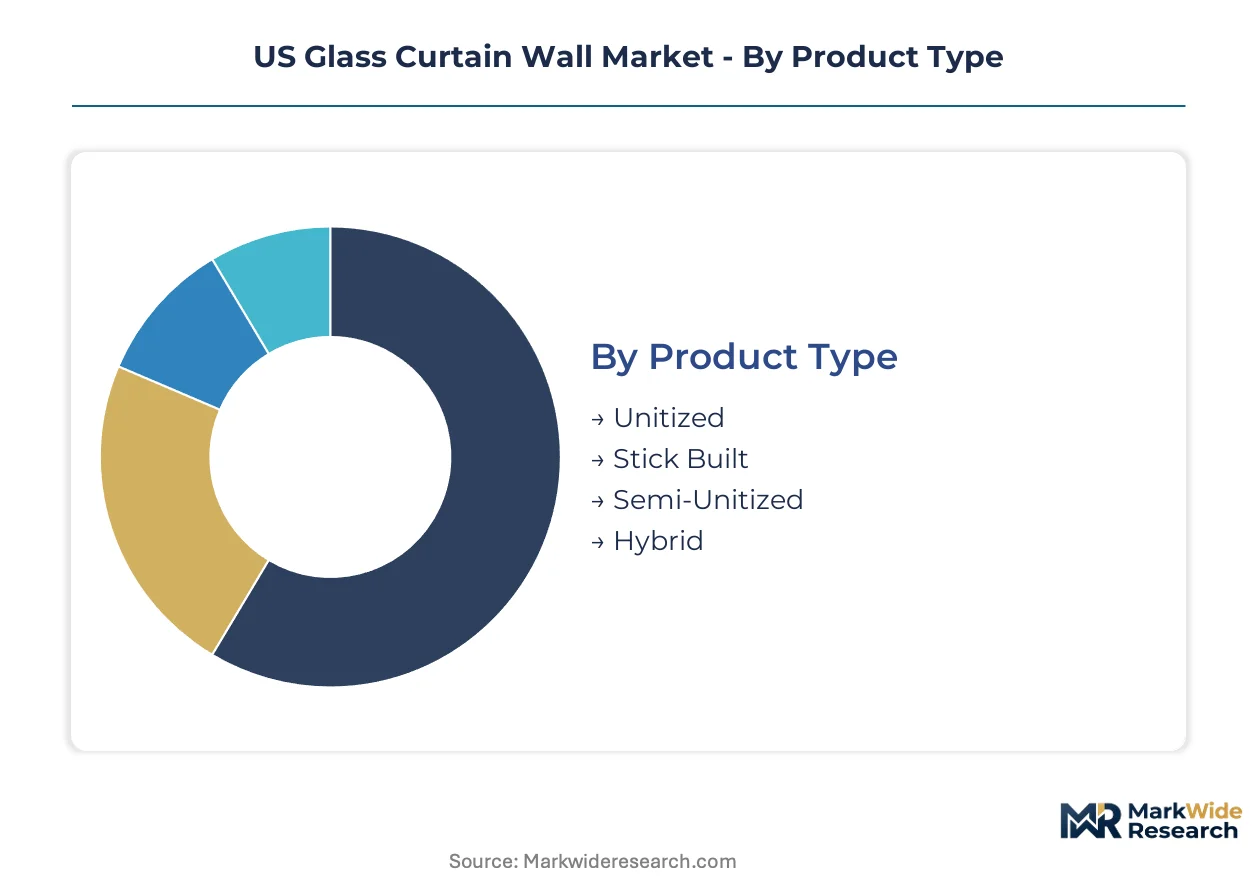
Curtain wall procurement decisions in the US hinge on four intersecting axes: fabrication methodology, building typology, structural material, and project delivery mode. Each axis carries distinct cost, schedule, and performance implications that reshape competitive positioning across the value chain.
Product Type:
Factory-integrated fabrication methods are compressing field labor dependency while stick-built approaches retain renovation flexibility.
- Unitized:Pre-assembled modules integrate glazing, framing, and gaskets under factory-controlled conditions. Demand concentrates in Manhattan and Chicago commercial towers where OSHA fall-protection mandates and compressed construction schedules favor off-site quality assurance.
- Stick Built:Field-assembled mullions and transoms accommodate irregular structural constraints. Applications cluster in Boston and New York retrofit workflows where existing steel frames preclude prefabricated module insertion.
- Semi-Unitized:Hybrid approach pairs factory-glazed vision panels with field-installed framing members.
- Hybrid:Custom configurations blending unitized and stick-built elements for complex geometric facades.
Mature deployment sits with Stick Built systems in renovation corridors. Newer deployment is concentrated in Unitized modules for ground-up commercial construction.
End Use:
Building typology dictates thermal performance thresholds, maintenance access requirements, and lease-up timing pressures.
- Commercial Buildings:High-rise office towers drive specification of thermally broken assemblies with sub-U-0.30 performance. Texas and Florida developers prioritize integrated glazing solutions that accelerate certificate of occupancy timelines.
- Mixed-Use Developments:Programs combining retail podium with residential tower require fire-rated spandrel transitions and acoustic isolation. These projects in Dallas, Houston, and Miami metro corridors are gaining share fastest as sunbelt migration concentrates.
- Residential Buildings:Premium towers in the Northeast corridor specify custom unitized systems with triple-glazed configurations.
- Institutional Buildings:Universities and hospitals emphasize lifecycle durability and maintenance access integration.
Volume leadership belongs to Commercial Buildings. Steepest expansion trajectory is occurring in Mixed-Use Developments where financing viability depends on accelerated lease-up.
Material:
Structural material selection balances weight, thermal conductivity, and supply chain resilience against aluminum price volatility.
- Aluminum:Dominant framing material for unitized systems, though primary ingot cost swings disrupt project budgeting for mid-rise commercial fabricators.
- Composite:Aluminum composite panels are capturing specification share from solid aluminum plate in spandrel zones, compressing margin pools for specialty metal fabricators.
- Glass:Vacuum-insulated and triple-glazed configurations command premium positioning for net-zero commercial towers.
- Steel:Structural backup and reinforcement in high-wind-load applications.
Cost pressure is most acute in Aluminum. Performance differentiation is concentrating in Glass and Composite combinations.
Installation Type:
Project delivery mode determines regulatory exposure, labor sourcing, and integration complexity with existing building stock.
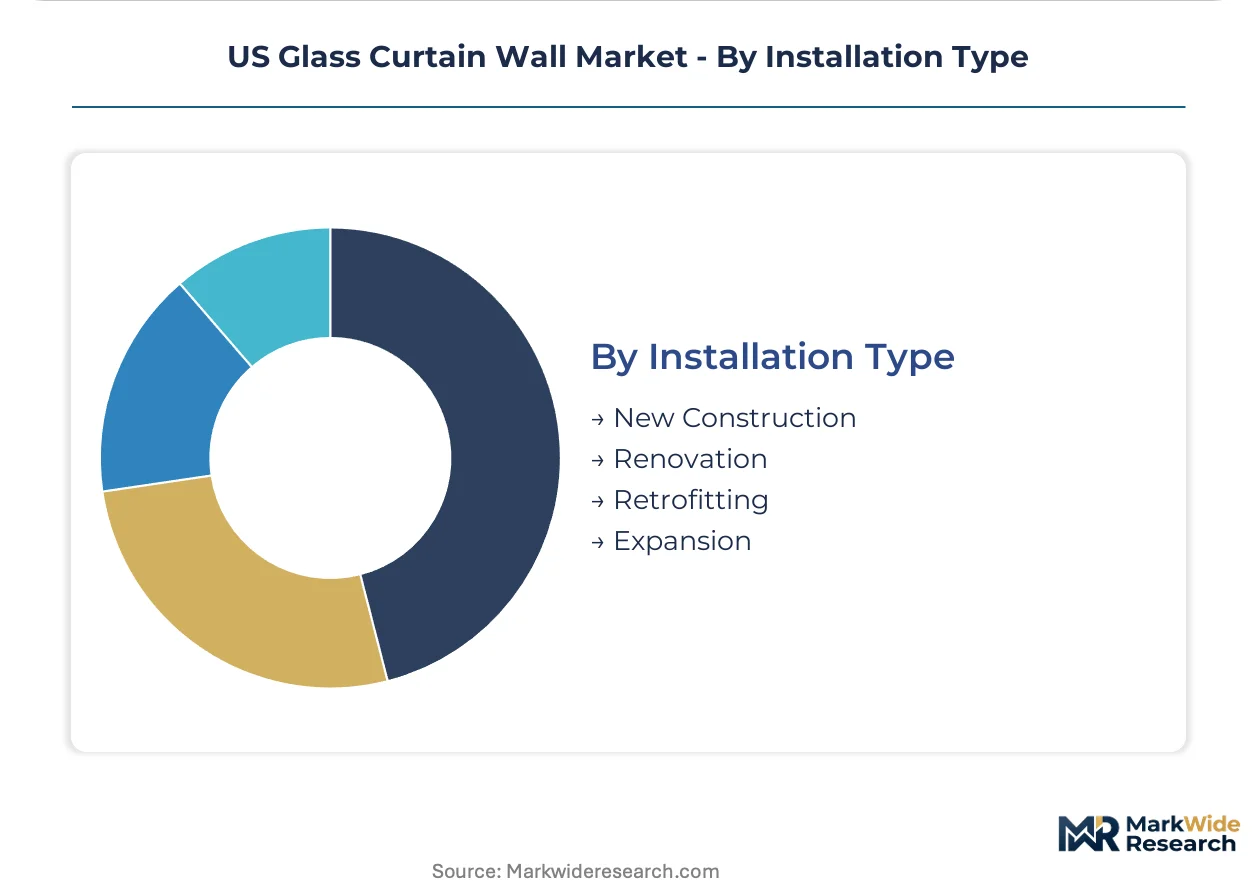
- New Construction:Ground-up projects enable full design-assist integration with facade engineers, concentrating in Texas and Florida mixed-use corridors.
- Retrofitting:Deep energy retrofit mandates in New York, Chicago, and Boston are opening replacement workflows for aging 1970s-1980s curtain wall stock.
- Renovation:Partial facade replacement with constrained structural access.
- Expansion:Vertical or horizontal additions requiring thermal and structural continuity with existing envelopes.
Capital allocation favors New Construction. Regulatory tailwinds are strengthening Retrofitting as local facade inspection ordinances tighten compliance obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and Florida are compressing procurement cycles for thermally broken curtain wall systems as developers race to secure federal tax advantages before construction deadlines. These incentive structures are redrawing the geographic concentration of facade engineering talent and fabrication capacity across the Sunbelt.
Texas
Dallas and Houston mixed-use towers are driving specification of integrated glazing solutions that bundle envelope performance with accelerated certificate-of-occupancy timelines. The Inflation Reduction Act's building performance incentives are reshaping procurement criteria for facade assemblies in these corridors. Local fabrication clusters in the Dallas-Fort Worth metroplex are expanding unitized module production to serve regional demand.
Florida
Miami and Tampa commercial high-rises are accelerating adoption of thermally broken systems to meet stringent wind-load requirements and thermal performance thresholds. The state's building code updates are compelling developers to front-load envelope specification decisions during pre-construction phases. Installation contractors are concentrating capacity in South Florida to capture recurring demand from luxury residential towers.
New York
Manhattan commercial towers and Brooklyn mixed-use developments are retrofitting aging 1970s-1980s curtain wall stock under local facade inspection ordinances. OSHA fall-protection regulations are driving replacement demand for older stick-built facades lacking integrated anchor points. Fabricators serving the Northeast corridor are specializing in custom unitized systems for premium residential towers.
Illinois
Chicago commercial high-rise construction is accelerating specification of vacuum-insulated glazing configurations to achieve sub-U-0.20 performance without triple-pane weight penalties. The city's periodic facade inspection regime is multiplying compliance overhead for national installation contractors. Local engineering firms are embedding these assemblies into unitized modules during pre-construction phases.
Massachusetts
Greater Boston institutional and commercial renovation projects are opening stick-built replacement workflows where existing steel frames preclude prefabricated module insertion. ASHRAE Standard 90.1 compliance timelines are requiring concurrent engineering of glazing, framing, and thermal break systems. Regional contractors are developing specialized expertise in constrained structural access environments.
US Glass Curtain Wall Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with complex geometric facade engineering commanding premium positioning against standardized unitized module production. The vendor base organizes around three archetypes: national installation platforms controlling project timelines, custom unitized system fabricators serving premium residential towers, and complex geometric specialists anchoring signature commercial developments. Competitive dynamics center on design-assist contract capture and factory-controlled quality positioning that compresses field labor dependency.
Among national installation platforms, Harmon Inc. exemplifies scale-driven timeline control across dispersed project portfolios, while Enclos Corp. occupies the complex geometric engineering tier for signature towers. New Hudson Facades represents the custom unitized specialization archetype, anchoring premium residential positioning in the Northeast corridor. These three patterns illustrate how competitive differentiation maps to project delivery mode, fabrication methodology, and geographic concentration rather than undifferentiated scale alone.
| Leading Market Players |
|---|
| W&W Glass LLC |
| Flynn Group of Companies |
| Harmon Inc. |
| Permasteelisa |
| Crown Corr Inc. |
| New Hudson Facades |
| Enclos Corp. |
| Architectural Glass and Aluminum Co. |
| Reflection Window + Wall |
| Others |
Pricing and Supply Chain Analysis
Primary aluminum ingot cost swings cascade through unitized system fabricators serving mid-rise commercial segments, compressing margin pools for specialty metal fabricators while creating three-tier pricing stratification across premium thermally broken assemblies, standard double-glazed configurations, and economy stick-built alternatives.
Pricing Analysis
Short lead-time premiums command substantial uplifts for unitized modules delivered within compressed construction schedules, while spot inventory of standard aluminum extrusions trades at discounts to contract-based procurement. Price differentiation hinges on thermal performance certification tiers and customization levels for complex geometric facades. Cost compression in mid-rise commercial segments is intensifying because aluminum composite panels displace solid aluminum plate in spandrel zones. Mixed-use developers in Texas and Florida demonstrate highest price sensitivity, whereas Manhattan signature tower developers prioritize performance over unit cost.
Supply Chain Analysis
OSHA fall-protection certification and ASHRAE 90.1 compliance documentation gate supplier access to commercial high-rise projects, creating qualification barriers for unverified fabricators. Supply concentrates in domestic aluminum extrusion facilities, Mexican component assembly operations, and Canadian primary metal production. Raw material dependencies encompass primary aluminum ingot, low-iron glass substrates, and polyamide thermal break strips. Single-source vulnerability sits with vacuum-insulated glazing seal technology controlled by limited qualified suppliers. Distribution runs through design-assist contracts with national installation platforms controlling project timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US glass curtain wall market functions as a cost-of-compliance arena where ASHRAE Standard 90.1 progressive U-factor mandates erect barrier-to-entry moats favoring fabricators with pre-certified thermal break systems and established regulatory relationships.
For Market Incumbents: Extend factory-controlled quality positioning into vacuum-insulated glazing integration to capture net-zero commercial tower specifications before code adoption cycles tighten. Defend against aluminum composite panel substitution in spandrel zones by anchoring premium positioning through design-assist contract capture with signature tower developers. Capacity addition in Dallas-Fort Worth metroplex fabrication clusters addresses Sunbelt demand concentration while compressing logistics exposure. For New Entrants and Emerging Players: Capture deep energy retrofit workflows in New York, Chicago, and Boston where local facade inspection ordinances drive replacement demand for aging 1970s-1980s stick-built stock lacking integrated anchor points. The most penetrable segment is constrained structural access renovation projects requiring field-assembled mullions and transoms. Go-to-market angle centers on specialized expertise in OSHA-compliant maintenance-access integration for legacy building envelopes. For Investors and Strategic Acquirers: Accelerating specification of triple-glazed unitized systems in mixed-use developments is the leading indicator that vacuum-insulated glazing convergence will consolidate supplier relationships around vertically integrated fabricators. Long-term viability favors acquisition targets with captive aluminum extrusion capabilities and pre-certified thermal break assembly lines. The signal to monitor is design-assist contract penetration rates with Texas and Florida general contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of primary framing material insulates margin pools from LME volatility. |
| Vacuum-Insulated Glazing Certification Program | ASHRAE 90.1 pre-compliance positioning secures specification share in net-zero towers. |
| Design-Assist Contract Expansion | Early envelope integration with general contractors compresses procurement cycle exposure. |
| Retrofit Channel Specialization | OSHA fall-protection mandate compliance creates recurring replacement revenue streams. |
| Sunbelt Fabrication Footprint | Dallas and Miami proximity reduces logistics costs for Texas and Florida construction clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across facade engineers, installation contractors, general contractor procurement leads, and aluminum extrusion plant managers. Bottom-up project pipeline analysis triangulated against top-down construction spending data from Census Bureau and Dodge Construction Network. Stakeholder validation incorporated ASHRAE code development committee perspectives and OSHA compliance officer assessments.
Granularity-level modeling deployed unit-level analysis for commercial high-rise, mixed-use, residential, and institutional building typologies, with additional dimensioning by fabrication methodology and thermal performance tier. CAGRs derived from regression analysis against construction starts, code adoption timelines, and incentive program enrollment trajectories. Industry-specific forecast inputs encompassed aluminum price futures curves and local facade inspection ordinance implementation schedules across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Inflation Reduction Act incentive continuity and ASHRAE 90.1 adoption pacing across jurisdictions. Model assumptions reflect documented regulatory trajectories and construction labor availability projections. A model refresh is warranted upon material change in primary aluminum ingot cost volatility or federal building performance tax credit structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Bamboo Engineered Wood Market