
 Global Venous Blood Collection Devices Market | 2026-2036
Global Venous Blood Collection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Venous Blood Collection Devices Market Intelligence
Polypropylene is consolidating its position over traditional PVC in vacuum tube manufacturing as healthcare systems prioritize leachate-free sample integrity. Becton, Dickinson and Company leverages its integrated polymer compounding capabilities to control supply continuity across North American and European distribution networks. Greiner Bio-One International GmbH anchors its competitive stance through specialized co-extrusion technology for serum separator tubes. Sekisui Chemical Co., Ltd. dominates Asian supply chains with vertically integrated resin-to-device production in Japan and Thailand.
Venous blood collection devices encompass sterile instruments engineered to extract blood from peripheral veins through calibrated needle gauges and evacuated tube systems maintaining precise vacuum pressure for volumetric accuracy. These devices serve clinical diagnostics, transfusion medicine, and biorepository operations where pre-analytical sample quality determines downstream analytical validity. Vacuum tubes command the largest product volume pool due to universal compatibility with automated analyzer lines, while safety-engineered butterfly needles represent the fastest-expanding category as OSHA needlestick prevention mandates tighten across US hospital systems. Diagnostic testing applications absorb the majority of device throughput, though blood banking generates premium pricing through specialized additive formulations and sterility assurance levels.
FDA quality system regulations and EU MDR conformity requirements are elevating barrier-to-entry thresholds for new manufacturers seeking US and European market access, particularly around biocompatibility testing and post-market surveillance obligations. ISO 13485 certification has become a non-negotiable procurement criterion for institutional buyers across OECD healthcare systems. Stakeholders must monitor evolving polymer substitution timelines and regulator-driven material disclosure requirements as sustainability criteria penetrate medical device purchasing frameworks.
Market Dynamics
Polymer substitution timelines and regulator-driven material disclosure requirements are compressing supplier margins while elevating technical qualification barriers for vacuum tube manufacturers serving OECD healthcare systems.
Growth Catalysts
- EU MDR traceability mandates:Material disclosure requirements for polymer-based collection systems are forcing suppliers to upgrade quality management systems, locking in compliant incumbents and reducing price competition.
- OSHA needlestick prevention enforcement:US hospital systems face escalating penalties for safety-engineered device non-compliance, accelerating safety butterfly needle procurement cycles.
- Centralized laboratory networks:India's private hospital chains are scaling automated phlebotomy workflows, creating volume concentration that favors suppliers with regional distribution infrastructure.
Market Restraints
- Petrochemical input volatility:Polypropylene and specialized additive formulations face feedstock price swings that compress margin predictability for tube manufacturers.
- Asian resin supply concentration:Vertically integrated producers in Japan and Thailand control critical polymer supply chains, creating bottleneck risk for Western device assemblers.
- ISO 13485 certification friction:Extended audit timelines and documentation burdens delay new market entrants from securing institutional procurement eligibility.
Strategic Opportunities
- Biorepository quality tier expansion:Specialized additive formulations for long-term sample preservation command premium positioning in academic and pharmaceutical research segments.
- Leachate-free material transition:Healthcare systems prioritizing sample integrity over unit cost create displacement opportunity for polypropylene against legacy PVC formulations.
- Automated analyzer line integration:Vacuum tube compatibility optimization with high-throughput diagnostic platforms opens specification lock-in with major laboratory equipment vendors.
Industry Challenges
- Biocompatibility testing backlog:FDA and EU MDR post-market surveillance obligations extend product validation timelines, straining R&D resource allocation.
- Legacy analyzer compatibility:New tube formulations must maintain dimensional and performance equivalence with installed base equipment, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Venous Blood Collection Devices Market |
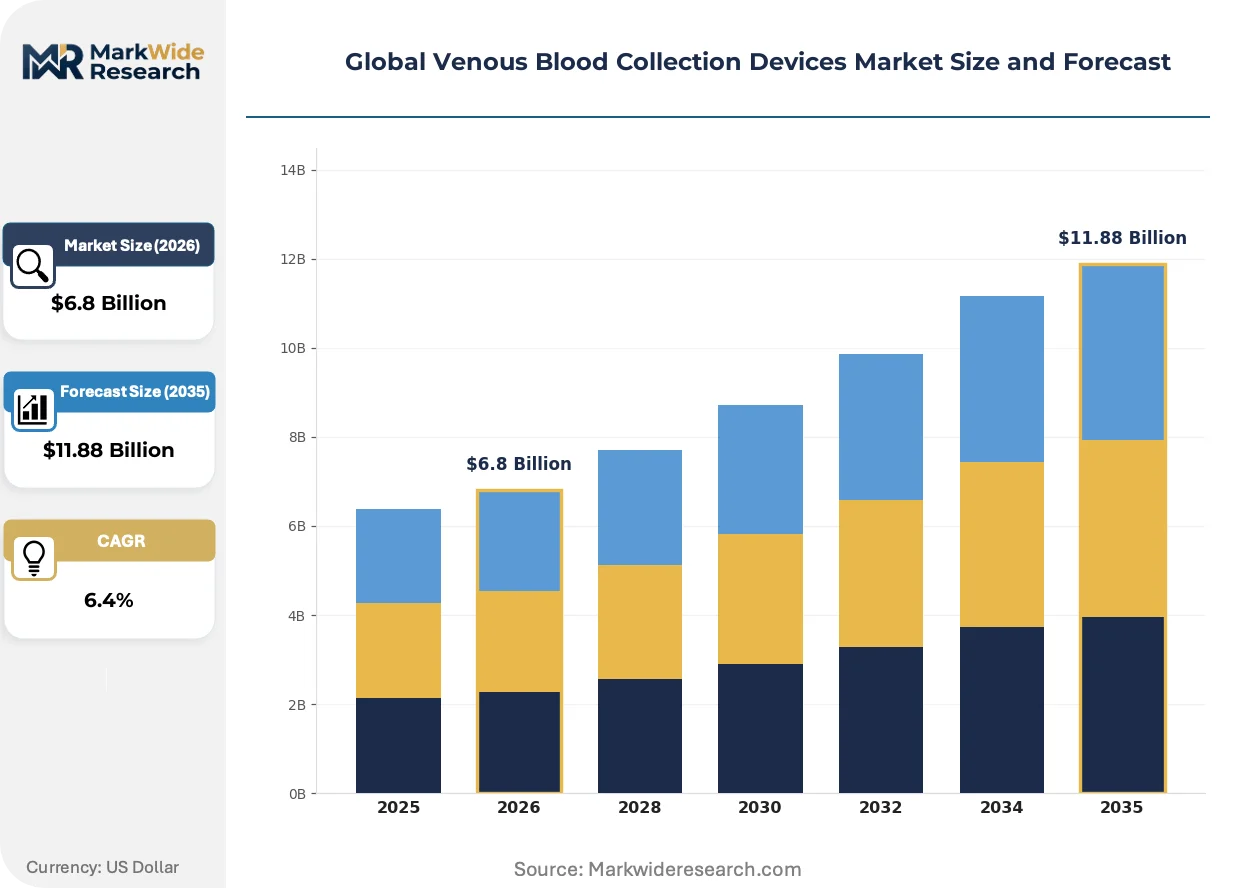
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Tubes, Butterfly Needles, Hypodermic Needles, Syringes, Safety Lancets Application: Diagnostic Testing, Blood Banking, Therapeutic Phlebotomy, Research Studies, Donor Screening End User: Diagnostic Laboratories, Blood Banks, Phlebotomists, Research Institutions, Collection Centers Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, Medical Retailers, Institutional Procurement |
| Companies Covered | Terumo Medical Corporation, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, Bio-Rad Laboratories, Inc., Sekisui Chemical Co., Ltd., Greiner Bio-One International GmbH, NIPRO Medical Corporation, Qiagen NV, Sarstedt AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Venous Blood Collection Devices Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure frameworks are restructuring competitive advantage around polymer purity and supply chain transparency rather than manufacturing scale alone.
Co-extrusion technology for serum separator tubes is expanding into high-volume diagnostic laboratory segments. German and French reference laboratories are adopting these systems to reduce sample hemolysis rates and eliminate manual processing steps. The technology is expanding into standard-of-care positioning previously occupied by basic gel separator tubes, compressing price premiums for differentiated products.
EU MDR material traceability requirements are elevating documentation burdens across polymer supply chains. Device manufacturers must now certify resin sourcing through compounding to finished tube, forcing supplier consolidation and disqualifying smaller compounders. Blood banking applications face the steepest compliance costs due to sterility assurance level documentation requirements.
Diagnostic laboratory procurement is consolidating around multi-year framework agreements with preferred suppliers. India's expanding private hospital chains are displacing spot purchasing with centralized blood collection network contracts that bundle tubes, needles, and safety devices. This concentration is most visible in Mumbai and Delhi metropolitan clusters where laboratory chains operate regional hub-and-spoke collection models.
Global Venous Blood Collection Devices Market Segmentation
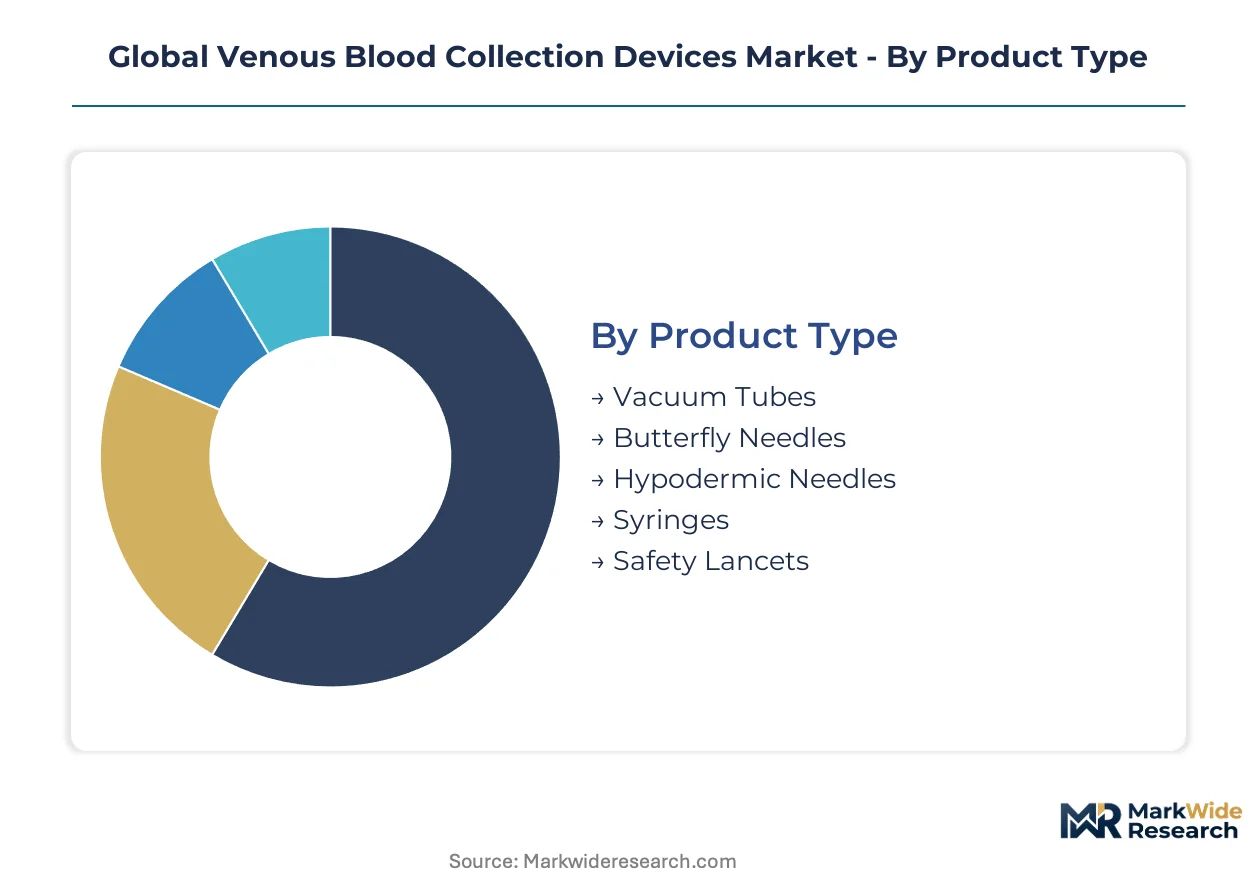
Device selection in venous blood collection pivots on specimen integrity requirements, automation compatibility, and regulatory compliance tiers. Procurement patterns diverge sharply between high-throughput diagnostic networks and decentralized collection sites. Understanding segment interdependencies reveals where specification lock-in and price elasticity concentrate.
Product Type:
Material composition and safety-engineering specifications drive buyer preference more than unit cost in institutional purchasing frameworks.
- Vacuum Tubes:Evacuated glass or polymer tubes maintain calibrated vacuum pressure for precise volumetric blood draw. Diagnostic laboratories in Germany and Japan specify these for automated analyzer line compatibility, with polypropylene formulations displacing PVC for leachate-free sample integrity.
- Butterfly Needles:Safety-engineered winged infusion sets with retractable or shielded needle mechanisms reduce occupational needlestick exposure. OSHA enforcement across US hospital systems accelerates procurement cycles for these devices, which command premium positioning against conventional hypodermic alternatives.
- Hypodermic Needles:Standard bevel-tip steel needles for manual syringe-based collection remain prevalent in cost-constrained settings.
- Syringes:Calibrated barrel-and-plunger systems for precise volume control in therapeutic phlebotomy and pediatric applications.
- Safety Lancets:Single-use activated blade or needle devices for capillary blood sampling in point-of-care glucose monitoring and rapid diagnostic testing.
Volume sits with vacuum tubes; growth tilts toward butterfly needles.
Application:
Downstream analytical requirements determine additive formulation complexity and sterility assurance thresholds.
- Diagnostic Testing:Routine clinical chemistry, hematology, and immunoassay applications consume the largest device throughput. Centralized laboratory networks in India's private hospital chains specify tube systems optimized for high-throughput analyzer platforms, creating volume concentration that favors suppliers with regional distribution infrastructure.
- Blood Banking:Collection and processing for transfusion medicine demands specialized anticoagulant formulations and elevated sterility documentation. EU MDR traceability mandates impose the steepest compliance costs here, as blood banking applications require resin-to-finished-device certification chains.
- Therapeutic Phlebotomy:Scheduled blood removal for polycythemia vera and hemochromatosis management relies on large-volume collection systems.
- Research Studies:Biorepository operations and clinical trials require specialized additive formulations for long-term sample preservation, commanding premium positioning.
- Donor Screening:Pre-donation infectious disease testing and blood type confirmation utilize rapid-turnaround collection protocols.
Diagnostic testing absorbs dominant volume; blood banking generates premium pricing power.
End User:
Procurement sophistication varies from centralized framework agreements to spot purchasing at individual practitioner level.
- Diagnostic Laboratories:High-throughput reference laboratories and hospital-affiliated labs operate automated phlebotomy workflows. France and Germany anchor European demand as these facilities consolidate supplier relationships around multi-year framework agreements bundling tubes, needles, and safety devices.
- Blood Banks:National and regional transfusion services enforce stringent material traceability requirements. These institutional buyers prioritize supply continuity and regulatory documentation over per-unit cost minimization.
- Phlebotomists:Individual practitioners and mobile collection services favor ergonomic safety-engineered devices for occupational protection.
- Research Institutions:Academic medical centers and pharmaceutical research organizations specify specialized formulations for sample biobanking.
- Collection Centers:Hub-and-spoke network nodes in metropolitan clusters like Mumbai and Delhi displace fragmented purchasing with centralized procurement.
Laboratory networks command procurement scale; collection centers are expanding fastest.
Distribution Channel:
Channel selection reflects order size predictability and technical support requirements.
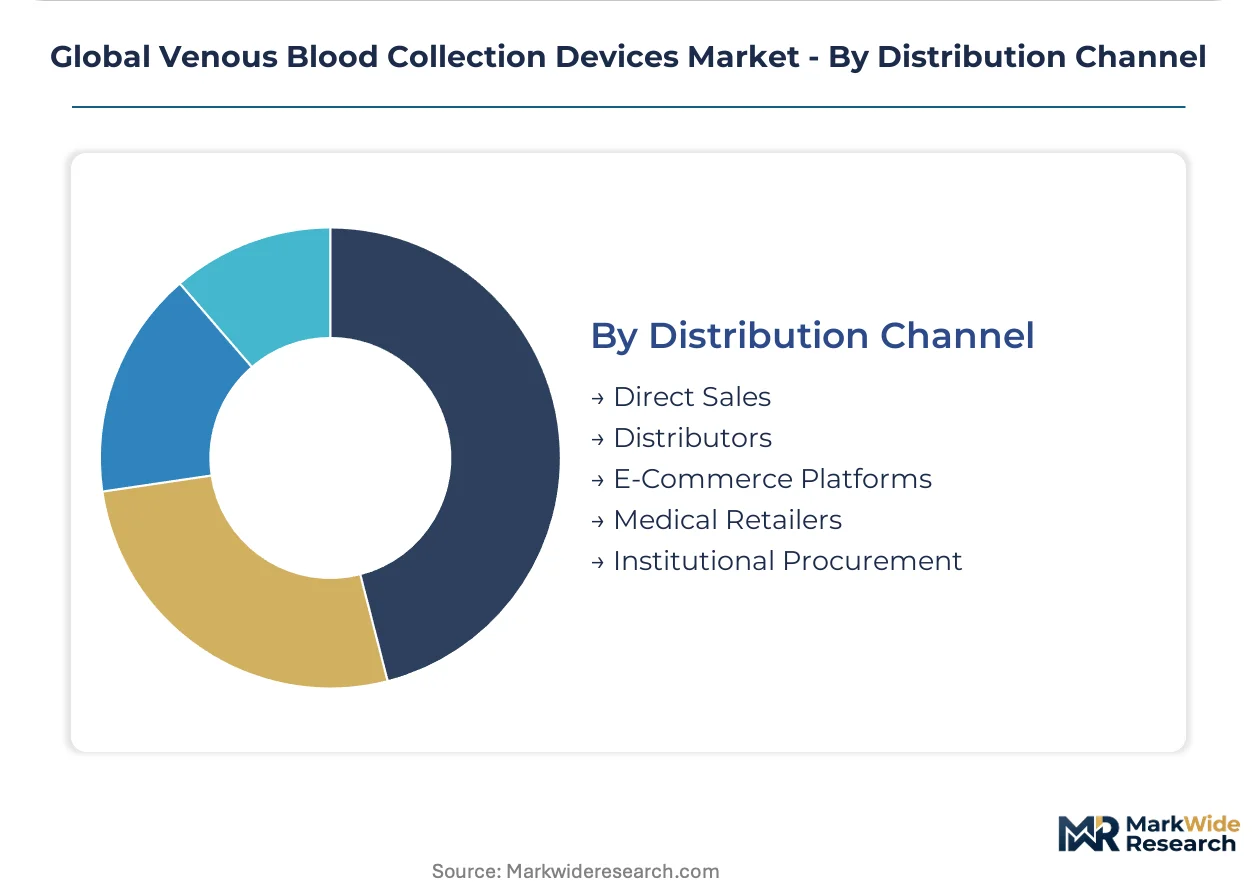
- Direct Sales:Manufacturer-to-institution relationships serve large diagnostic laboratory chains and national blood services. Becton, Dickinson and Company leverages direct channels to control supply continuity across North American and European networks.
- Distributors:Regional medical supply intermediaries aggregate fragmented demand from smaller laboratories and physician offices. Greiner Bio-One International GmbH anchors competitive positioning through specialized distributor partnerships for serum separator tube technology.
- E-Commerce Platforms:Digital procurement portals gain traction among smaller clinics and independent phlebotomy services seeking transparent pricing.
- Medical Retailers:Brick-and-mortar supply stores serve individual practitioners and emergency replenishment needs.
- Institutional Procurement:Group purchasing organizations and centralized hospital system contracts consolidate volume for price negotiation.
Direct sales capture premium accounts; distributor networks extend geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratory networks concentrate procurement power across Germany, Japan, and India, where automated phlebotomy workflows and centralized blood collection infrastructure reshape supplier access requirements.
United States
OSHA needlestick prevention enforcement accelerates safety-engineered butterfly needle procurement across hospital systems. FDA quality system regulations elevate biocompatibility documentation burdens for polymer-based collection devices. The Boston-Cambridge biorepository cluster demands specialized additive formulations for long-term sample preservation.
Germany
Reference laboratories in Munich and Hamburg adopt co-extrusion serum separator technology to reduce sample hemolysis rates. EU MDR traceability mandates force resin-to-finished-device certification chains that disqualify smaller compounders. The Baden-Württemberg medical technology corridor anchors automated analyzer line integration programs.
Japan
Vertically integrated resin-to-device production in Kanto and Kyushu regions controls critical polymer supply chains for Asian markets. PMDA post-market surveillance obligations extend validation timelines for new tube formulations. Tokyo metropolitan diagnostic networks specify vacuum tube systems optimized for high-throughput platforms.
India
Private hospital chains in Mumbai and Delhi displace fragmented purchasing with centralized blood collection network contracts. CDSCO material disclosure requirements gain traction as institutional procurement sophistication rises. The Bangalore laboratory hub operates regional hub-and-spoke collection models bundling tubes, needles, and safety devices.
France
Multi-year framework agreements consolidate supplier relationships around bundled device procurement in Paris and Lyon laboratory networks. ANSM enforces sterility assurance documentation for blood banking applications at elevated compliance cost. The Île-de-France region anchors EU MDR conformity assessment capacity for polymer traceability.
Global Venous Blood Collection Devices Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek polymer supply security and analyzer line specification lock-in. The vendor base clusters around three tiers: integrated resin-to-device producers with captive polymer supply, specialized tube technology licensors with co-extrusion capabilities, and regional assemblers dependent on external resin sourcing. Two archetypes define competitive positioning: vertically integrated compounders controlling material continuity, and technology specialists capturing premium positioning through formulation differentiation. Capacity expansion in Asian resin production and M&A targeting distributor networks represent the dominant competitive moves.
Within the integrated producer tier, Sekisui Chemical Co., Ltd. and Becton, Dickinson and Company exemplify archetypes of supply chain control. Among European technology specialists, Greiner Bio-One International GmbH occupies a position shaped by co-extrusion capabilities for serum separator applications. These three entities represent distinct competitive vectors: Asian vertical integration, North American distribution scale, and European formulation specialization.
| Leading Market Players |
|---|
| Terumo Medical Corporation |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories, Inc. |
| Sekisui Chemical Co., Ltd. |
| Greiner Bio-One International GmbH |
| NIPRO Medical Corporation |
| Qiagen NV |
| Sarstedt AG & Co. KG |
| Others |
Cost & Logistics Intelligence
Diagnostic laboratory networks in Germany, Japan, and India concentrate procurement power through multi-year framework agreements that compress spot-market pricing and lock in volume-tier discounts for compliant suppliers. This buyer consolidation forces manufacturers to absorb feedstock volatility while maintaining ISO 13485 certification premiums.
Pricing Analysis
Volume sits with standard vacuum tubes while margins concentrate in safety-engineered butterfly needles and biorepository-grade formulations. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified blood banking systems from basic diagnostic tubes and unbranded hypodermic alternatives. Cost compression in standard tubes is intensifying because polypropylene feedstock swings outpace contract renegotiation cycles. Price-sensitive procurement dominates India's private hospital chains, whereas blood banks in France and Germany prioritize traceability documentation over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO framework and Japan's PMDA post-market surveillance obligations are reshaping sourcing toward vertically integrated regional producers. Critical polymer supply chains center on Japan, Thailand, and Germany, with specialized additive formulations drawing from petrochemical feedstocks and medical-grade resin compounding operations. Single-source vulnerability runs through Asian resin production controlled by Sekisui Chemical's captive facilities. Distribution runs through direct sales for large laboratory chains and specialized medical distributors for fragmented clinic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a material-transition phase as polypropylene displaces legacy PVC formulations under regulator-driven leachate-free mandates. This substitution wave rewards suppliers with in-house compounding capabilities and disqualifies resin-dependent assemblers.
For Market Incumbents: Hedge against polymer price volatility through backward integration into resin compounding or long-term offtake agreements with Thai and Japanese suppliers. Lock in analyzer line specification partnerships with Roche and Siemens Healthineers to defend against co-extrusion technology challengers. Prioritize EU MDR documentation investments to maintain blood banking eligibility as ANSM enforcement tightens.
For New Entrants and Emerging Players: Regional distributor partnerships in India's Mumbai-Delhi corridor offer the fastest path to volume without direct sales infrastructure. Target biorepository quality tiers in the Boston-Cambridge and Tokyo academic clusters where specialized additive formulations command premium positioning and incumbent lock-in remains incomplete. Lead with leachate-free polypropylene formulations to exploit healthcare system sample integrity priorities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap tube manufacturers with dormant EU MDR certification pathways in Germany and France. Long-term viability hinges on five-to-ten year analyzer line integration durability rather than commodity volume scale. Watch for PMDA validation timeline compression in Japan as the inflection signal for accelerated Asian consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Extrusion Technology Licensing | Greiner Bio-One's serum separator systems reduce hemolysis rates in Munich reference laboratories. |
| EU MDR Certification Investment | Resin-to-device traceability documentation unlocks blood banking procurement in France and Germany. |
| Regional Distribution Partnership | Hub-and-spoke networks in India's metropolitan clusters displace fragmented spot purchasing. |
| Analyzer Line Integration Program | Specification lock-in with high-throughput platforms secures multi-year framework agreements. |
| Biorepository Formulation Development | Specialized additive systems command premium positioning in pharmaceutical research segments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and diagnostic laboratory directors combined with FDA 510(k) submissions, EU MDR technical documentation, and PMDA post-market surveillance reports. Bottom-up modeling of vacuum tube, needle, and safety device volumes triangulated against top-down healthcare expenditure flows across OECD and emerging markets.
Data-stream reconciliation across shipment records, procurement databases, and manufacturer disclosures shaped the analytical framework. Segmentation dimensions modeled include product type, application tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from curve-fitting techniques applied to historical volume trajectories and elasticity-adjusted demand projections. Feedstock price indices and analyzer line installation bases served as industry-specific forecast inputs across the projection horizon.
Caveats apply where EU MDR audit backlogs, polymer supply disruptions, or OSHA enforcement intensity could materially shift the outlook. Forecasts reflect assumptions around certification timeline normalization and healthcare system automation adoption without specific event timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Meniscal Rasps Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Europe C-Arms Market
Medical Devices
Disposable Lancets Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Veterinary Procedure Lights Market