
 Europe C-Arms Market | 2026-2036
Europe C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Europe C-Arms Market Foresight
Flat-panel detector specifications is redrawing competitive dynamics across the Europe C-Arms Market. Siemens Healthineers leverages in-house semiconductor fabrication to control detector yield and image latency. Ziehm Imaging GmbH specializes in mobile surgical configurations that dominate ambulatory settings across German-speaking markets. GE Healthcare anchors its position through extensive service networks that lock in multi-year hospital contracts.
C-Arms are motorized X-ray imaging systems with C-shaped gantries that rotate around the patient, typically operating at 50-120 kV tube voltage with flat-panel detectors replacing legacy image intensifiers for superior spatial resolution in real-time fluoroscopic guidance. Mobile C-Arms command the largest installed base due to their flexibility across hybrid operating rooms and outpatient surgical centers, while 3D imaging technology captures the fastest expansion as orthopedic and neurosurgical procedures demand intraoperative cone-beam computed tomography reconstruction. Digital imaging architectures now form the margin pool where vendors differentiate through software-enabled dose modulation and automated anatomical program selection.
The EU Medical Device Regulation and CE marking framework enforce stricter clinical evidence requirements for Class IIa imaging devices, extending approval timelines and favoring established manufacturers with dedicated regulatory affairs teams. EMA coordination with notified bodies shapes post-market surveillance obligations that drive recurring software validation costs. Stakeholders must weigh capital deployment between detector technology upgrades and compliance infrastructure as procurement consolidation across European hospital networks intensifies vendor selection pressure.
Market Dynamics
The EU Medical Device Regulation is compressing conformity assessment timelines for Class IIa imaging equipment, forcing manufacturers to reallocate R&D budgets toward clinical evidence generation and quality management system upgrades rather than pure hardware innovation.
Growth Catalysts
- Flat-panel detector migration:German university hospitals are accelerating replacement of legacy image intensifiers with solid-state detectors that deliver superior spatial resolution for fluoroscopic guidance during complex orthopedic procedures.
- MDR compliance infrastructure:The EU Medical Device Regulation's stricter post-market surveillance obligations are creating competitive moats for established manufacturers with dedicated regulatory affairs teams and notified body relationships.
- Ambulatory surgical expansion:Outpatient surgical centers across France's public hospital procurement clusters in Paris and Lyon are demanding mobile C-Arm configurations that enable same-day discharge protocols.
Market Restraints
- Xenon detector supply concentration:Specialized semiconductor fabrication for high-purity detector substrates remains concentrated among a limited set of European foundries, exposing lead times to single-source risks.
- MDR clinical evidence costs:The EU Medical Device Regulation's expanded requirements for Class IIa devices are extending approval timelines and inflating pre-market validation expenditures for smaller manufacturers.
- Refurbished system substitution:Secondary market channels for CE-marked refurbished C-Arms are capturing budget-constrained buyers in Southern European markets, pressuring new equipment pricing.
Strategic Opportunities
- 3D imaging white space:Intraoperative cone-beam computed tomography reconstruction remains underpenetrated in Spanish and Italian orthopedic suites, creating first-mover advantages for vendors with software-validated 3D workflows.
- AI-enabled dose modulation:Machine learning algorithms for automated anatomical program selection and real-time dose optimization represent convergence opportunities between imaging hardware and clinical decision support systems.
- Service network unbundling:Independent service organizations are capturing multi-year maintenance contracts from traditional OEM captive service models, particularly in the Benelux region where hospital procurement cooperatives prioritize total cost of ownership.
Industry Challenges
- Clinical engineering talent scarcity:Qualified biomedical engineers capable of servicing hybrid operating room installations are concentrated in Germany and France, leaving peripheral European markets underserved for preventive maintenance.
- Legacy PACS integration complexity:New digital imaging architectures face friction connecting to hospital picture archiving and communication systems that retain proprietary DICOM implementations from prior-generation equipment.
- Notified body capacity bottlenecks:MDR-designated conformity assessment organizations are experiencing application backlogs that delay CE marking timelines and compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe C-Arms Market |
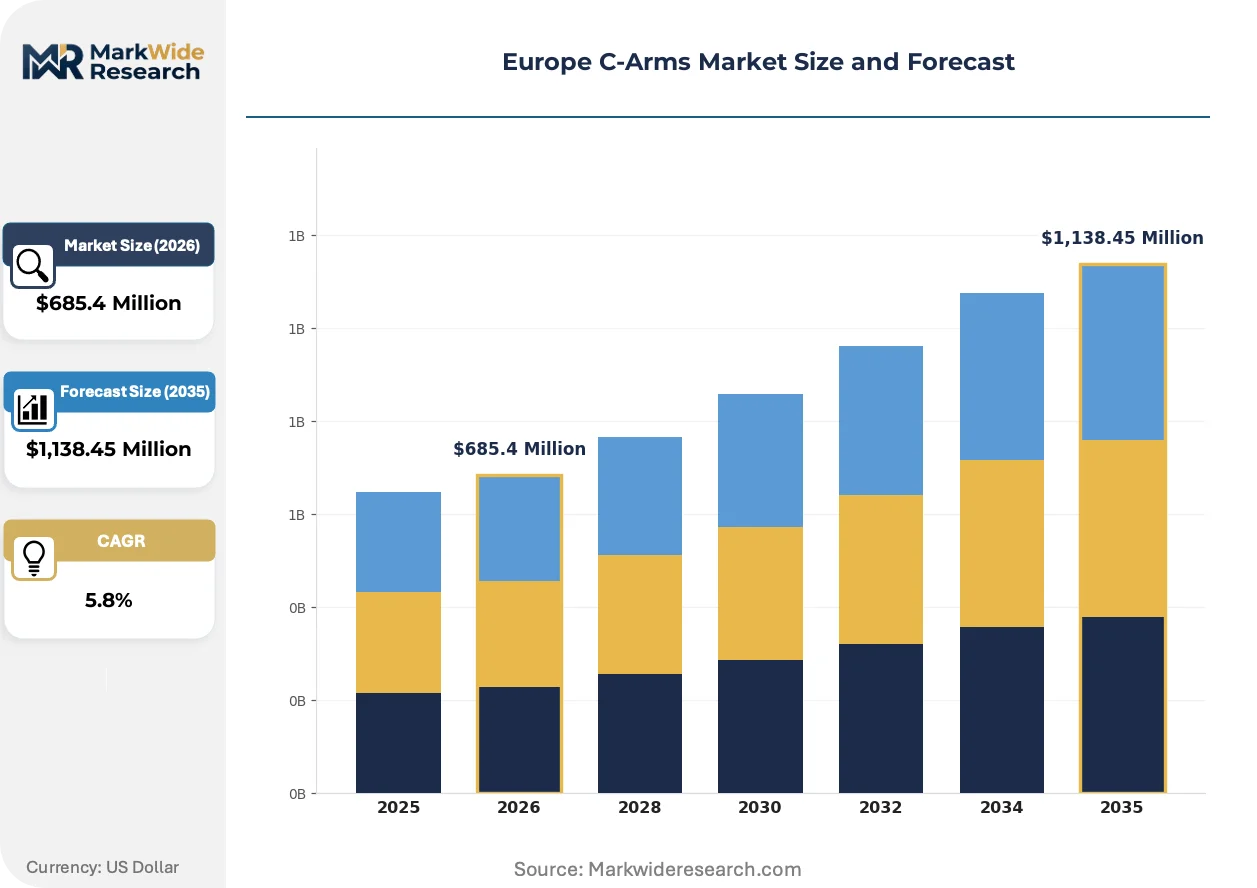
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed C-Arms, Mobile C-Arms, Mini C-Arms, Integrated C-Arms Application: Orthopedics, Cardiovascular, Neurosurgery, Pain Management End User: Hospitals, Outpatient Surgical Centers, Ambulatory Care Centers, Research Institutions Technology: Fluoroscopy, 3D Imaging, Digital Imaging, Contrast-Enhanced |
| Companies Covered | Canon Medical Systems Corporation, GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Ziehm Imaging GmbH, Hologic Inc., Shimadzu Corporation, Fujifilm Holdings Corporation, Genoray Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe C-Arms Market Shifts & Advancements
Software-enabled functionality is displacing hardware specifications as the primary competitive battleground, with automated workflow tools and AI-assisted imaging protocols commanding premium positioning in European procurement evaluations.
CMOS flat-panel detector technology is miniaturizing. These solid-state sensors convert X-ray photons directly to digital signals without intermediate scintillation layers, enabling thinner gantry profiles. Ambulatory surgical centers in German-speaking markets are adopting compact mobile configurations at twice the rate of conventional full-size systems. This miniaturization is compressing facility footprint requirements and enabling C-Arm deployment in outpatient settings previously excluded by spatial constraints.
The EU Medical Device Regulation's post-market clinical follow-up requirements are reshaping vendor business models. Manufacturers must now maintain systematic procedures to collect and evaluate clinical data from devices in active use. Class IIa imaging equipment with software-enabled features faces the steepest compliance burden, driving consolidation of regulatory affairs functions among established players with dedicated notified body relationships.
Hospital procurement cooperatives are consolidating vendor selection authority. France's regional hospital groups and Germany's university hospital alliances are centralizing imaging equipment purchasing decisions, displacing individual facility autonomy. This concentration is most visible in Paris and Lyon, where procurement clusters negotiate multi-year framework agreements that lock in service pricing and upgrade pathways across entire hospital networks.
Europe C-Arms Market Segmentation
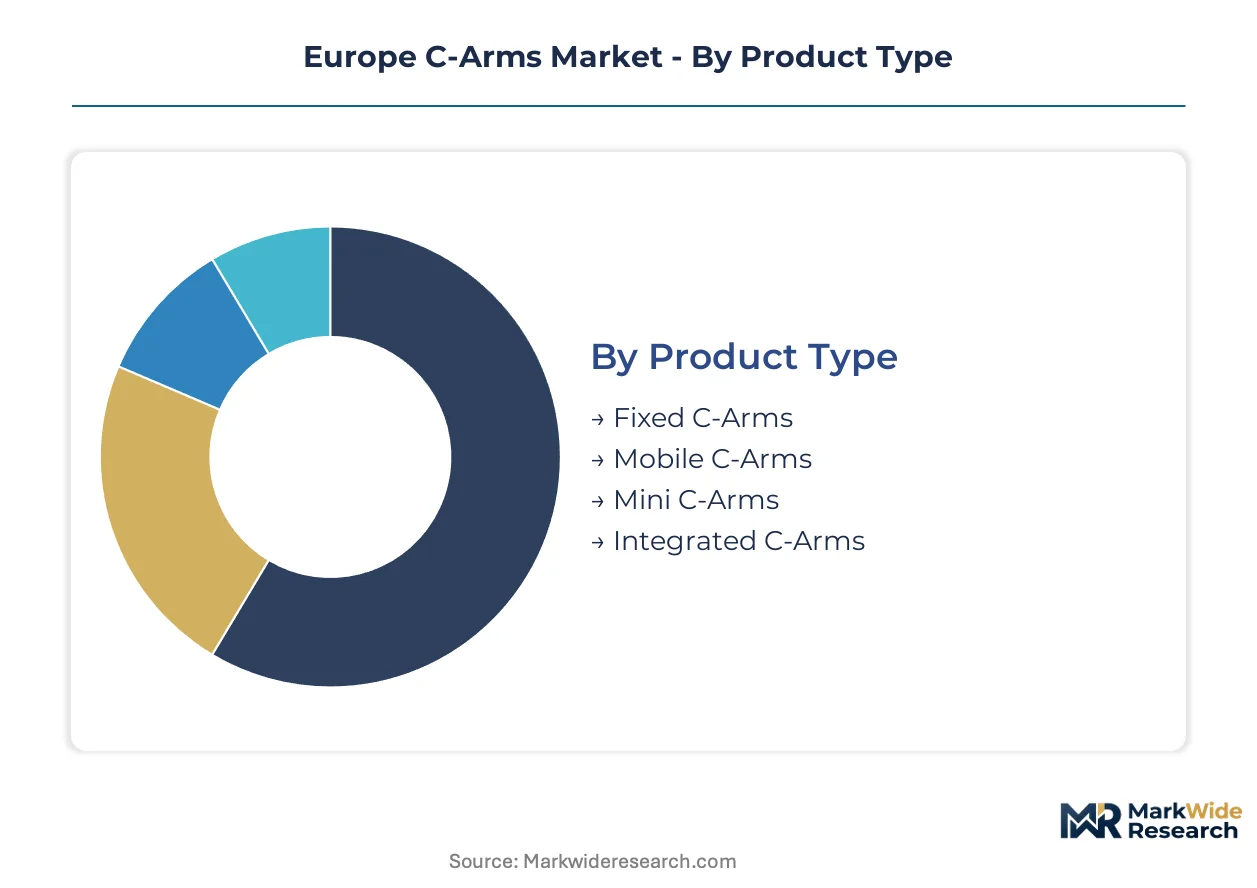
Segmentation in the Europe C-Arms Market reveals how procurement authority concentrates across facility types and how technology tiers map to reimbursement pathways. Understanding these divisions exposes where vendors can defend premium positioning versus where price competition dominates.
Product Type:
Margin pools concentrate in mobile configurations where flexibility commands service contract premiums and upgrade lock-in.
- Fixed C-Arms:Permanent ceiling-mounted or floor-anchored installations deliver the highest tube output and detector resolution for hybrid operating rooms. German university hospital networks in Bavaria and North Rhine-Westphalia are standardizing on these configurations for complex orthopedic and trauma surgery suites.
- Mobile C-Arms:Motorized wheeled gantries with battery power enable intraoperative positioning across multiple procedure rooms. French public hospital procurement clusters around Paris and Lyon are prioritizing mobile units to maximize equipment utilization rates across consolidated surgical networks.
- Mini C-Arms:Compact single-plane imaging systems target extremity surgery and podiatry with reduced footprint and lower dose profiles.
- Integrated C-Arms:Robotic positioning interfaces and surgical navigation coupling serve neurosurgical and spinal fusion workflows.
Mobile C-Arms hold installed capacity. Integrated C-Arms is rotating up the share rankings.
Application:
Orthopedic procedures generate the densest procedure volumes, though cardiovascular applications sustain the longest fluoroscopy durations per case.
- Orthopedics:Trauma reduction, joint replacement, and spinal instrumentation rely on real-time fluoroscopic guidance for hardware placement. German-speaking markets are driving detector specification upgrades as university hospitals replace legacy image intensifiers with flat-panel systems for superior spatial resolution.
- Cardiovascular:Percutaneous coronary intervention and electrophysiology mapping demand extended fluoroscopy runs with precise catheter visualization. The Benelux region's concentration of cardiac catheterization laboratories is pulling premium mobile configurations with advanced dose modulation software.
- Neurosurgery:Intraoperative imaging for tumor resection and vascular malformation treatment requires 3D cone-beam reconstruction capabilities.
- Pain Management:Epidural steroid injection and vertebroplasty guidance utilize lower-specification mobile units in outpatient settings.
Orthopedics anchors procedure volume. Neurosurgery is climbing the fastest as 3D reconstruction validation expands.
End User:
Hospital procurement cooperatives are consolidating vendor selection authority, compressing margins for equipment while extending service contract durations.
- Hospitals:Acute care facilities with hybrid operating rooms and dedicated surgical suites represent the capital-intensive core of demand. France's regional hospital groups are centralizing imaging equipment purchasing decisions across entire networks, displacing individual facility autonomy.
- Outpatient Surgical Centers:Same-day discharge protocols in ambulatory settings are expanding across German-speaking markets at twice the rate of conventional hospital admissions.
- Ambulatory Care Centers:Standalone diagnostic and minor procedure facilities utilize compact mini C-Arm configurations for extremity imaging.
- Research Institutions:University medical centers and clinical trial sites drive early adoption of 3D imaging and AI-enabled workflow tools.
Hospitals retain capital deployment dominance. Outpatient Surgical Centers are gaining share fastest as reimbursement shifts toward site-neutral payment.
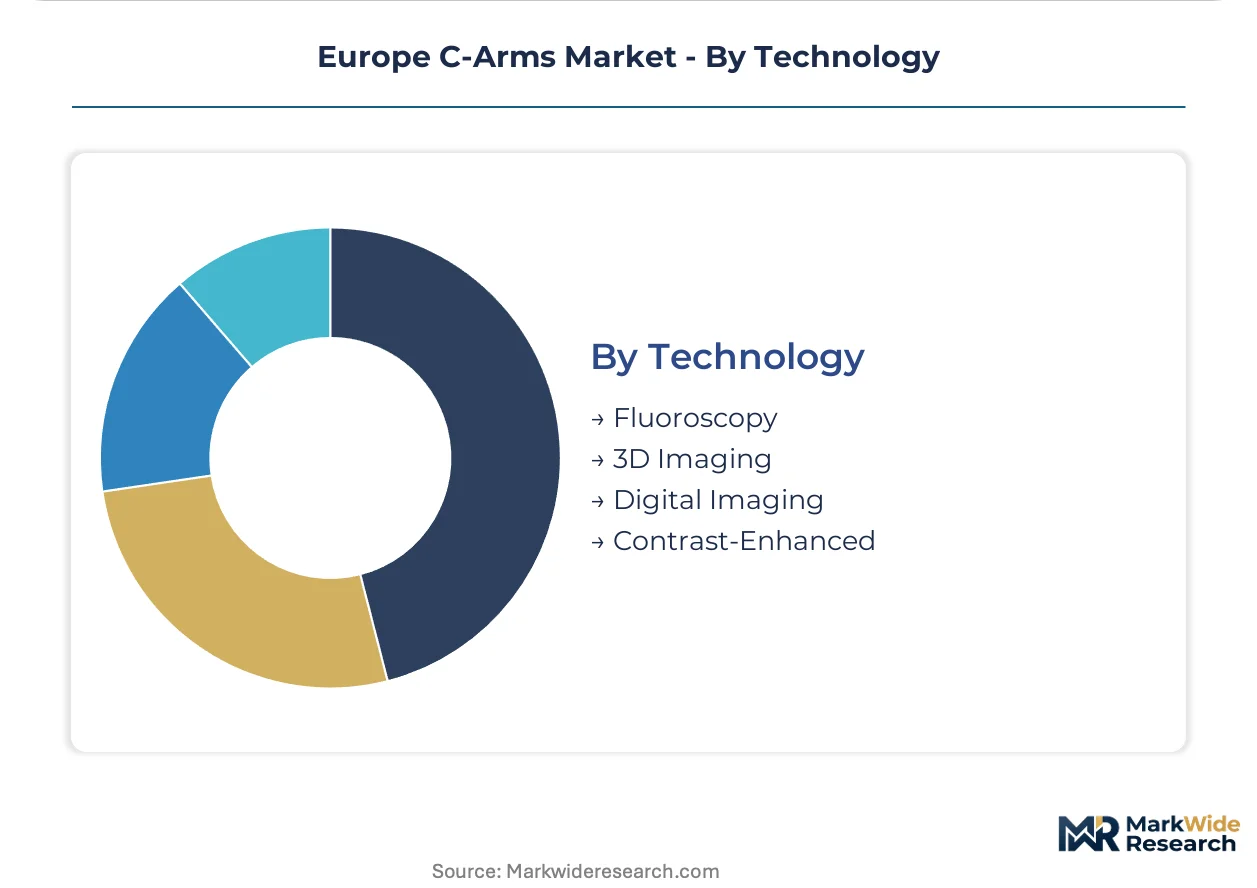
Technology:
Digital architectures now form the primary margin pool where software-enabled functionality displaces hardware specifications as the competitive battleground.
- Fluoroscopy:Continuous X-ray beam imaging with real-time display remains the foundational modality for interventional guidance. Southern European markets show persistent demand for conventional fluoroscopy systems where budget constraints limit premium technology adoption.
- 3D Imaging:Intraoperative cone-beam computed tomography reconstruction enables volumetric navigation during complex spinal and cranial procedures. Spanish and Italian orthopedic suites remain underpenetrated, creating first-mover positioning for validated 3D workflows.
- Digital Imaging:Flat-panel detector architectures with direct photon-to-digital conversion eliminate image intensifier degradation.
- Contrast-Enhanced:Iodinated or gadolinium-based agent protocols for vascular and urological visualization require synchronized injection interfaces.
Fluoroscopy maintains procedure volume leadership. 3D Imaging is expanding most quickly as orthopedic and neurosurgical validation accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector fabrication and regulatory expertise concentrate in Central European industrial corridors, with notified body relationships and university hospital procurement networks creating durable competitive positioning for established vendors.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are standardizing fixed C-Arm configurations for hybrid operating rooms. The EU Medical Device Regulation's CE marking framework extends approval timelines for Class IIa imaging devices, favoring manufacturers with dedicated regulatory affairs teams. Frankfurt and Munich host concentration of notified body relationships that accelerate conformity assessment.
France
Regional hospital groups are centralizing imaging equipment purchasing decisions across entire networks, displacing individual facility autonomy. ANSM coordinates with EMA on post-market surveillance obligations that drive recurring software validation costs. Public hospital procurement clusters around Paris and Lyon negotiate multi-year framework agreements locking in service pricing.
United Kingdom
NHS procurement frameworks are consolidating vendor selection authority for imaging equipment across integrated care systems. MHRA alignment with EU MDR requirements maintains CE marking recognition for market access. London and Manchester medical centers are driving early adoption of 3D imaging workflows for complex spinal procedures.
Italy
Orthopedic suites in Lombardy and Emilia-Romagna remain underpenetrated for intraoperative cone-beam computed tomography reconstruction. The Ministry of Health implements national procurement guidelines that reference EU MDR conformity assessment standards. Milan and Bologna hospital networks are evaluating first-mover positioning for software-validated 3D C-Arm systems.
Spain
Budget-constrained buyers in Madrid and Barcelona are evaluating refurbished CE-marked C-Arms through secondary market channels. The Spanish Agency for Medicines and Health Products enforces MDR-designated clinical evidence requirements for Class IIa devices. Andalusian and Valencian regional health services are prioritizing mobile configurations for ambulatory surgical expansion.
Europe C-Arms Market Competitive Landscape
Concentration sits with diversified health technology conglomerates and specialized surgical imaging firms. The vendor base stratifies across three tiers: integrated conglomerates with in-house semiconductor fabrication, mid-scale specialists in mobile surgical configurations, and regional service-focused distributors. Dominant competitive moves include M&A for regulatory affairs capabilities and strategic partnerships for detector technology access.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify archetypes with captive supply chain control over critical imaging components. Ziehm Imaging GmbH represents the specialized mid-scale tier focused on mobile surgical configurations. These three anchors illustrate how competitive positioning diverges between scale-driven regulatory infrastructure and focused application specialization.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Ziehm Imaging GmbH |
| Hologic Inc. |
| Shimadzu Corporation |
| Fujifilm Holdings Corporation |
| Genoray Co., Ltd. |
| Others |
Supply & Pricing Matrix
CE marking under the EU Medical Device Regulation gates both supply qualification and price differentiation simultaneously, with Class IIa imaging equipment facing extended conformity assessment timelines that inflate pre-market costs and compress margin flexibility for non-compliant vendors.
Pricing Analysis
The EU Medical Device Regulation dictates the pricing tier structure across the Europe C-Arms Market, separating premium configurations with validated 3D imaging workflows from standard fluoroscopy systems and economy-tier refurbished units. Price differentiation rests on detector specification grade and after-sales service bundling, with flat-panel detector architectures commanding substantial premiums over legacy image intensifier systems. Cost compression in the economy tier is intensifying because secondary market channels for CE-marked refurbished equipment are capturing budget-constrained buyers in Southern European markets. Outpatient surgical centers exhibit the highest price sensitivity due to capital constraints, while German university hospital networks demonstrate the least sensitivity given procurement cooperative frameworks that prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Extended lead times for specialized semiconductor substrates are constraining detector fabrication capacity across German, Dutch, and Belgian foundries that supply flat-panel detector components. The supply chain draws from high-purity xenon detector substrates, CMOS sensor wafers, and precision gantry motors as critical inputs. Single-source vulnerability concentrates in specialized semiconductor fabrication for detector substrates, where limited European foundry capacity exposes manufacturers to allocation risk. Distribution runs through hospital procurement cooperatives in France and Germany that negotiate multi-year framework agreements locking in service pricing and upgrade pathways across consolidated surgical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract attach rates are expanding faster than hardware shipments across the Europe C-Arms Market, with multi-year maintenance agreements and software upgrade subscriptions forming the primary recurring-revenue layer for vendors.
For Market Incumbents: Consolidate regulatory affairs capabilities and notified body relationships to defend against MDR compliance cost escalation that disadvantages smaller competitors. Deepen backward integration into flat-panel detector fabrication to control yield and image latency specifications that differentiate premium positioning. Capture hybrid operating room installations in Bavaria and North Rhine-Westphalia through captive service networks that lock out independent service organizations. For New Entrants and Emerging Players: Lead with AI-enabled dose modulation software that converges imaging hardware with clinical decision support systems, bypassing capital-intensive detector fabrication barriers. Target Spanish and Italian orthopedic suites where intraoperative cone-beam CT reconstruction remains underpenetrated, creating first-mover positioning without confronting entrenched incumbent relationships. Pursue independent service organization models in the Benelux region where hospital procurement cooperatives unbundle maintenance from equipment purchases. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale surgical imaging specialists possessing established notified body relationships and mobile C-Arm service networks. Long-term viability across the analysis window favors targets with software-validated 3D workflows and regulatory infrastructure capable of absorbing MDR post-market surveillance obligations. Monitor notified body capacity bottlenecks as an inflection indicator—backlogs that delay CE marking timelines will accelerate consolidation toward established players with dedicated conformity assessment resources.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | MDR-designated conformity assessment accelerates approval timelines for Class IIa imaging devices. |
| Hospital System Partnership | Procurement cooperatives in Paris and Lyon negotiate multi-year framework agreements locking in vendor selection. |
| Software Companion Development | AI-enabled dose modulation algorithms differentiate digital imaging architectures in competitive evaluations. |
| Backward Integration into Detectors | In-house semiconductor fabrication controls flat-panel detector yield and image latency specifications. |
| Reimbursement Strategy | Site-neutral payment expansion favors outpatient surgical centers demanding mobile C-Arm configurations. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at imaging equipment manufacturers, then refined through secondary validation across hospital procurement databases, GPO contract filings, EMA MDR guidance documents, and notified body conformity assessment records. Bottom-up segmentation modeling triangulated with top-down macroeconomic factor analysis.
Variance decomposition across product type, application, technology tier, and end-user facility category shaped the analytical framework over the projection horizon. CAGRs were derived from procedure volume elasticity models and equipment replacement cycle analysis. Forecast inputs incorporated EU Medical Device Regulation compliance cost trajectories and flat-panel detector technology adoption curves specific to orthopedic and neurosurgical suites.
Forecasts assume regulatory continuity in EU MDR and CE marking frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Global Joint Pain Injections Market