
 Meniscal Rasps Market | 2026-2036
Meniscal Rasps Market Size, Share, and Industry Trends Forecast 2026-2036
Meniscal Rasps Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over instrument refurbishment and calibration protocols. Stryker Corporation leverages its arthroscopy platform ecosystem to bundle rasp sales with maintenance contracts. Smith & Nephew anchors its position through specialized sports-medicine distribution channels that reach ambulatory surgery centers directly.
Meniscal rasps are precision arthroscopic instruments with serrated or abrasive working surfaces, typically manufactured from surgical-grade stainless steel or titanium alloy through CNC grinding and electropolishing processes, designed to debride torn fibrocartilage during knee meniscus repair procedures. The single-use segment dominates volume as hospitals prioritize infection control and eliminate reprocessing overhead, while powered technology represents the fastest-expanding margin pool as surgeons adopt battery-operated systems for operative efficiency. Stainless steel retains cost-sensitive share, though titanium rasps command premium placement in high-throughput orthopedic clinics where instrument longevity justifies acquisition price.
The FDA's 510(k) premarket notification framework governs US market entry for meniscal rasps, requiring substantial equivalence demonstrations that extend development timelines for novel designs. The EU Medical Device Regulation's Class IIa classification imposes clinical evaluation and post-market surveillance obligations that reshape competitive economics for European participants. Stakeholders must monitor how notified body capacity constraints and evolving biocompatibility testing standards will redistribute compliance costs across the supplier base.
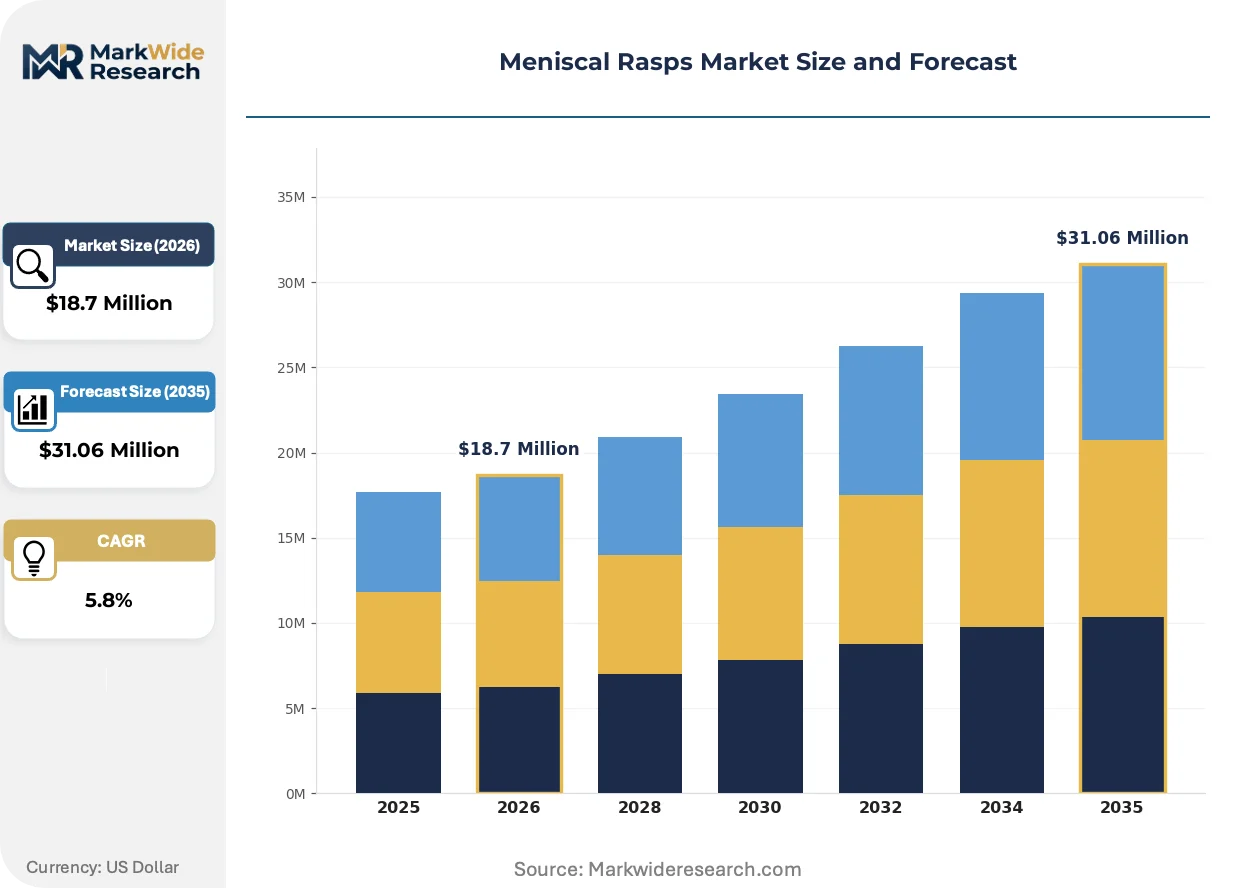
Market Dynamics
Powered rasp systems are compressing operative timeframes and forcing instrument portfolios toward battery-integrated platforms that bundle hardware with recurring consumable revenue.
Growth Catalysts
- EU Medical Device Regulation Class IIa pathway:Post-market surveillance mandates accelerate replacement cycles as hospitals prioritize single-use instruments to minimize reprocessing documentation burden.
- Ambulatory surgery center expansion:Outpatient knee arthroscopy volume concentrates demand for compact, sterilization-independent rasp systems that eliminate central sterile processing dependency.
- Titanium alloy adoption:High-throughput orthopedic clinics in Germany's Tuttlingen cluster justify premium instrument acquisition through extended service life and reduced replacement frequency.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel and chromium input costs fluctuate with commodity markets, squeezing margin on cost-sensitive product tiers.
- Notified body capacity constraints:EU MDR compliance timelines stretch 18-24 months as technical documentation review queues lengthen across European certification organizations.
- Reusable instrument refurbishment economics:OEM-controlled calibration protocols capture aftermarket revenue that independent service providers previously accessed.
Strategic Opportunities
- India's CDSCO streamlined medical device registration:The 2017 Medical Device Rules create lower entry barriers for Class A/B instruments, enabling direct distribution to tier-2 city hospitals.
- Japan's aging surgical workforce:PMDA-cleared powered systems address ergonomic demands from surgeons performing higher annual case volumes with reduced hand fatigue.
- Subscription-based instrument provision:Per-procedure pricing models align hospital procurement with actual utilization, displacing capital-intensive ownership structures.
Industry Challenges
- CNC grinding technician scarcity:Precision instrument manufacturing requires specialized electropolishing and serration expertise that vocational pipelines inadequately replenish.
- 510(k) substantial equivalence documentation:FDA predicate device identification consumes 6-9 months for novel rasp geometries, compressing effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meniscal Rasps Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $31.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Auto-Retractable, Manual Technology: Powered, Handheld, Surgical, Diagnostic End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Sports Institutions Material: Stainless Steel, Titanium, Plastic, Composite |
| Companies Covered | Stryker Corporation, Smith & Nephew, DePuy Synthes (Johnson & Johnson), Zimmer Biomet, Arthrex, Inc., CONMED Corporation, Medtronic, ARCURO MEDICAL, BIOTEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meniscal Rasps Market Strategic Shifts
Battery-operated platforms are redefining operative workflows and procurement economics simultaneously, while regulatory documentation burdens reshape competitive entry costs across jurisdictions.
Radiofrequency-integrated meniscal rasps combine thermal ablation with mechanical debridement in single instrument passes. High-volume orthopedic surgery departments in Germany and the United States adopt these hybrid platforms for complex meniscal tear patterns. Conventional mechanical-only rasps without energy delivery capability are rendering obsolete in premium hospital segments.
The EU Medical Device Regulation's Unique Device Identification mandate takes full effect for Class IIa instruments. Manufacturers must embed machine-readable codes on every device, forcing label redesign and serialization infrastructure investment. European notified bodies are prioritizing audit resources toward UDI compliance verification, delaying novel product certifications.
Hospital procurement departments now unbundle instrument sets from capital equipment purchases, negotiating standalone rasp pricing through group purchasing organizations. Ambulatory surgery centers leverage this fragmentation to source specialized sports-medicine instruments outside traditional vendor lock-in arrangements. This disintermediation is most pronounced in the United States, where ASCs command 40% of knee arthroscopy volume.
Meniscal Rasps Market Segmentation
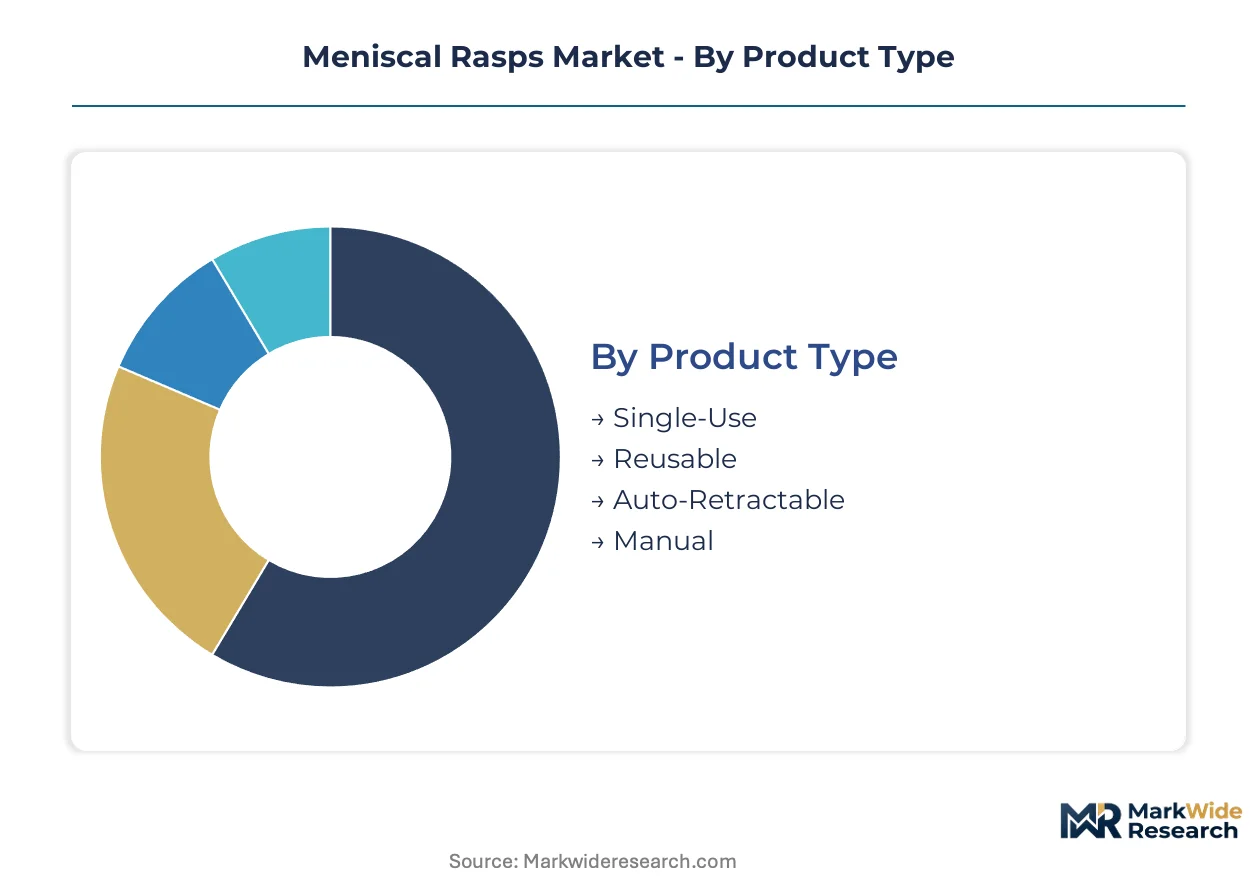
Segmentation in meniscal rasps reveals how procurement priorities diverge across clinical settings and regulatory environments. Material choices and sterilization economics drive purchasing decisions more than brand loyalty in this instrument category.
Product Type:
Mature disposable formats dominate volume while emerging automation features reshape premium positioning.
- Single-Use:Polymer-based instruments eliminate reprocessing documentation and central sterile processing bottlenecks. Hospital infection control departments in Germany's Tuttlingen cluster prioritize these for high-throughput arthroscopy suites where turnover speed determines scheduling capacity.
- Reusable:Surgical-grade stainless steel or titanium alloy rasps withstand hundreds of sterilization cycles when OEM-controlled refurbishment protocols are followed. Orthopedic clinics with captive sterilization infrastructure justify capital investment through per-procedure cost amortization.
- Auto-Retractable:Spring-loaded safety mechanisms reduce sharps injury incidents during crowded arthroscopic procedures.
- Manual:Basic mechanical designs without powered assistance retain placement in cost-constrained ambulatory settings.
Single-Use handles the majority of throughput; Auto-Retractable is the fastest mover on share.
Technology:
Cost tiers separate battery-integrated platforms from handheld mechanical alternatives.
- Powered:Battery-operated rotary or oscillating heads reduce operative time and surgeon fatigue. Japan's aging surgical workforce drives PMDA-cleared system adoption where ergonomic demands outweigh acquisition premiums.
- Handheld:Passive instruments without energy delivery depend entirely on surgeon manual control.
- Surgical:Purpose-built designs for meniscal debridement with optimized serration geometry.
- Diagnostic:Probe-style rasps for tactile assessment before definitive treatment.
Powered commands the steepest expansion trajectory as operative efficiency metrics reshape procurement scoring.
End User:
Customer type determines packaging, pricing, and service attachment strategies.
- Orthopedic Clinics:Specialized sports-medicine facilities demand instrument longevity and rapid replacement logistics. Germany's medical device cluster around Tuttlingen supplies these directly with minimized distribution overhead.
- Hospitals:Integrated delivery networks negotiate through group purchasing organizations with standardized specifications.
- Rehabilitation Centers:Post-operative settings require limited rasp inventory for minor debridement procedures.
- Sports Institutions:Team medical facilities prioritize compact storage and field-portable sterilization options.
Orthopedic Clinics handle the majority of throughput; Sports Institutions are climbing the fastest on share.
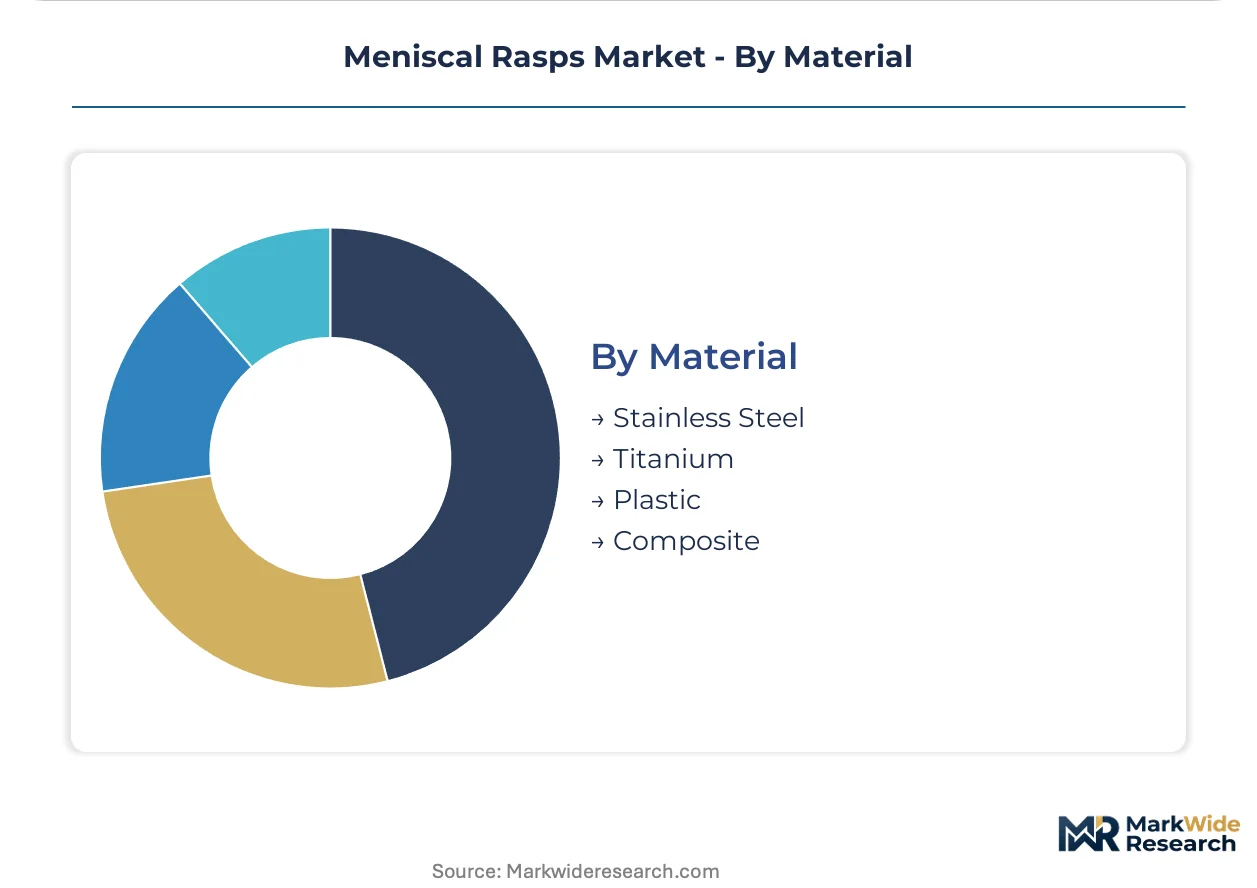
Material:
Margin structure differentiates premium alloys from commodity substrates.
- Stainless Steel:Nickel-chromium alloys provide cost-sensitive durability with established supply chains. Price volatility in commodity metals squeezes margin on economy-tier product lines.
- Titanium:Biocompatible alloy with superior strength-to-weight ratio commands premium placement. High-throughput clinics justify acquisition cost through extended service intervals and reduced replacement frequency.
- Plastic:Single-use polymer formulations for disposable instrument segments.
- Composite:Hybrid material constructions combining metal cutting surfaces with polymer handles.
Stainless Steel handles the majority of throughput; Titanium is gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing clusters in southern Germany and the US Great Lakes region supply the majority of arthroscopy tools. Distribution networks prioritize proximity to high-volume orthopedic surgery centers. Regulatory divergence between FDA and EU MDR pathways shapes regional entry strategies.
United States
Ambulatory surgery centers now perform over 40% of knee arthroscopy procedures, concentrating demand for sterilization-independent rasp systems. The FDA's 510(k) premarket notification pathway requires substantial equivalence demonstrations that extend development timelines for novel geometries. Minneapolis-based distribution hubs serve the Upper Midwest surgical corridor with rapid replacement logistics.
Germany
The Tuttlingen medical device cluster hosts precision instrument manufacturers serving high-throughput orthopedic clinics across Central Europe. EU Medical Device Regulation Class IIa classification imposes clinical evaluation and post-market surveillance obligations that accelerate single-use instrument adoption. Stuttgart-area sterilization service providers support captive reprocessing infrastructure for reusable titanium alloy systems.
Japan
An aging surgical workforce drives PMDA-cleared powered system adoption where ergonomic demands outweigh acquisition premiums. METI's medical device reimbursement frameworks prioritize operative efficiency metrics in procurement scoring. Osaka-based sports-medicine facilities anchor demand for battery-integrated platforms with reduced hand fatigue profiles.
India
CDSCO's 2017 Medical Device Rules created lower entry barriers for Class A/B instruments, enabling direct distribution to tier-2 city hospitals. Maharashtra and Gujarat-based hospital chains expand arthroscopy capacity with cost-sensitive stainless steel rasp procurement. Delhi-NCR orthopedic centers represent the fastest-growing addressable market for disposable instrument segments.
United Kingdom
NHS procurement frameworks unbundle instrument sets from capital equipment purchases, negotiating standalone rasp pricing through national purchasing agreements. The MHRA's post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific approvals. London and Manchester surgical hubs concentrate demand for radiofrequency-integrated hybrid platforms.
Meniscal Rasps Market Competitive Environment
Integrated platform vendors and specialized arthroscopy instrument manufacturers split the market between bundled ecosystem sales and standalone precision tool supply. Tier consolidation favors companies with captive sterilization service networks and direct ambulatory surgery center relationships. Two dominant strategic archetypes emerge: diversified orthopedic conglomerates leveraging cross-portfolio bundling, and focused instrument specialists capturing premium placement through sports-medicine channel depth. Competitive moves center on M&A for regulatory clearance assets and vertical integration into electropolishing capacity.
Among diversified orthopedic conglomerates, Stryker Corporation and Smith & Nephew exemplify platform-ecosystem positioning that bundles instrument sales with maintenance contracts and captive refurbishment protocols. Arthrex, Inc. occupies a specialist archetype, representing focused sports-medicine distribution depth that reaches ambulatory surgery centers outside traditional vendor lock-in arrangements. These three anchors illustrate how scale-driven bundling and channel specialization define competitive differentiation in instrument procurement.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew |
| DePuy Synthes (Johnson & Johnson) |
| Zimmer Biomet |
| Arthrex, Inc. |
| CONMED Corporation |
| Medtronic |
| ARCURO MEDICAL |
| BIOTEK |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in electropolishing facilities across southern Germany is compressing contract manufacturing margins and forcing OEMs toward captive finishing operations that reshape procurement economics for precision instruments.
Pricing Analysis
Aftermarket service revenue from refurbishment contracts and calibration protocols drives lifetime value capture in this category. Three-tier pricing structure across premium, standard, and economy levels separates titanium alloy systems from stainless steel alternatives from polymer disposables, with price differentiation anchored in certification grade and after-sales bundling intensity. Cost compression in economy-tier stainless steel instruments is intensifying because nickel and chromium commodity volatility squeezes margin. Ambulatory surgery centers exhibit highest price sensitivity, while high-throughput orthopedic clinics in Germany's Tuttlingen cluster demonstrate lowest sensitivity due to total-cost-of-ownership calculations.
Supply Chain Analysis
Export-control regimes on precision CNC grinding equipment limit technology transfer to emerging manufacturing hubs and concentrate advanced production capacity. Supply concentrates in Germany, the United States, and Switzerland for finished instruments, with raw material dependencies on Chinese rare earth processing for high-performance alloys, surgical-grade stainless steel from European mills, and polymer feedstocks from Middle Eastern petrochemical complexes. Single-source vulnerability in electropolishing chemical supply creates chokepoint exposure. Distribution runs through orthopedic-focused GPOs and direct ASC relationships in the United States, with regional instrument clusters serving European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-integrated platform economics are displacing standalone instrument procurement, creating ecosystem lock-in effects that favor vendors with captive consumable revenue streams and maintenance infrastructure.
For Market Incumbents: Pre-empt powered system commoditization by securing exclusive distribution through sports-medicine GPOs and backward integration into electropolishing capacity that captures margin from contract manufacturers. Radiofrequency-integrated hybrid platforms from specialized entrants threaten premium positioning; FDA 510(k) clearance assets and PMDA registrations represent critical defensive levers.
For New Entrants and Emerging Players: India's tier-2 city hospital expansion offers the most penetrable white-space target, where CDSCO Class A/B streamlined registration enables direct distribution without legacy vendor relationships. Disposable polymer rasps for cost-constrained settings and subscription-based per-procedure pricing models align procurement with actual utilization patterns.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable instrument segments as polymer molding displaces precision metal grinding. Long-term viability favors targets with regulatory clearance assets in multiple jurisdictions and established ASC channel relationships. PMDA-powered system adoption rates in Japan serve as the critical inflection indicator for ergonomic demand translation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Accelerates market access across European notified body jurisdictions with unified technical documentation. |
| Ambulatory Surgery Center Direct Distribution | Bypasses hospital GPO lock-in and captures 40% of knee arthroscopy volume in the United States. |
| Battery-Integrated Platform Development | Creates recurring consumable revenue and operative efficiency metrics that reshape procurement scoring. |
| Captive Electropolishing Capacity Addition | Secures margin capture from contract manufacturers and insulates against finishing bottleneck risks. |
| Radiofrequency Hybrid System Launch | Addresses complex meniscal tear patterns that render mechanical-only rasps obsolete in premium segments. |
Study Parameters
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data for surgical instrument categories. Bottom-up demand modeling from procedure volume data and top-down supply analysis from manufacturing capacity surveys were triangulated to converge on segment-level estimates.
Demand-supply balance dynamics across powered and handheld technology categories, titanium and stainless steel material tiers, and single-use versus reusable formats shaped the analytical framework over the projection horizon. CAGRs were derived from regression analysis against historical adoption curves and surgical volume projections, with specific inputs including ambulatory surgery center expansion rates and EU MDR transition timelines for Class IIa instruments.
Practitioners should monitor notified body capacity constraints and commodity metal price volatility for early signals of forecast deviation. Forecasts reflect assumptions about regulatory clearance timelines and surgical workforce demographics. Material shifts in FDA predicate device availability or EU MDR biocompatibility testing standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Creatinine Meter Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Medical Goggle Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Global Endodontic Reparative Cement Market