
 Saliva Collection Devices Market | 2026-2036
Saliva Collection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saliva Collection Devices Market Intelligence
Revenue from direct-to-consumer genetic testing kits is reshaping the traditional clinical diagnostics value chain. This shift places a premium on user-friendly, reliable collection systems that ensure sample integrity from home to lab. OraSure Technologies, Inc. leverages its established brand and distribution channels in the at-home testing space. Thermo Fisher Scientific, Inc. dominates the market through its extensive portfolio of life sciences products and global manufacturing scale. Salimetrics, LLC differentiates itself by specializing in high-sensitivity salivary immunoassays for academic and clinical research.
Saliva collection devices are instruments engineered for the non-invasive gathering of oral fluid samples for analysis. These devices frequently incorporate a stabilizing buffer solution to preserve the integrity of nucleic acids, proteins, and other biomarkers until they reach a laboratory. Their primary purpose is to facilitate diagnostics, drug testing, and genetic research without the need for phlebotomy. Complete kits, which bundle swabs or funnels with stabilizing tubes, represent the fastest-growing product category, propelled by demand in diagnostics and genetic testing. This trend corresponds with a notable expansion in the home users segment, altering the end-user market that was once exclusive to clinics and research institutions.
The market operates within a stringent regulatory framework defined by bodies like the FDA in the United States, the CE marking under the Medical Device Regulation (MDR) in Europe, and the NMPA in China. These regulations dictate device classification, manufacturing quality standards, and the clinical data required for market authorization. Adherence to these standards ensures sample quality and diagnostic reliability. Stakeholder success will depend on navigating the divergent regulatory pathways for direct-to-consumer versus professional-use devices across key international markets.
Market Dynamics
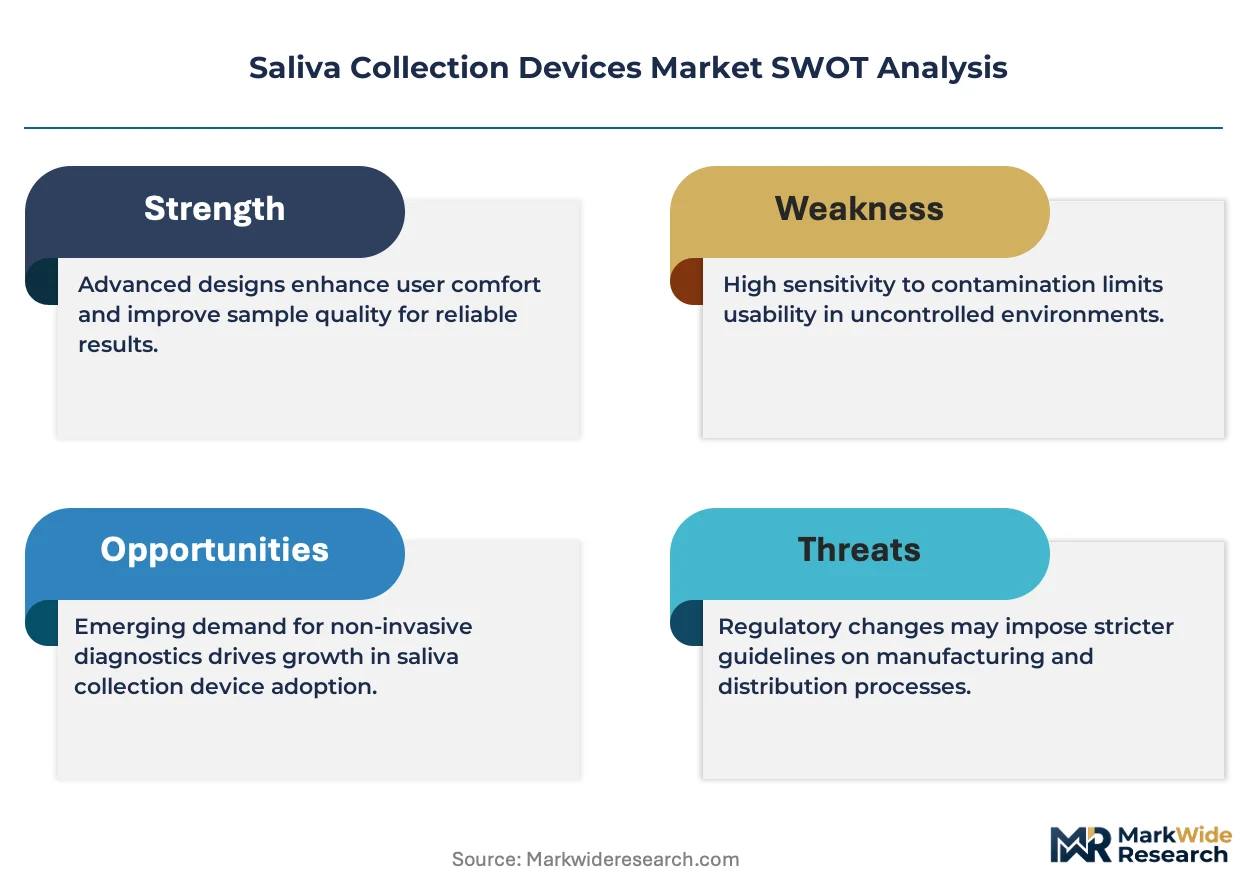
The convergence of consumer-driven healthcare and evolving regulatory frameworks for non-invasive diagnostics is the central force shaping the saliva collection device market. This dynamic is pushing innovation toward user-centric designs that satisfy both home-use simplicity and stringent clinical data requirements.
Growth Catalysts
- Regulatory Support:The FDA's emergency use authorizations and subsequent guidelines for at-home test kits have created a clear regulatory pathway, encouraging development for direct-to-consumer diagnostics in the United States.
- Genomics Expansion:The proliferation of genetic testing for ancestry, wellness, and pharmacogenomics creates sustained demand for reliable, non-invasive DNA sample collection methods suitable for mass-market distribution.
- Material Science Advances:Innovations in stabilizing buffer solutions that preserve nucleic acid and protein integrity at ambient temperatures are critical, reducing the need for cold chain logistics and improving sample viability from remote collection sites.
Market Restraints
- Sample Quality Variability:User error during self-collection, such as improper technique or contamination, can lead to sample rejection or inaccurate results, posing a significant challenge for diagnostic reliability in the home-use setting.
- Clinical Substitution:Blood-based diagnostics remain the gold standard for a wide array of systemic disease monitoring, with established clinical workflows and physician trust limiting the substitution to saliva for certain critical applications.
- Regulatory Fragmentation:Divergent device classification and data requirements between major markets, such as the FDA in the US and the MDR framework for CE marking in Europe, create significant compliance costs and lengthen time-to-market for manufacturers.
Strategic Opportunities
- Infectious Disease Surveillance:Expanding device applications beyond genetic testing into routine, at-home surveillance for respiratory viruses like influenza and RSV presents a major growth avenue, especially in post-pandemic public health initiatives.
- Emerging Market Penetration:Targeting healthcare systems in Latin America and Southeast Asia, where centralized phlebotomy services are less accessible, offers a significant opportunity for non-invasive collection technologies to fill a critical infrastructure gap.
- Digital Health Integration:The convergence of collection devices with smartphone applications to provide guided instructions, track sample shipment, and deliver results directly to the user creates value-added, integrated digital health solutions.
Industry Challenges
- Protocol Standardization:A lack of universally accepted standards for saliva collection and processing complicates the comparison of data across different research studies and clinical trials, hindering biomarker validation efforts.
- Logistical Complexity:Ensuring the integrity of temperature-sensitive stabilizing agents within kits distributed through global direct-to-consumer channels presents a persistent supply chain and quality control challenge.
- Data Security:As collection kits become linked to digital health platforms, ensuring robust data privacy and security in compliance with regulations like HIPAA in the US and GDPR in Europe is a critical operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saliva Collection Devices Market |
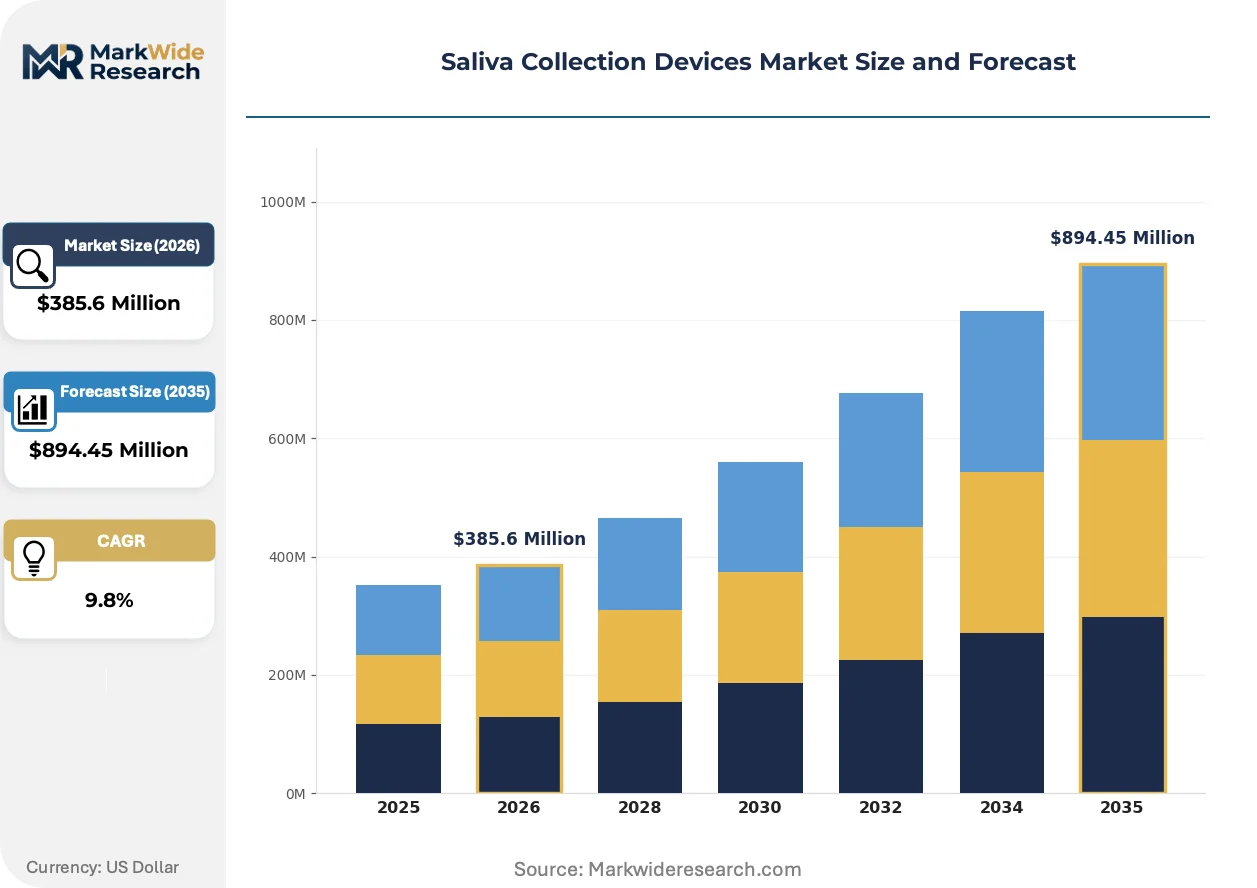
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $894.45 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swabs, Funnels, Tubes, Kits Application: Diagnostics, Drug Testing, Research, Genetic Testing End User: Clinics, Laboratories, Home Users, Research Institutions Material: Plastic, Glass, Silicone, Bio-compatible Materials |
| Companies Covered | OraSure Technologies, Inc., Neogen Corporation, Oasis Diagnostics Corporation, Thermo Fisher Scientific, Inc., Salimetrics, LLC, Porex Corporation, Sarstedt AG & Co, Quest Diagnostics, AboGen, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saliva Collection Devices Market Strategic Shifts & Innovations
The market's evolution reflects a transition from laboratory-centric tools to integrated components of a decentralized, consumer-facing healthcare ecosystem. This shift is driven by product innovations enabling more complex analyses and by new business models that bypass traditional clinical channels.
Advanced stabilizing buffers now preserve a wider spectrum of analytes, including fragile RNA molecules and proteins, in addition to DNA. Clinical research organizations and biotechnology firms are adopting these multi-analyte preservation technologies for more comprehensive biomarker studies. The market’s product focus is migrating from simple DNA preservation to multi-analyte stabilization, which enables more complex downstream applications like transcriptomics and proteomics from a single oral fluid sample.
Europe's Medical Device Regulation (MDR) imposes more rigorous pre-market and post-market obligations on device manufacturers compared to the previous directive. This increases the demand for extensive clinical evidence, quality management system audits, and continuous safety monitoring. Consequently, companies seeking CE marking for their saliva collection devices are now allocating greater resources to clinical performance studies and post-market surveillance activities to ensure compliance.
A notable behavioral shift is occurring in how devices are sourced, moving from large, bulk orders by clinical laboratories to individualized, on-demand kit fulfillment for direct-to-consumer health and wellness platforms. This change disrupts the conventional distributor-to-lab supply chain, creating an advantage for manufacturers with robust e-commerce and third-party logistics integration. This fulfillment model is most advanced in the United States, propelled by its mature direct-to-consumer genetic testing industry.
Saliva Collection Devices Market Segmentation
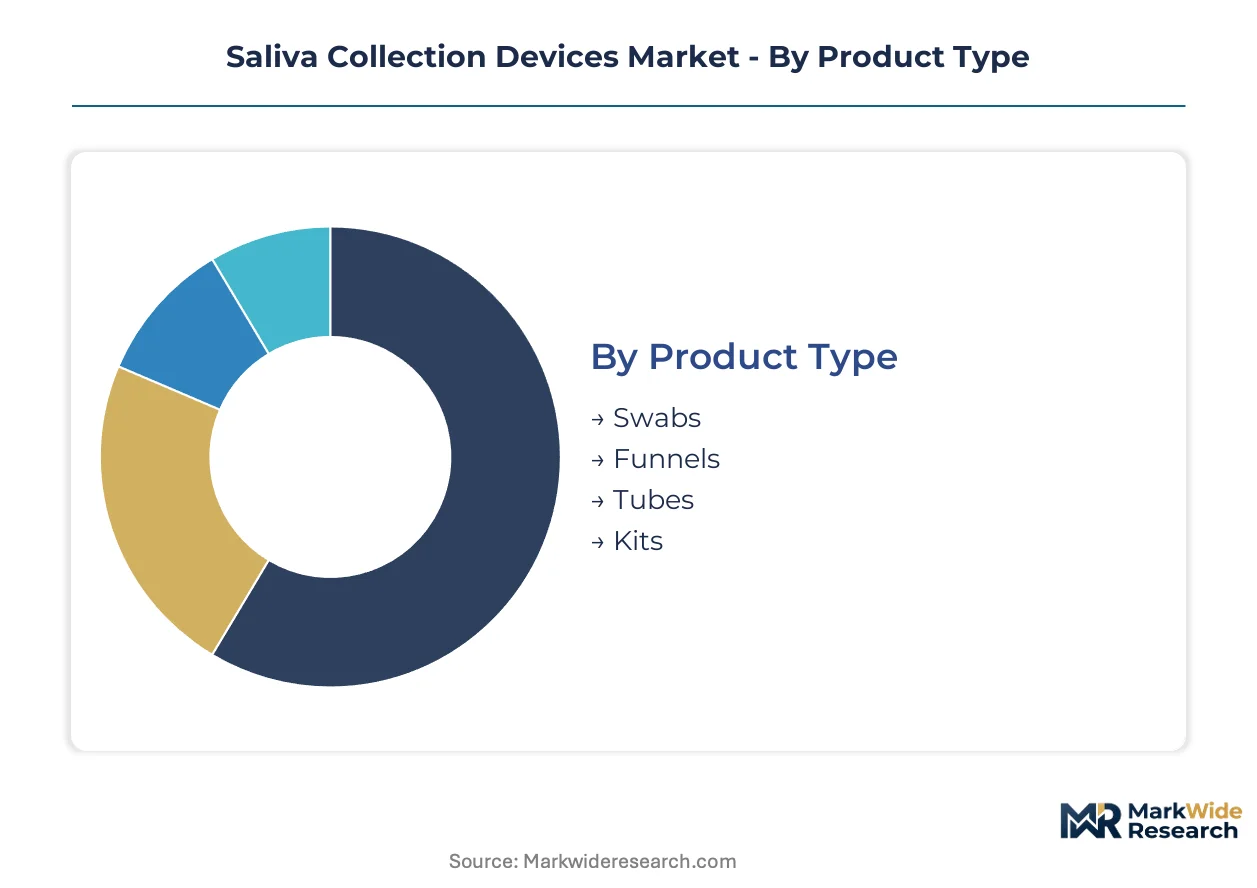
Understanding the segmentation of the saliva collection devices market is crucial for identifying areas of concentrated demand and emerging technological preferences. This analysis highlights how product design, application focus, end-user adoption, and material science collectively shape market dynamics.
Product Type:
The functional design of saliva collection devices delineates distinct product types, each optimized for specific collection methodologies and downstream analysis requirements.
- Kits:These complete packages bundle collection components like funnels or swabs with pre-filled stabilizing buffer tubes and instructions. Demand concentrates in direct-to-consumer diagnostics, driven by the need for user-friendly, reliable home collection.
- Funnels:Devices designed for direct expectoration of saliva into a collection tube, often integrated with a stabilizing solution. Demand is significant in at-home genetic testing, ensuring adequate sample volume and user comfort.
- Swabs:Absorbent materials, typically synthetic or cotton, used to gently collect oral fluid from the inside of the mouth.
- Tubes:Primary containers for saliva samples, frequently pre-filled with preservation media to maintain sample integrity during transport and storage.
Tubes command the established base. The steepest expansion runs through Kits.
Application:
The utility of saliva collection devices spans diverse analytical applications, reflecting their versatility as non-invasive sample tools across healthcare and research.
- Genetic Testing:Focuses on analyzing DNA and RNA from saliva for ancestry, pharmacogenomics, and disease predisposition. The proliferation of direct-to-consumer health platforms drives demand.
- Diagnostics:Encompasses a wide range of tests for infectious diseases, hormones, and general health markers using oral fluid samples. Demand is concentrating in at-home testing for respiratory viruses and other non-invasive screening.
- Drug Testing:Utilizes saliva to detect illicit substances, prescription medications, and alcohol metabolites.
- Research:Supports academic and clinical studies requiring non-invasive biomarker collection for various scientific investigations.
Genetic Testing applications are experiencing substantial growth. Diagnostics continues to broaden its scope across various health conditions.
End User:
The adoption patterns for saliva collection devices vary significantly across different end-user groups, from professional settings to individual consumers, influencing product design and distribution strategies.
- Home Users:Individuals collecting samples for personal health insights, ancestry analysis, or at-home diagnostic tests. Demand is fueled by the convenience and privacy offered by direct-to-consumer models.
- Laboratories:Centralized facilities processing large volumes of samples for clinical analysis, research, and drug testing. Demand remains high for high-throughput, standardized collection systems.
- Clinics:Healthcare facilities using devices for point-of-care testing, patient screening, or sample referral to external laboratories.
- Research Institutions:Universities, pharmaceutical companies, and dedicated research centers employing devices for scientific studies and clinical trials.
Home Users represent the fastest-growing end-user segment. Laboratories maintain a foundational role in sample processing.
Material:
The selection of materials for saliva collection devices impacts both sample integrity and user experience, with various options catering to specific analytical needs and manufacturing efficiencies.
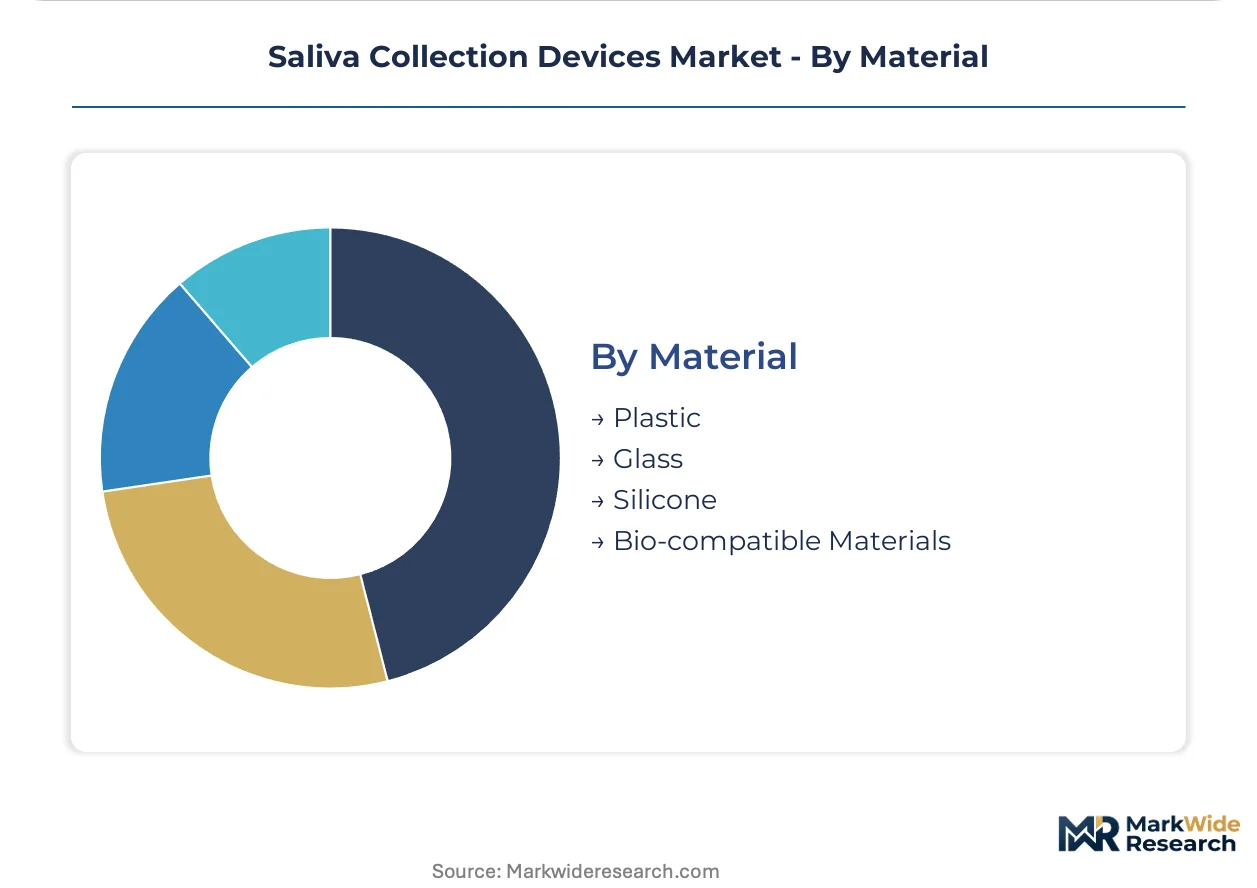
- Plastic:Dominates device manufacturing due to its cost-effectiveness, moldability, and disposability for single-use applications. Demand is widespread across all end-user segments, particularly for high-volume production.
- Bio-compatible Materials:Engineered to minimize interaction with biological samples, preserving analyte stability and purity, especially for sensitive assays. Demand is rising in advanced research and specialized diagnostic applications.
- Glass:Used in specific applications where chemical inertness is critical for maintaining the integrity of certain analytes or reagents.
- Silicone:Offers flexibility, chemical resistance, and biocompatibility, finding use in certain collection components like funnels or seals.
Plastic materials form the bulk of device construction. Bio-compatible materials are gaining share for specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The saliva collection devices market exhibits varied demand elasticity across regions. High-income countries prioritize advanced features and regulatory compliance, demonstrating lower price sensitivity for reliable diagnostic tools. Conversely, emerging markets often seek cost-effective, scalable solutions to address fundamental healthcare access gaps.
United States
Demand for saliva collection devices in the United States is driven by the robust direct-to-consumer genetic testing industry and expanding at-home diagnostic kits. The FDA's emergency use authorizations have created clear regulatory pathways for these products. Boston's prominent biotech hub consistently fosters innovation in non-invasive sample collection technologies.
Germany
Germany's market for saliva collection devices benefits from strong clinical research activities and a demand for high-quality medical diagnostics. Adherence to CE marking under the European Medical Device Regulation (MDR) ensures product reliability. Medical technology centers in Munich and Berlin actively contribute to advanced device development and manufacturing standards.
China
China's market is expanding due to increasing genetic screening programs and a focus on public health surveillance initiatives. NMPA regulations critically shape device classification, manufacturing quality, and market authorization for new products. The Yangtze River Delta region attracts substantial investment in diagnostic manufacturing and research capabilities.
Brazil
Brazil presents a significant opportunity for non-invasive collection technologies, addressing accessibility needs in remote areas and expanding diagnostic services. ANVISA plays a crucial role in regulating medical device approval and ensuring quality standards across the country. São Paulo's robust healthcare infrastructure supports the growing number of diagnostic laboratories and research activities.
India
India's market growth is propelled by the increasing prevalence of genetic disorders and the rising demand for wellness testing. The CDSCO guidelines significantly impact medical device imports and local manufacturing compliance. Bengaluru's dynamic biotech corridor actively drives innovation in developing affordable and accessible diagnostic solutions.
Saliva Collection Devices Market Key Industry Players
Established diagnostic giants and specialized biotech firms split the saliva collection devices market. Large, diversified life sciences companies provide extensive product portfolios, while agile niche players focus on specific collection methodologies or applications. Competitive activity centers on strategic partnerships to expand distribution, continuous innovation in stabilizing buffer solutions, and targeted geographic expansion into emerging markets. Many firms also prioritize digital health integration to enhance user experience.
Specialists in non-invasive diagnostics and life sciences tools include OraSure Technologies, Inc., which represents a strong position in at-home testing solutions with established brand recognition. Thermo Fisher Scientific, Inc., a diversified life sciences corporation, exemplifies broad portfolio offerings across various research and diagnostic needs, leveraging its global manufacturing scale. Salimetrics, LLC occupies a distinct position by focusing on high-sensitivity salivary immunoassays for academic and clinical research applications, anchoring specialized segments of the market through its expertise.
| Leading Market Players |
|---|
| OraSure Technologies, Inc. |
| Neogen Corporation |
| Oasis Diagnostics Corporation |
| Thermo Fisher Scientific, Inc. |
| Salimetrics, LLC |
| Porex Corporation |
| Sarstedt AG & Co |
| Quest Diagnostics |
| AboGen, Inc. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' cost dynamics directly influence the pricing of saliva collection devices, especially for mass-market kits. This concentration of logistics costs shapes price differentiation for end-users.
Pricing Analysis
Recurring revenue from genetic testing services drives the lifetime value proposition for saliva collection devices. Pricing is primarily transactional per-unit, often integrated into service bundles for end-users. Price differentiation stems from stabilizing buffer efficacy and established brand premiums. Pricing softness reflects increased competition in the direct-to-consumer genetic testing space. Home users exhibit the highest price sensitivity, while research institutions prioritize performance and reliability over cost.
Supply Chain Analysis
Extended payment terms are common for plastic component suppliers within the saliva collection device market. Manufacturing concentrates in China for plastic molding and assembly, while specialized buffer chemicals primarily source from facilities in the United States and Europe. The supply chain relies on medical-grade plastics and proprietary stabilizing buffer chemicals. Single-source vulnerability for unique buffer formulations presents a structural risk. Distribution runs through both direct-to-consumer e-commerce channels and established medical distributors for clinical and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The saliva collection devices market is experiencing a cyclical recovery, driven by renewed public health initiatives emphasizing non-invasive diagnostics. This shift supports sustained demand for at-home testing solutions.
For Market Incumbents: Harden existing direct-to-consumer distribution channels to counter emerging low-cost entrants. Incumbents must prioritize investment in multi-analyte preservation R&D to maintain technological leadership. Pursue FDA and CE marking certifications for new product iterations to reinforce diagnostic reliability. Deepen digital health integration to mitigate user error during self-collection and enhance user experience.
For New Entrants and Emerging Players: Pursue market entry into underserved emerging markets, particularly in Latin America and Southeast Asia. These regions offer significant white space for non-invasive collection technologies due to infrastructure gaps. Target the home users segment with cost-effective, culturally adapted kits for infectious disease surveillance. Leverage local partnerships for rapid distribution and regulatory navigation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences corporations seeking to divest non-core diagnostic assets. The market demonstrates sustained long-term viability over the next decade, driven by decentralized healthcare trends. Investors should seek specialized biotech firms with proprietary multi-analyte buffer technologies for strategic acquisition. Increased regulatory harmonization for at-home diagnostics across major markets signals market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Digital Health Integration | Digital integration enhances user compliance and data security for home users. |
| Expand Multi-Analyte Buffer R&D | Advanced buffers enable comprehensive transcriptomics and proteomics from single saliva samples. |
| Target Emerging Markets (LATAM/SE Asia) | Penetrating Latin America addresses critical healthcare infrastructure gaps with non-invasive tools. |
| Secure CE Marking for New Products | CE marking ensures product reliability and broadens market access across European Union member states. |
| Form Strategic Partnerships with DTC Platforms | Partnerships with direct-to-consumer platforms expand kit distribution and brand visibility. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research for validation. We engaged R&D directors, procurement managers at diagnostic laboratories, regulatory affairs specialists, and direct-to-consumer health platform executives. Secondary data sources included FDA guidelines, CE marking documents, NMPA regulations, and academic research databases. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
Forecast inputs considered market size, historical growth patterns, and projected demand drivers across the analysis window. The analytical framework segmented the market by product type, application, end-user, material, and regional regulatory frameworks. Compound annual growth rates derived from historical trends and anticipated market dynamics. Genetic testing adoption rates and at-home diagnostic kit utilization served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or consumer disposable income would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and evolving regulatory landscapes. Regulatory changes or unexpected shifts in user adoption rates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Medical Device Cros Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Foot and Ankle Devices Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Artificial Implants Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Europe Surgical Microscopes Market