
 Global Cranial and Facial Implants Market | 2026-2036
Global Cranial and Facial Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cranial and Facial Implants Market Foresight
PEEK polymer is repositioning titanium in mid-tier cranial flap applications due to superior radiolucency and reduced thermal conductivity. Stryker Corporation leverages its neurotechnology portfolio to sustain dominance in North American trauma reconstruction. Medtronic plc anchors its position through integrated surgical navigation and implant delivery systems. Zimmer Biomet Holdings differentiates via specialized maxillofacial portfolios that compete across European and Asian hospital networks.
Cranial and facial implants are biocompatible prosthetic devices, typically machined from titanium alloy, polyetheretherketone, or porous hydroxyapatite, designed to restore structural integrity after trauma, tumor resection, or congenital deformity. These devices must achieve precise anatomic fit with tolerance thresholds below 0.1 millimeter to ensure osseointegration and prevent cerebrospinal fluid leakage. Titanium implants retain the largest revenue share due to established reimbursement pathways and decades of clinical validation. PEEK implants represent the fastest-expanding product category, driven by rising demand for post-operative imaging clarity. Application demand concentrates in trauma reconstruction, where hospital procurement prioritizes off-the-shelf availability and rapid surgical turnaround.
The FDA enforces Class II device controls through 510(k) premarket notification, while the EU Medical Device Regulation mandates notified body conformity assessment and unique device identification for implant traceability. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains, with Japan's PMDA adding layer-specific biocompatibility testing for polymer-based cranial substitutes. Stakeholders must monitor evolving reimbursement criteria for custom 3D-printed implants as health technology assessment bodies in Germany, France, and South Korea develop distinct economic evidence requirements.
Market Dynamics
Patient-specific 3D-printed cranial plates are compressing traditional manufacturing lead times from weeks to days, forcing hospital procurement departments to renegotiate vendor contracts and inventory protocols across neurosurgical supply chains.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced traceability requirements for implantable devices are accelerating hospital adoption of digitally manufactured cranial plates with embedded unique device identifiers.
- Trauma reconstruction demand:Rising incidence of traumatic brain injury requiring cranioplasty in Germany, Japan, and the United States is expanding addressable surgical volumes for advanced implant solutions.
- PEEK polymer radiolucency:Post-operative MRI compatibility is driving material substitution in mid-tier applications where imaging clarity influences long-term patient management protocols.
Market Restraints
- Titanium powder supply concentration:Additive manufacturing feedstock for cranial implants depends on a limited supplier base in China and Germany, creating input cost volatility and qualification delays.
- FDA 510(k) predicate device requirements:Custom 3D-printed implants often lack established predicates, extending regulatory review timelines and compressing commercialization windows for novel geometries.
- Bioresorbable polymer limitations:Hydroxyapatite-based substitutes exhibit inconsistent resorption rates in cranial applications, constraining their displacement of permanent metallic solutions in trauma reconstruction.
Strategic Opportunities
- South Korea reimbursement evolution:Health technology assessment bodies are developing distinct economic evidence frameworks for patient-specific implants, creating first-mover advantage for localized manufacturing partnerships.
- Congenital craniofacial deformity correction:Pediatric applications remain underpenetrated relative to trauma, with specialized design workflows and growth-accommodating geometries representing untapped surgical demand.
- ISO 13485-certified distributed manufacturing:Hospital-integrated 3D printing facilities enable point-of-care production, compressing logistics costs and enabling same-day surgical scheduling for emergency cranioplasty.
Industry Challenges
- Biomedical engineer scarcity:Patient-specific implant design requires specialized expertise in computational anatomy and additive manufacturing, with talent concentrated in academic medical centers and contract research organizations.
- Multi-jurisdictional quality system compliance:Manufacturers must maintain parallel ISO 13485, FDA QSR, and PMDA documentation for titanium and PEEK cranial devices, inflating audit and certification maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cranial and Facial Implants Market |
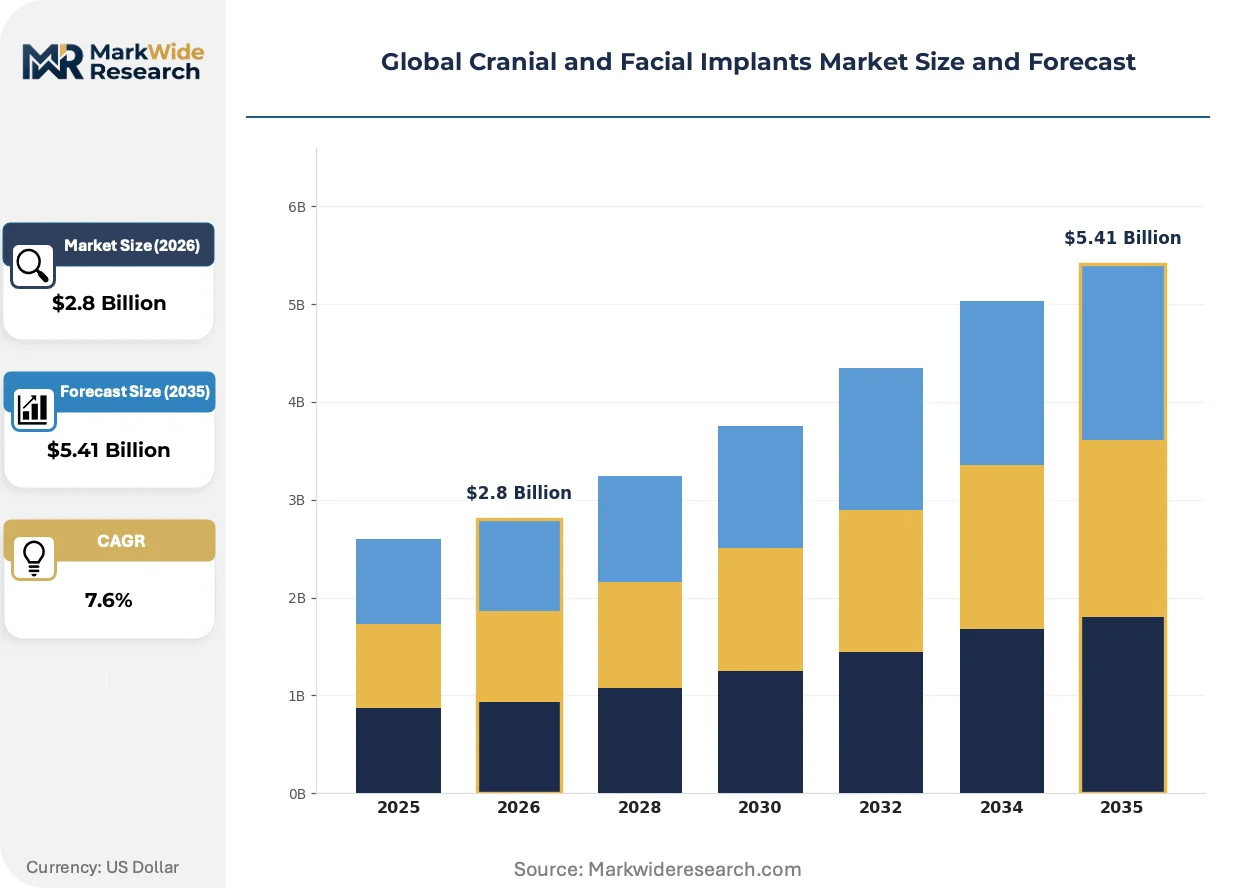
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Implants, PEEK Implants, Hydroxyapatite Implants, Ceramic Implants, Silicone Implants Application: Trauma Reconstruction, Congenital Defect Repair, Cosmetic Enhancement, Post-Tumor Reconstruction, Corrective Surgery End User: Neurosurgical Centers, Maxillofacial Clinics, Plastic Surgery Units, Dental Hospitals, Specialized Implant Labs Technology: 3D Printing, CAD/CAM Design, Biocompatible Coating, Custom Molding, Electron Beam Melting |
| Companies Covered | KLS Martin Group, B. Braun Melsungen AG, Stryker Corporation, Medtronic plc, DePuy Synthes, Zimmer Biomet Holdings, Medartis AG, Johnson & Johnson Services, Integra LifeSciences Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cranial and Facial Implants Market Shifts & Advancements
Digital surgical planning platforms are collapsing the traditional boundary between diagnostic imaging and implant fabrication, enabling real-time anatomical modeling that reshapes how neurosurgical teams prepare for complex reconstruction procedures.
Additive manufacturing of titanium cranial implants is decentralizing production authority from centralized OEM facilities to hospital-based or regional contract manufacturing sites. Academic medical centers in the United States and Germany are installing electron beam melting systems for same-day flap production. This geographic redistribution of manufacturing capability is compressing logistics costs and enabling emergency cranioplasty without inventory carrying costs.
The EU Medical Device Regulation's unique device identification mandate is forcing implant manufacturers to redesign labeling and data architecture for full supply chain traceability. Notified bodies in Germany and France are interpreting MDR requirements more stringently for custom 3D-printed devices than for standard catalog items. Cranial implant vendors are responding by integrating blockchain-based tracking systems and cloud-native quality management platforms.
Hospital procurement departments are consolidating vendor relationships around integrated surgical navigation and implant delivery systems rather than discrete device purchasing. Neurosurgical centers in Japan and the United States now evaluate cranial plate suppliers on compatibility with pre-operative planning software and intraoperative positioning tools. This bundling preference disadvantages pure-play implant manufacturers lacking navigation partnerships or digital surgery platforms.
Global Cranial and Facial Implants Market Segmentation
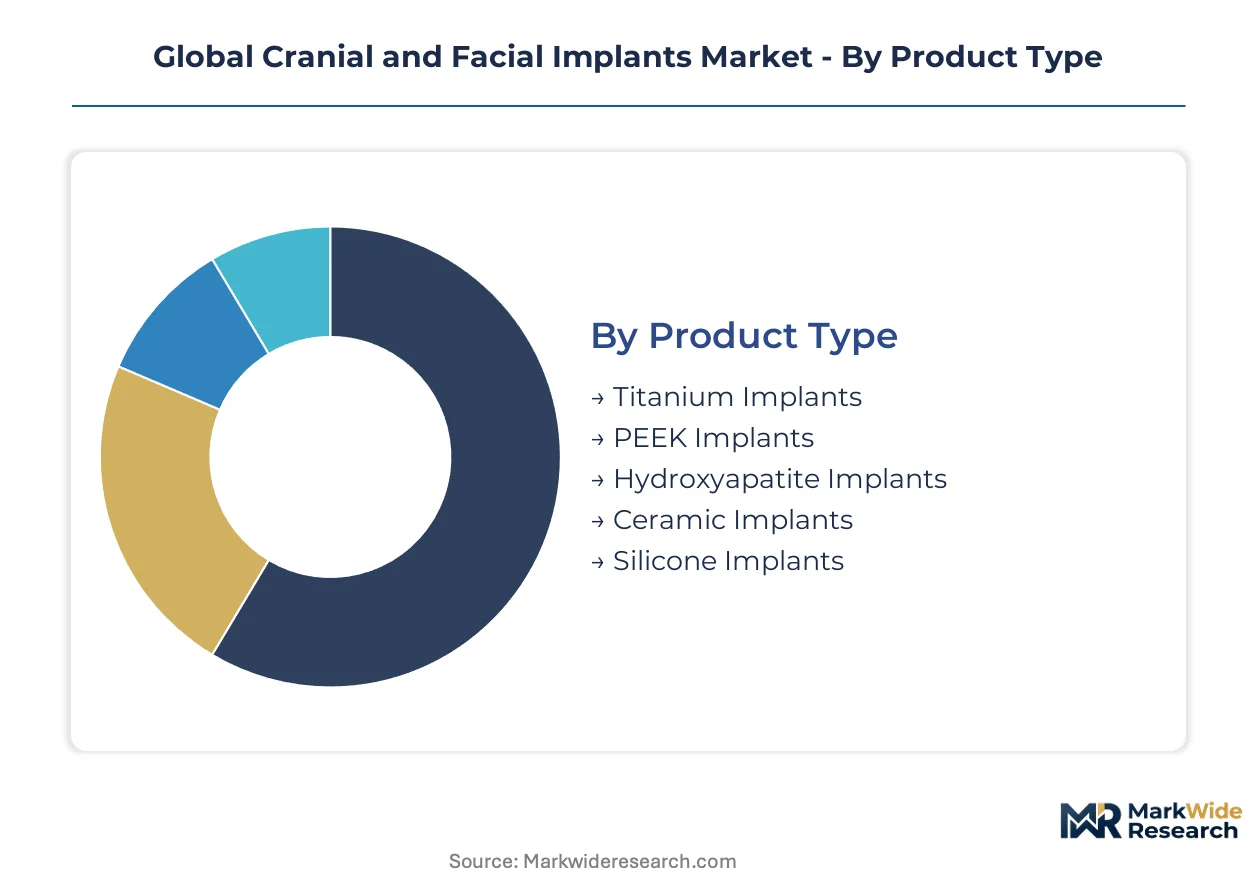
Material selection and manufacturing precision define competitive positioning across cranial and facial implant supply chains. Segmentation reveals how procurement criteria diverge between emergency trauma centers and elective cosmetic practices.
Product Type:
Cost tier separates high-volume trauma buyers from premium-seeking academic medical centers.
- Titanium Implants:Machined from Ti-6Al-4V ELI alloy with established osseointegration profiles and decades of clinical documentation. Hospital procurement in the United States and Germany prioritizes titanium for cranioplasty due to FDA 510(k) predicate abundance and immediate off-the-shelf availability.
- PEEK Implants:Polyetheretherketone polymer delivers radiolucent imaging compatibility and thermal insulation properties superior to metallic alternatives. Demand concentrates in Japan and South Korea where post-operative MRI protocols drive material substitution in mid-tier cranial flap applications.
- Hydroxyapatite Implants:Ceramic-calcium phosphate composite designed for gradual bone resorption and replacement.
- Ceramic Implants:Alumina and zirconia-based solutions for facial contouring with high biocompatibility.
- Silicone Implants:Soft-tissue compatible elastomer for chin and cheek augmentation procedures.
Volume sits with titanium; growth tilts toward PEEK.
Application:
Volume concentration follows trauma epidemiology rather than elective procedure economics.
- Trauma Reconstruction:Emergency cranioplasty following decompressive craniectomy accounts for the largest surgical volume. Neurosurgical centers in Germany, Japan, and the United States prioritize rapid implant availability and standardized geometries for traumatic brain injury cases.
- Congenital Defect Repair:Pediatric craniosynostosis and facial cleft corrections require growth-accommodating designs with extended follow-up protocols. Academic medical centers in France and South Korea are expanding specialized workflows for infant cranial vault reconstruction.
- Cosmetic Enhancement:Elective facial contouring and augmentation procedures.
- Post-Tumor Resection:Oncologic reconstruction following skull base or maxillofacial tumor removal.
- Corrective Surgery:Revision procedures addressing implant failure or aesthetic complications.
Trauma commands current surgical volume; congenital applications are climbing the fastest.
End User:
Customer sophistication determines whether procurement prioritizes speed, precision, or bundled surgical navigation.
- Neurosurgical Centers:High-acuity hospitals performing emergency and elective cranial procedures with integrated imaging and navigation infrastructure.
- Maxillofacial Clinics:Specialized units in France and Germany focus on orthognathic surgery and facial trauma with CAD/CAM-driven implant planning.
- Plastic Surgery Units:Elective aesthetic practices with lower trauma volume but higher per-procedure customization requirements.
- Dental Hospitals:Oral and maxillofacial surgery departments with overlapping implant procurement needs.
- Specialized Implant Labs:Regional manufacturing facilities serving point-of-care production for custom cranial plates.
Procurement authority concentrates in neurosurgical centers; specialized implant labs are gaining share fastest.
Technology:
Manufacturing maturity separates proven workflows from emerging capabilities with regulatory uncertainty.
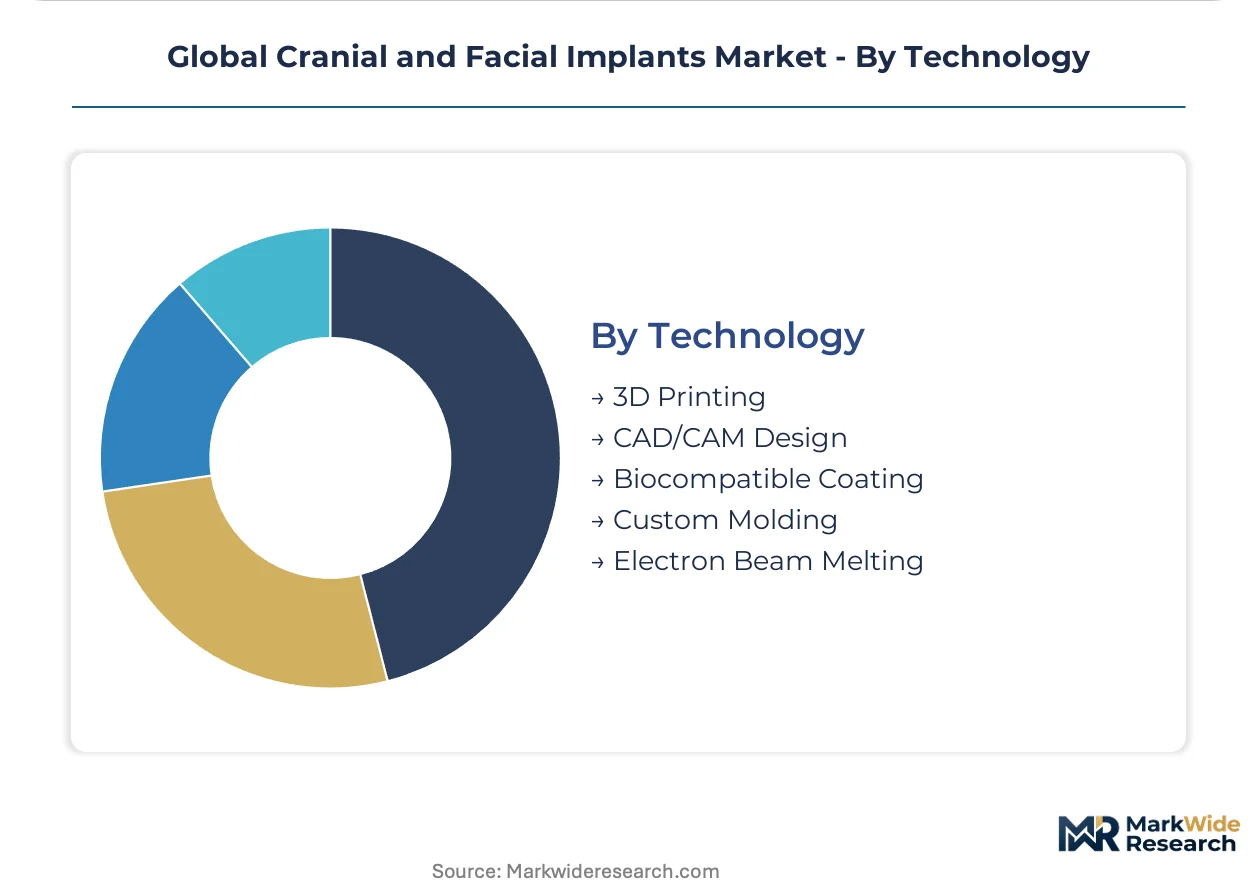
- 3D Printing:Powder-bed fusion and material extrusion systems enable patient-specific geometries with lead times compressed from weeks to days. Academic medical centers in the United States and Germany are installing hospital-based production for emergency cranioplasty.
- CAD/CAM Design:Digital surgical planning platforms integrate CT segmentation with automated implant modeling. This technology anchors current standard-of-care workflows across Japanese and South Korean neurosurgical networks.
- Biocompatible Coating:Surface modification techniques including hydroxyapatite deposition and plasma electrolytic oxidation.
- Custom Molding:Conventional subtractive manufacturing for standardized implant geometries.
- Electron Beam Melting:Vacuum-based additive manufacturing for titanium cranial implants with superior fatigue resistance.
CAD/CAM dominates current procedural volume; 3D printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany, Japan, and the United States account for the largest share of advanced cranial implant demand. Neurosurgical centers across these markets prioritize rapid surgical turnaround and post-operative imaging compatibility. Regulatory frameworks in each jurisdiction shape material preferences and manufacturing workflows.
United States
Trauma reconstruction volumes at Level I trauma centers drive titanium implant procurement. The FDA's 510(k) clearance framework favors established predicate devices, accelerating off-the-shelf cranial plate adoption. Academic medical centers in Boston and Baltimore are installing hospital-based electron beam melting systems for emergency cranioplasty production.
Germany
Maxillofacial clinics in Bavaria and North Rhine-Westphalia anchor European demand for patient-specific PEEK implants. The EU Medical Device Regulation's unique device identification mandate is compressing manufacturing lead times for digitally fabricated cranial plates. Stuttgart-based manufacturing clusters are integrating blockchain-based tracking systems for MDR compliance.
Japan
Post-operative MRI protocols at Tokyo and Osaka neurosurgical centers are displacing titanium with PEEK polymer in mid-tier applications. The PMDA enforces layer-specific biocompatibility testing for polymer-based cranial substitutes, extending qualification timelines. Nagoya academic hospitals are expanding CAD/CAM-driven implant planning workflows.
South Korea
Health technology assessment bodies in Seoul are developing distinct economic evidence frameworks for patient-specific 3D-printed implants. The MFDS is accelerating review pathways for digitally manufactured cranial devices with embedded traceability features. Busan-Ulsan manufacturing partnerships are targeting first-mover positioning in customized implant reimbursement.
France
Pediatric craniosynostosis correction at Paris and Lyon academic centers is expanding specialized workflows for infant cranial vault reconstruction. ANSM is interpreting MDR requirements stringently for custom 3D-printed devices versus standard catalog items. Auvergne-Rhône-Alpes clusters are developing growth-accommodating geometries for congenital applications.
Global Cranial and Facial Implants Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle surgical navigation with implant delivery systems. The vendor base concentrates around three tiers: diversified medtech conglomerates with neurotechnology portfolios, specialized maxillofacial device manufacturers, and emerging point-of-care production specialists. Consolidation pressures favor integrated platform providers over discrete device suppliers. M&A activity and technology licensing agreements represent the primary competitive vectors reshaping procurement relationships.
Within the diversified medtech tier, Stryker Corporation and Medtronic plc exemplify platform-centric positioning through neurotechnology integration. Zimmer Biomet Holdings occupies a specialized position serving European and Asian hospital networks with dedicated maxillofacial portfolios. These three entities anchor the competitive structure through distinct geographic and application emphases rather than overlapping direct competition.
| Leading Market Players |
|---|
| KLS Martin Group |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Medtronic plc |
| DePuy Synthes |
| Zimmer Biomet Holdings |
| Medartis AG |
| Johnson & Johnson Services |
| Integra LifeSciences Holdings Corporation |
| Others |
Supply & Pricing Matrix
Captive production of titanium powder feedstock in Germany and China anchors supply security for additive manufacturing while simultaneously constraining pricing flexibility for implant OEMs. Hospital procurement departments negotiate from a position shaped by concentrated upstream qualification requirements and the FDA's predicate device framework.
Pricing Analysis
Volume sits with standardized titanium plates while margins concentrate in patient-specific PEEK geometries. Three-tier pricing structure across premium, standard, and economy levels separates emergency trauma procurement from elective congenital workflows. Cost compression in mid-tier titanium applications is intensifying because Chinese powder suppliers are expanding qualification capacity. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to bundled navigation system requirements.
Supply Chain Analysis
Single-source vulnerability sits with titanium powder suppliers concentrated in China and Germany, where qualification timelines for medical-grade feedstock extend regulatory exposure. Raw material dependencies center on Ti-6Al-4V ELI alloy, polyetheretherketone resin, and electron beam melting equipment. Tariff exposure runs through German machinery imports for hospital-based production facilities. Distribution runs through specialized implant labs and GPO contracts at Level I trauma centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures favor integrated platform providers as the EU Medical Device Regulation's traceability mandates force smaller manufacturers into compliance cost distress. Procurement bundling around surgical navigation systems is accelerating exit pressures for pure-play implant vendors.
For Market Incumbents: Extend neurotechnology platform dominance by acquiring point-of-care production specialists in Germany and the United States. Deepen backward integration into PEEK resin compounding to defend margin position against material substitution threats from emerging polymer suppliers.
For New Entrants and Emerging Players: Hospital-integrated 3D printing services represent the most penetrable channel for bypassing established OEM procurement relationships. Target pediatric congenital applications in France and South Korea where specialized design workflows remain underdeveloped relative to trauma reconstruction.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking navigation-implant bundling capability. Mid-term viability through the projection horizon hinges on ISO 13485-certified distributed manufacturing assets. Watch South Korean reimbursement rulings on patient-specific implants as the inflection signal for geographic expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Medtronic leverage existing navigation installed base to lock in implant procurement at German neurosurgical centers. |
| CE Marking Pathway | Notified body relationships in Stuttgart and Paris determine market access velocity for custom 3D-printed cranial plates. |
| Software Companion Development | CAD/CAM platform integration with CT segmentation tools anchors procurement decisions at Japanese academic medical centers. |
| Reimbursement Strategy | Health technology assessment engagement in Seoul shapes economic evidence requirements for patient-specific implant adoption. |
| Backward Integration | In-house titanium powder atomization capacity insulates German manufacturers from Chinese supply qualification delays. |
Research Methodology
Multi-period observation of FDA 510(k) clearance patterns and EU MDR notified body decisions anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at implant manufacturers. Secondary validation drew from FDA 510(k) database filings, EUDAMED traceability records, hospital procurement databases, and ISO 13485 certification registries. Bottom-up surgical volume estimates triangulated against top-down manufacturer revenue disclosures.
Input-output matrices mapped titanium and PEEK material flows through additive manufacturing and machining workflows across the projection horizon. Segmentation dimensions included material type, application severity, end-user sophistication, and manufacturing technology maturity. CAGRs were derived from surgical volume elasticity models calibrated to trauma epidemiology data and technology substitution curves for PEEK versus titanium.
Caveats apply where FDA predicate device policy shifts or EU MDR enforcement variability could materially shift the outlook for custom 3D-printed implant commercialization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Bone Allografts Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Italy Ultrasound Devices Market