
 Clinical Trinocular Microscopes Market | 2026-2036
Clinical Trinocular Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trinocular Microscopes Market Outlook
A capital-intensity divergence between integrated optics manufacturers and assembly-dependent competitors is reorganizing competitive tiers in clinical microscopy. Zeiss Group leverages captive glass foundries and in-house lens grinding to sustain premium positioning across European hospital networks. Nikon Corporation anchors its North American presence through dedicated pathology application centers that specialize in workflow-integrated imaging systems.
Clinical trinocular microscopes employ three optical ports—binocular eyepieces plus a dedicated camera port—to enable simultaneous live viewing and digital image capture, typically achieving resolutions from 40x to 1000x through apochromatic objective correction for chromatic aberration. Optical microscopes dominate installed base volumes in routine histology workflows where pathologists prioritize direct ocular confirmation, while digital microscopes capture the fastest expansion as laboratories retrofit for telepathology and AI-assisted diagnostics. LED Illumination technology leads new system specifications due to energy efficiency and stable color temperature, though Laser Scanning variants command the highest margin pools in neuroscience research applications.
FDA device classification under 21 CFR 864.3600 shapes premarket requirements for diagnostic microscopes in the United States, while EU MDR and CE marking obligations govern European commercialization through notified body conformity assessment. ISO 10993 biocompatibility standards and IEC 60601 electrical safety protocols further constrain component sourcing and final assembly validation. Stakeholders must monitor evolving digital pathology reimbursement codes and interoperability mandates to align product roadmaps with institutional purchasing criteria.
Market Dynamics
The transition from optical to digital pathology workflows is compressing replacement cycles and forcing manufacturers to bundle software-enabled imaging platforms with traditional hardware, fundamentally altering how hospitals evaluate microscope procurement.
Growth Catalysts
- EU MDR compliance mandates:European diagnostic laboratories must upgrade to certified optical systems by notified body deadlines, accelerating capital expenditure on validated trinocular platforms with full quality documentation.
- Telepathology infrastructure buildout:Hospital networks in Germany, Japan, and the United States are standardizing on camera-integrated microscopes to enable remote consultation and second-opinion workflows.
- AI-assisted diagnostic validation:Digital image capture ports on trinocular heads feed machine learning pipelines for automated tissue analysis, creating pull from pathology departments seeking workflow efficiency.
Market Restraints
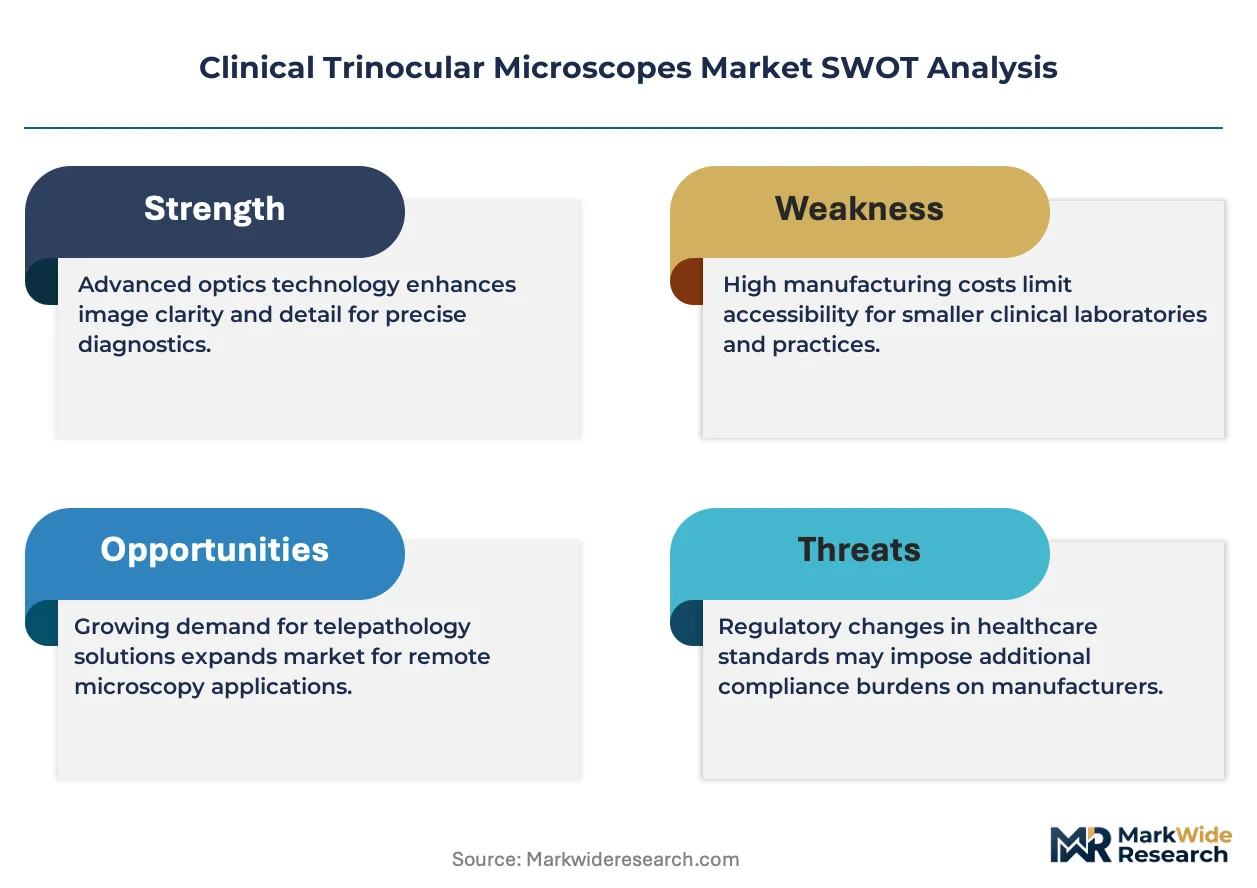
- Specialized optical glass supply concentration:High-index crown glass and fluorite crystal sourcing depends on a limited number of German and Japanese specialty foundries, exposing manufacturers to input volatility.
- FDA 510(k) pathway complexity:Digital microscope variants with embedded software face extended premarket review timelines compared to traditional optical-only devices, delaying revenue recognition.
- Flat-panel display substitution:Full-slide imaging scanners with monitor-based review are displacing ocular-dependent workflows in high-throughput reference laboratories.
Strategic Opportunities
- Brazil diagnostic network expansion:ANVISA regulatory harmonization with IMDRF standards reduces import barriers for certified manufacturers serving public hospital procurement programs.
- LED-fluorescence convergence:Modular illumination upgrades enable cost-effective retrofit of existing trinocular bodies for FISH and immunofluorescence applications without full system replacement.
- Cloud-native pathology platforms:Subscription-based image management software creates recurring revenue streams alongside capital equipment sales, shifting customer relationships from transactional to continuous.
Industry Challenges
- Optomechanical assembly technician scarcity:Precision lens alignment and interferometric testing require skilled craft labor that training pipelines have failed to replenish across manufacturing clusters.
- IEC 60601-1 third edition certification:Electrical safety and electromagnetic compatibility validation for camera-integrated systems extends development timelines and requires specialized notified body engagement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trinocular Microscopes Market |
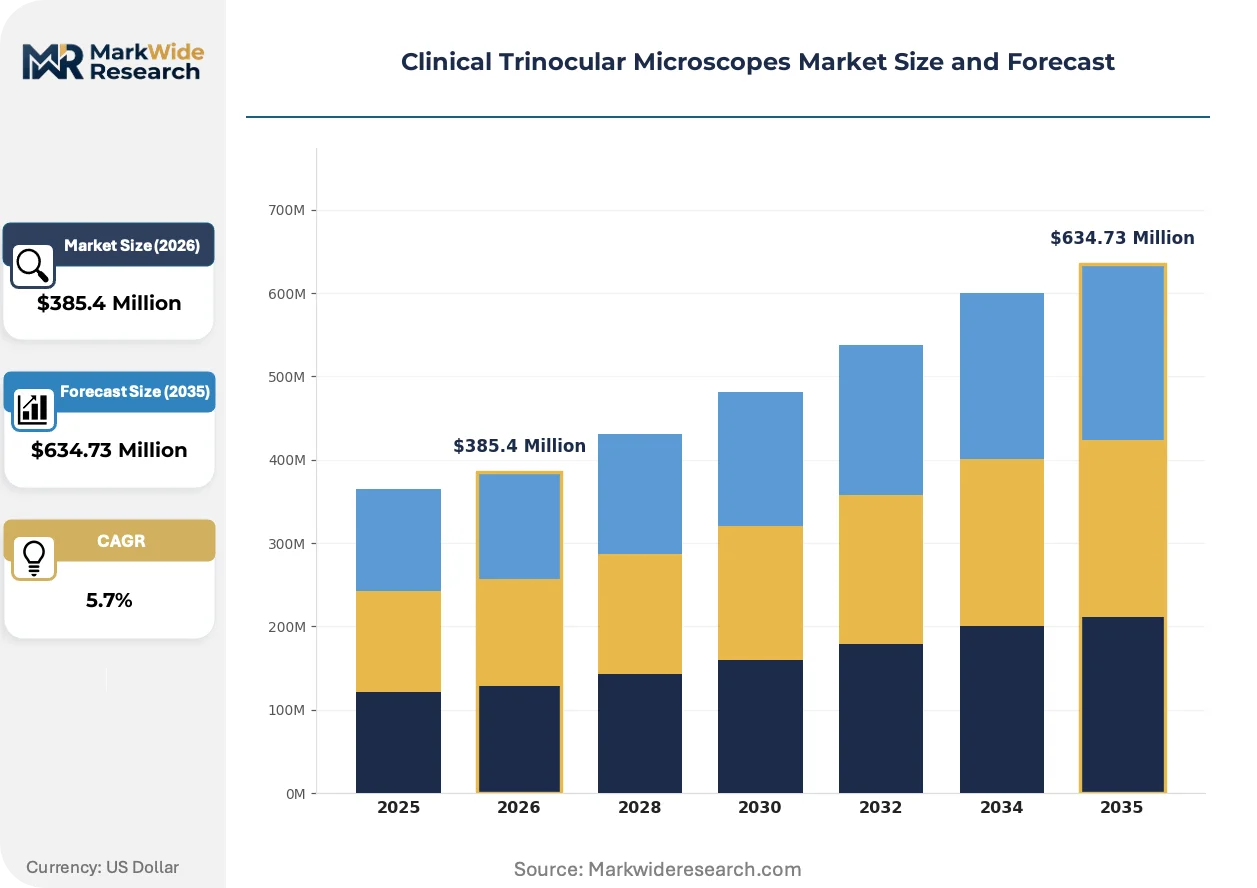
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopes, Digital Microscopes, Fluorescence Microscopes, Stereo Microscopes End User: Hospitals, Laboratories, Research Institutions, Clinics Application: Pathology, Histology, Cytology, Neuroscience Technology: LED Illumination, Laser Scanning, Image Capture, Computerized Control |
| Companies Covered | Leica Microsystems, Zeiss Group, Thermo Fisher Scientific Inc., Nikon Corporation, EVIDENT, Motic Microscopes, Euromex, Meiji Techno, Vision Engineering Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trinocular Microscopes Market Strategic Shifts
Digital capture modules are migrating from external attachments to embedded optical paths, collapsing the distinction between standalone microscopes and imaging workstations while compressing the total cost of ownership for integrated systems.
CMOS sensor arrays with backside illumination are miniaturizing the camera port architecture on trinocular heads, enabling direct sensor-to-optical-path coupling without intermediate relay optics. Academic medical centers in the United States are piloting these compact modules for intraoperative frozen section workflows. The reduction in optical train complexity is compressing system footprint and manufacturing cost structures for mid-range product tiers.
EU MDR Article 10 post-market surveillance requirements are mandating systematic vigilance reporting for diagnostic microscope software components, compelling manufacturers to establish dedicated regulatory affairs functions in European markets. Notified bodies are interpreting software as a medical device guidance strictly for image analysis algorithms embedded in capture systems. Pathology departments in France and Italy are prioritizing vendors with established EU MDR certificates over legacy CE-marked alternatives.
Service contract unbundling is separating preventive maintenance from warranty coverage in hospital procurement negotiations, with buyers in Japan demanding à la carte calibration and optical alignment schedules. Distributors are responding by building captive service technician networks rather than outsourcing to manufacturer field teams. Tokyo and Osaka metropolitan hospital consortia are piloting performance-based maintenance agreements tied to uptime metrics rather than scheduled visit frequencies.
Clinical Trinocular Microscopes Market Segmentation
Procurement patterns for clinical trinocular microscopes diverge sharply across product architectures and end-use settings. Regulatory validation requirements, workflow integration complexity, and capital allocation priorities reshape how manufacturers configure specifications for each segment cluster.
Product Type:
FDA 21 CFR 864.3600 classification and EU MDR Article 10 surveillance obligations create divergent compliance burdens across optical architectures, with digital variants facing extended notified body review timelines for embedded software components.
- Optical Microscopes:These systems rely on apochromatic objective correction and trinocular heads with dedicated camera ports for simultaneous ocular viewing and image capture. Pathology departments in Germany and the United States specify these for routine histology workflows where direct tissue confirmation remains mandatory.
- Digital Microscopes:Integrated CMOS sensor arrays with backside illumination enable direct optical-path coupling without relay optics. Academic medical centers in Japan and the United States are retrofitting these for telepathology and AI-assisted diagnostic pipelines.
- Fluorescence Microscopes:Modular LED-fluorescence upgrades support FISH and immunofluorescence applications.
- Stereo Microscopes:Lower magnification ranges serve surgical pathology and gross specimen examination.
Established volume favors Optical Microscopes; emerging adoption favors Digital Microscopes.
End User:
Capital allocation authority and reimbursement pathways segment demand across institutional types, with hospital networks consolidating procurement through centralized biomedical engineering committees.
- Hospitals:Integrated delivery networks in the United States and Germany dominate capital expenditure, prioritizing FDA-cleared and EU MDR-certified platforms with full quality documentation for pathology departments. These institutions negotiate performance-based maintenance agreements tied to uptime metrics.
- Laboratories:Independent reference laboratories and hospital-affiliated labs drive digital retrofit demand for high-throughput screening workflows. Tokyo metropolitan hospital consortia are standardizing on camera-integrated systems for remote consultation capabilities.
- Research Institutions:Neuroscience and basic science applications command premium specifications.
- Clinics:Limited capital budgets constrain procurement to mid-range optical configurations.
Procurement concentration sits with Hospitals; steepest expansion trajectory belongs to Laboratories.
Application:
Diagnostic specificity and reimbursement code availability determine specification requirements across clinical disciplines.
- Pathology:Histopathological diagnosis requires 40x to 1000x magnification with apochromatic correction for chromatic aberration elimination. Digital pathology reimbursement codes in the United States are pulling hospital networks toward camera-integrated trinocular heads for whole-slide imaging compatibility.
- Histology:Tissue section examination represents the highest installed base volume for routine optical workflows.
- Cytology:Cellular specimen analysis demands precise illumination stability for Pap smear and liquid-based cytology screening.
- Neuroscience:Laser Scanning variants command the highest margin pools in research-intensive settings.
Volume leadership rests with Pathology; margin expansion concentrates in Neuroscience.
Technology:
Illumination architecture and control interfaces differentiate cost structures and upgrade pathways.
- LED Illumination:Energy efficiency and stable color temperature have made this the dominant specification for new system configurations. LED modules reduce thermal load on tissue specimens while maintaining consistent CCT for digital capture calibration.
- Laser Scanning:Confocal architectures achieve optical sectioning for fluorescence applications in neuroscience research.
- Image Capture:Embedded CMOS arrays are collapsing the distinction between standalone microscopes and imaging workstations.
- Computerized Control:Motorized stage positioning and automated focus stacking support high-throughput screening protocols.
Specification leadership belongs to LED Illumination; integration momentum favors Image Capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Japanese manufacturers commanding premium positions, while procurement volume clusters in the United States where hospital network consolidation drives standardized specifications. Regulatory divergence between FDA 21 CFR 864.3600 and EU MDR Article 10 surveillance reshapes competitive access across major markets.
United States
Hospital pathology departments and academic medical centers drive capital expenditure on camera-integrated systems for telepathology workflows. FDA 510(k) premarket review timelines extend for digital variants with embedded software, delaying commercialization. The Boston and New York metropolitan hospital consortia are standardizing on trinocular platforms with whole-slide imaging compatibility.
Germany
EU MDR compliance mandates accelerate replacement cycles in diagnostic laboratories requiring full quality documentation. Notified body conformity assessment for software-enabled capture systems creates certification bottlenecks. The Jena and Oberkochen optical manufacturing clusters sustain captive glass foundries and precision lens grinding capabilities for premium system production.
Japan
Tokyo and Osaka metropolitan hospital networks are piloting performance-based maintenance agreements tied to uptime metrics rather than scheduled service visits. PMDA regulatory harmonization with IMDRF standards streamlines import pathways for certified manufacturers. The Kanagawa and Tokyo prefectures concentrate pathology application centers specializing in workflow-integrated imaging systems.
China
NMPA medical device registration requirements for diagnostic optical equipment intensify documentation burdens for imported systems. The Yangtze River Delta and Pearl River Delta manufacturing bases are developing domestic CMOS sensor integration capabilities for mid-range trinocular configurations. Shanghai teaching hospitals are retrofitting existing optical bodies with modular LED-fluorescence upgrades for FISH applications.
Brazil
ANVISA regulatory harmonization with IMDRF standards reduces import barriers for certified manufacturers serving public hospital procurement programs. The São Paulo and Rio de Janeiro state diagnostic networks are expanding capital equipment budgets for pathology infrastructure modernization. Southeast regional laboratories are prioritizing EU MDR-certified platforms over legacy alternatives to accelerate regulatory approval timelines.
Clinical Trinocular Microscopes Market Competitive Environment
Concentration sits with integrated optics manufacturers possessing captive glass foundries and in-house lens grinding capabilities, while assembly-dependent competitors occupy mid-tier positions through distributor networks. The vendor base stratifies across three archetypes: vertically integrated precision optical houses, modular system integrators, and regional assembly specialists. Competitive moves center on M&A for optical component sourcing security and strategic partnerships for cloud-native pathology software integration.
Among German and Japanese precision optical houses, Leica Microsystems and Zeiss Group exemplify the integrated archetype with captive manufacturing capabilities, while Nikon Corporation anchors the application-specialist tier through dedicated pathology workflow centers. These three occupy positions that represent divergent strategic vectors: full vertical control versus workflow-centric integration versus regional service density.
| Leading Market Players |
|---|
| Leica Microsystems |
| Zeiss Group |
| Thermo Fisher Scientific Inc. |
| Nikon Corporation |
| EVIDENT |
| Motic Microscopes |
| Euromex |
| Meiji Techno |
| Vision Engineering Ltd |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR 864.3600 and EU MDR certification tiers simultaneously gate supplier qualification and stratify price positioning, forcing buyers to pay premiums for systems with full notified body documentation while locking out uncertified competitors from institutional procurement channels entirely.
Pricing Analysis
Configured-to-order pricing for apochromatic objective systems with embedded CMOS capture modules commands spreads of 40-60 percent above standard optical-only configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling rather than optical performance alone. Cost compression in mid-range tiers is intensifying because Brazilian and Chinese manufacturers are qualifying for ANVISA and NMPA approvals at lower price points. Independent reference laboratories exhibit the highest price sensitivity, while German hospital networks prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Germany and Japan anchor precision optical glass production, with Jena and Oberkochen foundries supplying high-index crown glass and fluorite crystals for apochromatic objective manufacturing. Component sourcing draws from Taiwanese CMOS sensor fabricators and Japanese precision motor suppliers for automated stage positioning. Single-source vulnerability concentrates in specialty glass melting capacity, where decades of craft knowledge create irreplicable production know-how. Distribution runs through authorized dealer networks with captive service technician pools rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-slide imaging scanners pose a direct substitution threat to ocular-dependent trinocular workflows, compelling incumbents to bundle digital capture modules as standard rather than optional configurations to defend installed base positions.
For Market Incumbents: Fortify captive glass foundry positions through long-term supply agreements with German and Japanese specialty foundries, insulating against input volatility while denying competitors access to premium optical substrates. Accelerate EU MDR software-as-medical-device certification for embedded capture algorithms to create regulatory moats against mid-tier modular integrators. Prioritize backward integration into LED-fluorescence illumination modules to capture retrofit revenue from existing installed bases. For New Entrants and Emerging Players: Cloud-native pathology platform integration represents the most penetrable service-layer gap, with incumbents under-serving subscription-based image management needs. Target Brazil's ANVISA-harmonized procurement programs where regulatory barriers have fallen for IMDRF-certified manufacturers. Pursue partnership-based entry with Tokyo and Osaka metropolitan hospital consortia seeking performance-based maintenance alternatives to manufacturer-direct service contracts. For Investors and Strategic Acquirers: EU MDR Article 10 post-market surveillance requirements reshape the acquisition landscape toward targets with established notified body relationships and dedicated regulatory affairs functions. Frame long-term viability around 5-10 year digital pathology reimbursement expansion windows in the United States and Germany. Monitor FDA 510(k) premarket review timeline extensions for digital variants as the critical inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body approval unlocks German and French hospital procurement channels. |
| CMOS Sensor Integration Partnership | Direct optical-path coupling eliminates relay optics cost in mid-range tiers. |
| Cloud-Native Software Development | Subscription revenue shifts customer relationships from transactional to continuous. |
| LED-Fluorescence Module Retrofit | FISH application upgrades extend lifecycle of existing trinocular bodies. |
| Performance-Based Service Contracting | Uptime-metric agreements align vendor incentives with Japanese hospital consortium priorities. |
Study Parameters
The analysis maps optical microscope, digital microscope, fluorescence microscope, and stereo microscope configurations, each validated through biomedical engineering directors, pathology department heads, GPO contracts managers, and regulatory affairs specialists at notified bodies. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR certificates, hospital procurement databases, and CMS digital pathology reimbursement codes. Bottom-up unit economics triangulated against top-down market sizing across product architectures.
Consistency checks validated volume and value outputs against external benchmarks including customs import records, capital expenditure disclosures from hospital networks, and distributor shipment data. Segmentation modeling spanned product type, end user, application, and technology dimensions across the projection horizon. CAGRs derived from fitted growth curves incorporating replacement cycle compression from digital workflow transitions and regulatory mandate acceleration effects.
Forecasts assume regulatory continuity in FDA 21 CFR 864.3600 and EU MDR regimes; material policy shifts in software-as-medical-device classification or reimbursement code expansion would require re-modeling. Specific risks include supply disruption in German-Japanese optical glass channels and faster-than-anticipated flat-panel display substitution in high-throughput laboratories. Recalibration cycles align with material shifts in notified body interpretation timelines and digital pathology infrastructure deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Breathing Circuits Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market