
 Global Surgical Polypropylene Mesh Market | 2026-2036
Global Surgical Polypropylene Mesh Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Polypropylene Mesh Market Foresight
Post-operative monitoring subscriptions are decoupling device revenue from implant sales in the surgical mesh sector. Ethicon leverages its Johnson & Johnson parent infrastructure to bundle digital follow-up tools with mesh deployment, sustaining recurring revenue streams alongside hardware. Medtronic anchors its competitive stance through specialized hernia repair portfolios that dominate North American hospital purchasing agreements. B. Braun Melsungen AG competes on European manufacturing scale, controlling distribution through direct sales teams in German and French surgical centers.
Surgical polypropylene mesh consists of monofilament or multifilament polypropylene fibers woven or knitted into porous sheets with pore sizes typically exceeding 75 micrometers to permit tissue ingrowth and reduce inflammatory encapsulation. Surgeons implant these permanent synthetic constructs to reinforce weakened fascia during hernia repair, pelvic organ prolapse correction, and abdominal wall reconstruction procedures where native tissue tensile strength proves inadequate. Lightweight mesh variants now lead volume shipments due to reduced foreign body response and lower chronic pain incidence versus heavyweight predecessors, while composite mesh configurations command premium positioning by combining polypropylene substrates with absorbable barrier layers. Laparoscopic integration technology represents the fastest-expanding deployment modality as minimally invasive protocols displace open surgery in inguinal hernia protocols across developed health systems.
FDA 510(k) premarket notification requirements govern polypropylene mesh clearance in the United States, while EU MDR and CE marking obligations enforce biocompatibility and clinical performance documentation across European markets. China's NMPA implements GB standards for synthetic implant materials, creating divergent testing protocols that manufacturers must navigate for multi-territory product registration. Stakeholders must monitor how FDA post-market surveillance orders and EU MDR notified body capacity constraints reshape competitive access timelines for new mesh entrants.
Market Dynamics
Post-operative monitoring subscriptions are decoupling device revenue from implant sales, forcing manufacturers to build recurring revenue infrastructure alongside hardware production. EU MDR recertification timelines and FDA post-market surveillance orders compress competitive access windows for new entrants.
Growth Catalysts
- Laparoscopic integration technology:Minimally invasive protocols are displacing open surgery in inguinal hernia repair across German and US hospital systems. Surgeons demand mesh products compatible with robotic-assisted deployment platforms.
- Lightweight polypropylene variants:Reduced foreign body response and lower chronic pain incidence versus heavyweight predecessors drive hospital formulary adoption. Tissue ingrowth optimization above 75-micrometer pore thresholds improves long-term patient outcomes.
- China's NMPA pathway harmonization:Streamlined GB standards alignment for synthetic implant materials accelerates multi-territory registration strategies. Domestic production scale-up reduces import dependency for pelvic organ prolapse mesh.
Market Restraints
- Propylene monomer price volatility:Petrochemical feedstock fluctuations compress margin predictability for mesh manufacturers without backward integration into polymer production.
- EU MDR notified body capacity constraints:Extended CE marking timelines for polypropylene mesh recertification delay product launches and freeze competitive repositioning.
- Biologic mesh substitution threat:Porcine and bovine-derived alternatives capture premium abdominal wall reconstruction cases where synthetic foreign body response remains clinically contested.
Strategic Opportunities
- India's underpenetrated hernia repair market:CDSCO regulatory pathway maturation coincides with private hospital chain expansion into tier-2 cities. Mesh manufacturers can establish early procurement relationships before procurement consolidates.
- Composite mesh with absorbable barriers:Polypropylene substrates paired with anti-adhesive layers command premium positioning in ventral hernia repair where bowel contact risk demands specialized construction.
- Digital follow-up platform bundling:Remote patient monitoring subscriptions attached to implant sales create recurring revenue streams and deepen hospital account stickiness.
Industry Challenges
- Biocompatibility documentation complexity:ISO 10993 testing requirements for permanent implants demand extended preclinical timelines and specialized toxicology expertise that mid-cap manufacturers struggle to resource.
- Surgeon training protocol standardization:Laparoscopic mesh deployment techniques vary across teaching hospitals, creating inconsistent outcomes that complicate product positioning and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Polypropylene Mesh Market |
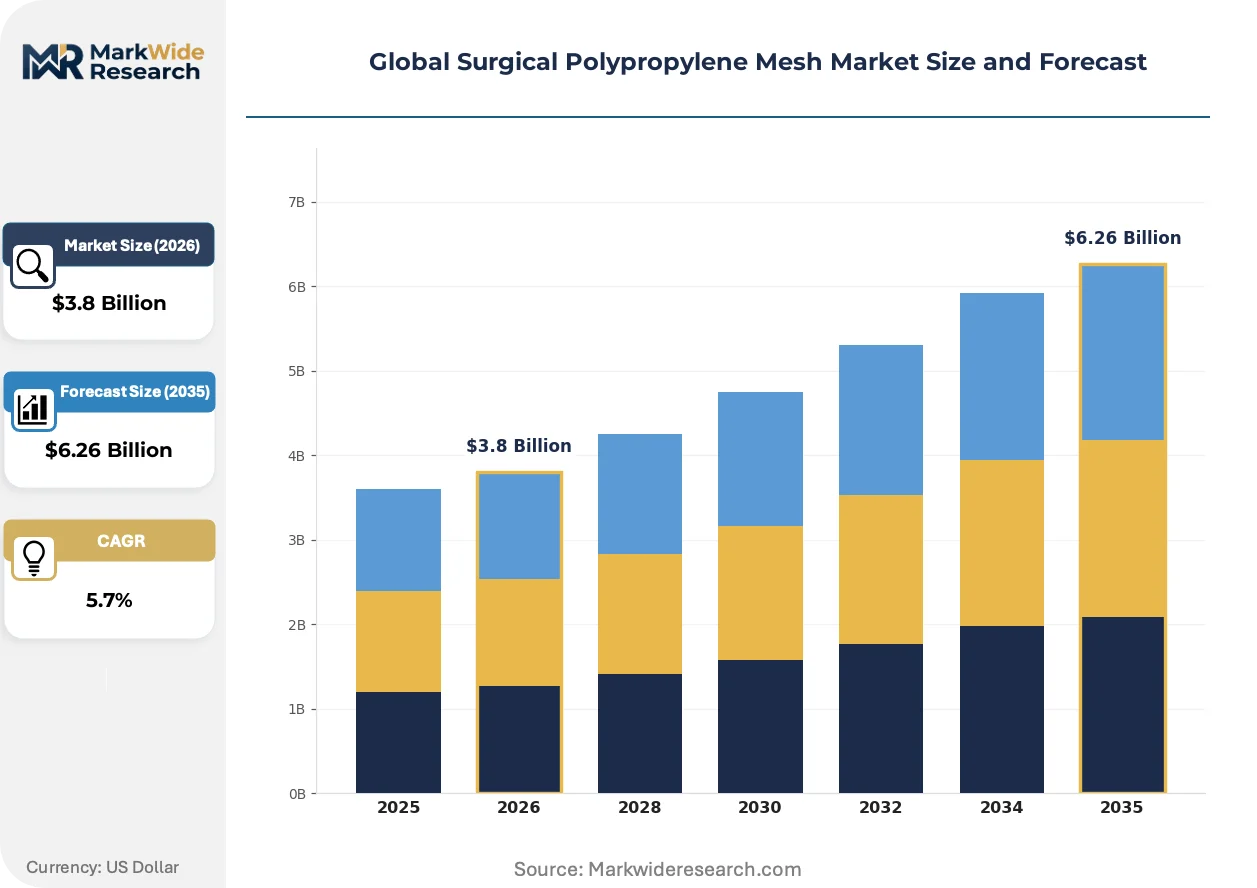
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Mesh, Heavyweight Mesh, Composite Mesh, Coated Mesh, Barbed Mesh Application: Hernia Repair, Pelvic Organ Prolapse, Stress Urinary Incontinence, Abdominal Wall Reconstruction End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Recovery Centers Technology: Knotless Fixation, Laparoscopic Integration, Robotic Assistance, Ultrasonic Sealing |
| Companies Covered | Ethicon, Medtronic, Johnson & Johnson, B. Braun Melsungen AG, Becton Dickinson, C. R. Bard, W. L. Gore & Associates, Pierson Surgical, Lotus Surgicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Polypropylene Mesh Market Shifts & Advancements
Lightweight mesh construction and digital service bundling are rewriting how manufacturers capture value beyond the implant transaction. Regulatory documentation burdens and procurement consolidation reshape competitive positioning across developed health systems.
Three-dimensional knitting technology is rewriting structural performance standards for polypropylene mesh. Multifilament fiber architectures permit directional compliance matching native fascia mechanics. Academic medical centers in Germany and the United States prioritize these constructions for complex abdominal wall reconstruction where anisotropic load distribution prevents recurrence. The technology is compressing market share for conventional woven sheet products.
EU MDR Article 120 transition deadlines enforce clinical performance documentation for legacy polypropylene mesh products. Notified body capacity shortages extend recertification timelines to 18-24 months. Lightweight and composite configurations face the tightest scrutiny due to post-market surveillance data requirements. Manufacturers with established quality management systems capture competitive access windows.
Hospital procurement consolidation around comprehensive service contracts concentrates vendor selection authority. Integrated delivery networks in the United States and purchasing cooperatives in Germany bundle mesh supply with training, warranty, and remote monitoring. Smaller surgical centers lose negotiation leverage and face reduced product choice. This pattern is most visible in North American health system consolidation.
Global Surgical Polypropylene Mesh Market Segmentation
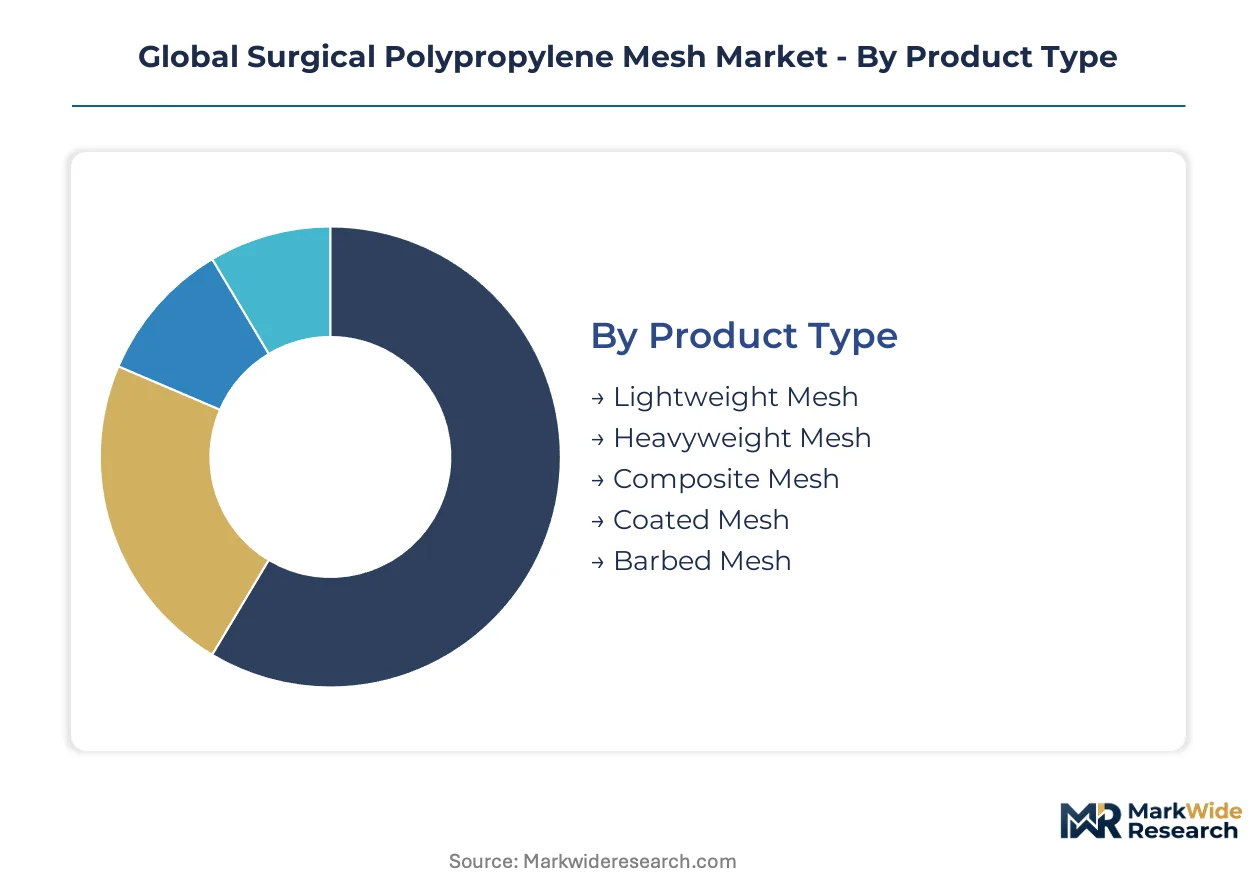
Surgical polypropylene mesh manufacturers align product portfolios with specific procedural economics and reimbursement pathways. Segmentation reveals where procurement authority concentrates and which technical specifications command premium positioning.
Product Type:
Hospital formulary committees differentiate mesh purchases based on chronic pain incidence profiles and recurrence rate data.
- Lightweight Mesh:Reduced polypropylene density below 35 grams per square meter minimizes foreign body response. German and US hospital systems prioritize these constructions for inguinal hernia protocols where patient-reported outcomes drive value-based contracting.
- Composite Mesh:Polypropylene substrates laminated with absorbable barrier layers prevent visceral adhesion in ventral hernia repair. Demand concentrates in academic medical centers performing complex abdominal wall reconstruction where bowel contact risk demands specialized construction.
- Heavyweight Mesh:Dense woven constructions exceeding 90 grams per square meter retain tensile strength for permanent fascial reinforcement in high-tension closures.
- Coated Mesh:Hydrophilic or collagen coatings modify surface properties to accelerate tissue integration in contaminated surgical fields.
- Barbed Mesh:Integrated fixation elements eliminate suture placement in laparoscopic deployment, reducing operative time in ambulatory settings.
Volume sits with Lightweight Mesh; growth tilts toward Composite Mesh.
Application:
Reimbursement coding density and litigation exposure reshape how manufacturers allocate commercial resources across surgical specialties.
- Hernia Repair:Inguinal and ventral hernia procedures generate the highest mesh consumption volumes globally. US Medicare bundled payment models and German DRG classifications standardize device selection around lightweight polypropylene for routine cases.
- Abdominal Wall Reconstruction:Complex defect repairs following trauma or oncologic resection require large-format mesh with directional compliance. Tertiary referral centers in the United States and Germany drive adoption of three-dimensional knitted architectures.
- Pelvic Organ Prolapse:Transvaginal mesh placement faces regulatory scrutiny from FDA post-market surveillance orders, compressing commercial access.
- Stress Urinary Incontinence:Mid-urethral sling procedures utilize narrow polypropylene tape configurations with specific pore architecture for tissue integration.
Revenue concentrates in Hernia Repair; margins expand fastest in Abdominal Wall Reconstruction.
End User:
Purchasing authority and inventory management requirements fragment demand across facility types with divergent capital constraints.
- Hospitals:Integrated delivery networks consolidate mesh procurement through centralized value analysis committees. Comprehensive service contracts bundle supply with training and warranty coverage, favoring vendors with established quality management systems.
- Ambulatory Surgical Centers:Freestanding facilities prioritize knotless fixation and pre-shaped mesh configurations to minimize operative time and anesthesia exposure. Reimbursement pressure drives preference for standard lightweight constructions over premium composites.
- Specialty Clinics:Urogynecology and hernia-focused practices maintain direct purchasing relationships for specific mesh geometries not available through hospital formularies.
- Recovery Centers:Post-acute facilities influence mesh selection indirectly through readmission penalty exposure transmitted to implanting surgeons.
Procurement volume aggregates in Hospitals; fastest expansion occurs in Ambulatory Surgical Centers.
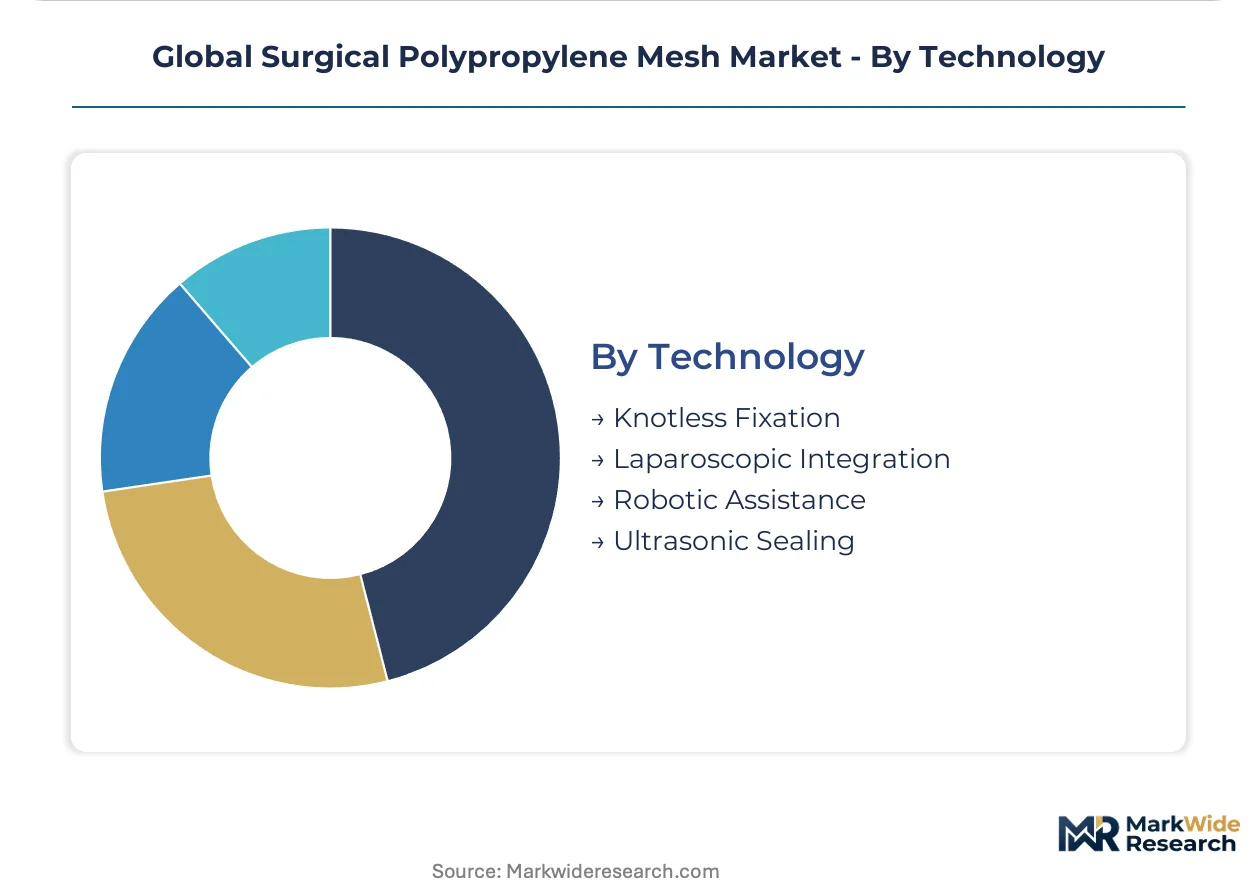
Technology:
Deployment modality determines mesh construction requirements and creates distinct competitive access points for instrumentation vendors.
- Laparoscopic Integration:Pre-shaped and memory-recoil mesh designs accommodate trocar insertion and intracorporeal manipulation. German surgical societies and US minimally invasive surgery fellowships standardize training around specific fixation device combinations.
- Robotic Assistance:Articulating mesh deployment systems integrate with da Vinci and competing platforms for precise placement in confined pelvic spaces. Capital equipment concentration in US health systems creates vendor lock-in effects.
- Knotless Fixation:Self-anchoring mesh constructions or integrated tacking systems eliminate suture time in open and laparoscopic cases.
- Ultrasonic Sealing:Energy-based mesh fixation reduces mechanical tacker complications in thin abdominal walls.
Deployment volume centers on Laparoscopic Integration; capability investment flows toward Robotic Assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of polypropylene mesh concentrates in Germany and the United States, while consumption spreads across hospital systems in China and India where hernia repair volumes outpace domestic production capacity. This geographic split shapes regulatory strategy and distribution investments for implant vendors.
United States
FDA 510(k) clearance pathways govern mesh entry into the world's highest-value surgical device market. Bundled payment models from CMS drive hospital formulary consolidation around lightweight polypropylene for routine hernia cases. The Minneapolis surgical corridor anchors North American distribution infrastructure for mesh manufacturers serving integrated delivery networks.
Germany
EU MDR recertification deadlines compress competitive timelines for legacy mesh products entering European markets. DRG reimbursement classifications standardize device selection around cost-effective lightweight constructions for inguinal repair. The Tuttlingen surgical instrument cluster integrates mesh supply with laparoscopic fixation systems for export across EU member states.
China
NMPA harmonization with GB standards accelerates registration for multinational mesh manufacturers seeking access to tier-1 hospital procurement. Domestic production scale-up in Jiangsu and Zhejiang provinces reduces import dependency for pelvic organ prolapse mesh. Shanghai's medical device innovation zones host joint ventures combining foreign polymer expertise with local regulatory navigation.
India
CDSCO pathway maturation coincides with private hospital chain expansion into tier-2 cities for hernia repair access. Price-sensitive procurement favors standard lightweight mesh over premium composite configurations in government hospital tenders. The Ahmedabad surgical device corridor builds regional manufacturing capacity for export to Southeast Asian and Middle Eastern markets.
Brazil
ANVISA registration requirements create extended timelines for polypropylene mesh commercialization in Latin America's largest surgical device market. Private health insurance expansion drives demand for laparoscopic-compatible mesh in São Paulo and Rio de Janeiro metropolitan surgical centers. Local distributors in the Campinas medical technology cluster manage import logistics for multinational manufacturers without direct Brazilian subsidiaries.
Global Surgical Polypropylene Mesh Market Competitive Landscape
Top-tier vendors anchor comprehensive service contracts with integrated delivery networks, while mid-cap specialists compete on European manufacturing scale and regional distribution relationships. Johnson & Johnson subsidiary infrastructure enables digital follow-up platform bundling that smaller manufacturers struggle to replicate. Strategic archetypes include diversified medical device conglomerates, European manufacturing specialists with direct sales teams, and emerging Asian fabricators building cost-positioned portfolios. Dominant competitive moves encompass M&A for digital health capabilities and capacity expansion in polymer fiber production to secure margin control.
Among diversified healthcare conglomerates, Ethicon and Medtronic exemplify the service-contract archetype through parent-company infrastructure enabling bundled monitoring subscriptions. B. Braun Melsungen AG occupies a position representing European manufacturing scale with direct distribution control in German and French surgical centers. These three anchors demonstrate how competitive positioning diverges between North American platform bundling and European manufacturing proximity strategies.
| Leading Market Players |
|---|
| Ethicon |
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Becton Dickinson |
| C. R. Bard |
| W. L. Gore & Associates |
| Pierson Surgical |
| Lotus Surgicals |
| Others |
Supply & Pricing Matrix
Backward integration into polymer fiber production anchors margin control for mesh manufacturers while compressing pricing power for non-integrated competitors. German and US producers with captive polypropylene supply command premium positioning against Asian fabricators exposed to propylene monomer spot markets.
Pricing Analysis
Cost compression in standard lightweight mesh reflects petrochemical feedstock volatility and procurement consolidation among US integrated delivery networks. Three-tier pricing structure across premium composite, standard lightweight, and economy heavyweight levels segments buyer archetypes by surgical complexity and reimbursement coding density. FDA 510(k) clearance tier and ISO 10993 biocompatibility certification grade drive price differentiation between established vendors and emerging entrants. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers prioritize clinical outcome data over unit cost.
Supply Chain Analysis
ISO 13485 quality management certification and EU MDR technical documentation requirements gate supplier entry for polypropylene fiber and mesh finishing tiers. Polymer production concentrates in Germany, the United States, and China, with medical-grade fiber drawing anchored in Tuttlingen surgical corridors and Minneapolis medical device clusters. Raw material dependencies span propylene monomer, medical-grade colorants, and absorbable barrier polymers for composite constructions. Single-source vulnerability in notified body capacity for CE marking creates recertification bottlenecks. Distribution runs through direct sales teams for hospital IDNs and specialized distributors for ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body capacity constraints prop pricing power for manufacturers with established quality systems, creating a supply-constrained market structure favoring incumbents with recertification runway.
For Market Incumbents: Lock in hospital procurement relationships through comprehensive service contracts bundling mesh supply with digital follow-up platforms and surgeon training protocols. Biologic mesh substitution threat from porcine-derived alternatives demands defensive R&D investment in composite barrier technologies. Capacity addition in polymer fiber production secures margin control against propylene monomer volatility. Certification investment in China's NMPA pathway captures tier-1 hospital access before domestic competitors scale. For New Entrants and Emerging Players: CDSCO regulatory pathway maturation in India opens a window for lightweight mesh positioning before private hospital chain procurement consolidates around established vendors. India's underpenetrated tier-2 city hernia repair market offers white-space expansion with price-sensitive government tender access. Robotic-assisted deployment platform compatibility represents the most penetrable technology segment for differentiated entry. Go-to-market angle should target direct relationships with hernia-focused specialty clinics bypassing hospital formulary gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified medical device conglomerates seeking digital health capabilities and European manufacturing footprint. Long-term viability favors targets with established EU MDR quality management systems and backward integration into polymer production. Acquisition target archetype: mid-cap European manufacturers with direct sales control in German surgical centers and pending NMPA registration in China. Signal to watch as inflection indicator: FDA post-market surveillance order modifications affecting transvaginal mesh litigation exposure and pelvic organ prolapse segment reopening.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Investment | Notified body capacity shortages extend timelines for legacy mesh products entering European markets. |
| Digital Follow-Up Platform Development | Remote patient monitoring subscriptions attached to implant sales create recurring revenue streams. |
| China NMPA Registration Pathway | Harmonized GB standards accelerate multinational access to tier-1 hospital procurement. |
| Robotic Deployment Compatibility | Articulating mesh systems integrate with da Vinci platforms for precise pelvic placement. |
| Backward Polymer Integration | Captive fiber production insulates margins from propylene monomer spot market volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this surgical mesh market assessment. Primary interviews with hernia surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, EU MDR notified body registries, NMPA approval records, and hospital procurement databases. Bottom-up mesh shipment estimates triangulated against top-down healthcare expenditure allocations.
Data-stream reconciliation across volume shipments, ASP trends, and reimbursement coding density validated segment-level projections. Modeled dimensions span product type, application, end user, and deployment technology across the projection horizon. CAGRs derived from procedure volume elasticity, pricing trajectory analysis, and technology substitution curves. Forecast inputs incorporate laparoscopic adoption rates and biologic mesh competitive displacement parameters.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted deployment would alter the outlook. Forecasts reflect assumptions regarding EU MDR recertification timelines and China domestic production scale-up. Material change in FDA post-market surveillance orders or notified body capacity expansion warrants a model refresh.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Surgical Mesh Market
Medical Devices
Baby Thermometer Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Surgical Devices Market