
 Blood Collection Market | 2026-2036
Blood Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Collection Market Intelligence
The division between specialized, value-added collection systems and high-volume, price-sensitive commodity products is recalibrating the market's competitive structure. Becton, Dickinson and Company leverages its extensive patent portfolio and integrated systems to command the premium segment. Greiner Bio-One International GmbH competes through specialization in safety-engineered devices and specific application niches. Cardinal Health utilizes its vast distribution network to serve the high-volume hospital and clinic channels with a broad portfolio of essential supplies.
Blood collection involves devices designed for the safe withdrawal and containment of whole blood, plasma, or serum for subsequent analysis. These systems often incorporate pre-measured vacuum pressure and specific additives like EDTA or sodium citrate to prevent coagulation for diagnostic procedures. Vacutainer tubes represent the largest product segment due to their widespread use in routine venipuncture. Hospitals and large diagnostic laboratories constitute the primary end-user base, commanding significant purchasing power and driving requirements for automation-compatible products.
Market access is governed by stringent regulatory frameworks, including the FDA's 510(k) clearance process in the United States and the CE marking under the MDR in Europe. China's NMPA imposes its own distinct device registration and testing requirements, creating another layer of compliance for manufacturers. Navigating these disparate regional standards while investing in automation-compatible and safety-engineered products remains a central challenge for all participants in this market.
Market Dynamics
The central structural force is the bifurcation of the market into high-volume, price-sensitive consumables and premium, specialized systems. This division dictates distinct competitive strategies, supply chain configurations, and regulatory pathways for participants targeting either diagnostic laboratories or niche clinical applications.
Growth Catalysts
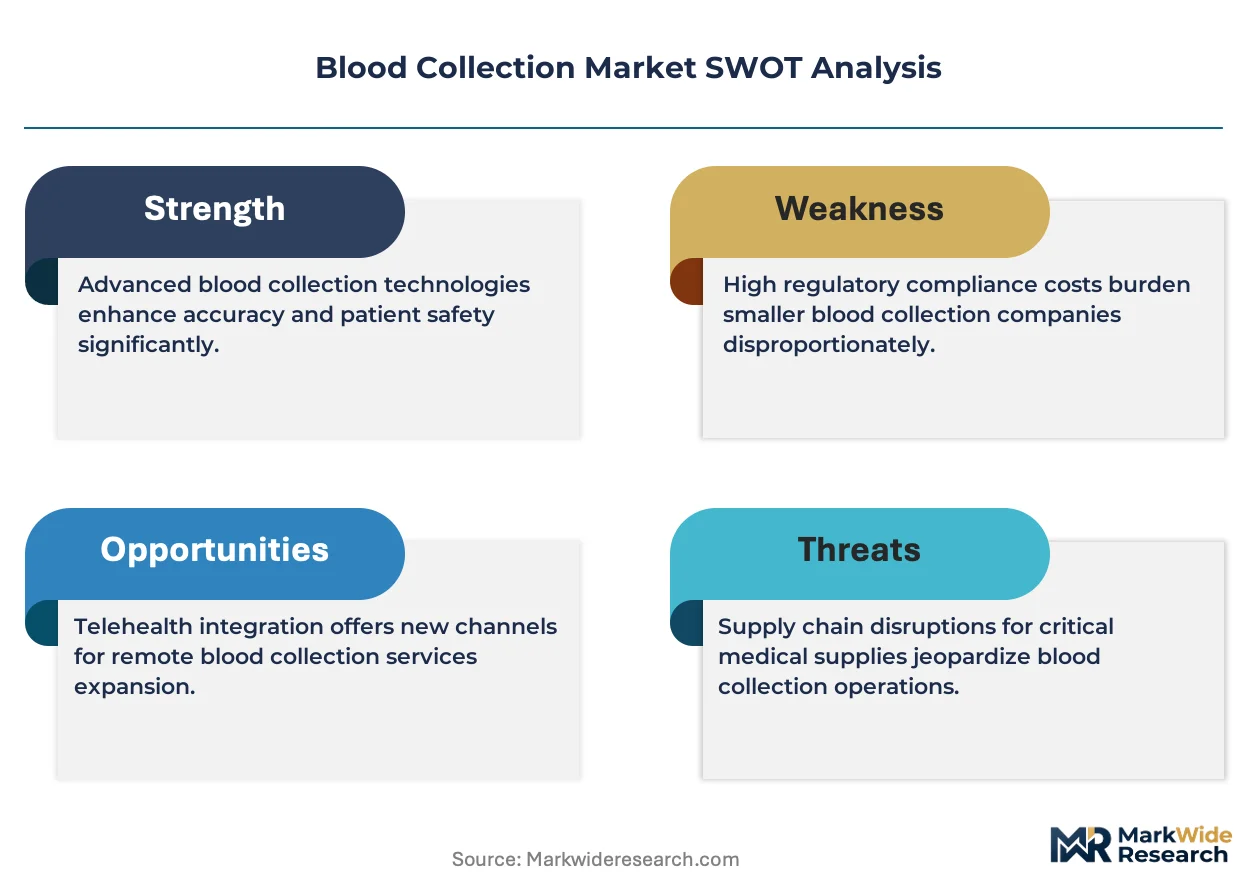
- Material Transition to PET:The industry-wide shift from glass to polyethylene terephthalate (PET) tubes, driven by improved safety and sample integrity demands from regulators like the FDA, expands the market for advanced plastic-based collection systems.
- Diagnostic Testing Volume:Chronic disease management and expanding preventative care programs in developed countries like the United States and Germany are increasing the volume of routine blood tests processed by diagnostic laboratories.
- Healthcare Infrastructure Expansion:Government investment in public health systems in countries such as China and Brazil creates new demand for fundamental diagnostic equipment, including blood collection devices, in newly established hospitals and clinics.
Market Restraints
- Commodity Price Pressure:In the high-volume segment for standard tubes, intense price competition from multiple vendors compresses profit margins, particularly for sales to large hospital networks with significant purchasing power.
- Regulatory Fragmentation:Manufacturers face significant costs and delays navigating disparate regulatory requirements, such as the FDA's 510(k) process, Europe's MDR, and China's NMPA standards, which hinders rapid global product rollouts.
- Additive Supply Chain Risks:The supply of critical anticoagulants like sodium citrate and EDTA is concentrated among a few chemical suppliers, creating potential vulnerability to price volatility or sourcing disruptions for tube manufacturers.
Strategic Opportunities
- Specialized Diagnostic Kits:Developing collection tubes optimized for emerging fields like liquid biopsy and cell-free DNA (cfDNA) testing offers a high-margin opportunity, catering to the specific preanalytical requirements of genomic and proteomic analysis.
- Digital Sample Tracking:Integrating RFID tags or unique 2D barcodes directly onto tubes enables seamless integration with Laboratory Information Management Systems (LIMS), improving sample traceability and reducing manual errors in automated labs.
- Point-of-Care Collection:Designing simplified, low-volume blood collection systems for use in clinics, pharmacies, and home-health settings opens a new channel outside the traditional hospital and large laboratory environment.
Industry Challenges
- Automation Compatibility:Ensuring new tube designs and sizes are fully compatible with the diverse range of high-throughput automated analyzers used in central laboratories presents a persistent engineering and validation challenge for device manufacturers.
- Sterilization Process Validation:Validating sterilization methods, such as gamma irradiation or ethylene oxide, to meet stringent sterility assurance levels required by the FDA and other bodies is a costly and time-consuming process for all product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Collection Market |
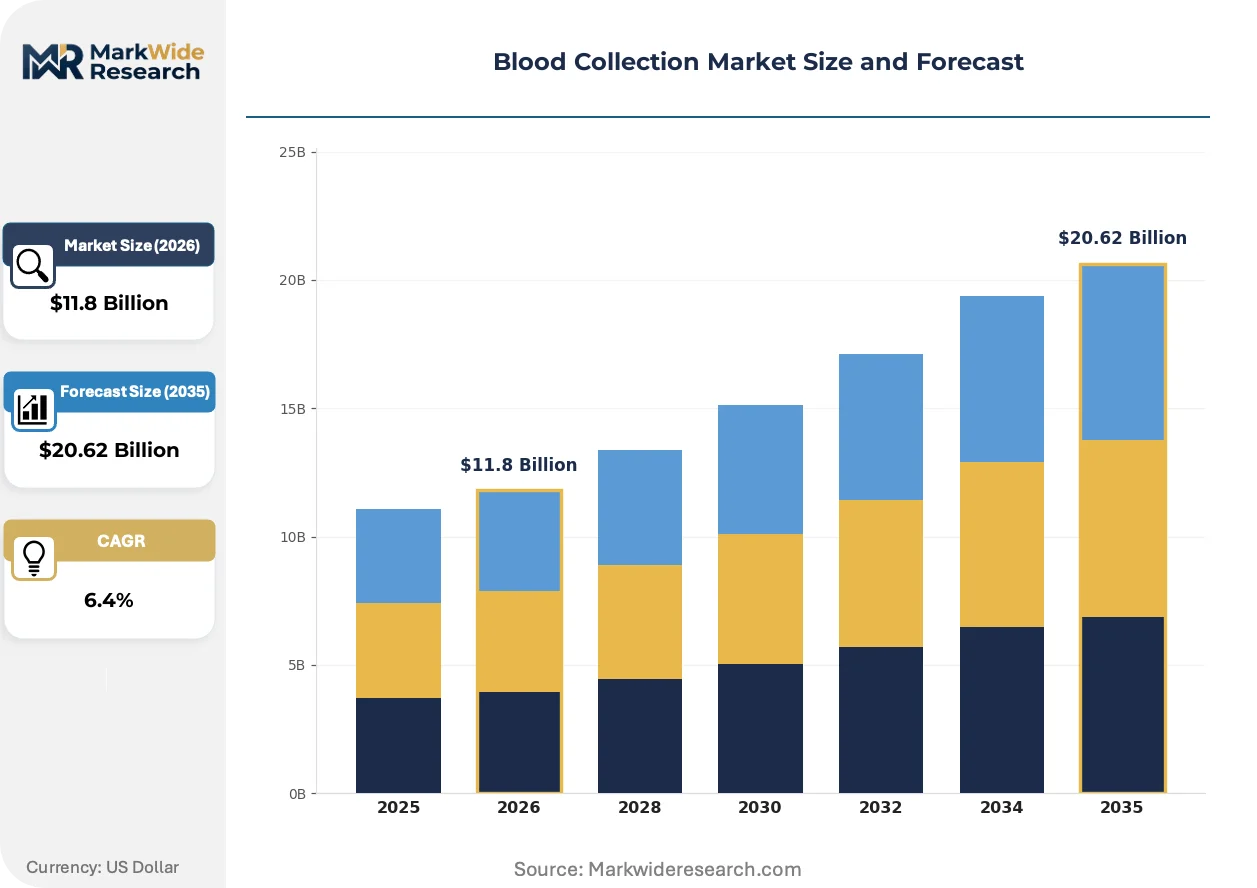
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacutainer, Blood Bag, Syringe, Capillary Tube End User: Hospitals, Blood Banks, Diagnostic Laboratories, Clinics Collection Method: Venipuncture, Fingerstick, Heelstick, Microcollection Material: Plastic, Glass, Coated Materials, Sterile Components |
| Companies Covered | Becton, Dickinson and Company, Terumo Corporation, Cardinal Health, Greiner Bio-One International GmbH, Fresenius SE & Co. KGaA, Haemonetics Corporation, Nipro Corporation, SARSTEDT AG & Co. KG, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Collection Market Strategic Shifts & Innovations
Product development is shaped by the parallel demands for greater automation efficiency within laboratories and enhanced safety for healthcare workers during sample collection. This results in innovations focused on mechanical design, material science, and digital integration to reduce human error.
Safety-engineered devices feature integrated mechanisms like retractable needles and protective shields to prevent accidental needlestick injuries. Healthcare systems adopt these products to comply with worker safety regulations, such as those enforced by OSHA in the United States. This focus on needlestick prevention is rewriting the standard of care for routine phlebotomy, making non-safety devices increasingly untenable in regulated markets.
The European Union's Medical Device Regulation (MDR) has introduced more rigorous requirements for clinical evidence, risk management, and post-market surveillance. This regulatory shift elevates the cost and complexity of maintaining a CE marking, which is essential for market access in Europe. The vacuum tube segment is particularly affected, forcing manufacturers to invest heavily in updated technical documentation and clinical evaluation reports.
Consolidation of purchasing power through Group Purchasing Organizations (GPOs) and large Integrated Delivery Networks (IDNs) is altering procurement dynamics. This trend favors large-scale manufacturers who can compete on volume pricing and offer a broad portfolio of supplies, often marginalizing smaller, specialized vendors. This model is especially dominant in the United States healthcare market, influencing purchasing decisions for the majority of hospitals.
Blood Collection Market Segmentation
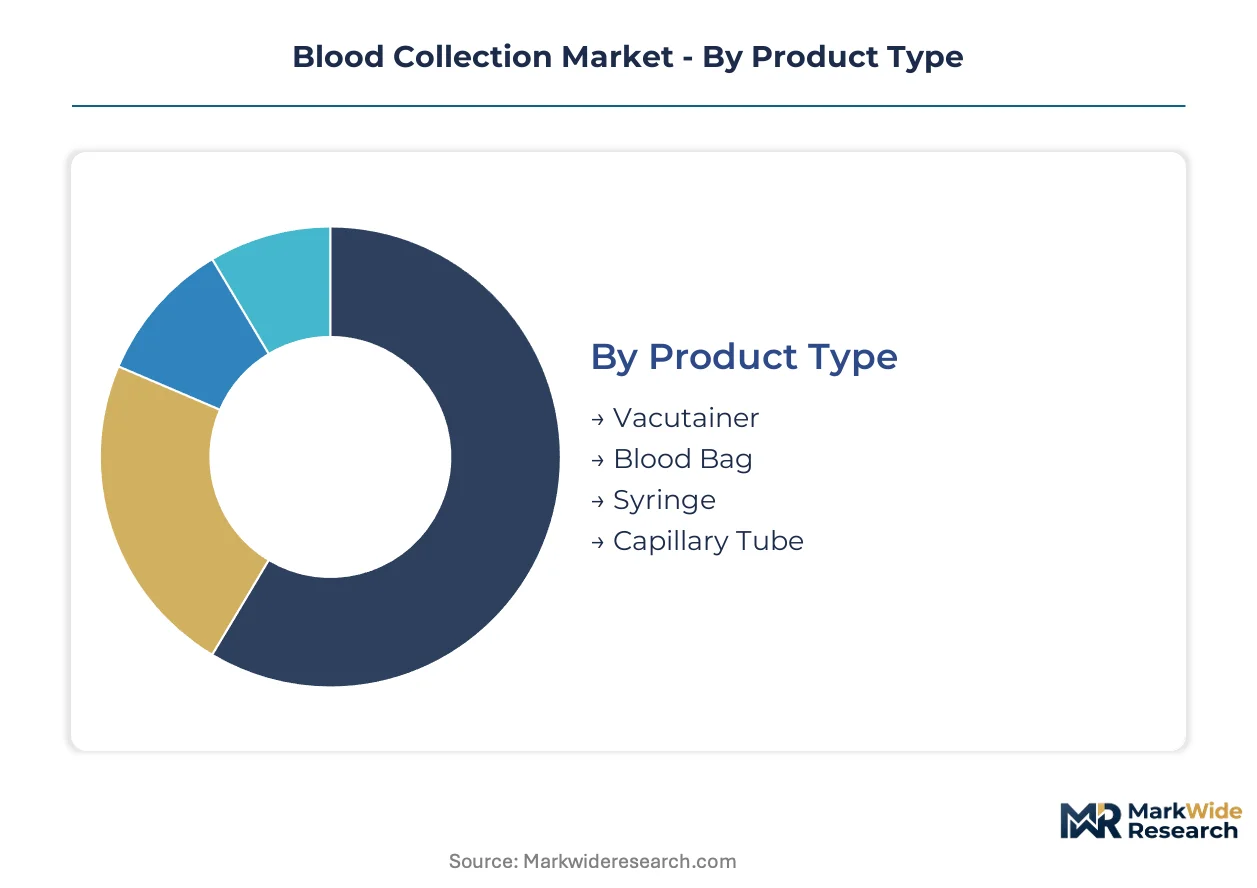
The Blood Collection Market's segmentation reveals the distinct product categories, end-user requirements, collection methodologies, and material innovations that define industry offerings. Understanding these divisions is crucial for manufacturers to align product development with specific clinical needs and regulatory demands across different healthcare settings.
Product Type:
Product type segmentation highlights the diverse technological approaches for blood collection, each designed for specific volumes and analytical requirements.
- Vacutainer:These evacuated tubes are the largest product segment, featuring pre-measured vacuum and various additives to prevent coagulation for diagnostic procedures. Their widespread use in routine venipuncture and compatibility with automated laboratory systems drives high-volume demand in diagnostic laboratories across the United States.
- Blood Bag:Designed for collecting and storing larger volumes of whole blood or blood components, these sterile bags are essential for transfusion medicine and blood banking operations. Demand concentrates in national blood services and major hospital networks in countries like China, supporting extensive patient care programs.
- Syringe:Traditional syringes offer controlled blood withdrawal, particularly useful for patients with fragile veins or in situations requiring precise manual aspiration. Clinics and smaller medical facilities utilize syringes for specific collection needs where vacuum tubes might be less suitable.
- Capillary Tube:These small-volume tubes are used for microcollection, often from fingersticks or heelsticks, suitable for pediatric patients or point-of-care testing.
Vacutainer leads on scale; Capillary Tube leads on momentum.
End User:
End-user segmentation differentiates procurement needs and application focus within healthcare, influencing product design and distribution strategies.
- Hospitals:These institutions represent a primary end-user segment, requiring a broad portfolio of blood collection devices for routine diagnostics, emergency care, and surgical procedures. Their significant purchasing power and demand for automation-compatible products shape supplier relationships.
- Diagnostic Laboratories:High-throughput diagnostic laboratories, both independent and hospital-affiliated, drive demand for efficient, high-volume collection systems compatible with automated analyzers. Specialized testing in these labs, particularly in Germany, requires specific tube types and additives.
- Blood Banks:Centralized blood banks focus on large-volume collection and safe storage solutions, prioritizing products that ensure sample integrity and donor safety. Regulatory compliance from bodies like the FDA is critical for these organizations.
- Clinics:Smaller clinics and physician offices utilize blood collection products for routine patient screening and localized diagnostic testing.
These entities drive demand for specialized solutions and high-volume consumables.
Collection Method:
Collection method segmentation reflects varying patient demographics and required blood volumes, influencing device design for comfort and efficacy.
- Venipuncture:The most common method, involving the withdrawal of blood from a vein, typically in the arm, using evacuated tubes or syringes. This technique remains the standard for routine diagnostic testing and large-volume sample collection in hospitals.
- Microcollection:This method involves obtaining small blood volumes, often from a fingerstick or heelstick, suitable for pediatric patients, point-of-care testing, or individuals with difficult venous access. Specialized collection devices are designed for minimal invasiveness and accurate small-volume measurement.
- Fingerstick:A common technique for obtaining capillary blood samples, primarily used for glucose monitoring or rapid diagnostic tests. It offers a less invasive alternative for certain patient populations.
- Heelstick:Specifically used for infants, this method collects capillary blood from the heel for newborn screening tests.
Venipuncture remains the standard, while microcollection techniques are expanding for sensitive patient groups.
Material:
Material segmentation underscores the importance of regulatory compliance and sample integrity, driving innovation in tube composition and safety features.
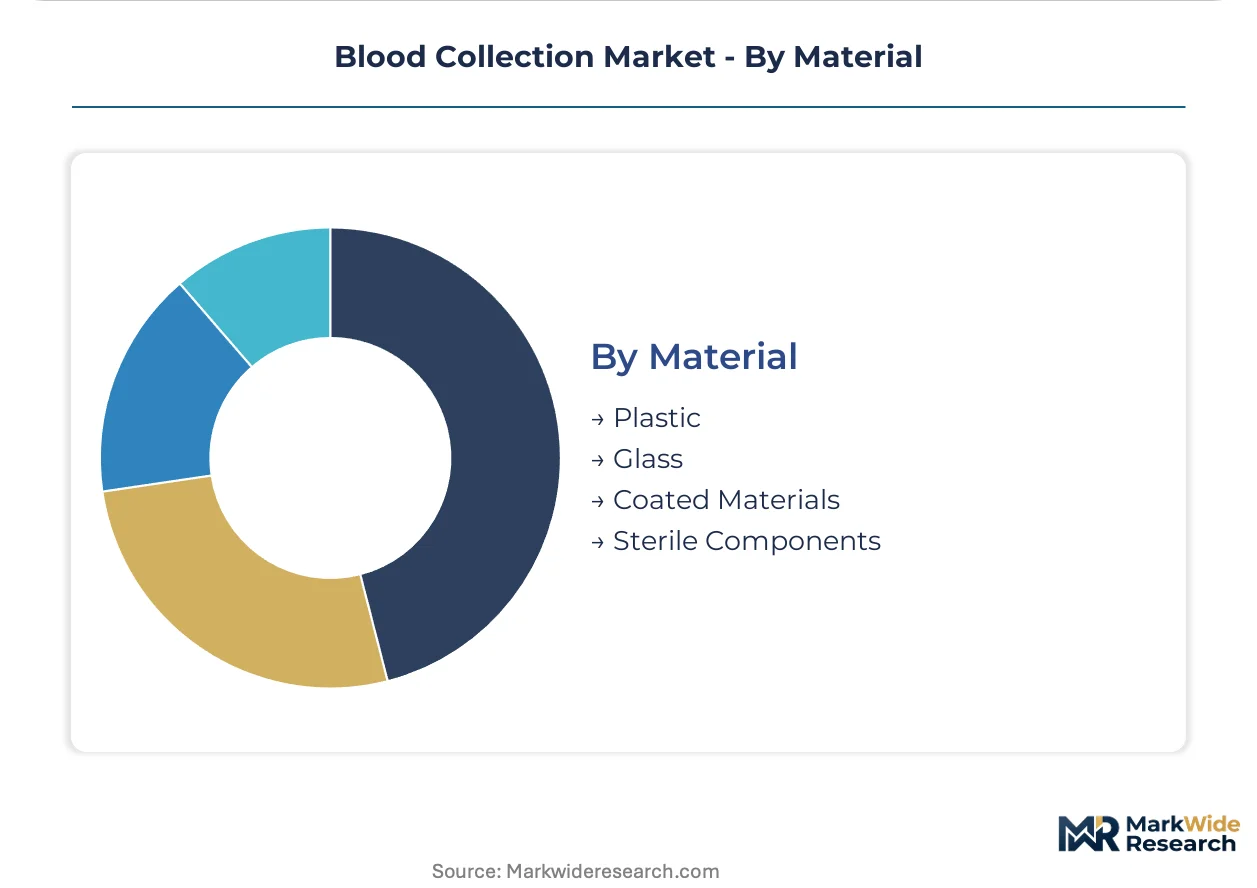
- Plastic:Polyethylene terephthalate (PET) plastic tubes are increasingly replacing glass due to improved safety, reduced breakage, and enhanced sample integrity. Regulatory bodies like the FDA mandate these material transitions for better healthcare worker protection.
- Coated Materials:These materials involve internal tube coatings with specific additives such as EDTA, sodium citrate, or heparin to prevent coagulation or preserve analytes. Such coatings are critical for accurate diagnostic results across various tests.
- Glass:Traditional glass tubes, while still in use, are being phased out in many markets due to safety concerns regarding breakage and potential biohazard exposure.
- Sterile Components:This category includes all sterile elements within blood collection systems, ensuring patient safety and preventing contamination during the collection process.
The shift to plastic materials addresses safety concerns and regulatory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global blood collection market sees significant workforce concentration in regions with advanced healthcare systems. These areas drive demand for both routine and specialized collection devices. Specialized phlebotomists and laboratory technicians form a critical talent pool supporting market expansion.
United States
Demand for blood collection systems in the United States stems from expanding preventative care programs and chronic disease management. The FDA's stringent regulations on sample integrity shape product development. Major diagnostic laboratory networks in New Jersey process high volumes of samples.
China
China's market expansion is propelled by government investment in public health infrastructure and rising diagnostic testing volumes. The NMPA imposes distinct device registration requirements for manufacturers. Large hospital systems in the Yangtze River Delta region are central to high-volume procurement.
Germany
Expanding preventative care programs in Germany contribute to sustained demand for routine blood tests and specialized collection systems. The EU's MDR introduces rigorous requirements for clinical evidence. Diagnostic laboratories in Bavaria often specialize in high-throughput analysis, requiring automation-compatible products.
Brazil
Government investment in public health systems in Brazil creates new demand for fundamental diagnostic equipment. ANVISA, the national health surveillance agency, regulates medical device approvals. Major urban centers such as São Paulo drive requirements for both basic and advanced blood collection technologies.
Japan
Japan's aging population and focus on comprehensive health screenings increase the volume of diagnostic blood tests. The PMDA oversees medical device approvals, emphasizing safety and efficacy. Large hospital groups in the Kanto region integrate advanced automation solutions for efficient sample processing.
Blood Collection Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the blood collection market. The industry exhibits a tiered structure, ranging from integrated global suppliers to specialized niche players across various product categories. Archetypes include broad-portfolio manufacturers, safety device specialists, and distribution network powerhouses serving diverse end-users. Strategic partnerships, portfolio diversification, and geographic expansion are common competitive moves.
On the premium-tier vector, Becton, Dickinson and Company exemplifies a global manufacturer leveraging an extensive patent portfolio for integrated systems. Greiner Bio-One International GmbH occupies a position among specialized European firms, focusing on safety-engineered devices and specific application niches within the market. Cardinal Health, Inc., a US-based entity, anchors the high-volume hospital and clinic channels through its vast distribution network, offering a broad portfolio of essential supplies. These companies represent distinct approaches to market access and product differentiation, reflecting the bifurcation into specialized and commodity segments.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Terumo Corporation |
| Cardinal Health |
| Greiner Bio-One International GmbH |
| Fresenius SE & Co. KGaA |
| Haemonetics Corporation |
| Nipro Corporation |
| SARSTEDT AG & Co. KG |
| McKesson Corporation |
| Others |
Cost & Logistics Intelligence
Polyethylene terephthalate (PET) tube adoption, driven by FDA safety mandates, simultaneously reshapes cost economics and supply concentration within the blood collection market. This material transition introduces new manufacturing complexities and raw material dependencies for device producers.
Pricing Analysis
Bundled solutions versus unbundled commodity products define the pricing landscape in blood collection. Per-unit transactional pricing dominates for standard vacutainer tubes, while contract-based long-term agreements secure large hospital network volumes. Price differentiation stems from certification level, such as FDA 510(k) clearance, and the volume scale of procurement. Pricing pressure from Group Purchasing Organizations intensifies in high-volume segments, making large diagnostic laboratories particularly price-sensitive for routine consumables.
Supply Chain Analysis
Reverse logistics for medical device returns remain minimal, given the single-use nature of blood collection products, focusing instead on waste management. Geographic supply concentration for raw materials like PET resin and critical anticoagulants draws heavily from China and specialized chemical producers. The supply chain faces structural risk from commodity price volatility for these essential inputs, which can impact tube manufacturers. Distribution runs through major medical supply companies like Cardinal Health for broad market access, complemented by direct sales for specialized systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood collection market is evolving into a late-cycle quality story, driven by a demand-shift toward premium specifications for automation compatibility and enhanced sample integrity. This trend prioritizes advanced materials and integrated digital features over basic functionality.
For Market Incumbents: Anchor existing market share by reinforcing extensive patent portfolios and integrated system offerings, particularly against emerging niche players. Invest heavily in R&D for automation-compatible designs and advanced safety-engineered devices to counter commodity price pressure from GPOs. Pursue strategic partnerships with diagnostic laboratories to co-develop next-generation sample tracking solutions. Certification investment for European MDR compliance remains crucial for market access.
For New Entrants and Emerging Players: Specialized preanalytical technology offers a technology-first wedge into high-margin segments like liquid biopsy and cell-free DNA testing. Target the underpenetrated point-of-care diagnostics market with simplified, low-volume collection systems for home-health settings. Implement a direct-to-specialty-lab go-to-market strategy, emphasizing unique sample preservation capabilities. Focus on rapid regulatory clearances for innovative devices in specific application niches.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy glass tube manufacturers facing material transition risks, offering potential for strategic divestiture. The long-term viability of this market rests on sustained global diagnostic testing volumes and expanding preventative care programs. Target acquisition archetypes include specialized technology firms developing digital sample tracking or novel microcollection devices. A key signal to watch is the accelerated adoption rates of new genomic testing modalities requiring specific collection protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for PET Tubes | Secures market access for safer, more compliant products, addressing regulatory mandates in the United States. |
| LIMS Integration Development | Enhances laboratory efficiency and sample traceability, meeting automation demands from large diagnostic networks. |
| Point-of-Care Device Launch | Expands market reach into new channels like clinics and home-health, capturing decentralized testing demand. |
| Advanced Additive Research | Develops specialized tubes for emerging diagnostics like liquid biopsy, capturing high-value niche applications. |
| GPO Partnership Expansion | Strengthens distribution and volume sales to large hospital systems, maintaining competitive pricing advantage. |
Research Approach
Bottom-up hospital and diagnostic laboratory end-use modeling reconciled against top-down manufacturer and raw material supply-side tracking forms the analytical core. Primary interviews engaged phlebotomists, lab directors, procurement managers, and regulatory experts across key geographies. Secondary validation drew from FDA 510(k) clearances, NMPA device registrations, company annual reports, and medical device databases. This approach ensures robust data triangulation.
Historical trendline analysis informed the projection of market dynamics across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user, collection method, material, and regional adoption patterns. Compound annual growth rates were derived from historical data, identified market drivers, and expert projections. Key forecast inputs included diagnostic testing volumes and healthcare infrastructure spending.
The model holds under conditions of stable regulatory frameworks and consistent material supply; deviation in geopolitical supply disruptions or rapid technological obsolescence would shift forecasts. Forecasts reflect documented base assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Disposable Lead Wires Market