
 Venous Blood Collection Market | 2026-2036
Venous Blood Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Blood Collection Market Analytics
The buyer base for venous blood collection products is broadening beyond traditional hospital systems toward diagnostic laboratories and research institutions running decentralized trials. Becton Dickinson and Company leverages its integrated portfolio of needles, tube systems, and safety devices to anchor procurement contracts with large laboratory networks. Sarstedt AG & Co. KG differentiates through specialized tube systems optimized for nucleic acid stabilization and specialized assays. Greiner Bio-One International GmbH competes on manufacturing scale across European and Asian production facilities.
Venous blood collection encompasses the sterile extraction, containment, and transport of blood from peripheral veins using evacuated tube systems, winged infusion sets, or syringe-based methods, with tube additives such as EDTA, heparin, or citrate determining downstream analytical compatibility. The primary commercial purpose centers on enabling accurate diagnostic testing, therapeutic monitoring, and safe blood component separation for transfusion medicine. Tube systems command the largest revenue pool given their consumable nature and regulatory-mandated single-use design, while safety devices represent the fastest-expanding category as OSHA compliance deadlines and EU MDR sharp-protection requirements accelerate mechanical needle shield adoption. Diagnostic laboratories generate the highest volume demand among end users, though blood banks sustain premium pricing for specialized collection sets meeting stringent sterility protocols.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement shape product development timelines and safety feature mandates in the United States, while EU MDR technical documentation requirements and REACH material compliance constrain European market entry for non-certified suppliers. ISO 6710 and ISO 10993 biocompatibility standards further harmonize material specifications across export markets. Stakeholders must monitor evolving EPA scrutiny on plastic tube disposal and shifting procurement consolidation among multi-site laboratory operators to anticipate volume concentration and pricing leverage dynamics.
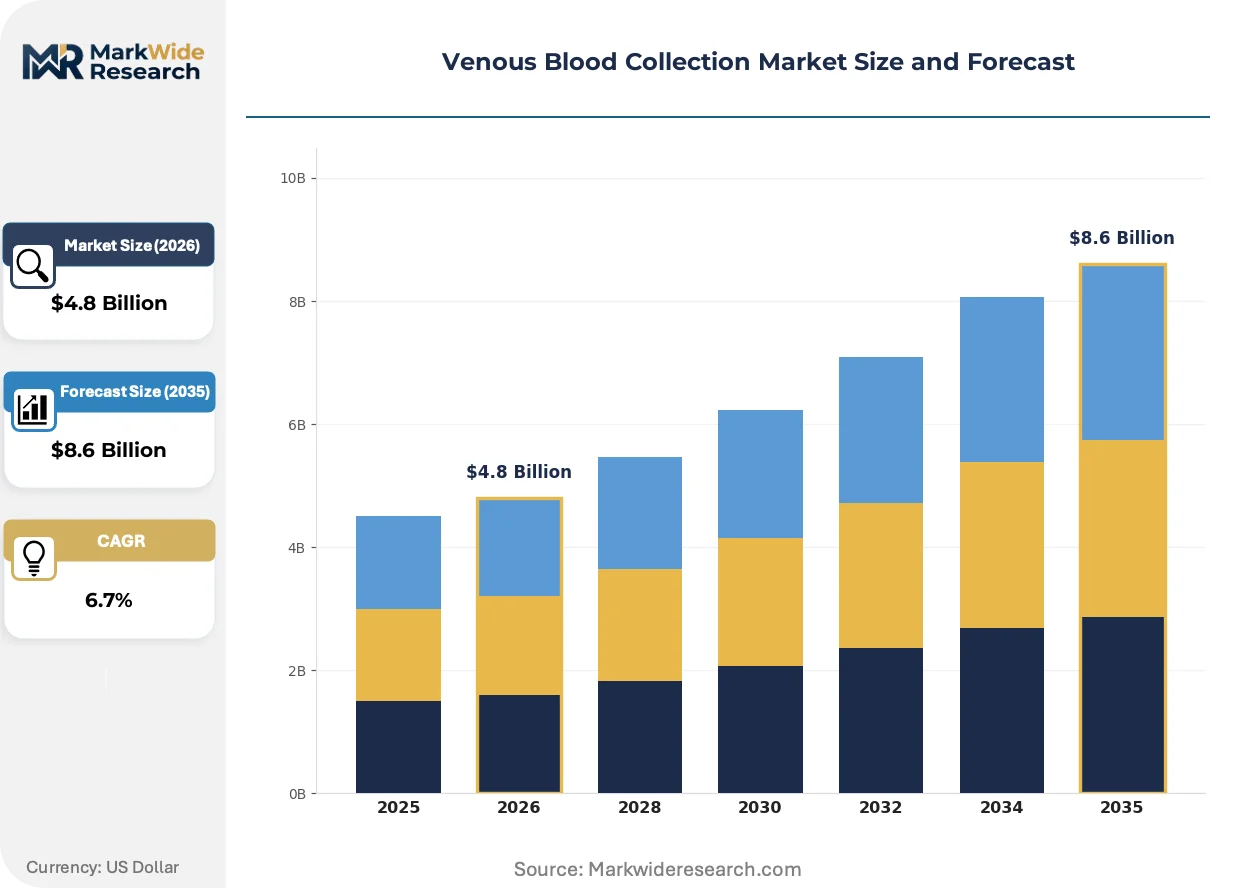
Market Dynamics
Centralized laboratory networks are consolidating procurement power while simultaneously fragmenting demand through decentralized clinical trial operations, forcing manufacturers to reconcile high-volume contract pricing with specialized product customization.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandatory safety-engineered needle requirements in US healthcare settings are accelerating mechanical shield adoption across hospital systems and outpatient clinics.
- Diagnostic laboratory automation:High-throughput sample processing lines in Germany and China are driving demand for standardized tube formats compatible with robotic handling systems.
- Nucleic acid stabilization:Specialized tube chemistries for molecular diagnostics are expanding addressable market scope beyond traditional hematology applications.
Market Restraints
- Petroleum-derived plastic dependency:Polypropylene and polyethylene input costs fluctuate with crude oil volatility, compressing margins on single-use tube manufacturing.
- EU MDR technical documentation:Extended conformity assessment timelines for Class IIa devices delay product launches and tie up regulatory capital.
- Capillary microsampling:Finger-stick alternatives for routine metabolic panels threaten volume erosion in pediatric and geriatric phlebotomy segments.
Strategic Opportunities
- India's CDSCO pathway harmonization:Streamlined medical device registration is opening access to a diagnostic infrastructure scaling rapidly through public-private laboratory partnerships.
- Home-based therapeutic monitoring:Remote blood collection kits for chronic disease management are creating direct-to-patient channel potential outside traditional hospital procurement.
- ISO 10993 biocompatibility convergence:Unified material safety standards are reducing re-certification burden for suppliers targeting multiple export markets simultaneously.
Industry Challenges
- Phlebotomy technician shortages:Workforce gaps in skilled blood collection are limiting throughput capacity at peak-demand diagnostic centers.
- Legacy LIS integration:New tube barcode formats require expensive middleware upgrades to synchronize with entrenched laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Blood Collection Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needles, Holders, Tube Systems, Safety Devices End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutions Delivery Mode: Direct Sales, Online Sales, Distribution Partners, Wholesalers Application: Routine Testing, Blood Donation, Clinical Trials, Research Studies |
| Companies Covered | Greiner Bio-One International GmbH, Medline Industries LP, Becton Dickinson and Company, Sarstedt AG & Co. KG, Nipro Corporation, Cardinal Health, Haemonetics Corporation, Fresenius Kabi AG, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Blood Collection Market Evolving Landscape
Safety engineering and material science are converging to redefine product specifications, while procurement centralization is compressing supplier margins and accelerating consolidation among mid-tier manufacturers.
Passive safety needle devices are expanding into routine venipuncture workflows across US hospital systems and European outpatient networks. These mechanisms deploy protective shields without clinician activation, reducing per-procedure time burden while satisfying OSHA compliance mandates. The technology is expanding into cost-sensitive segments previously dominated by conventional unguarded needles.
REACH substance restrictions on phthalate plasticizers are forcing reformulation of tube stopper compounds across European supply chains. ECHA scrutiny of endocrine-disrupting chemicals has accelerated migration toward thermoplastic elastomer alternatives. German and French manufacturers are absorbing certification costs fastest, while smaller southern European suppliers face delayed market re-entry.
Multi-site laboratory operators are consolidating vendor contracts to secure volume-based pricing and standardized product formats. Quest Diagnostics and LabCorp procurement templates are displacing fragmented purchasing across independent reference laboratories. This concentration is most visible in the United States, where three national networks now control majority share of tube and needle consumption.
Venous Blood Collection Market Segmentation
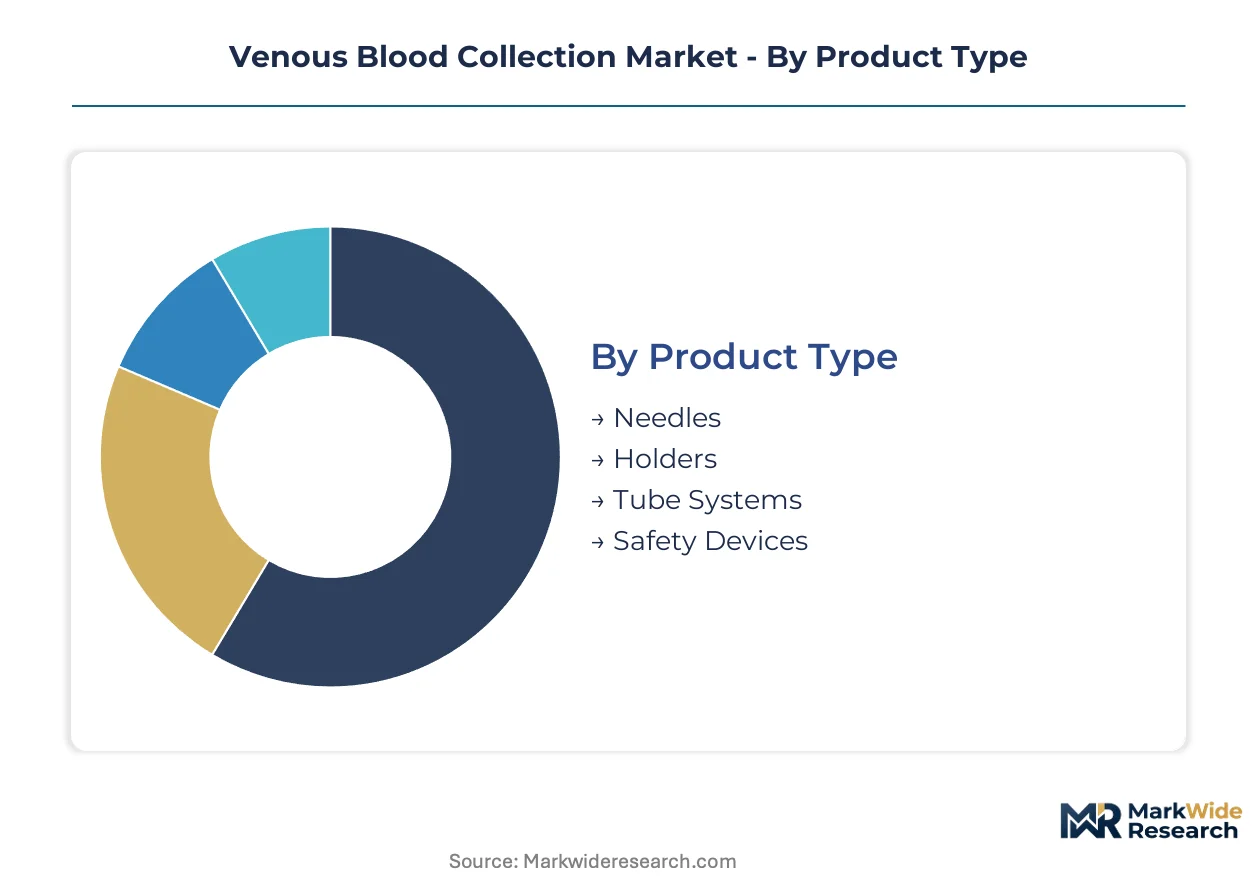
Venous blood collection segmentation reveals how capital deployment, regulatory compliance, and procurement scale reshape competitive positioning across product tiers and customer channels. Manufacturers must align manufacturing intensity with end-user automation requirements to capture contract value.
Product Type:
Tube systems demand the heaviest capital outlay for sterile molding lines and additive chemistry R&D, while safety devices require precision engineering for passive shield mechanisms.
- Tube Systems:Evacuated polypropylene containers with spray-dried additives (EDTA, heparin, citrate) determine analytical compatibility across hematology, chemistry, and molecular platforms. Demand concentrates in diagnostic laboratories across the United States, Germany, and China as these facilities scale automated sample processing lines. ISO 6710 compliance for single-use sterility and additive uniformity absorbs substantial quality assurance investment.
- Safety Devices:Mechanical needle shields with passive activation mechanisms satisfy OSHA Bloodborne Pathogens Standard mandates without clinician intervention. US hospital systems and European outpatient networks are accelerating replacement of conventional unguarded needles ahead of enforcement deadlines. EU MDR technical documentation requirements for Class IIa devices extend conformity assessment timelines and regulatory capital commitment.
- Needles:Stainless steel cannulae with bonded plastic hubs for single-use venipuncture.
- Holders:Plastic adapters connecting needles to evacuated tube systems for standard blood draws.
Tube systems absorb the bulk of installed capacity; safety devices are expanding most quickly.
End User:
Customer concentration varies sharply by procurement scale, with multi-site laboratory operators extracting volume-based pricing while research institutions require specialized customization.
- Diagnostic Laboratories:High-throughput reference labs and hospital-affiliated processing centers generate the largest consumable volumes through automated sample handling systems. Quest Diagnostics and LabCorp procurement templates in the United States are consolidating vendor relationships and standardizing tube formats. Robotic compatibility requirements favor manufacturers with dedicated automation engineering teams.
- Hospitals:Acute care facilities with mixed inpatient and emergency department phlebotomy demand safety-engineered devices for OSHA compliance and diverse tube configurations for STAT testing. US health systems are centralizing purchasing through group purchasing organizations to reduce per-procedure supply costs.
- Blood Banks:Collection sets for therapeutic donation and component separation require stringent sterility protocols and specialized bag systems.
- Research Institutions:Decentralized clinical trial operations and academic laboratories drive demand for nucleic acid stabilization tubes and specialized assay formats.
Diagnostic laboratories command the highest absolute consumption; research institutions are climbing the fastest as decentralized trial infrastructure expands.
Delivery Mode:
Channel economics favor direct relationships with large-volume purchasers, though distribution partners retain relevance for geographic coverage in fragmented markets.
- Direct Sales:Manufacturer field teams negotiate multi-year contracts with national laboratory networks and health system purchasing consortia. Direct relationships enable co-development of automation-compatible product formats and just-in-time inventory programs. US and German markets show the highest direct sales penetration due to customer concentration.
- Distribution Partners:Regional medical supply distributors serve independent laboratories and mid-tier hospital systems outside major metropolitan clusters. Indian and Chinese diagnostic infrastructure scaling through public-private partnerships relies heavily on distribution intermediaries for last-mile logistics.
- Online Sales:E-procurement platforms for smaller research laboratories and outpatient clinics.
- Wholesalers:Bulk purchasing intermediaries aggregating demand from fragmented rural healthcare providers.
Direct sales capture the majority of contract value; distribution partners are gaining share fastest in emerging diagnostic markets.
Application:
Use case differentiation determines product specification intensity, with routine testing favoring standardization and clinical trials demanding specialized chemistries.
- Routine Testing:Standard metabolic panels, complete blood counts, and lipid profiles drive the highest procedure volume through standardized EDTA and serum separator tubes. Diagnostic laboratories in the United States and Germany process millions of these draws annually through automated lines. Cost pressure from reimbursement compression favors high-volume, low-variation manufacturing.
- Clinical Trials:Decentralized studies require remote collection kits with nucleic acid stabilization, temperature-controlled transport, and chain-of-custody documentation. FDA guidance on investigational sample integrity and ICH-GCP compliance adds regulatory complexity. Direct-to-patient shipping models are emerging for chronic disease monitoring outside traditional site-based collection.
- Blood Donation:Therapeutic collection for transfusion medicine using sterile bag systems and component separation protocols.
- Research Studies:Academic and commercial R&D employing specialized tube chemistries for proteomics, metabolomics, and biomarker discovery.
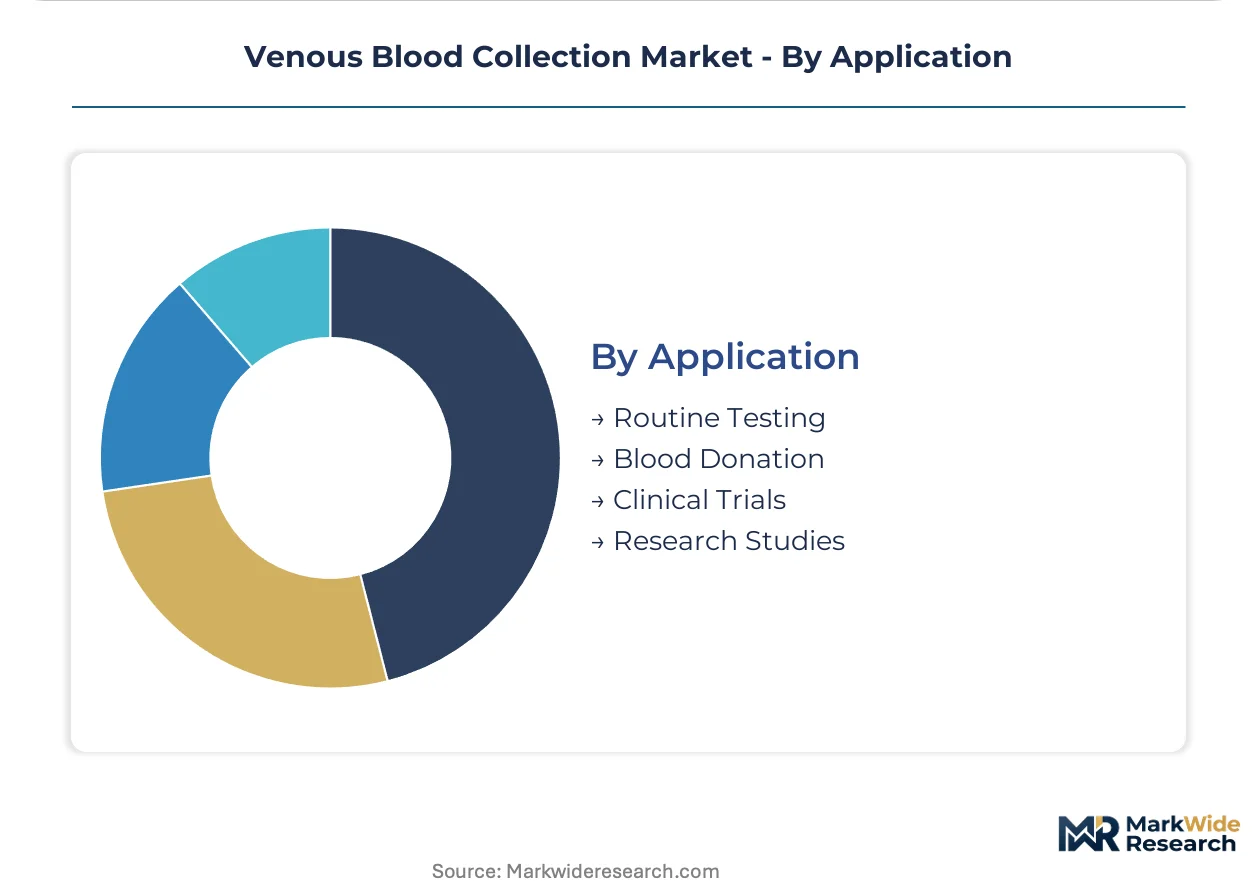
Routine testing dominates absolute procedure volume; clinical trials are expanding most quickly as decentralized trial designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin supply from the US Gulf Coast and German petrochemical corridors anchors tube manufacturing economics across major diagnostic markets. Regional demand patterns diverge sharply between mature laboratory networks and emerging health infrastructure scaling phases.
United States
Quest Diagnostics and LabCorp procurement templates now control majority tube and needle consumption through centralized vendor contracts. OSHA Bloodborne Pathogens Standard enforcement accelerates mechanical needle shield adoption across hospital systems and outpatient networks. Greater Boston and Research Triangle Park clusters concentrate specialized nucleic acid stabilization tube development for decentralized clinical trials.
Germany
High-throughput diagnostic laboratories in Munich and Hamburg drive standardized tube format demand compatible with robotic handling systems. REACH substance restrictions on phthalate plasticizers force rapid stopper compound reformulation across domestic supply chains. Baden-Württemberg manufacturing corridors absorb ECHA certification costs fastest while southern European suppliers face delayed market re-entry.
China
Public-private laboratory partnerships in Shanghai and Guangzhou scale automated sample processing lines requiring ISO 6710-compliant single-use containers. NMPA medical device registration harmonization with international standards accelerates foreign supplier market access. Yangtze River Delta diagnostic infrastructure expansion concentrates procurement volume among three national laboratory networks.
India
CDSCO pathway streamlining opens market access as diagnostic infrastructure scales through urban hospital laboratory partnerships. Mumbai and Bangalore clusters concentrate reference laboratory automation investments demanding standardized consumable formats. Distribution intermediaries retain critical last-mile logistics roles for mid-tier hospital systems outside metropolitan cores.
Japan
Aging demographics expand therapeutic monitoring demand through hospital-affiliated blood collection networks in Tokyo and Osaka. PMDA quality management system requirements maintain stringent entry barriers for non-certified tube suppliers. Kanto region diagnostic consolidation favors manufacturers with dedicated automation engineering support teams.
Venous Blood Collection Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized assay formats and nucleic acid stabilization chemistries. The vendor base stratifies across three maturity tiers: integrated multinationals with full portfolio coverage, mid-scale specialists commanding regional automation contracts, and niche entrants targeting decentralized trial logistics. Two dominant competitive moves shape positioning: manufacturing scale expansion across Asian production corridors and co-development partnerships with multi-site laboratory operators for robotic compatibility certification.
Within the integrated multinational tier, Becton Dickinson and Company and Greiner Bio-One International GmbH exemplify full-portfolio positioning spanning needles, tube systems, and safety devices. Sarstedt AG & Co. KG occupies a specialist position anchored in nucleic acid stabilization chemistries and customized assay formats. These three entities represent divergent strategic archetypes: comprehensive coverage, manufacturing scale, and technical specialization respectively.
| Leading Market Players |
|---|
| Greiner Bio-One International GmbH |
| Medline Industries LP |
| Becton Dickinson and Company |
| Sarstedt AG & Co. KG |
| Nipro Corporation |
| Cardinal Health |
| Haemonetics Corporation |
| Fresenius Kabi AG |
| Terumo Corporation |
| Others |
Value Network & Pricing Analysis
Tube system certification tiers bifurcate sharply between ISO 6710-compliant sterile containers and unbranded commodity alternatives, with that divergence manifesting in both procurement premiums paid by Quest Diagnostics and LabCorp and in the geographic clustering of polypropylene molding capacity along the US Gulf Coast and German petrochemical corridors.
Pricing Analysis
Service bundling separates manufacturers offering automation engineering support and just-in-time inventory programs from transactional suppliers. Pricing stratifies across premium, standard, and economy tiers based on ISO 6710 certification status and robotic handling compatibility. Cost compression in standard tubes intensifies because petroleum-derived polypropylene input costs fluctuate with crude oil volatility. Independent reference laboratories exhibit highest price sensitivity; multi-site laboratory operators extract volume-based concessions.
Supply Chain Analysis
Phlebotomy technician shortages in Greater Boston and Research Triangle Park clusters constrain sterile molding line throughput capacity. Polypropylene resin supply concentrates in the United States, Germany, and China; stainless steel cannulae fabrication rests on specialized German and Japanese metalworking equipment. Single-source vulnerability runs through Yangtze River Delta additive chemistry suppliers. Distribution runs through regional medical supply distributors serving independent laboratories outside metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile molding line capacity constraints prop pricing power for ISO 6710-certified manufacturers, as phlebotomy technician shortages and REACH compliance timelines limit rapid supply expansion.
For Market Incumbents: Anticipate nucleic acid stabilization tube commoditization by accelerating backward integration into polypropylene resin supply and securing multi-year automation engineering contracts with national laboratory networks before EU MDR conformity assessment timelines constrain competitor re-entry. For New Entrants and Emerging Players: Launch via distribution intermediaries targeting India's CDSCO-harmonized diagnostic infrastructure scaling through Mumbai and Bangalore public-private laboratory partnerships, with nucleic acid stabilization chemistries for decentralized clinical trials as the most penetrable white-space. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinationals seeking nucleic acid stabilization capabilities; long-term viability hinges on automation engineering talent retention. Watch phlebotomy technician training program graduation rates as inflection indicator for throughput-constrained diagnostic laboratory demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 6710 Certification Investment | Unlocks procurement contracts with Quest Diagnostics and LabCorp networks requiring sterile single-use compliance. |
| Automation Engineering Partnership | Enables robotic handling compatibility certification with high-throughput German and Chinese diagnostic laboratories. |
| REACH-Compliant Stopper Reformulation | Preserves European market access as ECHA scrutiny accelerates phthalate plasticizer restrictions. |
| Direct-to-Patient Collection Kit Development | Captures home-based therapeutic monitoring demand outside traditional hospital procurement channels. |
| CDSCO Registration Pathway Completion | Opens access to India's rapidly scaling diagnostic infrastructure through streamlined medical device registration. |
Research Methodology
Independent corroboration across FDA 510(k) filings, OSHA enforcement records, and EU MDR technical documentation databases underwrites the qualitative findings. Primary interviews with phlebotomy directors, GPO contracts managers, biomedical engineers, and diagnostic laboratory procurement leads combined with secondary validation from hospital procurement databases, GPO contract templates, and CMS Medicare reimbursement data. Bottom-up tube and needle volume estimates triangulated against top-down diagnostic procedure frequency models.
Comparable-period anchoring referenced pre-pandemic laboratory automation investment cycles and post-OSHA enforcement safety device adoption curves. Segmentation modeling spanned product type, end user, delivery mode, and application dimensions across the analysis window. CAGRs derived from installed base attrition rates and replacement demand curves, with nucleic acid stabilization tube penetration and capillary microsampling substitution risk as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for passive safety needle mechanisms would alter the outlook. Forecasts reflect assumptions regarding OSHA enforcement consistency, EU MDR assessment timeline normalization, and petroleum resin price stability. Material deviation in phlebotomy technician workforce expansion or REACH substance restriction acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
At-Home Hematology Testing Market
Hematology
Global Hematology Diagnostics Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Myelofibrosis Treatment Market
Hematology
Multiple Myeloma Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Patient Blood Management Market
Hematology
Hemocytometer Market
Hematology
Neutropenia Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market