
 Disposable Lancets Market | 2026-2036
Disposable Lancets Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Lancets Market Outlook
Chinese polymer suppliers is decoupling from Western needle assembly lines, forcing manufacturers to rebuild resin sourcing networks. BD leverages captive sterilization infrastructure across North American plants. Abbott sustains dominant channel presence in retail pharmacy distribution. Terumo Corporation differentiates through precision-ground tri-bevel geometries.
Disposable lancets are single-use sterile devices typically constructed from surgical-grade stainless steel or plastic with integrated spring mechanisms, designed to pierce skin at controlled depths for capillary blood sampling. Standard lancets occupy the volume base, while safety lancets command premium positioning through needle-retraction features that reduce sharps injuries. Adjustable lancets capture growing home-care preference as diabetic patients seek personalized depth control.
FDA 510(k) clearance requirements and EMA MDR compliance shape product development timelines and sterilization validation protocols. ISO 13485 quality management systems govern manufacturing consistency across export-oriented facilities. Stakeholders must monitor evolving needle-stick prevention mandates and polymer biocompatibility standards as regulators tighten post-market surveillance.
Market Dynamics
Home-based glucose monitoring is displacing clinical blood draws for routine diabetes management, compressing the addressable patient base for traditional phlebotomy services while expanding the installed base of personal lancet devices.
Growth Catalysts
- EMA MDR needle-stick prevention mandates:European safety lancet adoption accelerates as healthcare facilities retrofit sharps injury protocols, driving premium product substitution across hospital procurement.
- Polymer biocompatibility standards:ISO 10993 testing requirements for skin-contact materials are elevating barrier-to-entry for low-cost Asian manufacturers, consolidating compliant supplier networks.
- United States Medicare reimbursement expansion:Remote patient monitoring codes now cover continuous glucose monitor companion lancet supplies, extending device subsidy to previously uninsured populations.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel alloy surcharges fluctuate with Indonesian ore export quotas, compressing margin on standard lancet SKUs.
- Chinese polymer supply decoupling:Western needle assembly lines face resin sourcing reconstruction as domestic suppliers redirect volumes to local medical device clusters.
- Spring mechanism precision tolerances:Micro-coil manufacturing requires Swiss-style CNC equipment with 18-month lead times, constraining capacity expansion for adjustable-depth products.
Strategic Opportunities
- Germany's digital diabetes prevention programs:DMP reimbursement pathways for prediabetes screening create first-mover advantage in preventive lancet kit distribution.
- Retail pharmacy self-service kiosks:Automated blood pressure and glucose stations in CVS and Walgreens footprints bundle lancet dispensing with diagnostic workflows.
- FDA breakthrough device designation:Painless microneedle array technologies qualify for expedited review, compressing time-to-market for next-generation sampling platforms.
Industry Challenges
- Ethylene oxide sterilization validation timelines:ISO 11135 compliance documentation extends new product introduction cycles by 14-18 months.
- Legacy ERP integration with UDI traceability:Small-to-mid manufacturers struggle to retrofit SAP systems for FDA Unique Device Identifier serialization mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Lancets Market |
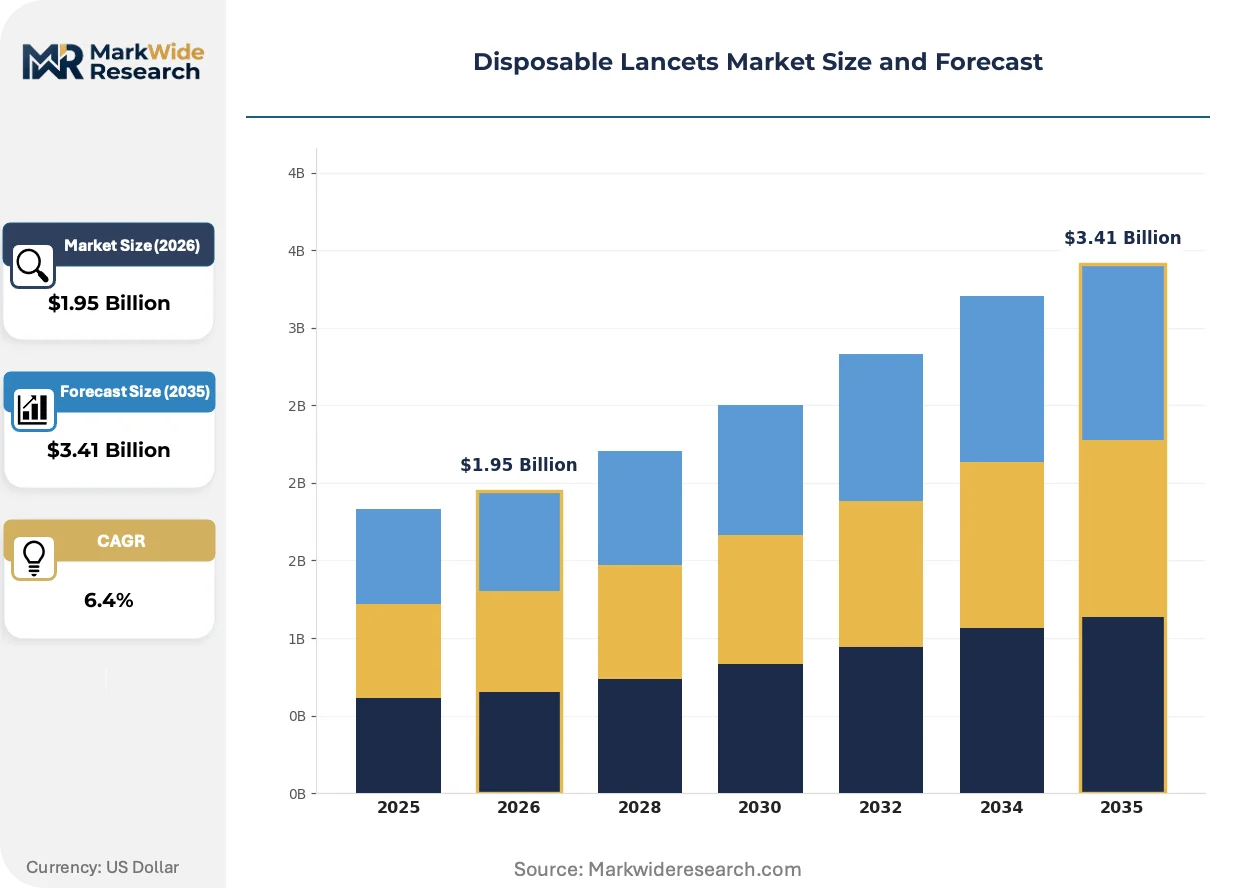
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lancets, Safety Lancets, Adjustable Lancets, Multi-Depth Lancets Application: Diabetes Management, Blood Glucose Testing, Lipid Profile Testing, Hemoglobin Testing End User: Home Care, Hospitals, Diagnostic Laboratories, Clinics Distribution Channel: Retail Pharmacy, Online Store, Hospital Supply, Wholesaler |
| Companies Covered | BD, Abbott, Bayer AG, LifeScan IP Holdings, B. Braun Melsungen AG, ARKRAY, Terumo Corporation, Owen Mumford, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Lancets Market Strategic Shifts
Disposable lancet design is bifurcating between ultra-low-cost commodity strips for emerging markets and precision-engineered safety mechanisms for regulated healthcare systems, with material science advances enabling both trajectories simultaneously.
Microneedle array technology is decentralizing blood sampling from centralized laboratories to point-of-care settings. Diabetic patients in Germany and the United States are adopting 0.5mm silicon microneedle patches at twice the rate of conventional spring-lancet devices. This shift is compressing the clinical trial infrastructure for glucose monitoring, as home-collected capillary samples replace venous draws for HbA1c correlation studies.
EMA MDR Class IIa reclassification of all blood sampling devices is extending notified body review timelines from 12 to 24 months. Sterilization validation protocols now require endotoxin testing at 0.5 EU per device, forcing manufacturers to relocate EtO facilities to EU-member states. Adjustable-depth lancets with integrated depth selectors face the steepest compliance burden, as moving parts trigger enhanced biocompatibility assessments.
Direct-to-consumer subscription models are fragmenting traditional wholesale pharmacy distribution. Patients in the United States now receive 90-day lancet supplies through Amazon Pharmacy and Ro Health platforms, bypassing durable medical equipment distributors. This channel shift is most pronounced among Type 1 diabetics under 35, where auto-replenishment algorithms linked to continuous glucose monitor data trigger lancet reshipments before inventory depletion.
Disposable Lancets Market Segmentation
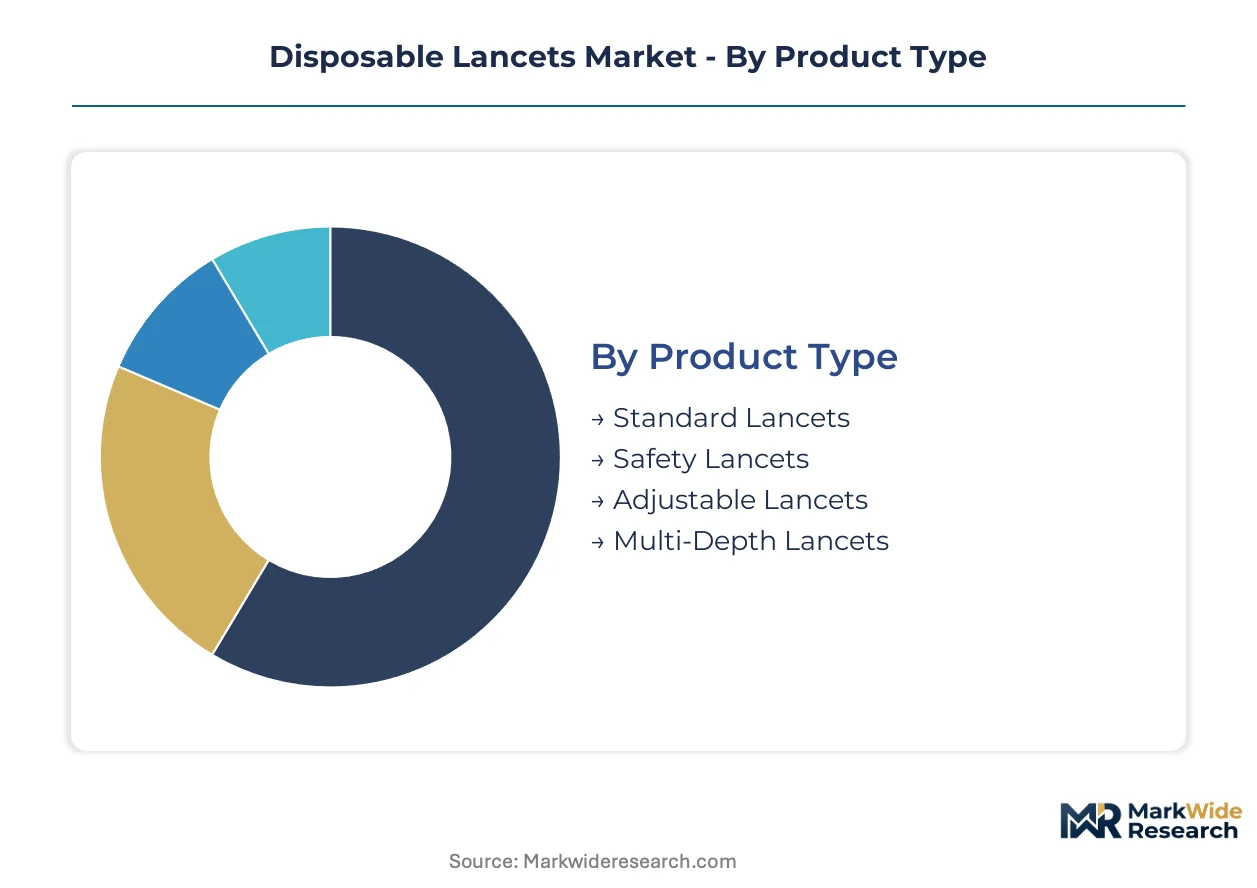
Disposable lancet procurement patterns diverge sharply between regulated healthcare systems and consumer-direct channels, with product specifications and pricing tiers calibrated to distinct sterilization, depth-control, and safety requirements across each segment.
Product Type:
Replacement cycles accelerate as safety mechanisms mature and adjustable-depth features migrate from premium to standard positioning.
- Standard Lancets:Single-use sterile devices with fixed-depth penetration, typically 28-30 gauge surgical-grade stainless steel construction. Demand concentrates in emerging market clinics and cost-sensitive hospital procurement in India, where bulk purchasing agreements prioritize unit economics over needle-retraction features.
- Safety Lancets:Spring-loaded mechanisms with automatic needle shielding post-activation, eliminating sharps injury risk. European hospital systems under EMA MDR mandates are retrofitting entire lancet inventories to safety variants, with Germany's university hospitals leading procurement volume for retractable needle designs.
- Adjustable Lancets:Integrated depth selectors enabling 0.8mm to 3.0mm penetration calibration for varying skin thickness.
- Multi-Depth Lancets:Preset depth tiers optimized for pediatric, adult, and calloused skin sampling without manual adjustment.
Volume placements concentrate in Standard Lancets; the faster expansion belongs to Safety Lancets.
Application:
Testing frequency and reimbursement pathways determine lancet consumption intensity across clinical versus home-use contexts.
- Diabetes Management:Daily capillary sampling for Type 1 and insulin-dependent Type 2 patients, generating the highest per-capita lancet consumption. United States Medicare remote patient monitoring codes now subsidize companion lancet supplies for continuous glucose monitor users, expanding the addressable patient base.
- Blood Glucose Testing:Episodic screening for prediabetes and gestational diabetes monitoring. German digital prevention programs (DMP) are embedding lancet kits into reimbursed screening workflows, creating bundled procurement channels distinct from retail pharmacy distribution.
- Lipid Profile Testing:Fingerstick cholesterol panels requiring deeper penetration than glucose sampling.
- Hemoglobin Testing:Point-of-care anemia screening with modified lancet geometry for larger blood volume collection.
Diabetes Management generates the highest unit velocity; Blood Glucose Testing is climbing the fastest as prediabetes screening scales.
End User:
Site-of-care economics and infection control protocols create divergent specification requirements across settings.
- Home Care:Patient-directed use with emphasis on pain minimization and disposal convenience. Direct-to-consumer subscription platforms in the United States—Amazon Pharmacy, Ro Health—now capture significant volume among Type 1 diabetics under 35, with auto-replenishment algorithms triggering reshipments before inventory depletion.
- Hospitals:Centralized procurement with mandatory safety-engineered device compliance. EMA MDR Class IIa reclassification is extending European hospital review timelines, consolidating supplier relationships toward manufacturers with captive EU-based sterilization infrastructure.
- Diagnostic Laboratories:High-throughput environments requiring standardized penetration depth for result consistency.
- Clinics:Mixed-use settings balancing cost constraints with occupational safety mandates.
Home Care leads absolute volume; Hospitals command the steepest expansion trajectory as safety mandates tighten.
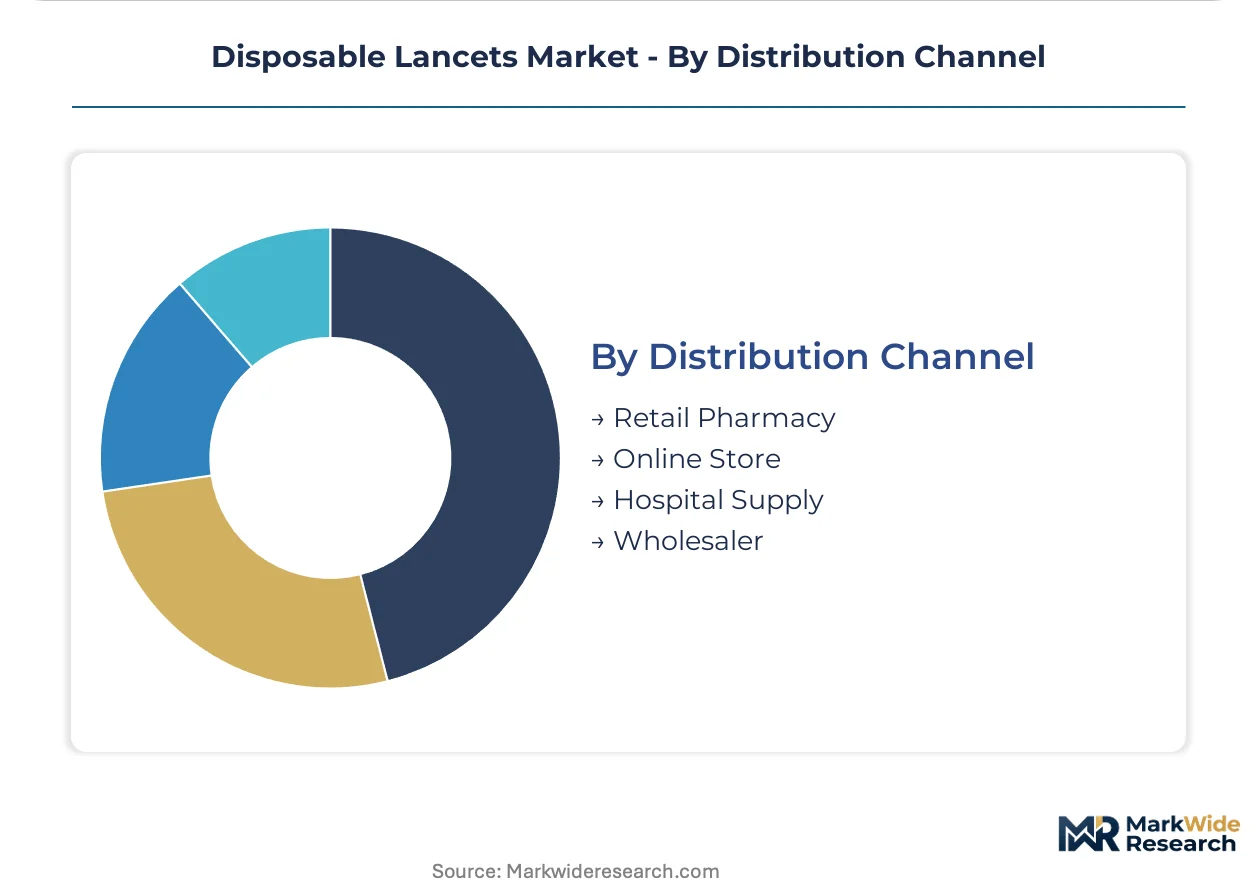
Distribution Channel:
Channel configuration determines margin capture and patient access speed across emergency replenishment versus planned procurement.
- Retail Pharmacy:Immediate-access replenishment with pharmacist counseling on proper technique. CVS and Walgreens self-service kiosk networks in the United States are bundling lancet dispensing with diagnostic workflows, capturing impulse purchases alongside blood pressure and glucose station usage.
- Online Store:Subscription-based auto-replenishment with price transparency and bulk discounts. Patient data integration with continuous glucose monitor outputs enables predictive reshipment timing, reducing stockout risk for intensive insulin users.
- Hospital Supply:Contracted group purchasing organization arrangements with sterilization documentation requirements.
- Wholesaler:Intermediate distribution to independent pharmacies and small clinic networks.
Retail Pharmacy maintains the deepest volume footprint; Online Store channels are gaining share fastest among digitally native patient cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel ore export quotas anchor surgical-grade stainless steel pricing volatility, directly compressing margin structures for standard lancet manufacturers across export-oriented production hubs.
United States
Medicare remote patient monitoring codes now subsidize companion lancet supplies for continuous glucose monitor users, expanding the addressable patient base. FDA 510(k) clearance requirements shape product development timelines and sterilization validation protocols. Retail pharmacy self-service kiosks at CVS and Walgreens bundle lancet dispensing with diagnostic workflows in urban clusters.
Germany
Digital diabetes prevention programs create first-mover advantage in preventive lancet kit distribution through reimbursed screening workflows. EMA MDR Class IIa reclassification extends notified body review timelines from 12 to 24 months for all blood sampling devices. University hospitals in Baden-Württemberg lead procurement volume for retractable needle safety designs.
China
Domestic polymer suppliers redirect volumes to local medical device clusters, forcing Western needle assembly lines to rebuild resin sourcing networks. NMPA biocompatibility standards for skin-contact materials elevate barrier-to-entry for low-cost manufacturers. Yangtze River Delta medical device parks concentrate adjustable-depth lancet production capacity.
Japan
PMDA quality management system inspections govern manufacturing consistency across export-oriented facilities serving Asia-Pacific markets. Precision-ground tri-bevel geometries differentiate premium product positioning in aging-population home-care segments. Osaka-Kobe industrial corridor hosts specialized micro-coil manufacturing equipment for spring mechanism components.
India
Bulk purchasing agreements in emerging market clinics prioritize unit economics over needle-retraction features for standard lancet procurement. CDSCO medical device rules tighten post-market surveillance for imported blood sampling devices. Gujarat pharmaceutical manufacturing zones attract contract sterilization infrastructure investments.
Disposable Lancets Market Competitive Environment
Global majors compete with regional champions across regulatory compliance capabilities and sterilization infrastructure ownership. The vendor base stratifies between consolidated safety-lancet specialists with captive EU-based EtO facilities and fragmented standard-lancet assemblers dependent on third-party sterilization. Three archetypes dominate: vertically integrated device-diagnostics conglomerates, precision-component specialists with Swiss-style CNC capabilities, and polymer-to-needle integrated manufacturers. Competitive moves concentrate on M&A for sterilization asset control and strategic partnerships for microneedle array technology licensing.
Within the integrated device-diagnostics tier, BD and Abbott exemplify archetypes of regulatory-scale operators. BD leverages captive sterilization infrastructure across North American plants to compress validation timelines. Abbott sustains dominant channel presence in retail pharmacy distribution networks. Terumo Corporation occupies a precision-specialist position, with tri-bevel geometry capabilities differentiating premium safety mechanism positioning.
| Leading Market Players |
|---|
| BD |
| Abbott |
| Bayer AG |
| LifeScan IP Holdings |
| B. Braun Melsungen AG |
| ARKRAY |
| Terumo Corporation |
| Owen Mumford |
| Nipro Corporation |
| Others |
Value Chain & Pricing Dynamics
Swiss-style CNC machinists concentrated in the Osaka-Kobe corridor command wage premiums that compress margin spreads between economy-grade fixed-depth lancets and premium adjustable-depth variants. Labor-cost differentials between Japanese micro-coil specialists and Chinese assembly operators create pricing-tier spreads that manufacturers cannot arbitrage without sacrificing spring mechanism precision.
Pricing Analysis
Warranty and sterilization documentation bundling separates hospital supply contracts from retail pharmacy transactions, with EMA MDR-compliant EtO validation certificates commanding premium positioning. Three-tier pricing structure across premium safety-lancet, standard fixed-depth, and economy bulk-procurement levels reflects certification grade and captive sterilization ownership. Cost compression in economy tiers intensifies because Indonesian nickel ore export quotas inflate surgical-grade stainless steel surcharges. Emerging market clinics in India exhibit highest price sensitivity; German university hospitals demonstrate lowest sensitivity due to mandated safety-engineered device compliance.
Supply Chain Analysis
Surgical-grade stainless steel supply rests on Indonesian nickel smelters, German specialty alloy producers, and Japanese precision metalwork facilities. Polymer resin feedstock draws from Yangtze River Delta petrochemical clusters, while Swiss-style CNC equipment for micro-coil manufacturing anchors in Japanese and German machine tool builders. Single-source vulnerability concentrates in EtO sterilization infrastructure, where EU MDR mandates force relocation to member-state facilities. Distribution runs through hospital group purchasing organizations in regulated markets and direct-to-consumer subscription platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable lancets market functions as a cost-of-compliance story, where EMA MDR Class IIa reclassification erects barrier-to-entry moats favoring manufacturers with captive EU-based sterilization infrastructure.
For Market Incumbents: Cement sterilization asset control through acquisition of EU-member-state EtO facilities before notified body review timelines extend further. Secure Swiss-style CNC equipment purchase agreements with 18-month lead times to constrain competitor capacity expansion for adjustable-depth products. Microneedle array substitution threatens spring-lancet incumbents; backward integration into silicon microneedle foundry partnerships defends positioning. For New Entrants and Emerging Players: Begin with prediabetes screening kit bundling in Germany's digital diabetes prevention programs, where reimbursement pathways create white-space access distinct from entrenched retail pharmacy channels. Target direct-to-consumer subscription platforms in the United States, where auto-replenishment algorithms linked to continuous glucose monitor data enable patient lock-in without distributor relationships. Go-to-market angle: painless microneedle array technologies qualifying for FDA breakthrough device designation. For Investors and Strategic Acquirers: Re-rating potential sits with precision-component specialists possessing Swiss-style CNC capabilities given adjustable-depth lancet demand acceleration in home-care segments. Long-term viability over the next decade favors manufacturers with polymer-to-needle integration and captive sterilization infrastructure. Acquisition target archetype: mid-cap safety-lancet specialists with EMA MDR compliance documentation and EU-based EtO facilities. Signal to watch: FDA 510(k) clearance timelines for microneedle array platforms as inflection indicator for spring-lancet displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR Class IIa reclassification extends notified body review timelines to 24 months for blood sampling devices. |
| Hospital System Partnership | German university hospitals in Baden-Württemberg lead procurement volume for retractable needle safety designs. |
| Backward Integration | Captive EtO sterilization infrastructure in EU member states compresses validation timelines against third-party dependent competitors. |
| Software Companion Development | Auto-replenishment algorithms linked to continuous glucose monitor data trigger lancet reshipments before inventory depletion. |
| Reimbursement Strategy | United States Medicare remote patient monitoring codes now subsidize companion lancet supplies for continuous glucose monitor users. |
Study Parameters
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at sterilization facilities underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract repositories, and CMS Medicare reimbursement code updates. Bottom-up patient population modeling triangulates against top-down manufacturer capacity assessments across the analysis window.
Rate-of-change decomposition separates volume growth from pricing trajectory across product type, application, end user, and distribution channel dimensions. CAGRs derive from patient population epidemiology, testing frequency assumptions, and reimbursement pathway expansion. Forecast inputs incorporate continuous glucose monitor adoption curves and microneedle array technology maturation timelines without specifying commercialization dates.
Underlying measurement precision varies by segment; diabetes management and safety lancet categories carry tighter precision than emerging market standard lancet procurement. Forecasts reflect documented assumptions regarding regulatory timeline stability and raw material cost trajectories. Supply chain disruption from Indonesian export policy shifts, polymer sourcing network reconstruction, and EtO facility relocation mandates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Smart Mask Market
Medical Devices
Digital Reading Micropipettes Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
3D Printed Implants Market
Medical Devices
Cheek Implants Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Annuloplasty System Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Asthma Device Market
Medical Devices
Prefilled Glass Syringes Market