
 Blood Collection Devices Market | 2026-2036
Blood Collection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Collection Devices Market Intelligence
Hospital procurement consortia is reconfiguring how blood collection devices reach end users in North America and Western Europe. Becton, Dickinson and Company leverages its direct-to-laboratory distribution network to sustain volume commitments across integrated health systems. Greiner Bio-One International GmbH anchors European supply through specialized vacuum tube production facilities in Austria and Germany. Terumo BCT differentiates in therapeutic apheresis segments where product performance standards exceed routine diagnostic thresholds.
Blood collection devices comprise engineered systems for the extraction, containment, and transport of human blood specimens, with vacuum tubes typically maintaining negative pressure between 5.5 and 10 inches of mercury to ensure precise fill volumes. These devices serve diagnostic laboratories, blood banks, and clinical research sites where specimen integrity directly determines test accuracy and patient safety. Vacuum blood collection tubes command the largest product share due to standardization in high-throughput laboratory environments, while lancets represent the fastest-expanding category as point-of-care glucose monitoring and capillary testing decentralize beyond traditional phlebotomy settings. Plastic materials dominate tube construction for shatter resistance and transport safety, though glass persists in specialized coagulation and chemistry panels where surface inertness affects analyte stability.
The FDA enforces sterility and biocompatibility standards under 21 CFR 820 quality system regulations, while the EU Medical Device Regulation requires notified body certification for blood collection needles and tubes sold in European markets. ISO 6710 specifies capillary tube dimensions and heparin coating requirements that manufacturers must meet for international market access. Stakeholders must monitor evolving FDA guidance on closed-system transfer devices and the EU's phased reduction of ethylene oxide sterilization capacity, as these regulatory shifts will reshape manufacturing location decisions and compliance cost structures.
Market Dynamics
Centralized laboratory networks in Germany are consolidating venipuncture infrastructure, compressing procurement timelines and favoring suppliers with automated phlebotomy integration capabilities. This structural concentration is redistributing volume commitments toward integrated health systems capable of standardizing collection protocols across multi-site operations.
Growth Catalysts
- EU Medical Device Regulation:The MDR's stricter notified body certification requirements for blood collection needles and tubes is filtering out marginal manufacturers, concentrating demand among compliant suppliers with established European production footprints.
- Diagnostic laboratories:Automated phlebotomy workflows across North America and Europe are replacing manual collection methods, driving replacement demand for vacuum tube systems compatible with robotic handling equipment.
- Capillary testing decentralization:Point-of-care glucose monitoring and micro-sampling applications are expanding lancet utilization beyond traditional hospital settings into retail clinics and home diagnostics.
Market Restraints
- Ethylene oxide sterilization capacity:The EU's phased reduction of EtO sterilization facilities is constraining throughput for vacuum tube manufacturers dependent on this process for terminal sterilization.
- Glass tube supply concentration:Specialized borosilicate glass production for coagulation and chemistry panels concentrates among limited European suppliers, exposing the market to input bottlenecks.
- Surface chemistry limitations:Plastic tube materials exhibit variable analyte adsorption characteristics that compromise specimen integrity for certain specialized panels, preserving glass dependency despite shatter risks.
Strategic Opportunities
- Closed-system transfer devices:FDA guidance evolution on contamination prevention during specimen handling is creating compliance-driven demand for integrated needle-tube systems with engineered transfer mechanisms.
- Therapeutic apheresis expansion:Performance standards exceeding routine diagnostic thresholds in cell collection and plasma exchange applications command premium positioning for specialized device configurations.
- Micro-sampling technologies:Convergence of capillary collection with dried blood spot analytics is opening specimen collection to decentralized clinical trial sites and remote patient monitoring programs.
Industry Challenges
- Phlebotomy technician certification:Labor shortages in certified specimen collection personnel are extending implementation timelines for automated workflow deployments in integrated health systems.
- Legacy LIS integration:Compatibility requirements with existing laboratory information systems are complicating vendor transitions and prolonging procurement cycles for next-generation collection devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Collection Devices Market |
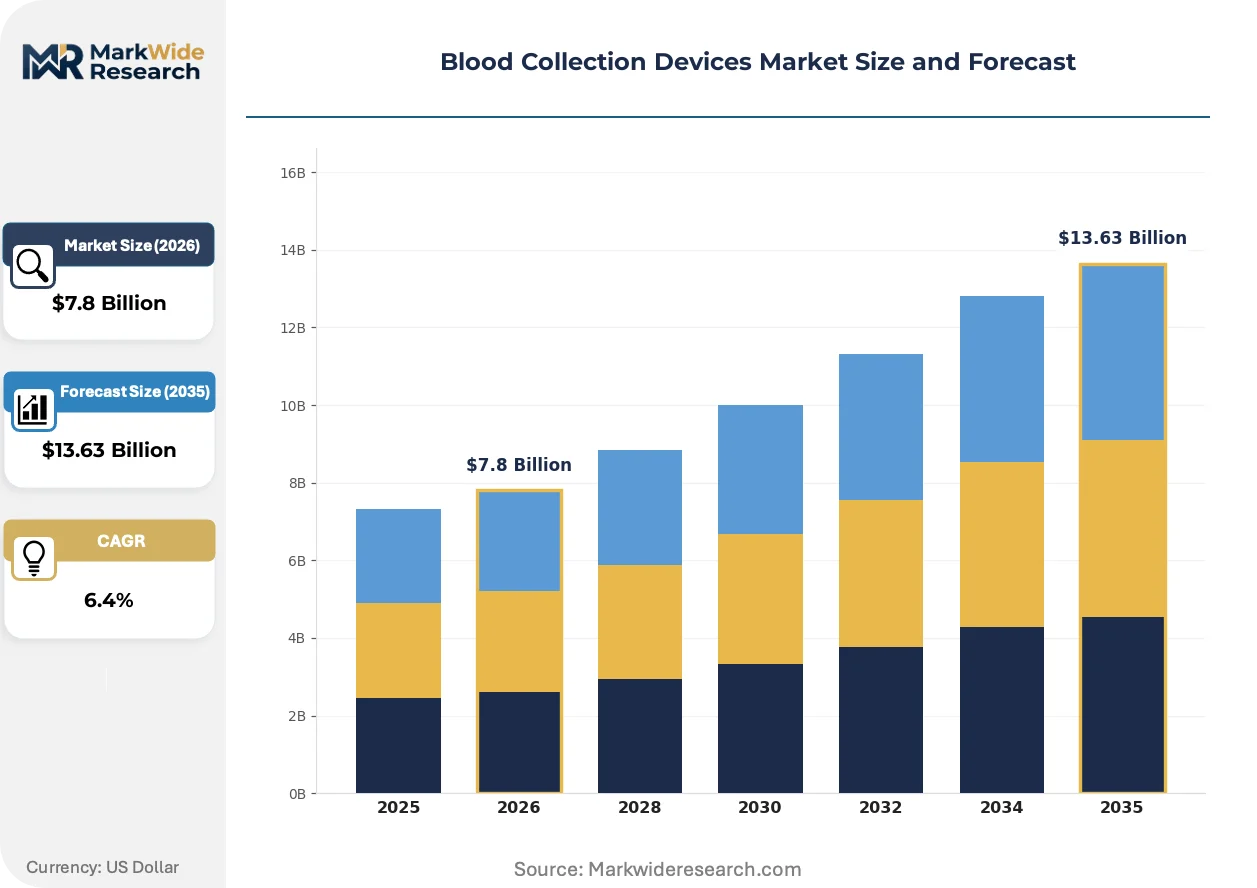
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Blood Collection Tubes, Needle Sets, Lancets, Capillary Tubes, Syringes Material: Plastic, Stainless Steel, Silicone, Rubber, Glass Application: Diagnostic Testing, Therapeutic Drug Monitoring, Laboratory Analysis, Blood Donation, Clinical Research End User: Diagnostic Laboratories, Blood Banks, Academic Institutions, Pharmaceutical Companies, Research Centers |
| Companies Covered | Greiner Bio-One International GmbH, Haemonetics Corporation, Becton, Dickinson and Company, Nipro Medical Corporation, SARSTEDT AG & Co. KG, Terumo BCT, Cardinal Health, Grifols, S.A., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Collection Devices Market Strategic Shifts & Innovations
Digital specimen tracking and smart packaging technologies are transforming how blood collection devices integrate into laboratory workflow automation. These innovations compress identification error rates while enabling real-time chain-of-custody documentation.
Micro-sampling capillary technologies are virtualizing specimen collection by enabling volumetrically precise dried blood spot formation from finger-stick samples. Clinical research organizations are adopting these systems for decentralized trial participation, eliminating phlebotomy center visits. The technology is virtualizing geographic constraints on specimen access, allowing remote patient enrollment without compromising analyte stability.
FDA guidance evolution on closed-system transfer devices is mandating engineered barriers against environmental contamination during blood culture inoculation. Manufacturers are redesigning needle-tube interfaces to incorporate sealed transfer chambers. Blood bank operations face the steepest compliance timeline, with accreditation surveys already scrutinizing open-system handling protocols.
Hospital procurement consortia are consolidating supplier relationships through multi-year volume commitments tied to standardization mandates. Integrated delivery networks in the United States are displacing fragmented purchasing across individual facilities with centralized contracting offices. Germany exhibits the most advanced consolidation, where regional laboratory associations negotiate collective terms for venipuncture infrastructure upgrades.
Blood Collection Devices Market Segmentation
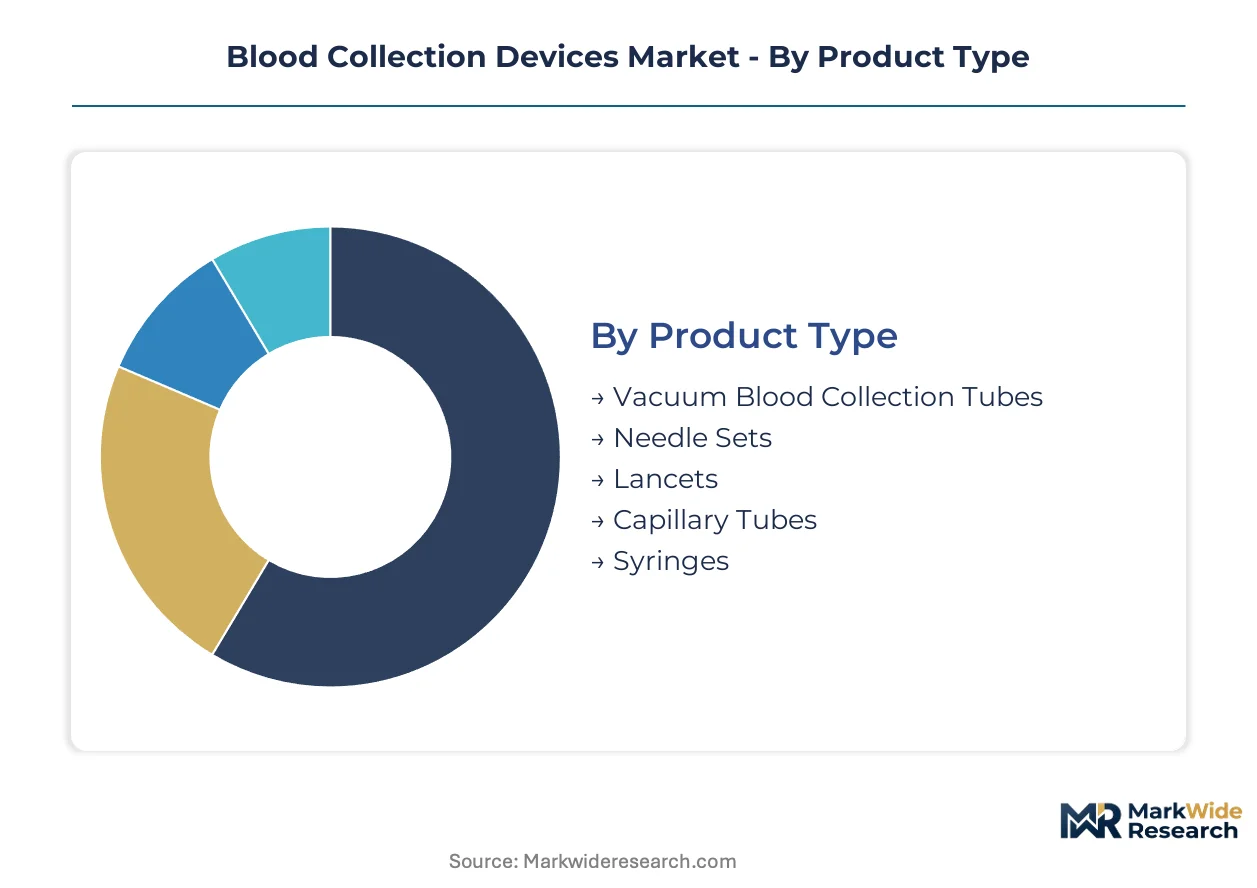
Device configuration and material selection in blood collection systems directly determine specimen integrity, handling automation compatibility, and regulatory compliance pathways. Segmentation reveals where procurement concentration and technology substitution are restructuring supplier relationships across diagnostic and therapeutic use cases.
Product Type:
Volume concentration and automation readiness separate high-throughput laboratory staples from emerging point-of-care formats.
- Vacuum Blood Collection Tubes:These devices maintain calibrated negative pressure between 5.5 and 10 inches of mercury to ensure precise fill volumes across coagulation, chemistry, and hematology panels. Demand concentrates in Germany's centralized laboratory networks where automated phlebotomy workflows require standardized tube dimensions and barcoded identification systems. The EU MDR's sterility certification requirements are filtering supplier资格 toward manufacturers with validated vacuum retention testing protocols.
- Lancets:Spring-loaded or pressure-activated devices for capillary blood access are climbing the fastest as point-of-care glucose monitoring and micro-sampling applications decentralize beyond traditional phlebotomy settings into retail clinics and home diagnostics. Surface geometry and blade depth calibration determine patient pain scores and sample adequacy for dried blood spot formation.
- Needle Sets:Multi-sample needles and safety-engineered holders interface with vacuum tubes for venipuncture; configurations vary by gauge, length, and activation mechanism for sharps injury prevention.
- Capillary Tubes:Heparin-coated or plain glass or plastic tubes for micro-volume collection; ISO 6710 dimensional standards govern international market access for hematocrit and rapid testing applications.
- Syringes:Manual aspiration systems persist in specialized coagulation studies and difficult-access patients where vacuum pressure may compromise specimen integrity or patient safety.
Vacuum tubes hold installed capacity. Lancets are rotating up the share rankings.
Material:
Surface chemistry and mechanical properties dictate analyte stability, transport safety, and sterilization pathway selection.
- Plastic:Polypropylene and polyethylene terephthalate formulations dominate routine chemistry and hematology panels where shatter resistance reduces biohazard exposure during transport. Plastic exhibits variable protein and drug adsorption characteristics that compromise specialized therapeutic drug monitoring panels, preserving glass dependency despite handling risks.
- Glass:Borosilicate construction maintains surface inertness for coagulation studies and certain chemistry analytes where plastic adsorption would distort clinical results; supply concentrates among limited European manufacturers.
- Stainless Steel:Hypodermic needle cannulas and lancet blades require medical-grade alloys with precise bevel grinding for penetration force consistency.
- Silicone:Needle lubrication coatings reduce patient discomfort and tissue trauma during venipuncture; biocompatibility testing requirements have tightened under FDA guidance.
- Rubber:Tube stoppers and septum materials must maintain vacuum integrity through shelf life while permitting clean needle penetration without coring.
Plastic commands routine volume. Glass defends specialized positioning.
Application:
Performance thresholds and regulatory scrutiny intensity vary across diagnostic, therapeutic, and research use cases.
- Diagnostic Testing:Routine chemistry, hematology, and immunoassay panels drive the highest specimen throughput in hospital and reference laboratory settings. FDA 21 CFR 820 quality system regulations enforce sterility and biocompatibility benchmarks that shape manufacturer compliance investments.
- Therapeutic Drug Monitoring:Precision requirements for immunosuppressant and anti-epileptic drug levels demand specialized tube additives and handling protocols; Terumo BCT and comparable suppliers differentiate through performance standards exceeding routine diagnostic thresholds.
- Laboratory Analysis:Research-grade specimen handling for method development and quality control; less stringent patient safety regulations but demanding precision specifications.
- Blood Donation:Whole blood and apheresis collection systems face blood bank accreditation scrutiny on open-system handling protocols; closed-system transfer device guidance is mandating engineered contamination barriers.
- Clinical Research:Micro-sampling and decentralized trial participation are virtualizing geographic constraints on specimen access; dried blood spot technologies enable remote patient enrollment without phlebotomy center visits.
Diagnostic testing anchors procurement volume. Clinical research is expanding most quickly.
End User:
Procurement scale and standardization mandate intensity determine supplier relationship structures.
- Diagnostic Laboratories:High-throughput integrated health systems in the United States and regional laboratory associations in Germany negotiate multi-year volume commitments tied to automated phlebotomy infrastructure standardization. Becton, Dickinson and Company leverages direct-to-laboratory distribution networks to sustain these consolidated relationships.
- Blood Banks:Therapeutic apheresis and whole blood collection operations face the steepest FDA compliance timeline on closed-system transfer devices; accreditation surveys already scrutinize open-system handling protocols.
- Academic Institutions:Research specimen handling with variable standardization; fragmented purchasing across individual investigators.
- Pharmaceutical Companies:Clinical trial supply chains and companion diagnostic development; micro-sampling adoption is accelerating for decentralized trial designs.
- Research Centers:Specialized coagulation and chemistry method development; small-batch procurement with premium pricing tolerance for custom configurations.
Diagnostic laboratories concentrate procurement leverage. Blood banks face compliance-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European laboratory supply chains, connecting Central European diagnostic networks to vacuum tube manufacturers in Austria and Lower Saxony.
United States
Integrated delivery networks in Texas and California are consolidating procurement through centralized contracting offices that demand automated phlebotomy compatibility. FDA's updated 21 CFR 820 guidance on sterility benchmarks is compressing supplier qualification timelines. The Research Triangle in North Carolina anchors clinical trial micro-sampling adoption for decentralized patient enrollment.
Germany
Regional laboratory associations in Bavaria and North Rhine-Westphalia negotiate collective terms for venipuncture infrastructure standardization. The EU Medical Device Regulation's notified body certification requirements are filtering supplier资格 toward manufacturers with validated vacuum retention protocols. Manufacturing clusters in Lower Saxony concentrate specialized borosilicate glass production for coagulation panels.
China
NMPA's tightened biocompatibility testing requirements for blood collection needles are extending product registration timelines for domestic and foreign manufacturers. The Yangtze River Delta hosts vacuum tube production facilities serving hospital procurement consortia across East Asia. Shanghai's clinical research organizations are piloting dried blood spot technologies for remote patient monitoring.
Japan
PMDA's quality system regulations enforce surface chemistry standards that preserve glass dependency for specialized therapeutic drug monitoring. The Kanto region around Tokyo concentrates diagnostic laboratory networks upgrading to automated specimen handling. Osaka-based blood banks face accelerated compliance timelines on closed-system transfer device guidance.
India
CDSCO's medical device rules are harmonizing with ISO 6710 standards for capillary tube dimensions and heparin coating requirements. Maharashtra's diagnostic laboratory chains are expanding point-of-care glucose monitoring networks into tier-2 cities. Bangalore's clinical research sites adopt micro-sampling for decentralized trial participation.
Blood Collection Devices Market Key Industry Players
On the supply side, the industry is consolidating around manufacturers with validated European production footprints and automated phlebotomy integration capabilities. Tiered supplier structures separate integrated health system contractors from regional distributors serving fragmented clinic networks. Three archetypes dominate: diversified medical technology conglomerates, specialized vacuum tube manufacturers, and therapeutic apheresis equipment specialists. Competitive moves concentrate on M&A for manufacturing capacity and strategic partnerships for automated workflow integration.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Cardinal Health exemplify scale-driven positioning through direct-to-laboratory distribution networks. Greiner Bio-One International GmbH represents the specialized vacuum tube manufacturing archetype with Austrian and German production assets. Terumo BCT occupies the therapeutic apheresis specialist tier where performance standards exceed routine diagnostic thresholds.
| Leading Market Players |
|---|
| Greiner Bio-One International GmbH |
| Haemonetics Corporation |
| Becton, Dickinson and Company |
| Nipro Medical Corporation |
| SARSTEDT AG & Co. KG |
| Terumo BCT |
| Cardinal Health |
| Grifols, S.A. |
| Fresenius Kabi AG |
| Others |
Cost & Logistics Intelligence
Specialized borosilicate glass production for coagulation panels concentrates among limited European suppliers in Lower Saxony and Austria, anchoring premium margin pools with manufacturers serving therapeutic drug monitoring and specialized chemistry applications where plastic tube adsorption would compromise analyte stability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared closed-system transfer devices from conventional vacuum tube configurations and unbranded commodity lancets. Price differentiation hinges on EU MDR certification status and automated phlebotomy compatibility, with diagnostic laboratory consortia extracting volume discounts that compress margins for mid-tier suppliers. Pricing pressure stems from ethylene oxide sterilization capacity constraints in Europe, which is forcing manufacturers to absorb higher compliance costs or surrender share to competitors with validated gamma irradiation protocols. Blood banks and therapeutic apheresis operators exhibit the lowest price sensitivity, while retail clinic networks and home diagnostic channels drive aggressive procurement terms.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for plastic tube manufacturers dependent on polypropylene resin flows. Manufacturing gravity centers on Germany, Austria, and China, with vacuum retention testing protocols and automated assembly equipment drawing from specialized precision engineering clusters in Switzerland and Japan. Raw material dependencies include medical-grade stainless steel for needle cannulas, silicone lubrication coatings, and rubber stopper formulations that maintain vacuum integrity through shelf life. Single-source vulnerability persists in heparin coating chemistry for capillary tubes. Distribution runs through direct-to-laboratory networks for integrated health systems and regional medical distributors serving fragmented clinic infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-sampling technology adoption in decentralized clinical trials represents an early-cycle expansion opportunity, with dried blood spot platforms virtualizing geographic constraints on specimen access and opening remote patient enrollment pathways that bypass traditional phlebotomy infrastructure.
For Market Incumbents: Build regulatory certification moats by accelerating EU MDR notified body approvals and FDA closed-system transfer device compliance ahead of accreditation survey timelines. Deepen backward integration into specialized borosilicate glass production to defend against input bottlenecks from limited European suppliers. Channel control through direct-to-laboratory distribution networks remains the critical lever for sustaining volume commitments against emerging automated phlebotomy integrators. For New Entrants and Emerging Players: Establish a beachhead in micro-sampling capillary technologies for clinical research organizations piloting decentralized trial participation, where incumbent footprint remains underdeveloped. The most penetrable white space sits in home diagnostic lancet configurations for remote patient monitoring programs, with go-to-market traction achievable through partnerships with digital health platforms managing chronic disease populations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized vacuum tube manufacturers lacking automated phlebotomy integration capabilities. Long-term viability over a multi-year horizon favors targets with validated European production footprints and MDR certification pipelines. The signal to watch is consolidation velocity among regional laboratory associations in Germany, where collective procurement terms will determine which suppliers capture infrastructure upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body approval timelines filter supplier资格 toward compliant manufacturers with established European production assets. |
| Automated Phlebotomy Integration | Robotic handling compatibility secures multi-year volume commitments from integrated health systems standardizing collection protocols. |
| Closed-System Transfer Device Development | FDA guidance on contamination prevention mandates engineered barriers that command premium positioning in blood bank operations. |
| Micro-Sampling Platform Launch | Dried blood spot technologies enable clinical research organizations to enroll remote patients without phlebotomy center visits. |
| Backward Integration into Glass Production | Captive supply of specialized borosilicate glass defends against input concentration risk among limited European manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs leads at vacuum tube manufacturers, and refined through secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and ISO 6710 compliance documentation. Bottom-up demand modeling across diagnostic laboratory networks and top-down supply assessment from manufacturing capacity disclosures were triangulated to converge on volume and value estimates.
Demand-supply-balance framing anchored the analytical framework, with segmentation across product type, material composition, application specificity, and end-user procurement scale modeled throughout the forecast period. CAGRs were derived from installed base replacement cycles, automation penetration curves, and regulatory compliance-driven upgrade timelines. Industry-specific forecast inputs included ethylene oxide sterilization capacity constraints in Europe and the phased implementation of FDA closed-system transfer device guidance.
Stress conditions across ethylene oxide sterilization throughput, borosilicate glass supply availability, and certified phlebotomy technician labor pools were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and automation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Insulin Pumps Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
US Contact Lenses Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Laryngoscopes Market