
 Blood Market | 2026-2036
Blood Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Market Analysis
REACH compliance is pivoting the European plasma derivatives sector toward higher purity thresholds and traceable cold-chain documentation. CSL Limited leverages its vertically integrated plasma collection network across multiple continents to secure raw material access. Grifols S.A. sustains one of the world's largest donor center footprints, anchoring its fractionation capacity. Takeda Pharmaceutical Company Limited competes through specialized immunoglobulin portfolios and rare disease focus.
Blood comprises a complex suspension of erythrocytes, leukocytes, platelets, and plasma proteins circulating at approximately 7.35-7.45 pH, with plasma alone containing over 700 proteins including albumin, immunoglobulins, and clotting factors essential for oxygen transport, immune defense, and hemostasis. Plasma fractionation yields therapeutic proteins for hemophilia, immunodeficiency, and critical care applications across hospital and home settings. Whole blood and red blood cell concentrates dominate transfusion volumes in emergency and surgical therapy areas, though plasma-derived biologics command disproportionate margin pools due to manufacturing complexity and orphan drug designations. Platelet segments show structural growth tied to oncology patient volumes and prophylactic transfusion protocols.
The FDA enforces Current Good Manufacturing Practice for blood and plasma establishments, while the EMA's MDR and F-Gas Regulation shape cold-chain equipment standards and device traceability across European distribution channels. China's NMPA and GB standards govern domestic plasma collection quotas and fractionation facility licensing, constraining import dependency. Stakeholders must monitor regulatory divergence between plasma source qualification rules and fractionation technology transfer requirements as biologic substitution pressures intensify.
Market Dynamics
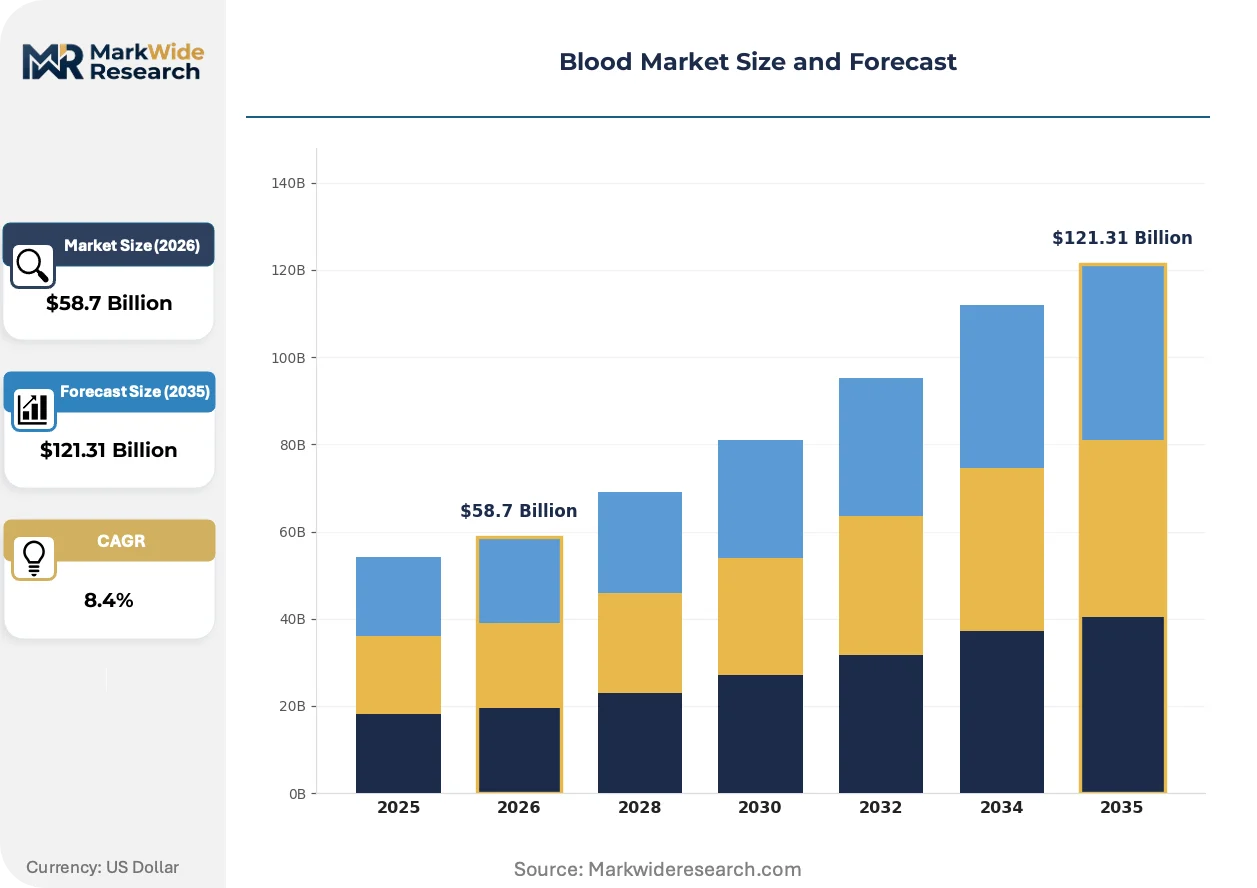
Plasma fractionation capacity constraints are tightening supply elasticity across therapeutic protein markets, while hospital transfusion volumes rebound from deferred surgical procedures accumulated during the pandemic period. The FDA's donor deferral policy revisions and China's NMPA plasma collection quotas are simultaneously reshaping raw material access patterns.
Growth Catalysts
- Oncology patient volumes:Rising cancer incidence rates across aging populations are expanding prophylactic platelet transfusion protocols in tertiary care centers.
- REACH compliance thresholds:European cold-chain documentation mandates are accelerating investment in traceable plasma logistics infrastructure.
- Immunoglobulin portfolio expansion:Specialized antibody therapies for rare immunodeficiency disorders are capturing premium reimbursement positions in hospital formularies.
Market Restraints
- Donor pool limitations:FDA plasma collection frequency restrictions and health-based deferral criteria constrain source plasma availability in the United States.
- Fractionation facility concentration:Geographic clustering of licensed plasma processing plants creates supply vulnerability during regional disruptions.
- Recombinant substitution:Engineered clotting factors for hemophilia A and B are displacing plasma-derived alternatives in developed markets.
Strategic Opportunities
- Home infusion protocols:Subcutaneous immunoglobulin administration is shifting treatment delivery from hospital infusion centers to patient residences.
- China's hospital network:Domestic plasma fractionation buildout is reducing import dependency for albumin and intravenous immunoglobulin.
- Pathogen reduction technologies:INTERCEPT and Mirasol systems are opening market access in jurisdictions with stringent transfusion safety mandates.
Industry Challenges
- Specialized technician scarcity:Qualified immunohematology technologists and fractionation process engineers command premium compensation in tight labor markets.
- Legacy blood bank information systems:Hospital transfusion service software requires costly interoperability upgrades to meet ISBT 128 labeling and traceability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Blood, Plasma, Red Blood Cells, Platelets Therapy Area: Transfusion, Surgical Procedures, Hemophilia, Anemia End User: Hospitals, Blood Banks, Clinics, Research Institutions Distribution Channel: Direct Sales, Online Platforms, Wholesalers, Third-Party Distributors |
| Companies Covered | CSL Limited, Grifols S.A., Takeda Pharmaceutical Company Limited, Octapharma AG, Baxter International Inc., Bio-Rad Laboratories, Haemonetics Corporation, Terumo Corporation, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Market Emerging Trajectories
Automated collection platforms and extended plasma storage technologies are compressing donor center operating costs while expanding therapeutic protein yields per liter of source material processed.
Automated plasmapheresis systems with higher frequency collection protocols are rewriting donor throughput economics at CSL and Grifols collection networks. These platforms extract larger plasma volumes per session while reducing citrate reaction rates. The technology is compressing per-donor collection costs and enabling geographic expansion into secondary population centers previously deemed uneconomical.
EMA's Medical Device Regulation and F-Gas Regulation are mandating refrigerant transitions and enhanced device traceability across European cold-chain infrastructure. Plasma derivative distributors must retrofit transport containers and storage facilities to comply with phased hydrofluorocarbon phase-down schedules. Fractionation facilities in Germany and Spain are absorbing compliance costs that filter into regional pricing structures.
Hospital blood management programs are consolidating vendor relationships and negotiating multi-year supply agreements with integrated service components. Transfusion committees in the United States are unbundling traditional supplier contracts to separate product procurement from therapeutic monitoring and inventory optimization services. This restructuring is most visible in academic medical centers pursuing value-based care contracts with commercial payers.
Blood Market Segmentation
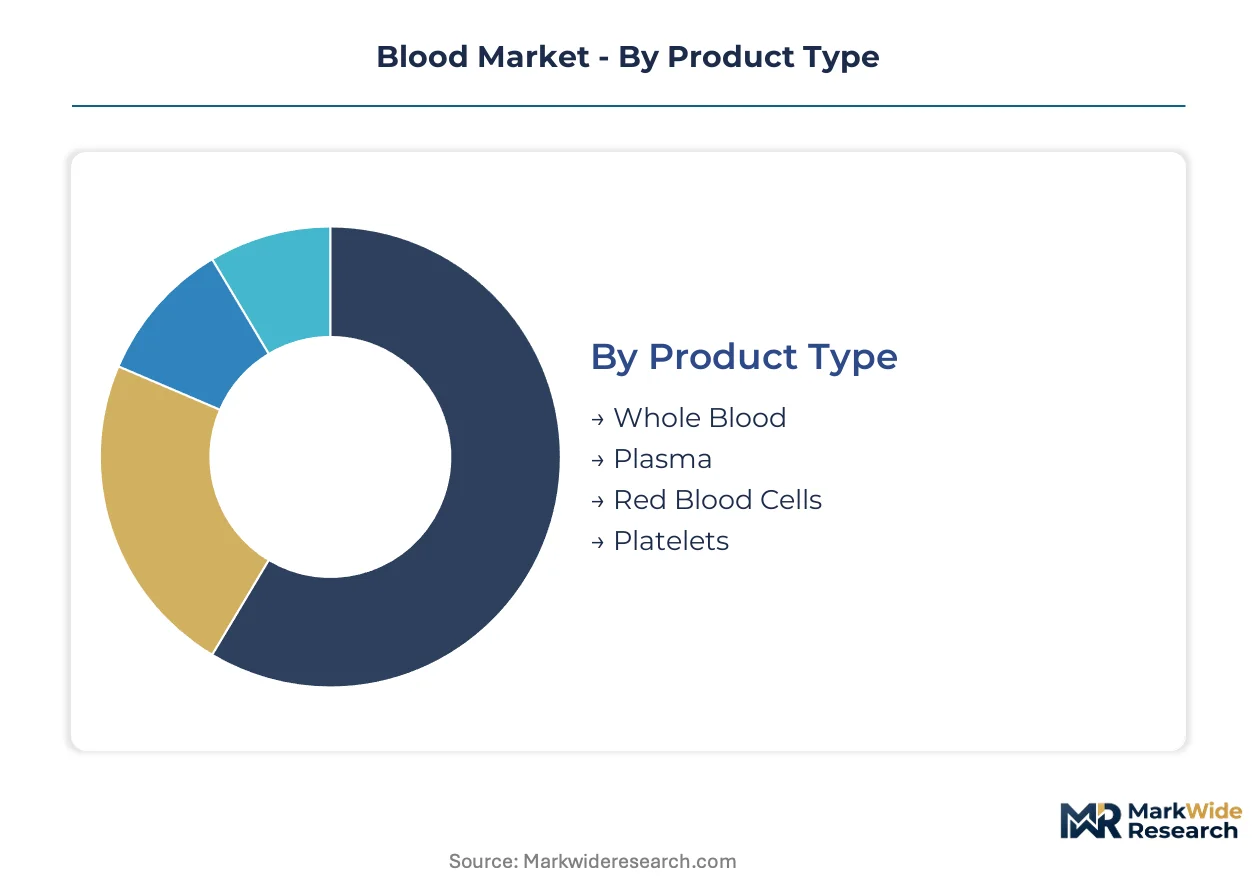
Product heterogeneity in blood markets creates distinct margin profiles across collection, processing, and therapeutic application stages. Segmentation reveals where volume concentration diverges from value capture.
Product Type:
Plasma commands premium pricing per liter while red blood cells dominate transfusion volumes in hospital settings.
- Whole Blood:Unfractionated blood containing all cellular and plasma components, collected for immediate transfusion in trauma and massive hemorrhage protocols. Demand concentrates in US emergency departments and military medical facilities, constrained by short shelf life and type-specific matching requirements.
- Plasma:Liquid component comprising water, electrolytes, proteins, and clotting factors, extracted through apheresis for fractionation into albumin, immunoglobulins, and factor concentrates. US collection centers and Chinese fractionation facilities anchor supply, with protein yield economics driving geographic expansion of donor networks.
- Red Blood Cells:Oxygen-carrying erythrocyte concentrates depleted of plasma and leukocytes, standardized for hemoglobin content and hematocrit. Surgical backlogs in German and Spanish hospitals are expanding prophylactic transfusion protocols.
- Platelets:Thrombocyte suspensions for hemostasis, stored at controlled temperatures with limited viability windows. Oncology centers in Japan and South Korea are scaling prophylactic use amid rising cancer patient volumes.
Mature deployment sits with Red Blood Cells. Newer deployment is concentrated in Plasma fractionation derivatives.
Therapy Area:
Application intensity varies from acute episodic use to chronic lifelong therapy, reshaping procurement and inventory strategies.
- Transfusion:Acute blood product administration for hemorrhage, surgical support, and critical care stabilization. Tertiary hospitals in Texas, California, and New York drive volume through trauma center designations and cardiovascular surgery programs.
- Surgical Procedures:Planned transfusion support for cardiac, orthopedic, and transplant operations. Elective procedure backlogs accumulated during pandemic periods are clearing across NHS England facilities and French university hospitals.
- Hemophilia:Clotting factor replacement for inherited coagulation disorders, delivered through prophylactic or on-demand protocols. Plasma-derived and recombinant factor concentrates compete for patient share in US and European hemophilia treatment centers.
- Anemia:Red blood cell support for chronic disease, chemotherapy, and renal failure patients. Dialysis chains and oncology practices in Italy and Poland are expanding transfusion-dependent patient management programs.
Acute therapy models dominate Transfusion and Surgical Procedures. Chronic therapy infrastructure is expanding fastest in Hemophilia.
End User:
Facility type determines regulatory oversight intensity, inventory holding requirements, and supplier relationship structures.
- Hospitals:Acute care institutions with transfusion services, blood banks, and specialized coagulation laboratories. US academic medical centers are unbundling supplier contracts to separate product procurement from therapeutic monitoring services.
- Blood Banks:Collection, processing, and distribution facilities operating under FDA or EMA licensing frameworks. German and Austrian plasma collection networks are consolidating under fractionator-affiliated ownership structures.
- Clinics:Outpatient settings for infusion therapy, including hemophilia treatment centers and subcutaneous immunoglobulin administration. Home infusion protocols are shifting patient volume from hospital-based to clinic and residential settings.
- Research Institutions:Academic and commercial laboratories utilizing blood components for diagnostic development and therapeutic research. Cell therapy manufacturing facilities in Massachusetts and California are contracting for specialized blood-derived starting materials.
Operational maturity clusters in Blood Banks. Capability investment is concentrating in Clinics for decentralized therapy delivery.
Distribution Channel:
Channel selection reflects product temperature sensitivity, traceability mandates, and customer scale economics.
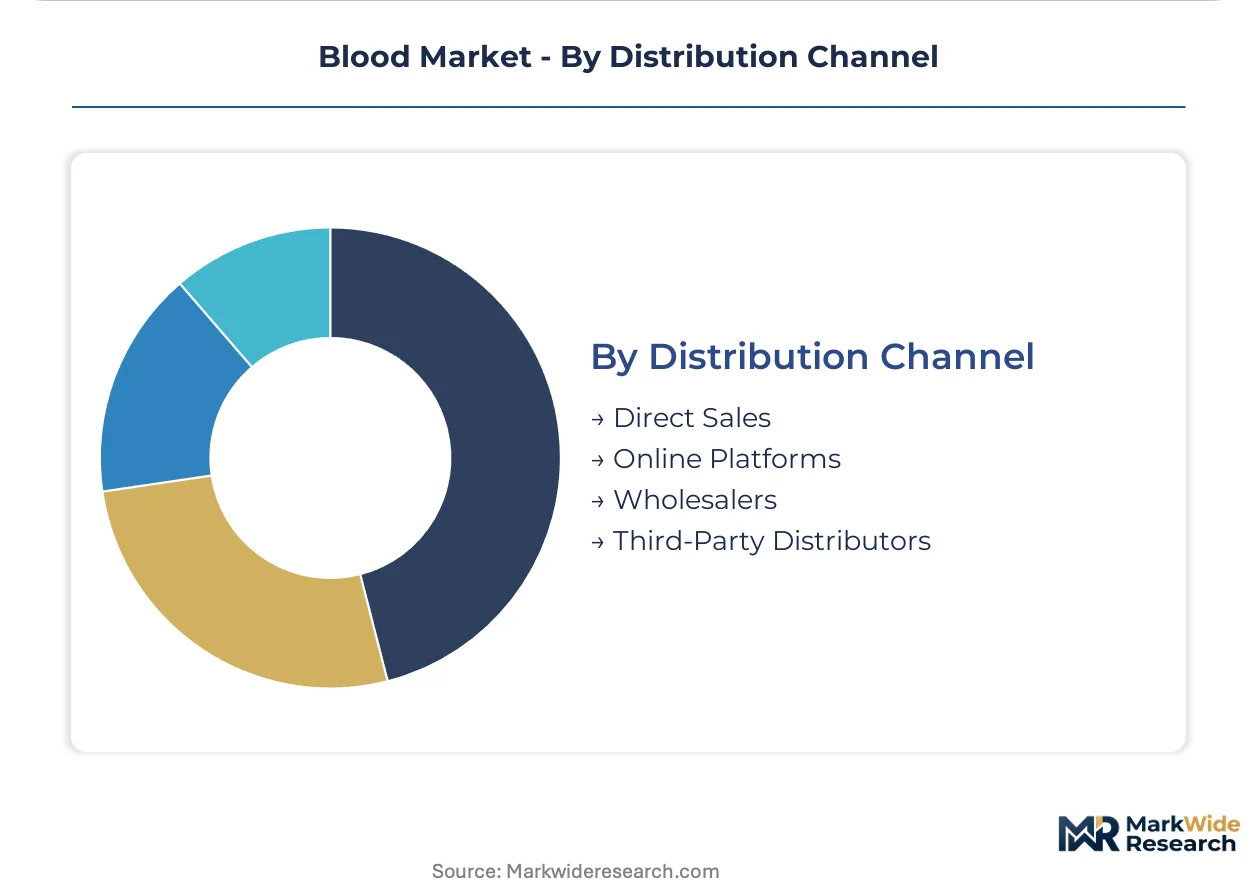
- Direct Sales:Manufacturer-to-institution relationships for plasma derivatives and specialized coagulation products. CSL and Grifols maintain captive distribution for immunoglobulin and albumin to major hospital systems.
- Online Platforms:Digital procurement interfaces for blood typing reagents, diagnostic consumables, and non-therapeutic products. REACH-compliant cold-chain documentation systems are integrating with hospital inventory management platforms.
- Wholesalers:Regional distributors handling high-volume red blood cell and platelet logistics under temperature-controlled conditions. US blood centers rely on contracted wholesale networks for rural hospital coverage.
- Third-Party Distributors:Specialized logistics providers for plasma derivatives requiring international cold-chain integrity. EMA F-Gas Regulation compliance is retrofitting refrigerant systems across European distribution infrastructure.
Established infrastructure supports Direct Sales and Wholesalers. Digital integration is advancing fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital transfusion volumes concentrate most heavily in the United States, where surgical backlog clearance and trauma center networks drive demand intensity. Plasma fractionation capacity clusters across three continents, with regulatory divergence creating distinct supply zone dynamics.
United States
FDA donor deferral policy revisions and plasma collection frequency restrictions are tightening source material availability. The agency's evolving screening protocols reshape collection economics at major fractionator networks. Texas, California, and New York trauma centers anchor transfusion demand through cardiovascular surgery and emergency care volumes.
China
NMPA plasma collection quotas and domestic fractionation facility licensing are constraining import dependency for albumin and immunoglobulin. The regulator's GB standards govern manufacturing quality thresholds. Hospital network expansion in provincial capitals is scaling prophylactic transfusion protocols and plasma-derived therapeutic access.
Germany
EMA Medical Device Regulation and F-Gas Regulation mandates are retrofitting cold-chain refrigerant systems across plasma logistics infrastructure. REACH compliance thresholds accelerate traceable documentation investment. Fractionation facilities in Bavaria and North Rhine-Westphalia absorb compliance costs that filter into regional pricing structures.
Japan
PMDA oversight of plasma-derived biologics and METI industrial policy shape fractionation import reliance and domestic production incentives. Oncology patient volumes in Tokyo and Osaka metropolitan areas are expanding prophylactic platelet transfusion protocols. Aging demographics intensify chronic immunoglobulin therapy infrastructure requirements.
United Kingdom
NHS England surgical backlog clearance is expanding elective procedure transfusion support across cardiac and orthopedic programs. The country's national pharmaceutical regulator enforces cold-chain integrity standards aligned with EMA frameworks. London and Southeast academic medical centers are unbundling supplier contracts to separate product procurement from therapeutic monitoring services.
Blood Market Vendor Landscape
United States and Australian producers anchor one tier; European specialists hold fractionation technology leadership; Japanese equipment fabricators supply automated collection infrastructure. The vendor base shows moderate consolidation around vertically integrated plasma networks, with three distinct strategic archetypes: captive collection-to-fractionation operators, standalone therapeutic protein developers, and blood component technology suppliers. Dominant competitive moves include geographic expansion of donor center footprints and strategic partnerships for pathogen reduction technology licensing.
Within the integrated plasma network tier, CSL Limited and Grifols S.A. exemplify archetypes defined by captive collection infrastructure spanning multiple continents. Takeda Pharmaceutical Company Limited occupies a position emphasizing specialized immunoglobulin portfolios and rare disease therapeutic focus. These three entities represent distinct strategic postures: Australian-based vertical integration, Spanish-dominant donor center scale, and Japanese-headquartered specialty biologics concentration.
| Leading Market Players |
|---|
| CSL Limited |
| Grifols S.A. |
| Takeda Pharmaceutical Company Limited |
| Octapharma AG |
| Baxter International Inc. |
| Bio-Rad Laboratories |
| Haemonetics Corporation |
| Terumo Corporation |
| Fresenius Kabi AG |
| Others |
Supply Flow & Price Mechanics
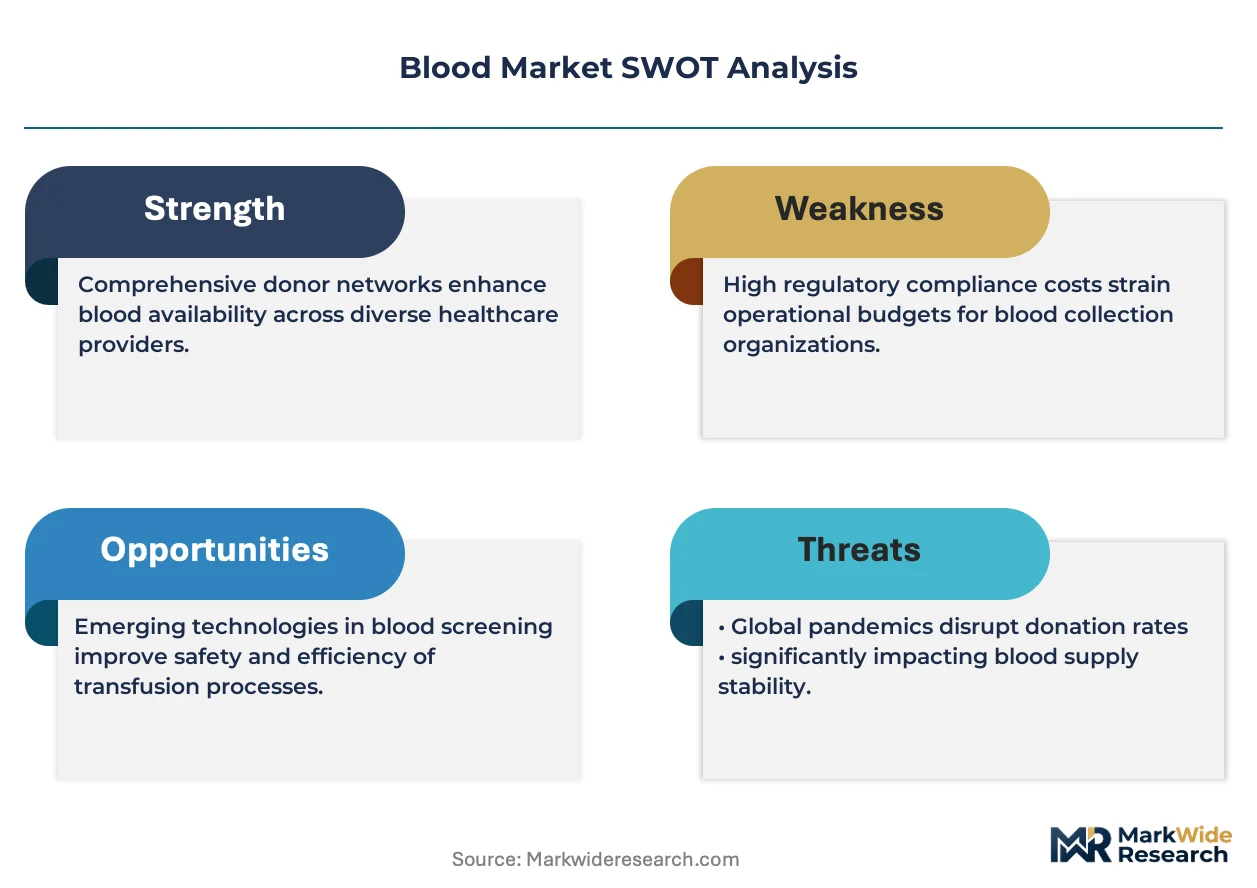
Vertically integrated plasma fractionators with captive donor center networks exercise asymmetric pricing power over standalone collection facilities, translating upstream control into premium positioning for immunoglobulin and albumin portfolios while compressing margins at non-integrated blood component suppliers.
Pricing Analysis
Short lead-time premiums for plasma derivatives with documented cold-chain integrity command pricing advantages in hospital procurement cycles, while spot inventory of red blood cell concentrates trades at discounts due to perishable viability windows. Three-tier pricing structure across premium, standard, and economy levels separates pathogen-reduced platelets from conventional units from imported alternatives. Cost compression in standard-tier products is intensifying because REACH compliance investments filter into European distribution markups. Dialysis chains and oncology practices demonstrate highest price sensitivity, while hemophilia treatment centers exhibit lowest elasticity due to therapeutic necessity and limited substitution options.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Illinois anchor hub-and-spoke patterns for red blood cell logistics, while plasma fractionation draws from concentrated processing capacity in the United States, Germany, and Spain. Raw material dependencies rest on apheresis collection equipment, citrate anticoagulant solutions, and specialized cold-chain refrigerants. Single-source vulnerability in automated plasmapheresis system manufacturing creates procurement risk for collection network expansion. Distribution runs through manufacturer-captive channels for plasma derivatives and contracted wholesale networks for cellular components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Blood Market operates as a cost-of-compliance story where FDA donor screening protocol revisions and EMA cold-chain mandates erect capital-intensive barriers that favor incumbent fractionators with established regulatory infrastructure.
For Market Incumbents: To counter recombinant clotting factor substitution in hemophilia A and B, CSL and Grifols should deepen backward integration into automated collection technology and expand pathogen-reduction certification across European distribution networks. Capacity addition in China's provincial hospital corridors captures domestic fractionation buildout momentum. For New Entrants and Emerging Players: Specialized third-party logistics providers with F-Gas Regulation-compliant refrigerant systems represent the most penetrable channel partner type for market entry. White-space targets include home infusion protocol service layers and pathogen reduction technology licensing in Asia-Pacific jurisdictions with emerging transfusion safety mandates. A go-to-market angle emphasizing interoperable blood bank information systems addresses legacy infrastructure upgrade demand. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale plasma collection networks with underutilized fractionation tolling agreements in Germany and Austria. Long-term viability hinges on regulatory compliance infrastructure amortization across multi-year hospital supply contracts. The signal to watch is NMPA plasma collection quota expansion signaling Chinese import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen Reduction Technology Licensing | INTERCEPT and Mirasol system deployments open access in EMA-regulated jurisdictions with stringent safety mandates. |
| Automated Collection Platform Deployment | Haemonetics and Terumo equipment compresses per-donor collection costs while enabling secondary market center expansion. |
| Home Infusion Protocol Development | Subcutaneous immunoglobulin administration shifts patient volume from hospital infusion centers to residential settings. |
| Cold-Chain Refrigerant Retrofit | F-Gas Regulation compliance mandates hydrofluorocarbon phase-down across European plasma logistics infrastructure. |
| Hospital Supply Agreement Restructuring | Unbundled contracts separate product procurement from therapeutic monitoring services in academic medical centers. |
Methodological Framework
Independent corroboration across fractionation facility operators, hospital transfusion service directors, and plasma collection network managers underwrites the qualitative findings in this study. Primary interviews with regulatory affairs specialists at FDA and EMA, GPO contracts managers, and biomedical engineers combined with secondary validation from FDA 510(k) filings, EMA marketing authorization databases, and hospital procurement contract repositories. Bottom-up modeling of collection center throughput and top-down triangulation against fractionation capacity utilization rates anchored volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth in cellular components from value expansion in plasma derivatives. Segmentation dimensions modeled include product type, therapy area, end-user facility category, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity constraint analysis. Forecast inputs incorporated surgical backlog clearance trajectories and immunoglobulin portfolio expansion rates in rare disease indications.
Several conditions sit outside the modeled scope, including pandemic-related donor deferral policy reversals, novel recombinant protein approvals displacing plasma-derived alternatives, and geopolitical trade restrictions affecting cold-chain equipment supply. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Performance Enhancing Drugs Market