
 Coronary Angiography Devices Market | 2026-2036
Coronary Angiography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Coronary Angiography Devices Market Analysis
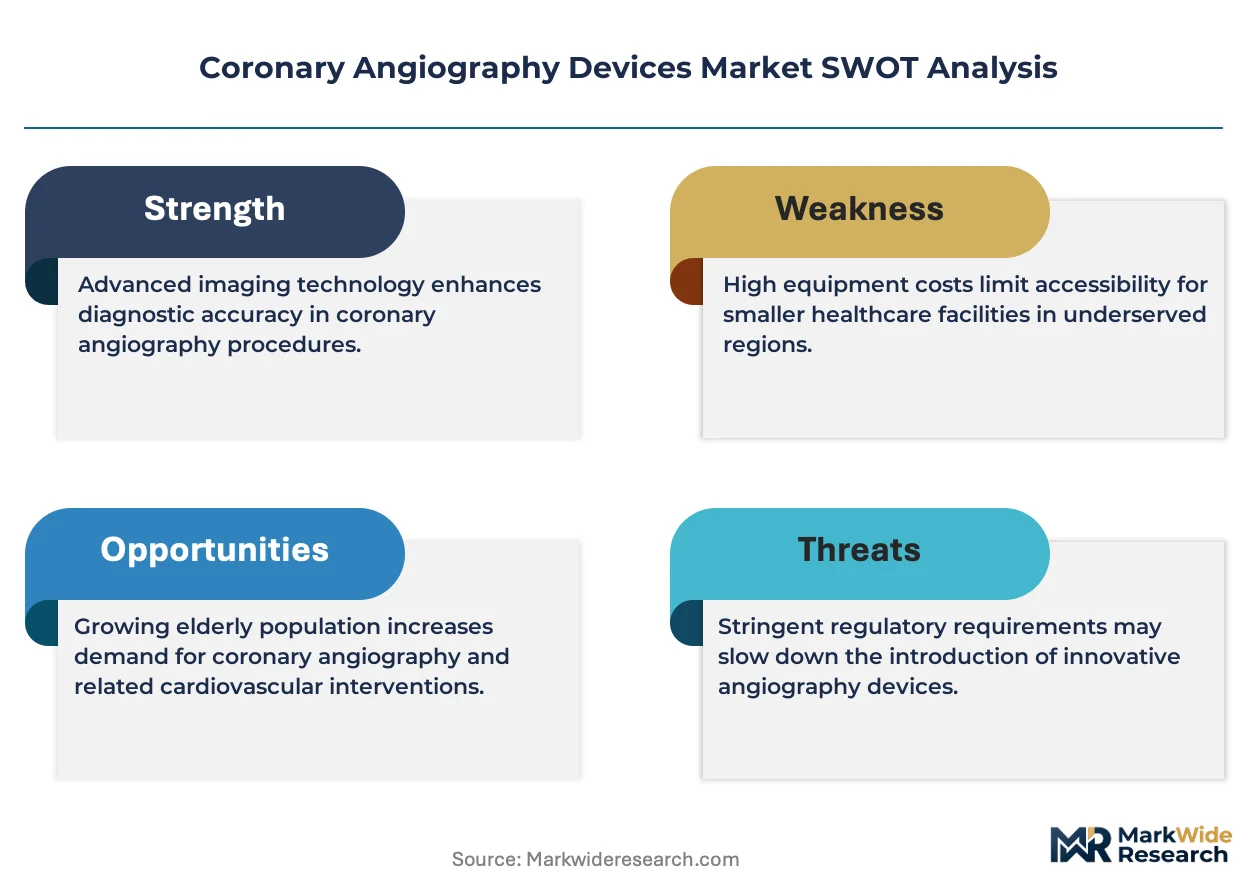
High-definition imaging specifications is bifurcating the competitive landscape into premium visualization platforms and cost-optimized systems. Siemens Healthineers leverages its photon-counting detector portfolio to sustain technology leadership in cardiac CT. Medtronic plc anchors its position through integrated cath lab ecosystems that span diagnostic imaging through interventional delivery. Abbott Laboratories differentiates via intravascular ultrasound platforms that combine anatomical imaging with physiological assessment.
Coronary angiography devices encompass X-ray fluoroscopy systems, computed tomography scanners, intravascular ultrasound catheters, and optical coherence tomography probes that employ iodinated contrast media to visualize coronary artery lumen and wall morphology. These systems achieve spatial resolutions below 0.2 millimeters in digital subtraction angiography modes, enabling clinicians to identify stenotic lesions and plan percutaneous coronary interventions. X-Ray Systems occupies the dominant revenue position due to installed base expansion across emerging health systems, while IVUS Systems captures accelerating demand as physiology-guided PCI protocols gain clinical acceptance. Digital Imaging leads technology adoption through AI-enhanced noise reduction algorithms, though 3D Reconstruction is gaining traction for complex bifurcation lesion planning.
FDA premarket clearance requirements under 21 CFR 892 shape device innovation timelines and clinical trial investment levels for US market entrants. The EU MDR and CE marking obligations impose stricter post-market surveillance and clinical evidence standards, filtering smaller manufacturers from European procurement channels. China's NMPA registration pathways and GB standards for medical electrical equipment add a third compliance layer for multinational suppliers. Stakeholders must monitor reimbursement parity between diagnostic angiography and combined diagnostic-therapeutic sessions as bundled payment models reshape hospital capital allocation priorities.
Market Dynamics
Hybrid operating room installations are concentrating capital expenditure among tertiary cardiac centers, forcing mid-tier hospitals into equipment leasing arrangements and shared service models that reshape vendor pricing power.
Growth Catalysts
- Physiology-guided PCI protocols:Fractional flow reserve and instantaneous wave-free ratio adoption is expanding IVUS catheter utilization rates in interventional cardiology departments across Germany and the United States.
- China's NMPA accelerated review pathways:Priority registration channels for innovative medical devices are shortening time-to-market for photon-counting CT systems targeting domestic hospital procurement cycles.
- Emerging health system cath lab buildouts:Government-funded cardiovascular infrastructure programs in India and Brazil are driving fluoroscopy system installations in previously underserved secondary cities.
Market Restraints
- Iodinated contrast media supply volatility:Manufacturing concentration among European and Chinese pharmaceutical suppliers creates intermittent shortages that delay scheduled angiography procedures.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for Class III devices are extending certification timelines and elevating compliance costs for OCT probe manufacturers.
- Interventional cardiologist training bottlenecks:Fellowship program capacity constraints in the United States and Western Europe limit cath lab throughput expansion regardless of equipment availability.
Strategic Opportunities
- Rural and semi-urban China:County-level hospital upgrades under the Healthy China 2030 initiative represent underserved demand for mobile C-arm systems with remote diagnostic connectivity.
- AI-enhanced image reconstruction:Deep learning noise reduction algorithms are converging with low-dose fluoroscopy protocols to enable outpatient cardiac catheterization in ambulatory surgical centers.
- Japan's PMDA Sakigake designation:Fast-track approval incentives for breakthrough devices are attracting intravascular imaging platform developers seeking early commercialization in the Asia-Pacific region.
Industry Challenges
- Biomedical engineer specialization gaps:Maintenance and calibration expertise for photon-counting detector arrays is concentrated among OEM-trained technicians, elevating service contract costs.
- Legacy PACS integration complexity:New imaging platforms face interoperability friction with hospital-wide archiving systems that operate on decade-old DICOM standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coronary Angiography Devices Market |
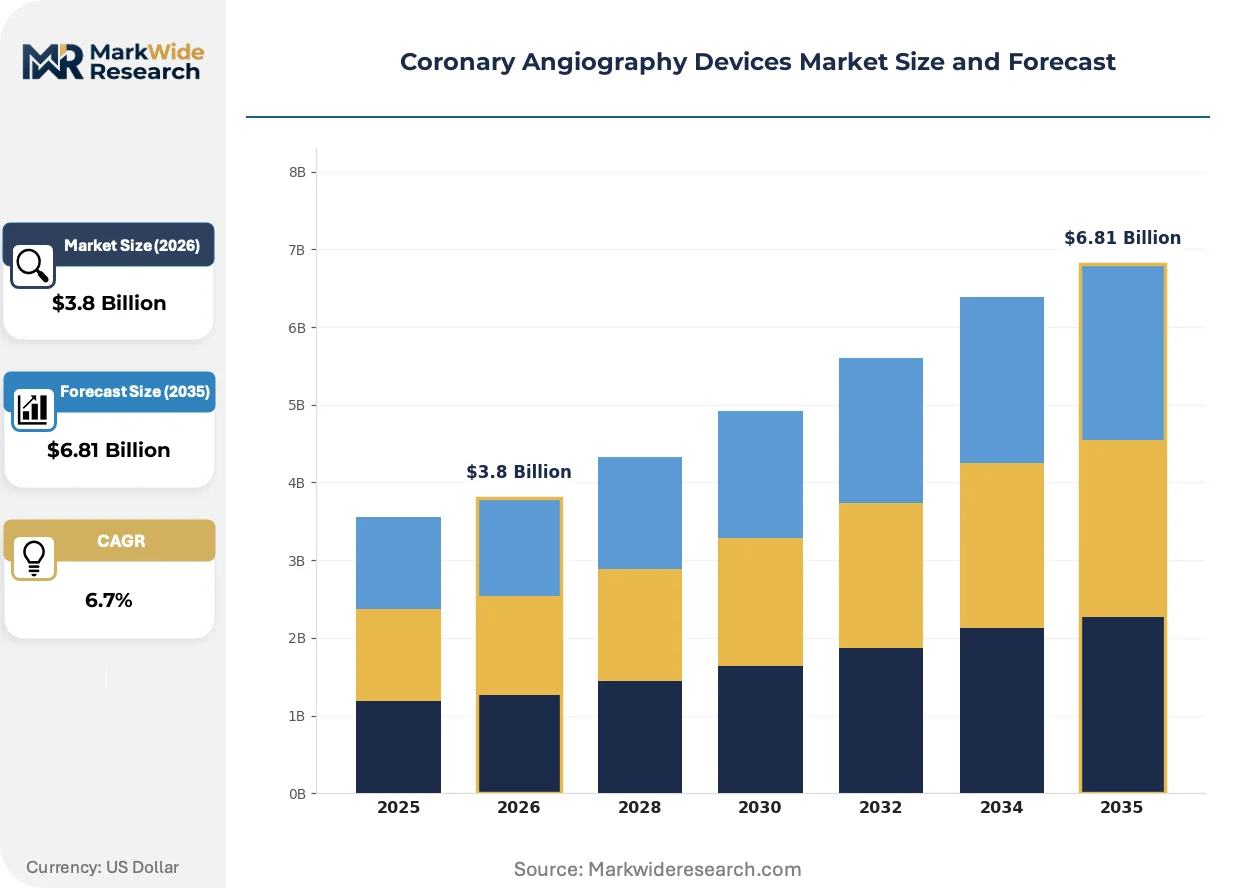
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, CT Angiography, Ultrasound Devices, IVUS Systems Technology: Digital Imaging, Electrophysiology, Robotics, 3D Reconstruction End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Research Institutions Application: Diagnostic Procedures, Therapeutic Interventions, Patient Monitoring, Preoperative Planning |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Abbott Laboratories, GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Terumo Corporation, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coronary Angiography Devices Market Emerging Trajectories
Computational imaging and regulatory harmonization are compressing product development cycles while fragmenting procurement authority across clinical and administrative stakeholders.
Photon-counting detector technology is bifurcating the cardiac CT market. Tertiary centers in the United States and Germany are adopting Siemens Healthineers' NAEOTOM Alpha platforms for spectral imaging capabilities. Cost-optimized energy-integrating systems are retreating to price-sensitive secondary hospitals in India and Southeast Asia.
EU MDR post-market clinical follow-up requirements are tightening evidence standards for intravascular ultrasound catheters. Manufacturers must now submit periodic safety updates and real-world performance data to notified bodies. European procurement committees are screening suppliers for established quality management systems, disadvantaging newer market entrants.
Hospital purchasing committees are unbundling service contracts from equipment sales. Large health systems in the United States are negotiating direct maintenance agreements with third-party service organizations. This disintermediation is most visible among integrated delivery networks in Texas and Florida that operate multi-site cath lab networks.
Coronary Angiography Devices Market Segmentation
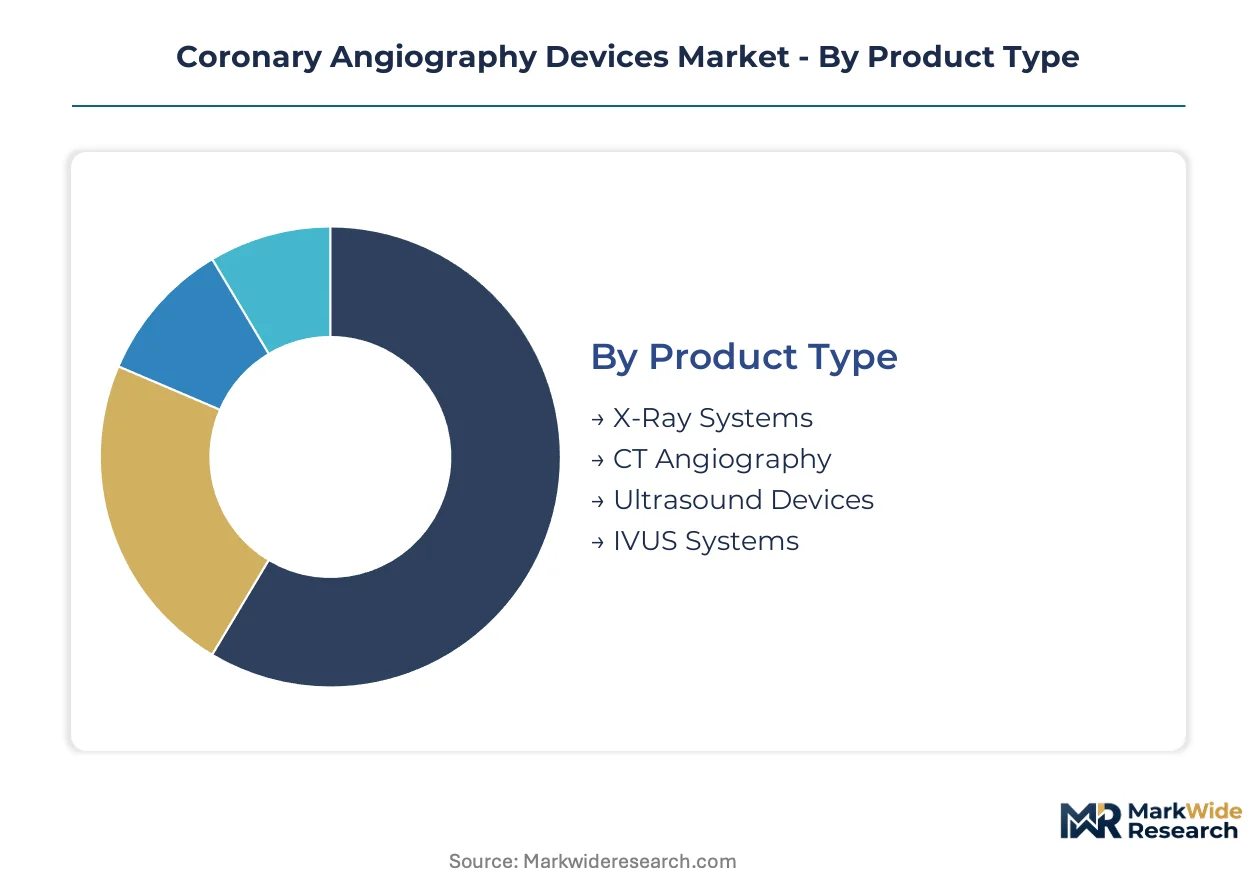
Device segmentation in coronary angiography reflects divergent capital intensity and reimbursement pathways. X-ray fluoroscopy platforms dominate installed base economics while intravascular imaging modalities capture incremental procedure value. Understanding substitution dynamics across product and technology tiers clarifies vendor positioning and hospital procurement priorities.
Product Type:
CT Angiography faces the strongest substitution pressure from photon-counting detector upgrades that render energy-integrating systems obsolete in tertiary centers.
- X-Ray Systems:Digital subtraction angiography platforms achieve spatial resolution below 0.2 millimeters using iodinated contrast protocols. Demand concentrates in United States and German tertiary centers expanding hybrid operating room capacity to handle complex PCI caseloads.
- IVUS Systems:Intravascular ultrasound catheters combine anatomical imaging with physiological assessment through fractional flow reserve integration. Cardiology departments in Germany and the United States are expanding catheter utilization as physiology-guided PCI protocols gain clinical acceptance.
- CT Angiography:Spectral imaging capabilities from photon-counting detectors are displacing conventional cardiac CT in premium hospital segments.
- Ultrasound Devices:Transthoracic and transesophageal echocardiography systems serve screening functions in cost-sensitive secondary hospitals across India and Brazil.
X-Ray Systems anchors the volume base while IVUS Systems gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium visualization platforms from price-optimized systems in mid-tier hospital procurement.
- Digital Imaging:AI-enhanced noise reduction algorithms enable low-dose fluoroscopy protocols that reduce radiation exposure during extended procedures. Ambulatory surgical centers in Texas and Florida are adopting these systems for outpatient cardiac catheterization programs.
- 3D Reconstruction:Computational modeling of coronary bifurcations supports complex PCI planning through virtual stent deployment simulation. Tertiary cardiac centers in Germany and China are integrating these tools into hybrid operating room workflows.
- Robotics:Remote catheter manipulation systems address interventional cardiologist training bottlenecks through standardized procedural mechanics.
- Electrophysiology:Integrated mapping and ablation platforms serve arrhythmia procedures that share cath lab infrastructure with coronary interventions.
Digital Imaging commands the largest installed base while 3D Reconstruction demonstrates the most rapid adoption trajectory in complex lesion centers.
End User:
Customer type determines capital deployment models with hospitals favoring outright purchase while smaller facilities pursue equipment leasing.
- Hospitals:Tertiary cardiac centers concentrate capital expenditure in hybrid operating room installations spanning diagnostic imaging through interventional delivery. United States integrated delivery networks in Texas and Florida are negotiating unbundled service contracts with third-party maintenance organizations.
- Ambulatory Surgical Centers:Outpatient cardiac catheterization facilities require compact C-arm systems with remote diagnostic connectivity. County-level hospital upgrades under China's Healthy China 2030 initiative are expanding this segment in underserved semi-urban markets.
- Cardiology Clinics:Specialist practices focus on diagnostic screening with referral relationships to hospital-based interventional programs.
- Research Institutions:Academic medical centers drive early adoption of photon-counting CT and intravascular imaging platforms for clinical trial endpoints.
Hospitals anchor the volume base while Ambulatory Surgical Centers expand most quickly as reimbursement shifts toward site-neutral payment models.
Application:
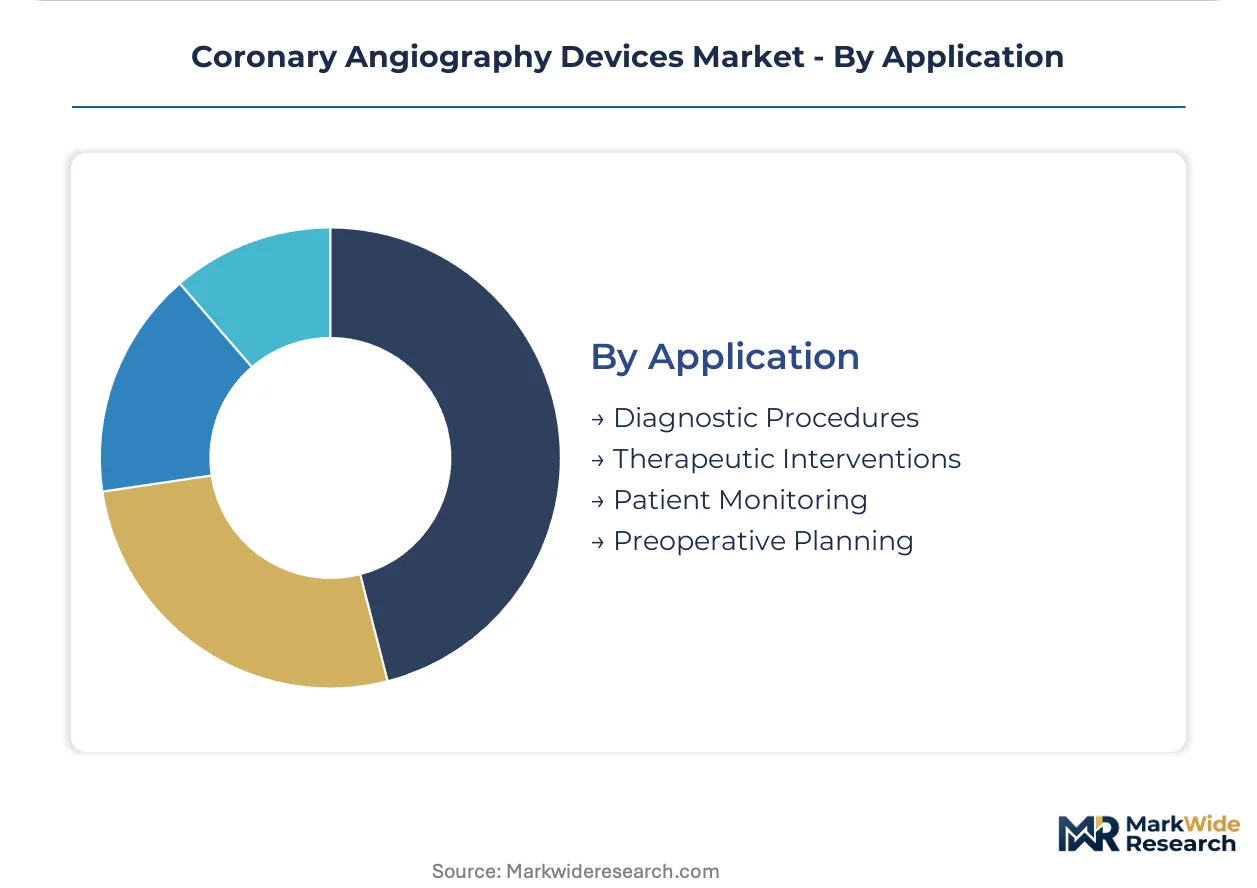
Procedure volume distribution favors diagnostic angiography though therapeutic integration captures higher per-procedure reimbursement.
- Diagnostic Procedures:Coronary angiography for stenosis identification and treatment planning constitutes the foundational application across all product categories. Reimbursement parity between standalone diagnostic sessions and combined diagnostic-therapeutic encounters is reshaping hospital capital allocation priorities in United States bundled payment markets.
- Therapeutic Interventions:PCI guidance using intravascular ultrasound and optical coherence tomography enables stent optimization and complication management. German and United States interventional cardiology departments are expanding physiology-guided protocols that pair anatomical with functional assessment.
- Preoperative Planning:CT-based coronary analysis supports surgical revascularization decisions in hybrid operating room environments.
- Patient Monitoring:Serial angiographic surveillance tracks graft patency and disease progression in post-intervention populations.
Diagnostic Procedures anchors the volume base while Therapeutic Interventions climbs the fastest as PCI complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Germany, the United States, and Japan, while procurement demand is fragmenting across tertiary cardiac centers in China and mid-tier hospitals in India. Regulatory divergence between FDA 21 CFR pathways, EU MDR certification, and China's NMPA registration is forcing multinational suppliers to maintain parallel compliance infrastructures. This geographic complexity rewards vendors with established quality management systems across multiple jurisdictions.
United States
Integrated delivery networks in Texas and Florida are expanding multi-site cath lab networks through hybrid operating room installations. FDA premarket notification pathways under 21 CFR 892 shape innovation timelines for domestic entrants. The Greater Boston cluster anchors photon-counting CT development alongside academic medical centers driving early adoption of intravascular imaging platforms.
Germany
Physiology-guided PCI protocols are expanding IVUS catheter utilization rates in interventional cardiology departments across Bavaria and North Rhine-Westphalia. EU MDR post-market surveillance obligations filter smaller manufacturers from European procurement channels. The Munich-Stuttgart corridor concentrates Siemens Healthineers' detector technology development alongside tertiary cardiac centers adopting spectral imaging capabilities.
China
County-level hospital upgrades under the Healthy China 2030 initiative are driving demand for mobile C-arm systems with remote diagnostic connectivity. NMPA accelerated review pathways for innovative medical devices shorten time-to-market for photon-counting CT systems. The Yangtze River Delta cluster concentrates domestic hospital procurement cycles for fluoroscopy system installations.
Japan
PMDA Sakigake fast-track designation incentives attract intravascular imaging platform developers seeking early Asia-Pacific commercialization. METI industrial policy supports computational imaging research through academic-industry partnerships. The Tokyo-Osaka corridor anchors Terumo Corporation's catheter manufacturing alongside regulatory consulting expertise for breakthrough device submissions.
India
Government-funded cardiovascular infrastructure programs are driving fluoroscopy system installations in secondary cities across Maharashtra and Karnataka. CDSCO medical device registration requirements add compliance complexity for multinational suppliers. The Mumbai-Pune cluster concentrates mid-tier hospital procurement for cost-optimized energy-integrating systems.
Coronary Angiography Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the coronary angiography devices landscape. The market structure consolidates around integrated imaging platform vendors, specialized catheter manufacturers, and diversified medical technology conglomerates. Three strategic archetypes dominate: premium visualization platform developers, integrated cath lab ecosystem providers, and physiology-guided intervention specialists. Competitive moves concentrate in strategic partnerships for AI-enhanced image reconstruction and unbundled service contract negotiations with large health systems.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories exemplify the integrated cath lab ecosystem archetype spanning diagnostic imaging through interventional delivery. Siemens Healthineers occupies a position representing premium visualization platform leadership through photon-counting detector portfolios. Boston Scientific Corporation anchors the physiology-guided intervention specialist tier alongside intravascular ultrasound and optical coherence tomography platform development.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Abbott Laboratories |
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Others |
Supply Flow & Price Mechanics
EU MDR post-market surveillance obligations gate both supplier qualification and price differentiation simultaneously, as notified bodies now audit quality management systems before procurement committees approve vendor lists. This regulatory filter compresses margins for non-compliant manufacturers while allowing certified incumbents to command service contract premiums.
Pricing Analysis
FDA 21 CFR 892 premarket notification pathways dictate the pricing tier structure across diagnostic imaging platforms. Three-tier pricing separates photon-counting CT systems from digital subtraction angiography platforms from mobile C-arm configurations, with certification grade and after-sales service bundling as primary differentiation levers. Pricing pressure stems from hospital purchasing committees unbundling maintenance agreements from equipment sales. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while German tertiary cardiac centers prioritize spectral imaging capabilities over cost optimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate iodinated contrast media procurement, though photon-counting detector arrays require strategic stockpiling given single-source manufacturing concentration. Supply concentrates in Germany, the United States, and Japan for detector technology, while China and India anchor fluoroscopy system assembly. Raw material dependencies include rare-earth scintillators, tungsten collimators, and high-purity iodine compounds. Tariff exposure on semiconductor components creates supply chain risk. Distribution runs through OEM direct sales forces for tertiary centers and third-party distributors for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coronary angiography devices sit in early-cycle expansion as hybrid operating room installations accelerate physiology-guided PCI adoption beyond traditional diagnostic applications.
For Market Incumbents: Fortify service contract profitability by developing in-house biomedical engineer training programs, reducing dependence on OEM-certified technicians for photon-counting detector maintenance. Pursue backward integration into iodinated contrast media supply through strategic pharmaceutical partnerships, mitigating manufacturing concentration risk among European and Chinese suppliers. For New Entrants and Emerging Players: China's NMPA accelerated review pathways offer fastest regulatory clearance for innovative intravascular imaging platforms. Target county-level hospital upgrades under Healthy China 2030, where mobile C-arm demand outpaces established vendor coverage. Lead with AI-enhanced noise reduction algorithms as differentiated software companion offerings rather than competing on hardware specifications. For Investors and Strategic Acquirers: EU MDR certification deadlines reshape the acquisition landscape by stranding non-compliant catheter manufacturers without notified body relationships. Five-to-ten year viability favors physiology-guided intervention specialists with integrated FFR-IVUS platforms over pure-play diagnostic imaging vendors. Watch NMPA registration queue lengths as inflection indicator for China market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment opens procurement channels in German and French hospital systems. |
| Hospital System Partnership | Integrated delivery networks in Texas negotiate unbundled service contracts across multi-site cath lab networks. |
| Software Companion Development | AI-enhanced image reconstruction enables low-dose protocols for ambulatory surgical center expansion. |
| Reimbursement Strategy | CMS bundled payment parity between diagnostic and therapeutic sessions reshapes capital allocation priorities. |
| FDASubmission | 510(k) clearance under 21 CFR 892 establishes US market entry for photon-counting detector upgrades. |
Methodological Framework
A standing panel of interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, NMPA registration databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up equipment installation tracking and top-down revenue estimates were triangulated to anchor segmentation outputs.
Consistency checks against external benchmarks validated volume and value projections across the modeling period. The analytical framework modeled product type, technology tier, end-user facility class, and application mix as core segmentation dimensions. CAGRs were derived from procedure volume growth curves and capital expenditure cycles specific to cath lab infrastructure buildouts. Forecast inputs incorporated iodinated contrast media supply volatility and interventional cardiologist fellowship capacity constraints.
Decision-makers should treat outputs as directional under assumptions of stable regulatory clearance timelines and continued hospital capital expenditure prioritization; material deviation would warrant model refresh. Revision becomes warranted when EU MDR notified body capacity constraints or NMPA review queue extensions cross thresholds that alter time-to-market assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Stool Management Systems Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Ventilator Accessories Market