
 Global Cataract Surgery Devices Market | 2026-2036
Global Cataract Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cataract Surgery Devices Market Foresight
The EU Medical Device Regulation is rebalancing procurement criteria across European ophthalmology departments toward extended biocompatibility tracking and post-market surveillance. Alcon Inc. leverages its vertically integrated phacoemulsification platform to sustain service revenue attachment rates across installed base upgrades. Johnson & Johnson Services, Inc. anchors its competitive position through proprietary femtosecond laser workflows that integrate pre-operative diagnostics with surgical execution. Carl Zeiss Meditec AG differentiates via optical coherence tomography-guided cataract platforms that occupy the premium diagnostic-surgical convergence segment.
Cataract surgery devices encompass phacoemulsification systems, femtosecond laser platforms, intraocular lenses, and associated consumables designed to fragment, extract, and replace opacified crystalline lenses through corneal incisions typically measuring 1.8 to 2.2 millimeters. These instruments restore visual acuity by emulsifying the cataractous lens with ultrasonic energy or laser photodisruption, then implanting a synthetic intraocular lens within the capsular bag. Intraocular lenses generate the dominant margin pool due to recurring upgrade cycles toward toric and extended-depth-of-focus platforms. Femtosecond laser devices represent the fastest-growing product category as surgical centers adopt bladeless corneal incision and automated capsulotomy for refractive outcomes consistency.
The FDA maintains Class II and Class III premarket notification pathways for phacoemulsification handpieces and premium intraocular lenses, while the EU MDR imposes stricter clinical evidence thresholds through notified body conformity assessments. Japan's PMDA applies distinct pharmaceutical-medical device hybrid review standards for drug-eluting and accommodative lens technologies. Stakeholders must monitor evolving reimbursement coding for laser-assisted cataract procedures across Medicare, NHS England, and statutory health insurers in Germany and Japan.
Market Dynamics
The cataract surgery devices sector is experiencing a fundamental reorientation as femtosecond laser platforms compress procedural variability and shift margin capture toward consumable attachments. This technological inflection is redistributing competitive advantage from standalone equipment vendors toward integrated system providers capable of locking in recurring revenue streams across surgical workflows.
Growth Catalysts
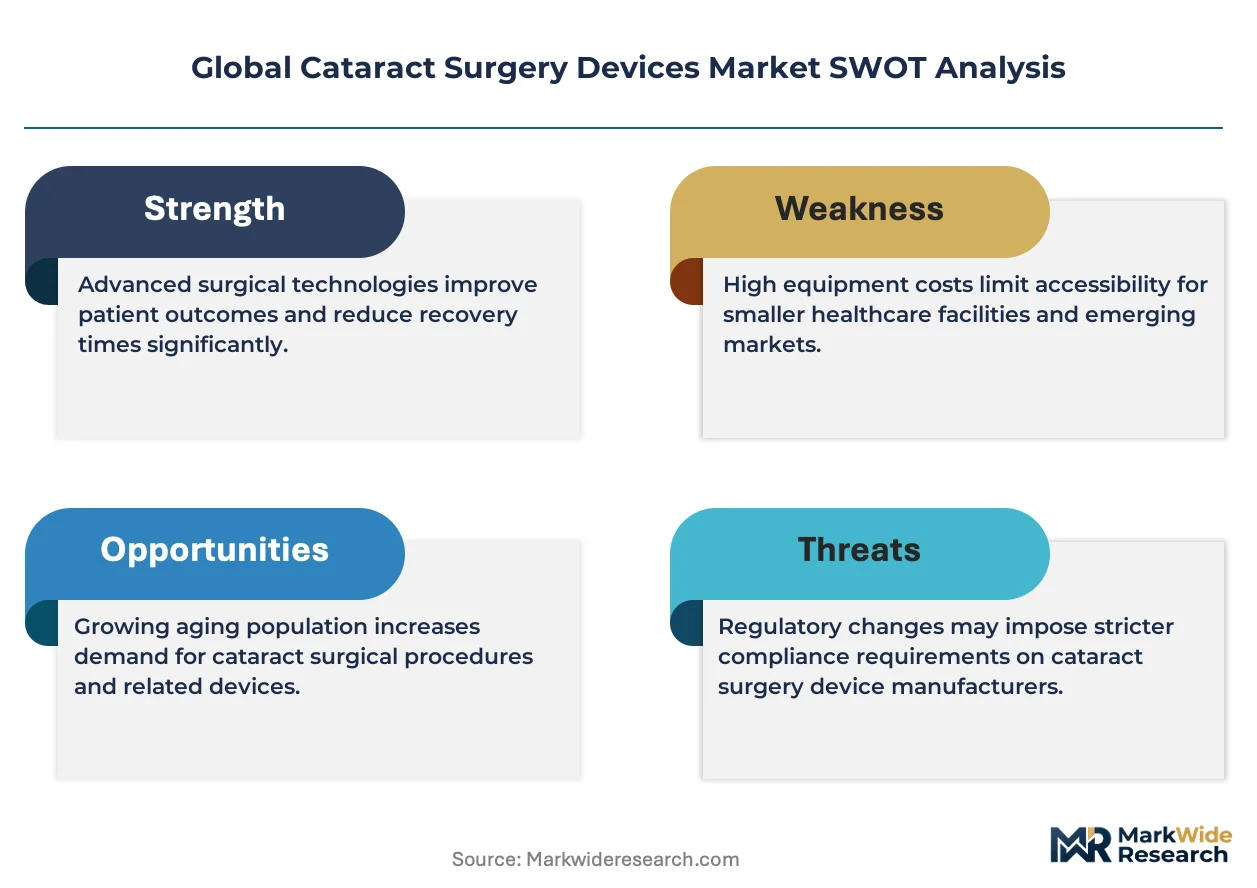
- EU MDR Compliance Thresholds:Stricter biocompatibility surveillance requirements for intraocular lenses are accelerating replacement cycles as older lens portfolios face forced obsolescence. European ophthalmology departments are consolidating procurement around vendors with established post-market tracking infrastructure.
- Japan's Aging Surgical Population:METI projections indicate sustained procedural volume expansion as the 75-plus demographic segment grows. Statutory health insurance frameworks in Japan are expanding reimbursement bandwidth for premium lens upgrades.
- Femtosecond Laser Automation:Bladeless capsulotomy and automated corneal incision capabilities are reducing surgeon-to-surgeon outcome variance. Ambulatory surgical centers in Germany and the United States are prioritizing capital allocation toward these platforms to support refractive cataract service lines.
Market Restraints
- Capital Equipment Intensity:Phacoemulsification system refresh cycles require substantial upfront investment, constraining independent surgical centers and public hospital systems with fixed capital budgets.
- Notified Body Bottlenecks:EU MDR conformity assessment capacity constraints are extending time-to-market for novel intraocular lens designs, compressing effective patent life and deterring mid-stage R&D commitments.
- Monofocal Lens Substitution Pressure:Standard monofocal intraocular lenses face commoditization as tender-based procurement in emerging markets prioritizes unit cost over optical performance differentiation.
Strategic Opportunities
- Extended-Depth-of-Focus Convergence:Hybrid optical designs combining multifocal and extended-depth-of-focus characteristics are integrating with diagnostic platforms to reduce spectacle dependence. Premium private pay segments in Switzerland and Australia are absorbing first-generation premiums.
- Drug-Eluting Lens Platforms:PMDA's pharmaceutical-medical device hybrid pathway is creating regulatory precedent for post-surgical medication delivery via implanted lenses. Japanese academic medical centers are establishing clinical evidence frameworks for these combination products.
- Direct-to-Surgeon Digital Channels:Equipment manufacturers are bypassing traditional distributor networks to capture procedure data and consumable reorder flows. Cloud-connected phacoemulsification handpieces are enabling predictive inventory replenishment in United States ambulatory surgery chains.
Industry Challenges
- Femtosecond Laser Surgeon Certification:Proprietary workflow interfaces require dedicated training protocols, creating onboarding friction and temporary throughput reductions during platform transitions.
- Optical Coherence Tomography Integration Complexity:Pre-operative diagnostic data formats lack standardization across equipment vendors, forcing surgical centers to maintain redundant diagnostic hardware or accept interoperability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cataract Surgery Devices Market |
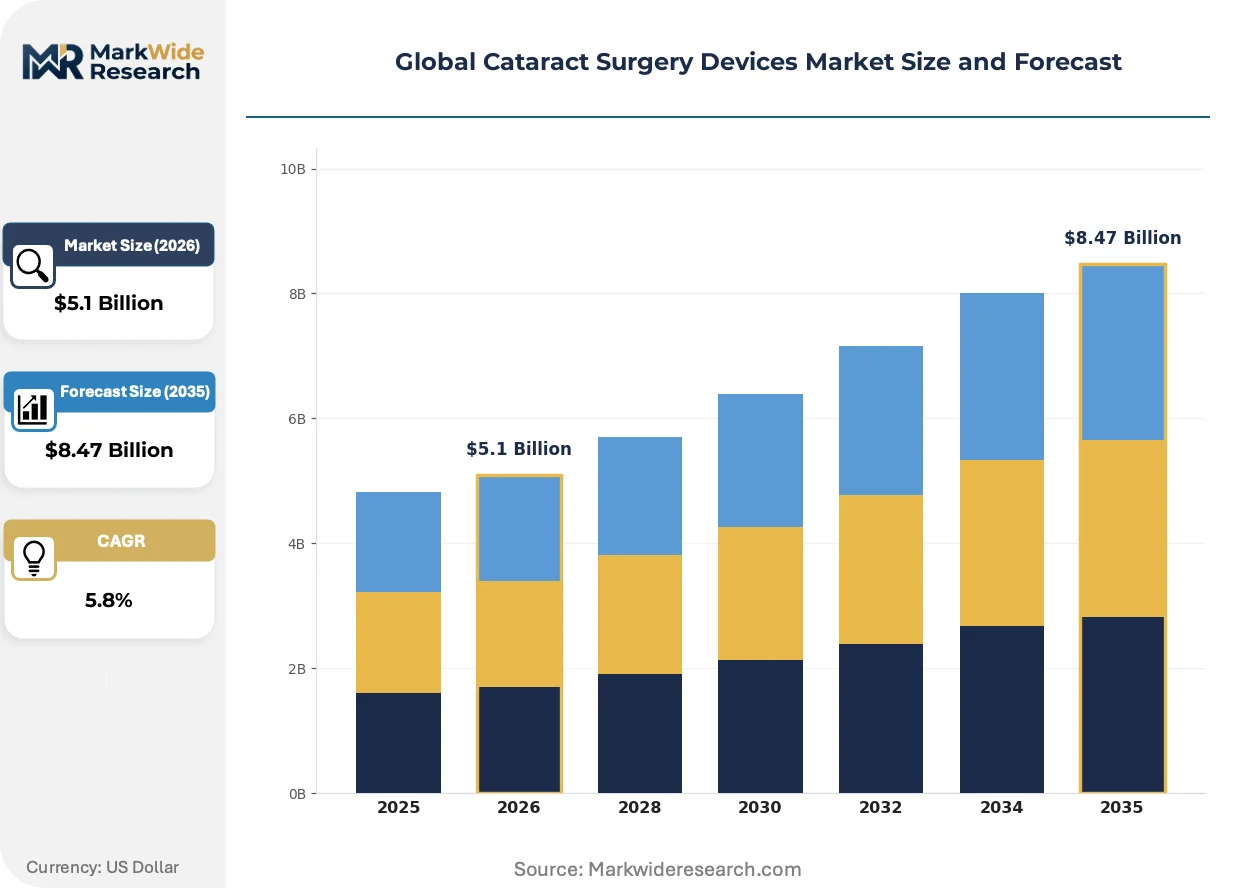
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phacoemulsification Systems, Femtosecond Laser Devices, Intraocular Lenses, Vitrectomy Instruments, Ophthalmic Viscoelastic Devices Application: Cataract Extraction, Lens Fragmentation, Lens Implantation, Corneal Incision, Anterior Vitrectomy End User: Eye Clinics, Specialized Surgery Centers, Ophthalmology Departments, Ambulatory Surgical Facilities, Vision Care Hospitals Technology: Ultrasound Phacoemulsification, Laser-Assisted Surgery, Micro-Incision Techniques, Manual Small Incision, Automated Fluidics Systems |
| Companies Covered | Alcon Inc., Johnson & Johnson Services, Inc., Carl Zeiss Meditec AG, Bausch Health Companies Inc., Abbott Laboratories, NIDEK Co., Ltd., HOYA Corporation, STAAR Surgical Company, Ziemer Ophthalmic Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cataract Surgery Devices Market Shifts & Advancements
Femtosecond laser technology is restructuring competitive boundaries by merging refractive surgery precision with cataract extraction workflows. This convergence is forcing equipment manufacturers to rearchitect service revenue models and diagnostic-surgical integration layers.
Intraoperative optical coherence tomography is integrating real-time anterior segment imaging directly into phacoemulsification surgical microscopes. Academic medical centers in Germany and Japan are adopting these platforms to guide capsular bag centration and posterior capsule assessment. The technology is integrating pre-operative biometric planning with intraoperative feedback loops, compressing revision rates for toric lens misalignment.
Japan's PMDA is tightening evidentiary standards for accommodative intraocular lenses through enhanced long-term stability protocols. Manufacturers must now submit five-year follow-up data on capsular bag fibrosis and lens position stability prior to approval. Premium lens portfolios targeting the Japanese market are experiencing delayed launch timelines and expanded clinical trial budgets.
United States ambulatory surgery centers are unbundling equipment service contracts from capital purchase agreements. Purchasers are negotiating usage-based maintenance models tied to validated procedure volumes rather than fixed annual fees. This shift is most visible in regional surgery center chains consolidating phacoemulsification fleet management under centralized procurement functions.
Global Cataract Surgery Devices Market Segmentation
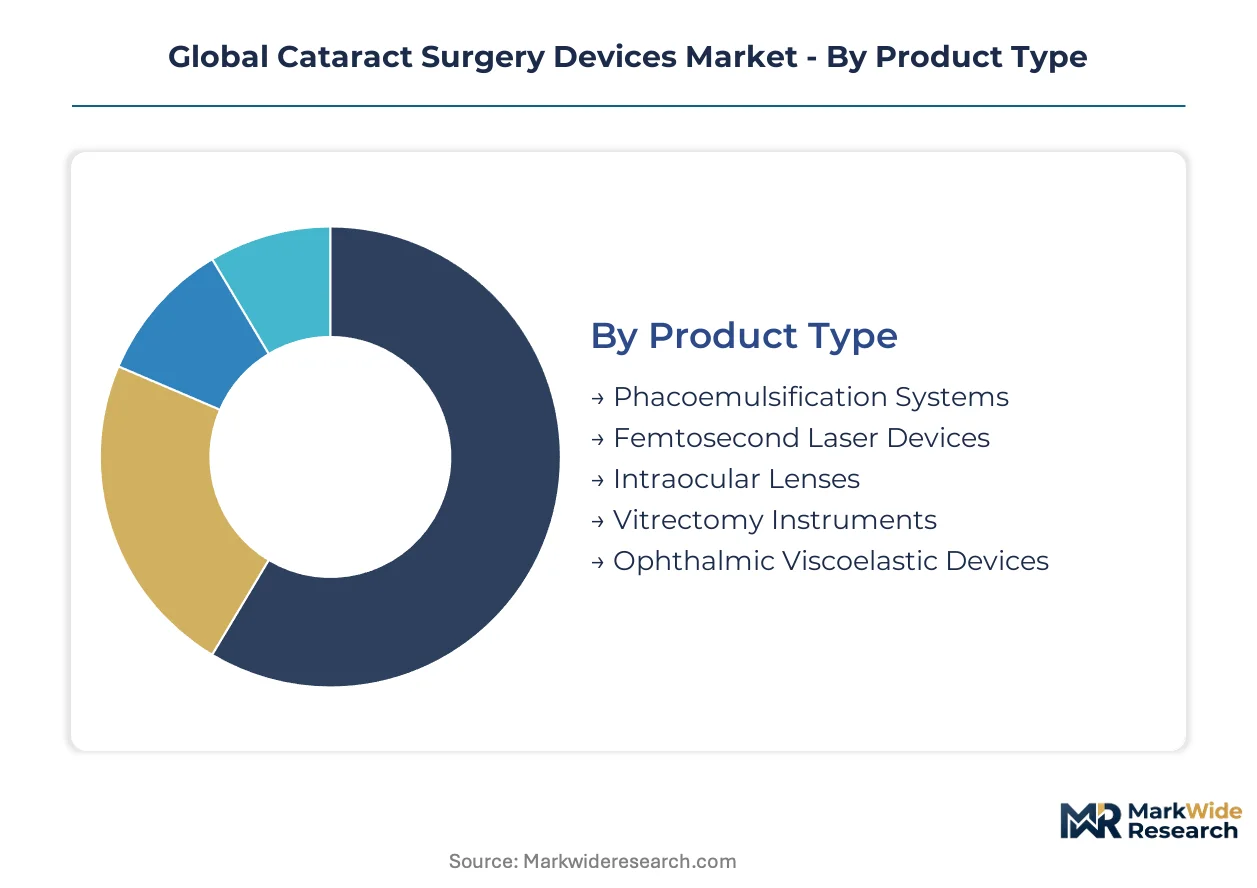
Device segmentation in cataract surgery reflects divergent margin profiles across capital equipment, disposable consumables, and implantable biologics. Procurement patterns split between high-volume standard procedures and premium refractive cataract workflows that demand integrated diagnostic-surgical platforms.
Product Type:
Technical sophistication and recurring revenue attachment define competitive positioning across device categories.
- Intraocular Lenses:Synthetic optical implants restore refractive power through monofocal, toric, and extended-depth-of-focus designs. Japanese statutory health insurance and United States Medicare Advantage plans are expanding reimbursement bandwidth for premium lens upgrades, though EU MDR biocompatibility surveillance is accelerating replacement cycles for older portfolios.
- Femtosecond Laser Devices:Bladeless platforms execute automated capsulotomy and corneal incision through photodisruption rather than mechanical cutting. Ambulatory surgical centers in Germany and the United States are prioritizing capital allocation toward these systems to reduce surgeon-to-surgeon outcome variance in refractive cataract service lines.
- Phacoemulsification Systems:Ultrasonic handpieces emulsify cataractous lens material through corneal incisions.
- Vitrectomy Instruments:Specialized cutters and illumination systems address posterior segment complications.
- Ophthalmic Viscoelastic Devices:Space-maintaining gels protect corneal endothelium during lens insertion.
Mature deployment sits with phacoemulsification systems. Newer deployment is concentrated in femtosecond laser devices.
Application:
Procedural steps map to distinct equipment requirements and consumable attachment rates.
- Cataract Extraction:Complete removal of opacified crystalline lens material through phacoemulsification or manual techniques. Eye clinics in Japan are expanding procedural volumes as the 75-plus demographic grows, with METI projections indicating sustained demand through the forecast horizon.
- Lens Implantation:Insertion and centration of synthetic intraocular lens within the capsular bag. Specialized surgery centers in Switzerland and Australia are absorbing first-generation premiums for extended-depth-of-focus platforms in private pay segments.
- Lens Fragmentation:Pre-extraction emulsification or laser pre-treatment of nuclear material.
- Corneal Incision:Self-sealing entry wounds for instrument access.
- Anterior Vitrectomy:Removal of vitreous from the anterior chamber during complicated cases.
Standard workflows dominate cataract extraction. Premium positioning is accelerating fastest in lens implantation.
End User:
Facility type determines capital intensity tolerance and premium technology adoption rates.
- Ambulatory Surgical Facilities:Outpatient centers optimized for high-throughput cataract workflows with same-day discharge protocols. United States regional surgery chains are unbundling equipment service contracts and negotiating usage-based maintenance models tied to validated procedure volumes.
- Specialized Surgery Centers:Dedicated ophthalmology facilities with refractive cataract service lines. German centers are prioritizing femtosecond laser platforms to support premium lens upgrade pathways within statutory health insurance frameworks.
- Eye Clinics:Office-based settings for diagnosis and minor procedures.
- Ophthalmology Departments:Hospital-integrated units with academic research missions.
- Vision Care Hospitals:Comprehensive eye care institutions handling complex cases.
Volume concentration rests with ambulatory surgical facilities. Technology leadership is shifting toward specialized surgery centers.
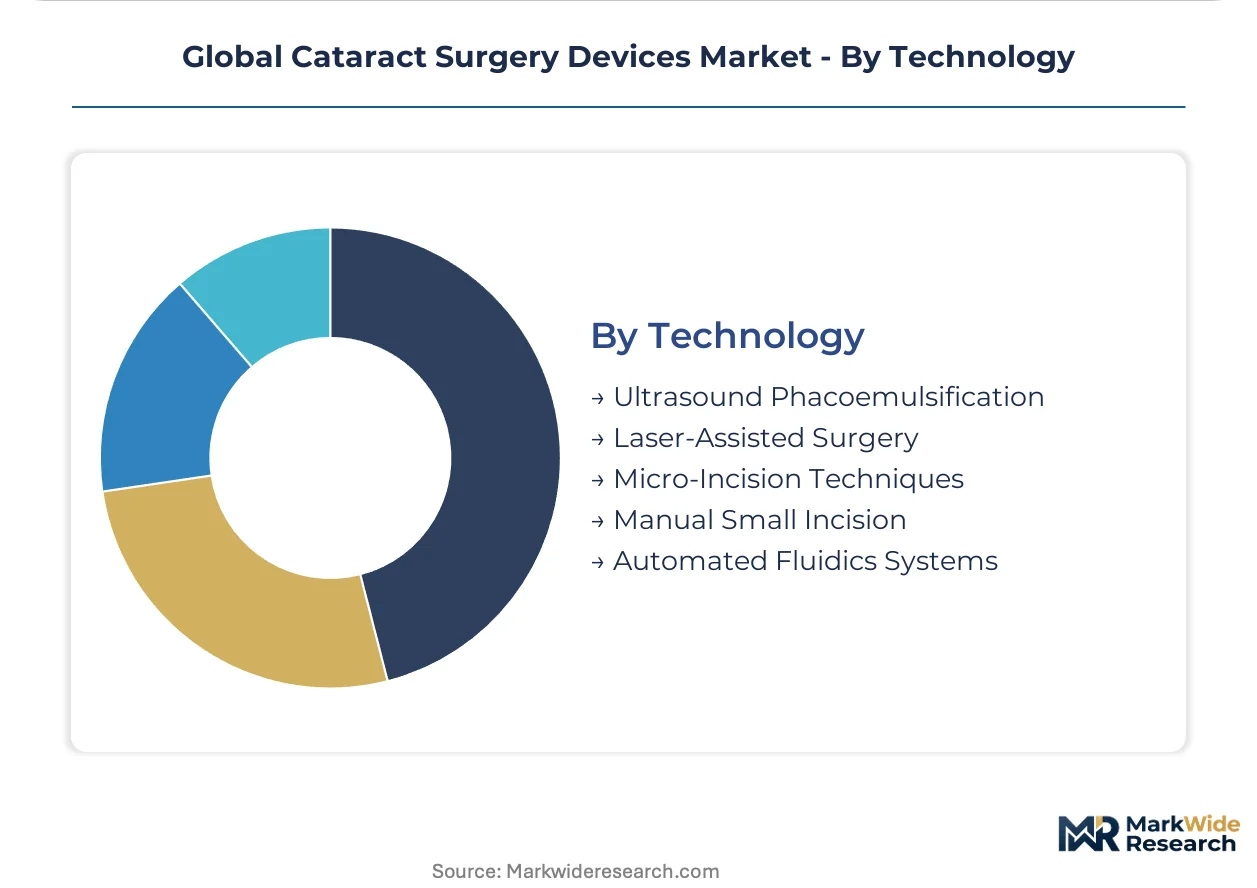
Technology:
Energy delivery modality and incision scale differentiate clinical outcomes and equipment economics.
- Laser-Assisted Surgery:Femtosecond photodisruption replaces mechanical blades for capsulotomy, lens fragmentation, and corneal incision. PMDA in Japan and FDA in the United States maintain distinct regulatory pathways for these platforms, with Japan applying pharmaceutical-medical device hybrid standards for drug-eluting combinations.
- Micro-Incision Techniques:Corneal entry wounds measuring 1.8 to 2.2 millimeters reduce induced astigmatism and accelerate visual recovery. Academic medical centers in Germany are adopting intraoperative optical coherence tomography guidance to optimize incision architecture and toric lens alignment.
- Ultrasound Phacoemulsification:Conventional ultrasonic emulsification through handheld probes.
- Manual Small Incision:Sutureless extracapsular techniques for resource-constrained settings.
- Automated Fluidics Systems:Computer-controlled irrigation-aspiration management.
Established infrastructure supports ultrasound phacoemulsification. Steepest expansion trajectory belongs to laser-assisted surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Germany, Switzerland, and Japan while procedural consumption centers on the United States and aging Asian populations. This geographic split shapes regulatory compliance priorities and capital allocation patterns across the value chain.
United States
Medicare Advantage plans are expanding reimbursement bandwidth for premium intraocular lens upgrades. The FDA maintains Class II and Class III premarket notification pathways for phacoemulsification handpieces and accommodative lens designs. Ambulatory surgery centers in Florida and Texas are unbundling equipment service contracts in favor of usage-based maintenance models.
Germany
Statutory health insurance frameworks favor premium lens upgrade pathways within refractive cataract service lines. The EU Medical Device Regulation imposes stricter clinical evidence thresholds through notified body conformity assessments. Academic medical centers in Bavaria and Baden-Württemberg are adopting intraoperative optical coherence tomography guidance for toric lens alignment.
Japan
METI projections indicate sustained procedural volume expansion as the 75-plus demographic segment grows. The PMDA applies pharmaceutical-medical device hybrid review standards for drug-eluting and accommodative lens technologies. Eye clinics in Tokyo and Osaka are establishing clinical evidence frameworks for combination product platforms.
Switzerland
Private pay segments are absorbing first-generation premiums for extended-depth-of-focus lens platforms. Swissmedic maintains distinct conformity assessment procedures for premium implantable devices exceeding standard optical performance thresholds. Specialized surgery centers in Zurich and Geneva anchor premium refractive cataract service lines for cross-border patient flows.
Australia
Private health insurance funds are expanding coverage bandwidth for femtosecond laser-assisted procedures. The TGA aligns premarket assessment pathways with FDA and European precedents for intraocular lens biocompatibility. Vision care hospitals in Sydney and Melbourne are consolidating procurement around vendors with established post-market surveillance infrastructure.
Global Cataract Surgery Devices Market Competitive Landscape
The competitive structure tilts toward integrated system providers capable of locking in recurring revenue streams across surgical workflows. Tiered positioning separates premium diagnostic-surgical convergence platforms from standalone equipment vendors. Two strategic archetypes dominate: vertically integrated ophthalmology conglomerates with captive lens portfolios, and specialized laser platform developers with proprietary workflow interfaces. Dominant competitive moves include strategic partnerships for diagnostic-surgical integration and geographic expansion through distributor network consolidation.
Within the integrated ophthalmology tier, Alcon Inc., Johnson & Johnson Services, Inc., and Carl Zeiss Meditec AG occupy positions as archetype anchors. Alcon represents the vertically integrated phacoemulsification platform model. Johnson & Johnson Services, Inc. exemplifies the proprietary femtosecond laser workflow approach. Carl Zeiss Meditec AG sits within the optical coherence tomography-guided convergence segment. These three entities collectively illustrate the strategic divergence between equipment-centric and diagnostic-integrated competitive vectors.
| Leading Market Players |
|---|
| Alcon Inc. |
| Johnson & Johnson Services, Inc. |
| Carl Zeiss Meditec AG |
| Bausch Health Companies Inc. |
| Abbott Laboratories |
| NIDEK Co., Ltd. |
| HOYA Corporation |
| STAAR Surgical Company |
| Ziemer Ophthalmic Systems AG |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up ophthalmology equipment specialists anchor supply-side consolidation, compressing procurement leverage for independent surgical centers while enforcing disciplined tiered pricing across premium, standard, and economy lens portfolios. This ownership pattern concentrates distribution power with integrated platform vendors who bundle capital equipment, consumables, and service contracts into multi-year lock-in arrangements.
Pricing Analysis
Margin tightening in standard monofocal lenses reflects tender-based procurement prioritization across emerging market hospital systems. Three-tier pricing structure across premium, standard, and economy levels differentiates by optical performance certification and surgeon training bundling. Pricing pressure intensifies in phacoemulsification handpiece refills as ambulatory surgery chains negotiate usage-based maintenance models. Public hospital systems exhibit highest price sensitivity; private refractive cataract service lines absorb premium positioning with least resistance.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and Japan feed hub-and-spoke patterns into United States and Asia-Pacific consumption nodes. Manufacturing draws from precision optical glass, medical-grade silicone, and ultrasonic transducer components. Single-source vulnerability concentrates in femtosecond laser crystal suppliers. Distribution runs through authorized dealer networks with direct-to-surgeon digital channels emerging for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cataract surgery devices sector functions as a vertical-integration race where captive intraocular lens production determines margin capture against standalone equipment competitors. Control over consumable attachment rates represents the decisive downstream lever.
For Market Incumbents: To counter femtosecond laser platform commoditization, Alcon Inc. and Johnson & Johnson Services, Inc. should deepen backward integration into diagnostic software layers and lock hospital systems into exclusive lens-upgrade pathways. CE marking investment for extended-depth-of-focus portfolios under EU MDR tightens procurement consolidation. For New Entrants and Emerging Players: Ambulatory surgery center chains in the United States Southeast present the most penetrable white-space target for cloud-connected phacoemulsification handpieces with predictive inventory features. Direct-to-surgeon digital channels bypass entrenched distributor relationships. Reimbursement strategy consulting bundled with equipment trials accelerates initial placement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale femtosecond laser developers with PMDA submission-ready platforms in Japan. Long-term viability hinges on recurring revenue attachment rates exceeding capital equipment replacement cycles. Watch EU notified body capacity expansion as the signal for accelerated novel lens launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Notified body certification accelerates premium lens portfolio replacement cycles across German and Swiss procurement. |
| Hospital System Partnership | Exclusive lens-upgrade agreements with United States ambulatory surgery chains lock in multi-year consumable flows. |
| Software Companion Development | Cloud-connected handpieces enable predictive inventory replenishment for regional surgery center consolidation. |
| Reimbursement Strategy | Medicare Advantage bandwidth expansion for toric and extended-depth-of-focus platforms shifts private pay absorption. |
| CE Marking Pathway | Swissmedic distinct procedures for premium implants exceeding standard optical thresholds anchor Zurich premium positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cataract surgery devices analysis. Primary interviews with cataract surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, EU MDR notified body registers, PMDA approval summaries, and Medicare reimbursement coding to enable bottom-up and top-down triangulation.
Data-stream reconciliation across procedural volume databases, equipment shipment records, and lens implant registries generated consistent growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, application, end-user facility class, energy delivery technology, and regional regulatory cluster. CAGRs derived from installed base expansion rates and premium lens upgrade penetration curves.
Caveats apply where EU notified body capacity constraints, Japan's five-year accommodative lens stability protocols, or United States reimbursement coding shifts could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transilluminators Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Pathology Devices Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Penile Implants Market
Medical Devices
Toe Fixation System Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Medical Oxygen Concentrators Market