
 Cranial Navigation Systems Market | 2026-2036
Cranial Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Navigation Systems Market Analysis
The divergence between premium optical navigation and commodity electromagnetic tiers is hardening as hospital procurement committees weigh sub-millimeter accuracy against capital budget constraints. Medtronic leverages its integrated surgical ecosystem to sustain installed-base loyalty across academic medical centers. Brainlab AG differentiates through software-centric architectures that reduce hardware footprint in crowded operating rooms. Stryker competes by extending its navigation portfolio through robotics-assisted platforms that command higher service contract values.
Cranial navigation systems comprise intraoperative positioning platforms that fuse preoperative imaging with real-time surgical instrument tracking, typically achieving spatial resolution below one millimeter through optical, electromagnetic, or hybrid sensor arrays. These systems enable precise localization of anatomical targets during neurosurgical, oncological, and functional procedures where millimetric error risks catastrophic neurological deficit. Electromagnetic systems lead current hospital adoption due to lower capital thresholds and flexible line-of-sight requirements, while optical platforms capture premium placements in complex tumor resections where superior accuracy justifies higher per-procedure costs. Robotics-assisted technology represents the fastest-expanding segment as vendors bundle navigation with automated instrument positioning to capture recurring software licensing revenue.
FDA 510(k) pathways and EU MDR conformity assessments shape product development cycles by mandating clinical validation of algorithmic tracking accuracy, while ISO 19401 standards govern electromagnetic compatibility in operating room environments. Japan's PMDA imposes additional language and usability requirements that filter market entrants lacking localized regulatory infrastructure. Stakeholders must monitor evolving reimbursement codes for image-guided surgery across Medicare, German statutory health funds, and Japan's diagnosis procedure combination system to anticipate volume shifts between hospital tiers.
Market Dynamics
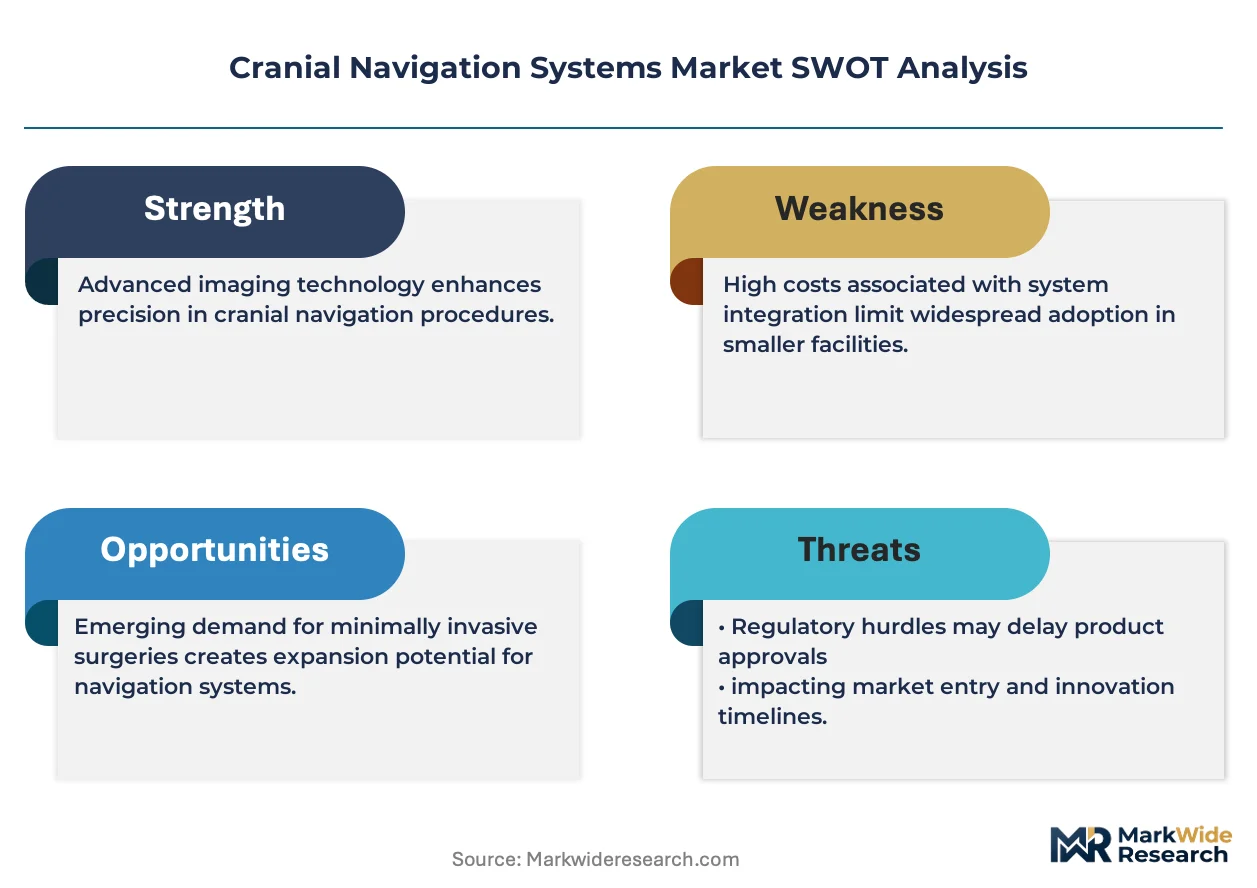
The cranial navigation systems market is bifurcating around accuracy thresholds as hospital procurement committees enforce stricter total cost-of-ownership models that weigh per-procedure disposable costs against capital amortization schedules.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated pathways for software-only updates reduce validation cycles for optical tracking algorithms, enabling faster feature deployment in academic medical centers.
- Japan's diagnosis procedure combination system:Reimbursement codes for image-guided neurosurgery now cover electromagnetic navigation, expanding addressable procedure volumes in tertiary hospitals.
- Hybrid sensor fusion:Combined optical-electromagnetic arrays deliver sub-millimeter accuracy without line-of-sight constraints, capturing placements in functional neurosurgery suites.
Market Restraints
- Optical component supply concentration:German and Japanese precision optics suppliers control infrared camera sensor production, creating input cost volatility for navigation hardware manufacturers.
- EU MDR software validation burden:Extended clinical evidence requirements for algorithmic tracking accuracy delay product launches by 18-24 months versus previous CE marking timelines.
- Fluoroscopy-based intraoperative imaging:Mobile C-arms with integrated navigation software threaten standalone system demand in cost-constrained community hospitals.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Streamed registration for software-as-medical-device creates first-mover advantage in Latin America's underpenetrated neurosurgical equipment market.
- Augmented reality overlay convergence:Integration of heads-up displays with navigation data streams enables hands-free anatomical visualization during tumor resections.
- Remote technical support channels:Cloud-based intraoperative assistance reduces field service engineer density requirements in dispersed geographic markets.
Industry Challenges
- Electromagnetic interference mitigation:Operating rooms with multiple active devices require specialized shielding expertise that strains biomedical engineering departments.
- Legacy PACS integration complexity:DICOM routing between preoperative imaging archives and navigation workstations demands custom interface development for each hospital IT environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Navigation Systems Market |
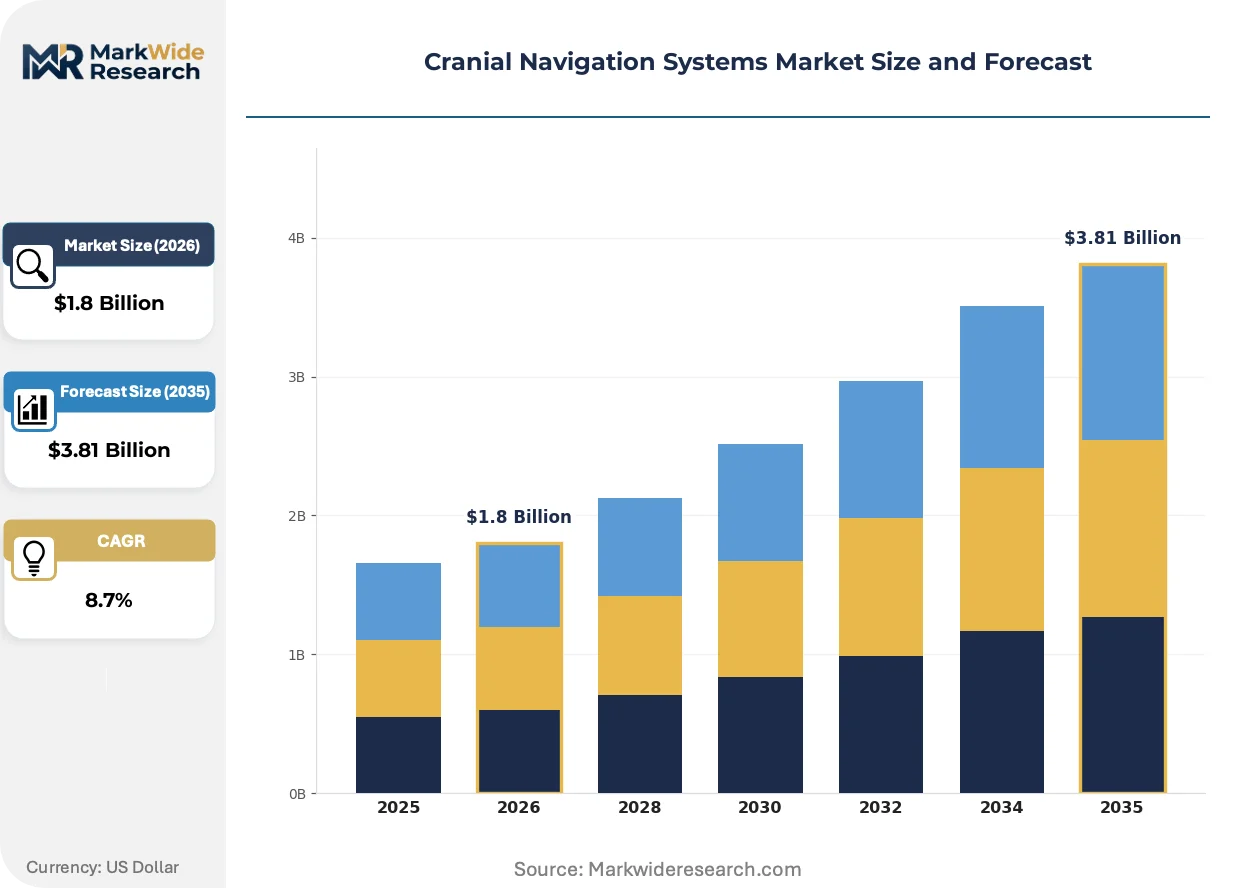
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Electromagnetic Systems, Optical Systems, Hybrid Systems End User: Hospitals, Ambulatory Surgical Centers, Neuro Clinics, Research Institutions Technology: Visualization Technology, Image Guidance, Robotics-Assisted Technology, Navigation Systems Application: Neurosurgery, Oncology, Pain Management, Postoperative Care |
| Companies Covered | GE Healthcare, HRS Navigation, Medtronic, ClaroNav, Zeta Surgical Inc., Stryker, 7D Surgical, Fiagon GmbH, Brainlab AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Navigation Systems Market Emerging Trajectories
Robotics-assisted surgical platforms are compressing the traditional navigation hardware value chain by bundling tracking, positioning, and instrument control into unified capital equipment purchases.
Artificial intelligence-based predictive registration is consolidating preoperative imaging alignment workflows by automating landmark identification that previously required manual surgeon verification. Academic medical centers in Germany and Japan are deploying these algorithms to reduce setup time by eliminating iterative manual adjustments. The technology is consolidating vendor competitive advantage around software architecture rather than sensor hardware specifications.
EU MDR Article 10 clinical evaluation requirements are forcing navigation system manufacturers to generate prospective accuracy validation data for each intended surgical indication. The regulation compresses product development timelines by mandating parallel rather than sequential software and hardware validation. Electromagnetic system vendors face particular burden given the broader range of surgical environments where interference profiles vary.
Hospital procurement committees are unbundling service contracts from initial capital purchases, demanding itemized pricing for software maintenance, hardware warranty, and training separately. This pattern is displacing traditional bundled pricing models that obscured lifetime cost comparisons. The shift is most visible in United States academic medical centers where value analysis committees now mandate total cost-of-ownership spreadsheets across 7-10 year horizons.
Cranial Navigation Systems Market Segmentation
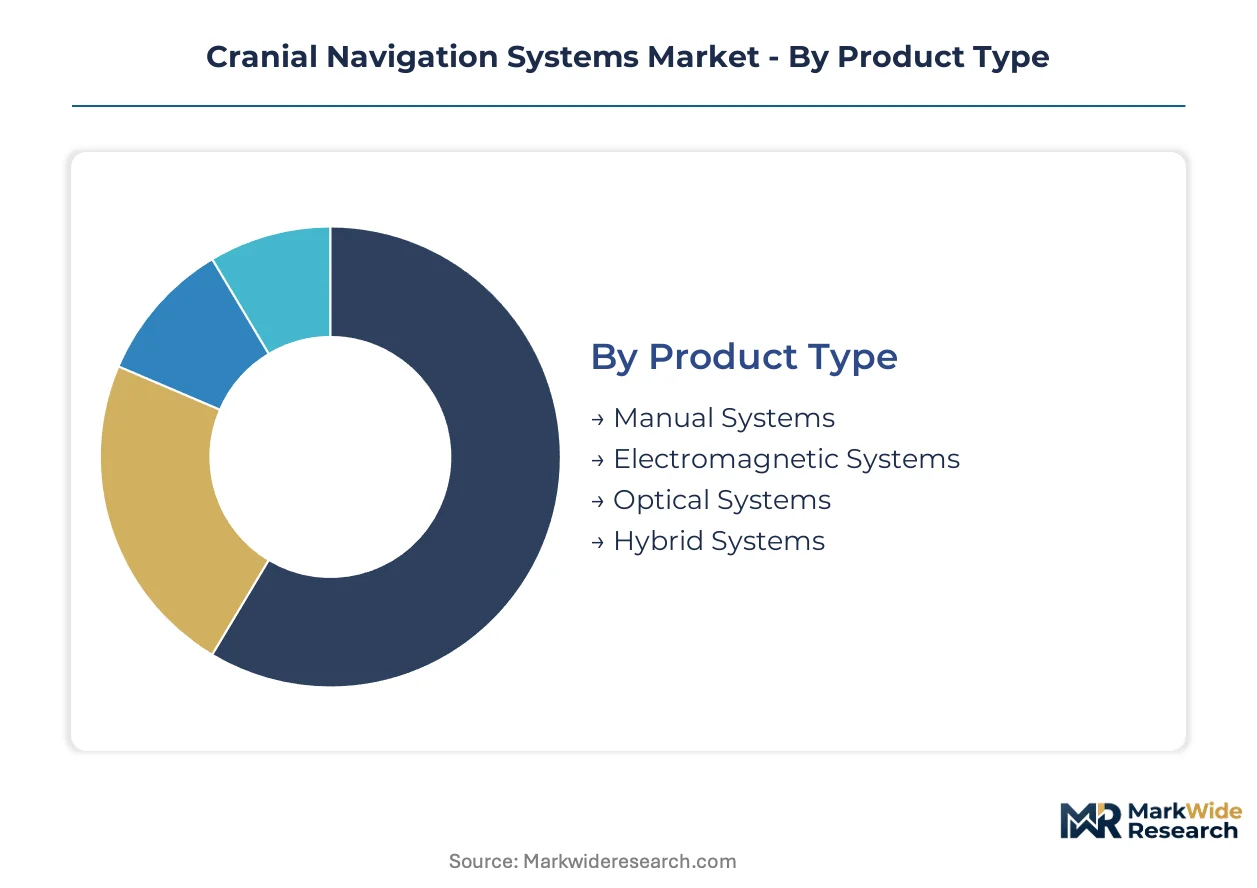
Segmentation in cranial navigation systems reveals how accuracy requirements, capital constraints, and reimbursement structures fragment purchasing behavior across hospital tiers. Procurement committees evaluate technology choices against procedure volumes and total cost-of-ownership horizons.
Product Type:
Volume penetration concentrates in electromagnetic platforms while optical systems command premium placements where sub-millimeter precision justifies higher capital outlays.
- Electromagnetic Systems:These platforms utilize low-frequency magnetic field arrays to track surgical instruments without direct line-of-sight constraints. Demand clusters in community hospitals across the United States and Germany where capital budgets favor lower entry thresholds and flexible OR configurations.
- Optical Systems:Infrared camera arrays paired with reflective marker tracking deliver superior spatial resolution for complex tumor resections. Academic medical centers in Japan and the United States absorb these systems where Medicare and diagnosis procedure combination reimbursements offset per-procedure disposable costs.
- Hybrid Systems:Sensor fusion architectures combining electromagnetic flexibility with optical precision target functional neurosurgery suites requiring both accuracy and maneuverability.
- Manual Systems:Frame-based stereotactic platforms retain niche placement in resource-constrained settings where electromagnetic interference or capital limitations preclude automated tracking.
Today's leader: Electromagnetic Systems. Tomorrow's challenger: Hybrid Systems.
End User:
Procurement authority and reimbursement access determine technology tier allocation across facility types.
- Hospitals:Tertiary centers with neurosurgical departments generate concentrated demand for optical and robotics-assisted platforms where procedure volumes amortize capital investments across high-throughput tumor and functional surgery programs.
- Ambulatory Surgical Centers:These facilities favor electromagnetic systems with streamlined setup protocols and lower disposable costs per case, aligning with Medicare facility fees for outpatient neurosurgical procedures.
- Neuro Clinics:Specialized practices concentrate demand for portable electromagnetic units supporting biopsy and deep brain stimulation programming in office-based settings.
- Research Institutions:Academic laboratories drive early adoption of hybrid sensor arrays and AI-enhanced registration algorithms for clinical validation studies.
Procurement consolidation favors hospitals. Volume expansion targets ambulatory surgical centers.
Technology:
Software architecture differentiation increasingly supersedes hardware specifications as competitive leverage.
- Robotics-Assisted Technology:Automated instrument positioning bundled with navigation tracking commands elevated service contract values. German and Japanese academic centers prioritize these platforms for recurring software licensing revenue models.
- Image Guidance:Preoperative-to-intraoperative image fusion algorithms represent the core value proposition across all system tiers, with FDA 510(k) clearance pathways accelerating deployment of software-only updates.
- Visualization Technology:Heads-up display integration and augmented reality overlays enable hands-free anatomical orientation during tumor resections.
- Navigation Systems:Standalone tracking platforms without robotic positioning retain placement in cost-constrained environments where capital bundling is prohibited.
Revenue concentration: Image Guidance. Steepest expansion trajectory: Robotics-Assisted Technology.
Application:
Clinical indication dictates accuracy requirements and reimbursement eligibility.
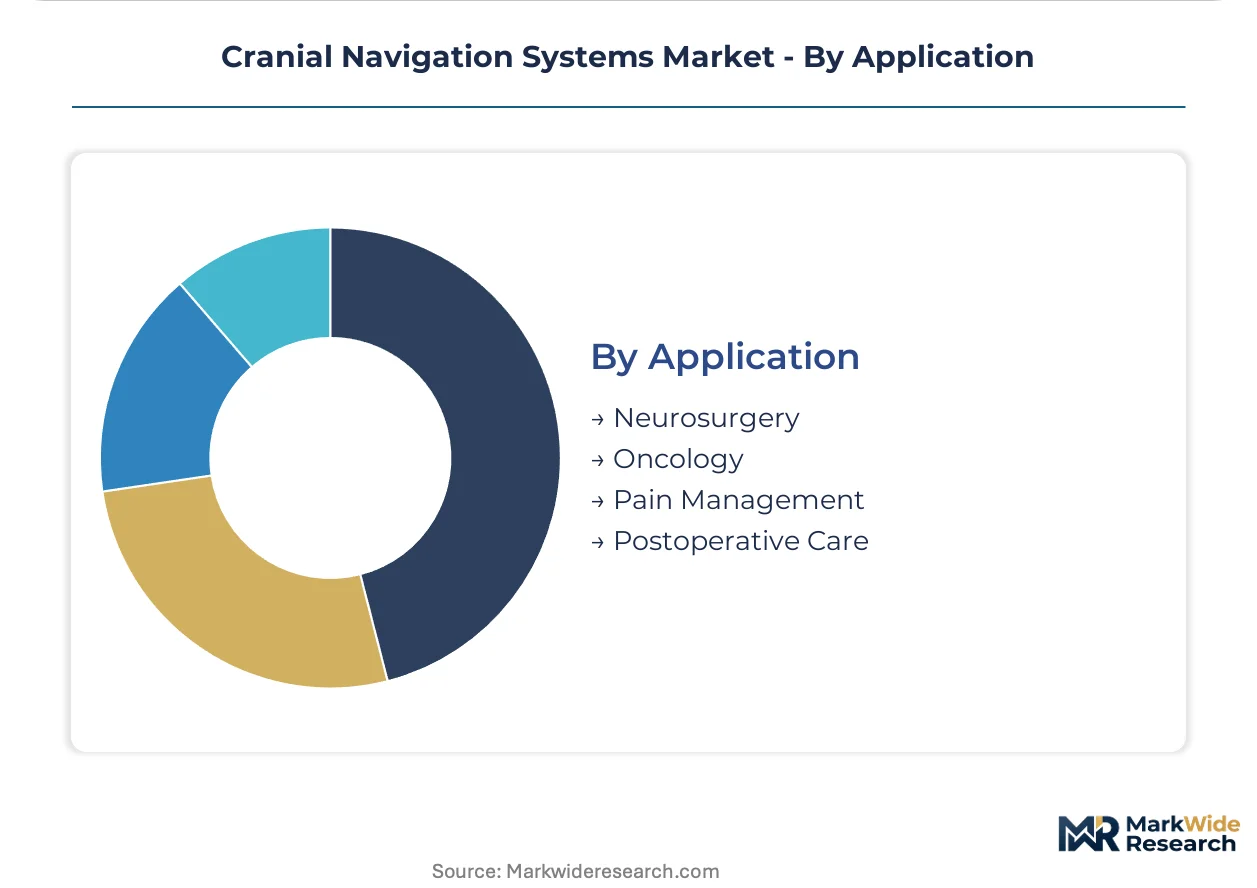
- Neurosurgery:Tumor resections, epilepsy surgery, and vascular procedures drive premium optical system placements where millimetric error risks neurological deficit. Medicare and German statutory health funds maintain established reimbursement codes for image-guided neurosurgical procedures.
- Oncology:Biopsy and ablation procedures in metastatic disease management favor electromagnetic flexibility for rapid multi-target access.
- Pain Management:Spinal cord stimulation lead placement and peripheral nerve targeting utilize lower-cost electromagnetic tracking given reduced accuracy demands.
- Postoperative Care:Hardware explantation and revision surgery generate intermittent demand across all system types.
Revenue anchor: Neurosurgery. Volume growth engine: Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurosurgical specialists cluster in academic medical centers across Germany, Japan, and the United States where reimbursement infrastructure supports capital-intensive navigation platforms. Training pipelines in these markets sustain institutional demand for precision instrumentation.
United States
Medicare facility fees for image-guided neurosurgery drive tertiary hospital procurement of optical and robotics-assisted systems. FDA 510(k) clearance pathways accelerate software-only updates for tracking algorithms. The Cleveland Clinic and Mayo Clinic anchor adoption clusters in Ohio and Minnesota where high-throughput tumor programs amortize capital investments.
Germany
Statutory health fund reimbursement codes cover electromagnetic navigation in university hospitals and community settings alike. EU MDR conformity assessments impose extended clinical evidence requirements that filter market entrants lacking localized regulatory infrastructure. The Berlin-Brandenburg and Bavarian medical technology corridors concentrate vendor field service operations and training centers.
Japan
PMDA imposes additional language and usability requirements that shape product localization strategies. Diagnosis procedure combination reimbursement now covers electromagnetic navigation, expanding addressable volumes in Tokyo and Osaka metropolitan tertiary centers. The Kanto region anchors domestic distribution networks serving high-density neurosurgical departments.
Brazil
ANVISA fast-track pathways for software-as-medical-device create first-mover positioning in Latin America's underpenetrated neurosurgical equipment market. Private hospital chains in São Paulo and Rio de Janeiro pilot electromagnetic platforms for tumor biopsy programs. Southeast regional distributors build technical service capacity to support nascent adoption curves.
United Kingdom
NHS England specialized commissioning frameworks concentrate navigation system placements in designated neuroscience centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining national access pathways. The Greater Manchester and London academic health science networks coordinate multi-site validation studies for hybrid sensor technologies.
Cranial Navigation Systems Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cranial navigation systems market. The vendor base separates into integrated surgical ecosystem providers, software-centric platform developers, and specialized sensor technology firms. Three strategic archetypes dominate: diversified medical technology conglomerates bundling navigation with robotics, pure-play navigation specialists monetizing software licensing, and component suppliers capturing value in precision optics and electromagnetic arrays. Competitive moves concentrate on strategic partnerships for AI-enhanced registration algorithms and geographic expansion through distributor networks in underpenetrated markets.
Among diversified medical technology conglomerates, Medtronic and Stryker occupy positions representing integrated ecosystem strategies that bundle hardware, software, and service contracts. Brainlab AG exemplifies the software-centric archetype with reduced hardware footprint architectures. Zeta Surgical Inc. and 7D Surgical sit within the emerging specialist tier targeting specific procedural niches with streamlined platform configurations.
| Leading Market Players |
|---|
| GE Healthcare |
| HRS Navigation |
| Medtronic |
| ClaroNav |
| Zeta Surgical Inc. |
| Stryker |
| 7D Surgical |
| Fiagon GmbH |
| Brainlab AG |
| Others |
Supply Flow & Price Mechanics
Premium-optical versus commodity-electromagnetic tier divergence hardens procurement committee decisions, compressing margins in the lower tier while infrared camera arrays sustain pricing power through German and Japanese precision optics supply constraints.
Pricing Analysis
Bundled-versus-unbundled service splits now dominate hospital procurement negotiations, with value analysis committees demanding itemized software maintenance, hardware warranty, and training pricing across 7-10 year total cost-of-ownership horizons. Three-tier pricing structure across premium optical, standard hybrid, and economy electromagnetic levels reflects accuracy thresholds and disposable cost burdens. Pricing pressure stems from fluoroscopy-integrated mobile C-arms threatening standalone system demand in cost-constrained community hospitals. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare facility fee limitations, while academic medical centers absorb premium tiers where diagnosis procedure combination reimbursements offset per-procedure costs.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese precision optics suppliers controlling infrared camera sensor production for optical tracking arrays. Hardware manufacturing draws from Taiwan for electromagnetic coil assemblies, Germany for precision optics, and the United States for FDA-validated software processing units. Critical dependencies include rare-earth magnet components, high-resolution CMOS sensors, and validated surgical instrument fiducials. Tariff exposure runs through precision optics import channels from Japan. Distribution runs through direct hospital sales forces for capital equipment, with service contracts managed through regional technical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory validation requirements, with EU MDR Article 10 clinical evidence mandates extending product launch timelines and filtering market entrants lacking localized infrastructure.
For Market Incumbents: Acquire AI-enhanced registration algorithm assets to consolidate software-centric competitive advantage as hardware specifications commoditize. Prioritize backward integration into precision optics supply through exclusive partnerships with German sensor manufacturers. Defend against robotics-assisted platform bundling by unbundling service contracts to penetrate cost-constrained hospital tiers.
For New Entrants and Emerging Players: Begin with Brazil's ANVISA fast-track pathway for software-as-medical-device registration, exploiting underpenetrated Latin American neurosurgical equipment demand. Target electromagnetic platform placements in São Paulo private hospital chains where capital constraints favor lower entry thresholds. Pursue cloud-based remote technical support channels to reduce field service engineer density requirements in dispersed geographic markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed standalone revenue thresholds for pure-play navigation specialists. Long-term viability favors software-centric platforms with recurring licensing revenue over hardware-dependent capital sales. Monitor hybrid sensor fusion adoption curves in German and Japanese functional neurosurgery suites as inflection indicators for technology transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-Only Pathway | Accelerated validation cycles enable faster optical tracking algorithm deployment in academic medical centers. |
| EU MDR Clinical Evidence Investment | Prospective accuracy validation data requirements compress development timelines and filter undercapitalized entrants. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic adoption clusters anchor high-throughput tumor program placements. |
| Software Companion Development | AI-enhanced predictive registration consolidates vendor advantage around architecture rather than sensor specifications. |
| Reimbursement Strategy | Medicare and diagnosis procedure combination code alignment determines volume allocation across hospital tiers. |
Methodological Framework
Multiple input streams — primary interviews with neurosurgeons and hospital purchasing committees, secondary validation through FDA 510(k) filings and CMS reimbursement databases, and trade data analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included biomedical engineering directors, GPO contracts managers, and navigation system field service engineers. Secondary sources encompassed hospital procurement databases, EU MDR conformity assessment records, and Japanese diagnosis procedure combination reimbursement schedules.
Historical volume trajectories were cross-referenced against expert panel inputs to construct projection frameworks across the analysis window. Segmentation dimensions modeled include product type tier, end-user facility category, technology architecture, and application indication. CAGRs were derived from procedure volume elasticity to reimbursement code expansion and capital equipment replacement cycles. Industry-specific inputs incorporated electromagnetic interference mitigation costs and software validation timeline compression under EU MDR.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway modifications and supply chain disruptions from geopolitical trade restrictions. Forecasts reflect documented assumptions regarding reimbursement stability and hospital capital budget allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Diabetic Eye Disease Devices Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Europe Spinal Fusion Devices Market