
 Polycythemia Vera Treatment Market | 2026-2036
Polycythemia Vera Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Polycythemia Vera Treatment Market Analytics
The polycythemia vera treatment landscape is decoupling between premium JAK inhibitor regimens and commodity hydroxyurea protocols. Novartis AG leverages its hematology franchise to anchor premium positioning in interferon-based therapies. Incyte Corporation dominates the JAK inhibitor segment through sustained clinical investment and narrow therapeutic specialization.
Polycythemia vera treatment encompasses pharmacological interventions that modulate myeloproliferative cell signaling, primarily targeting the JAK-STAT pathway with agents such as ruxolitinib or pegylated interferon formulations to reduce thrombotic risk and splenomegaly. The JAK Inhibitors product category leads value generation due to superior cytoreduction efficacy, while the Hospitals end-user segment anchors volume through infusion-dependent administration protocols. The Oral delivery mode segment is expanding fastest as patient preference shifts toward ambulatory management and pharmacy-benefit structures favor self-administration.
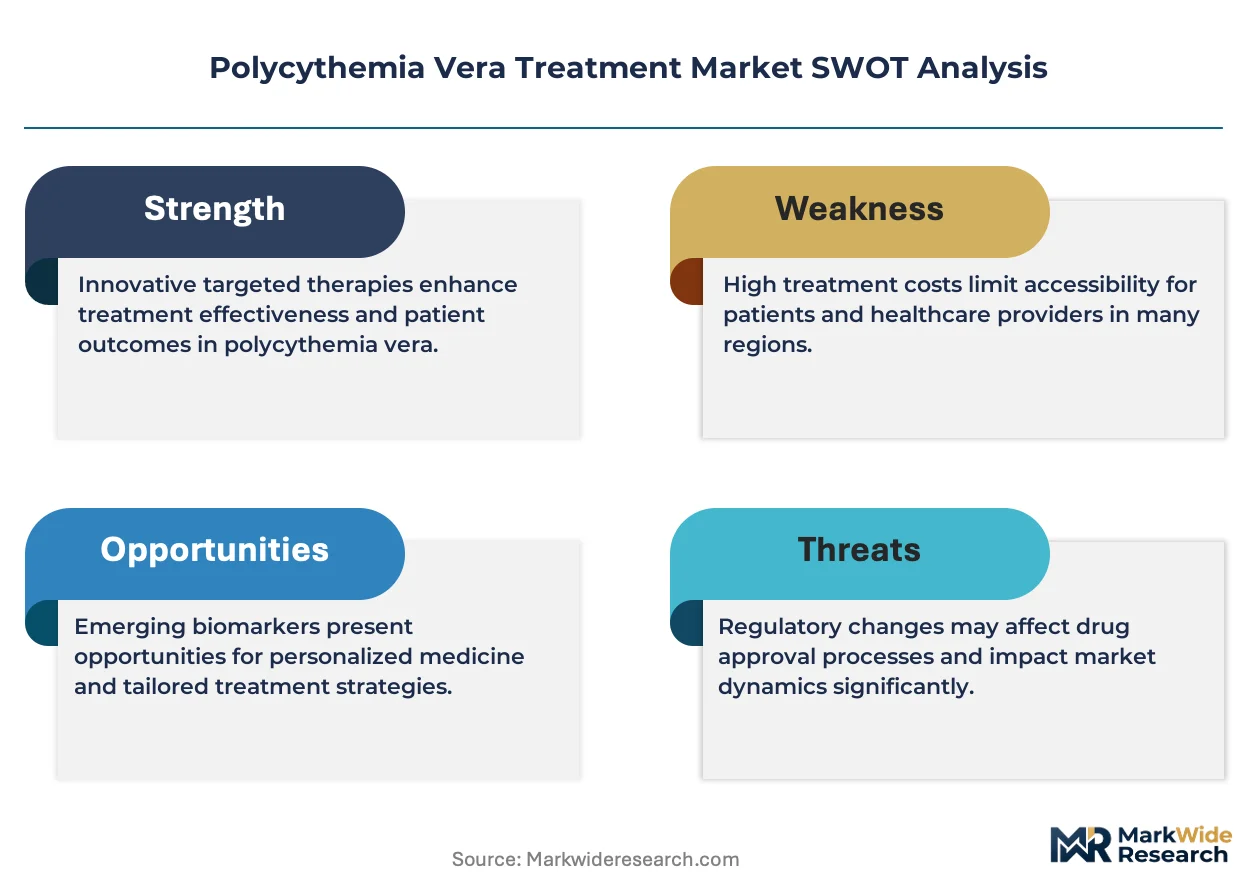
The FDA's orphan drug designation framework and the EMA's PRIME eligibility pathway for hematologic malignancies are accelerating market access for novel myeloproliferative neoplasm therapies. The IRA's Medicare price negotiation provisions are reshaping reimbursement calculus for chronic oral oncology agents in the United States. Stakeholders must monitor evolving biomarker-driven patient stratification criteria that will determine which therapeutic classes capture long-term treatment positioning.
Market Dynamics
The polycythemia vera treatment landscape is bifurcating between premium JAK inhibitor protocols and commodity cytoreductive therapies, driven by Medicare reimbursement compression under the Inflation Reduction Act and hematology clinic consolidation.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's orphan drug designation framework for myeloproliferative neoplasms compresses clinical trial timelines and expands patient access to novel JAK-STAT pathway modulators.
- Hematology Clinic Consolidation:Large academic medical centers in the United States are centralizing myeloproliferative neoplasm care, creating concentrated demand for oral oncology agents with pharmacy-benefit favorable reimbursement.
- Biomarker-Driven Stratification:Next-generation sequencing adoption in hematology practices enables precision patient selection for interferon-based versus JAK inhibitor first-line therapy.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for ruxolitinib and related JAK inhibitors concentrates among contract manufacturers in India and China, exposing sponsors to geopolitical supply disruption.
- Reimbursement Compression:The IRA's Medicare price negotiation provisions directly target chronic oral oncology agents, compressing net pricing power for JAK inhibitor developers.
- Hydroxyurea Substitution:Generic hydroxyurea remains the standard of care in cost-constrained health systems, particularly in Medicaid-dominant U.S. states and emerging markets, limiting premium therapy penetration.
Strategic Opportunities
- Underpenetrated U.S. Community Oncology:Community hematology-oncology practices outside major academic centers represent expansion targets for oral JAK inhibitor therapy, supported by remote patient monitoring integration.
- EMA PRIME Eligibility Acceleration:The European Medicines Agency's priority medicines designation offers expedited assessment pathways for novel myeloproliferative neoplasm therapies entering the European Union.
- Digital Therapeutic Adjuncts:Convergence of pharmacological intervention with digital symptom tracking and thrombotic risk algorithms creates bundled value propositions for payers.
Industry Challenges
- Hematopathologist Workforce Constraints:Accurate polycythemia vera diagnosis and molecular monitoring require specialized hematopathology expertise that concentrates at academic medical centers, creating diagnostic bottlenecks.
- Long-Term Safety Surveillance Infrastructure:Chronic JAK inhibitor therapy mandates robust pharmacovigilance systems to capture secondary malignancy and infectious complication signals, straining smaller sponsor organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycythemia Vera Treatment Market |
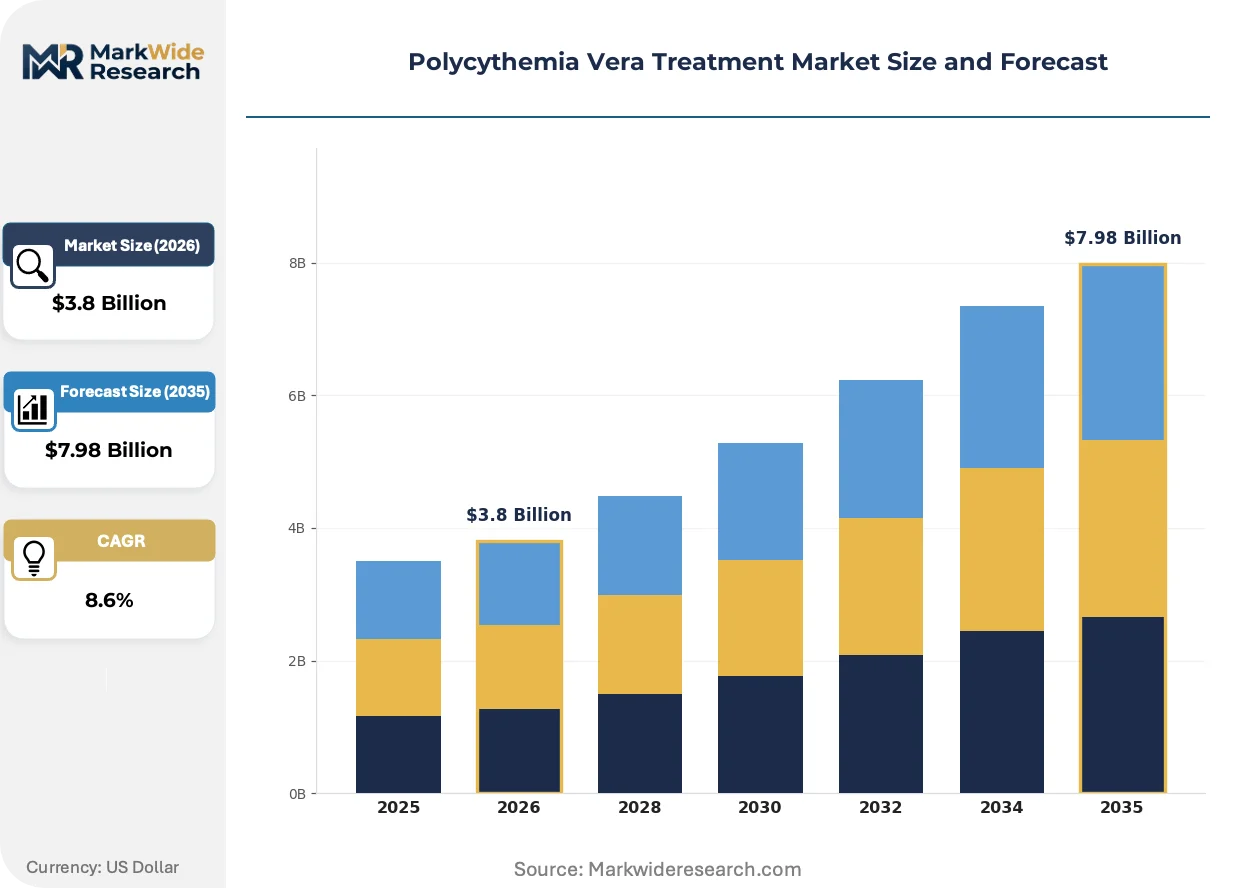
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxyurea, Interferon Alpha, JAK Inhibitors, Busulfan End User: Hospitals, Clinics, Homecare, Diagnostic Laboratories Therapy Area: Oncology, Hematology, Palliative Care, Preventive Care Delivery Mode: Oral, Injectable, Subcutaneous, Intravenous |
| Companies Covered | Novartis AG, Incyte Corporation, Bristol-Myers Squibb Company, Roche Holding AG, AbbVie Inc., Protagonist Therapeutics, PharmaEssentia Corporation, Pfizer Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycythemia Vera Treatment Market Evolving Landscape
Myeloproliferative neoplasm therapeutics are converging around precision medicine architectures, with regulatory frameworks and reimbursement models co-evolving to reward biomarker-validated treatment selection.
Next-generation JAK inhibitors with expanded selectivity profiles are unifying cytoreduction and symptom management into single-agent protocols. Hematology clinics at academic medical centers are adopting these agents rapidly, displacing sequential hydroxyurea-to-JAK inhibitor treatment algorithms. This unification compresses the addressable patient pool for combination therapy developers while elevating the competitive bar for first-line positioning.
The EMA's PRIME eligibility pathway for hematologic malignancies is accelerating market access timelines for novel myeloproliferative neoplasm therapies in the European Union. Sponsors receiving PRIME designation gain enhanced scientific advice and accelerated assessment, compressing the gap between pivotal trial completion and reimbursement attainment. This regulatory tailwind particularly benefits interferon-based and JAK inhibitor programs targeting treatment-naïve patient segments.
Patient preference for ambulatory management is reshaping distribution channel selection in the United States. Oral oncology agents with pharmacy-benefit coverage are displacing infusion-dependent protocols in Medicare Advantage plans, with specialty pharmacies capturing dispensing volume previously held by hospital outpatient departments. This channel rotation is most visible in Florida and Texas, where Medicare Advantage penetration exceeds national averages and hematology clinic networks prioritize pharmacy-benefit-aligned formularies.
Polycythemia Vera Treatment Market Segmentation
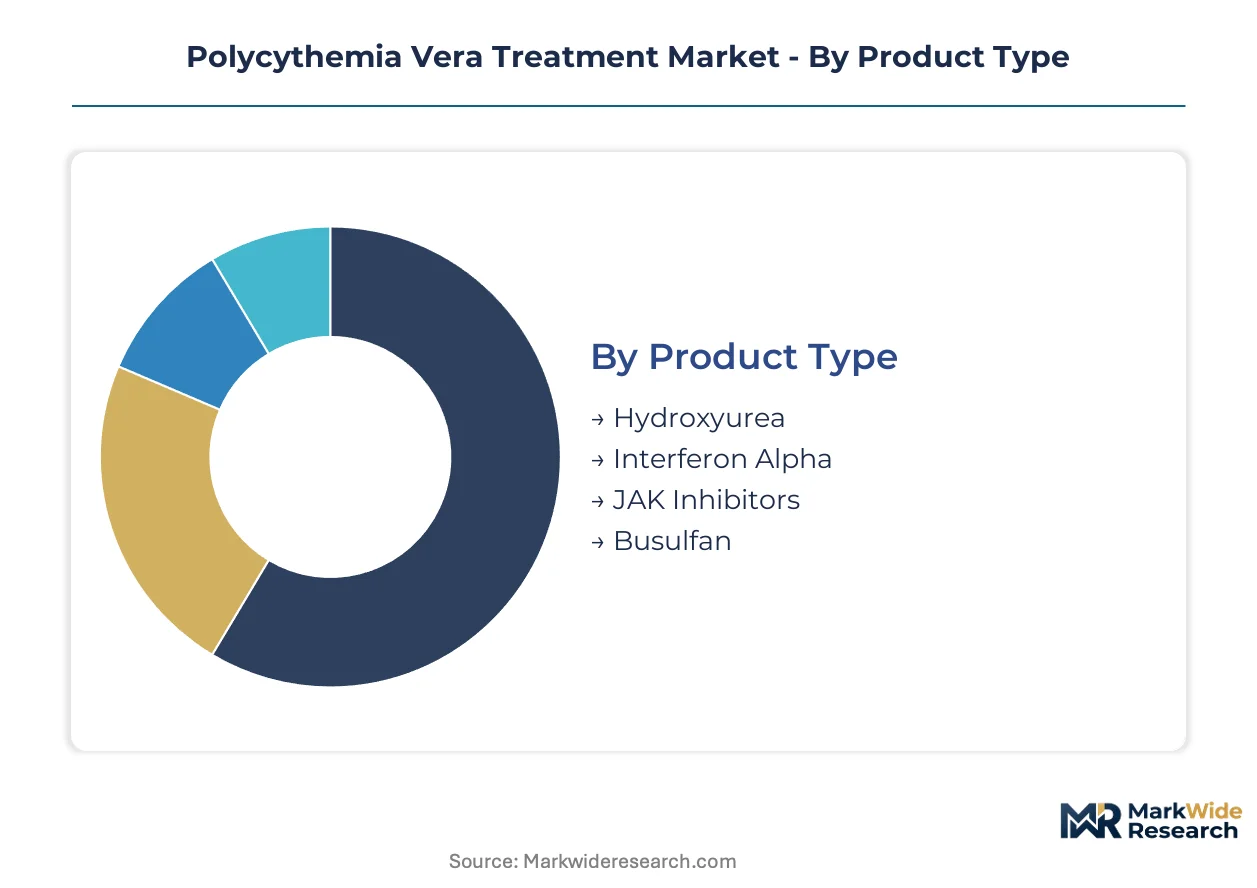
Polycythemia vera treatment segmentation reflects divergent clinical economics between premium targeted therapies and commodity cytoreductive protocols. Reimbursement mechanics and site-of-care policies determine which delivery modes and end-user channels capture patient volume.
Product Type:
Treatment selection pivots on thrombotic risk stratification and cytoreduction urgency, with cost tiers separating first-line from salvage protocols.
- JAK Inhibitors:Small-molecule agents such as ruxolitinib modulate the JAK-STAT signaling cascade to reduce splenomegaly and symptom burden. Demand concentrates at academic hematology centers in the United States where Medicare Advantage pharmacy-benefit structures favor oral oncology agents over infusion-dependent alternatives.
- Interferon Alpha:Pegylated formulations induce durable molecular responses in younger, treatment-naïve patients with low-risk disease profiles. European adoption is accelerating under EMA PRIME eligibility pathways that compress assessment timelines for interferon-based myeloproliferative neoplasm programs.
- Hydroxyurea:Generic cytoreductive agent remains the cost-constrained standard across Medicaid-dominant U.S. states and emerging markets.
- Busulfan:Alkylating agent reserved for refractory cases with aggressive disease progression requiring rapid hematologic control.
JAK Inhibitors leads on scale; Interferon Alpha leads on momentum.
End User:
Site-of-care migration is reshaping channel economics as oral therapy diffusion enables ambulatory displacement of hospital-based administration.
- Hospitals:Academic medical centers anchor complex myeloproliferative neoplasm care, managing high-risk patients requiring therapeutic phlebotomy and cytoreductive monitoring. Florida and Texas health systems concentrate volume through Medicare Advantage network contracts that retain infusion-dependent cases.
- Clinics:Community hematology-oncology practices are expanding oral JAK inhibitor prescribing supported by remote patient monitoring integration and specialty pharmacy dispensing partnerships.
- Homecare:Subcutaneous interferon administration and oral JAK inhibitor regimens shift monitoring burden to home nursing and telemedicine platforms.
- Diagnostic Laboratories:Molecular testing facilities enable JAK2 V617F mutation confirmation and treatment response monitoring.
Hospitals dominates current volume; Clinics shows the steepest expansion trajectory.
Therapy Area:
Clinical specialization depth determines protocol selection, with hematology expertise concentrating at tertiary referral centers.
- Hematology:Dedicated myeloproliferative neoplasm programs at centers such as MD Anderson and Memorial Sloan Kettering drive adoption of biomarker-stratified first-line therapy. Workforce constraints limit accurate diagnosis and molecular monitoring to specialized hematopathology services.
- Oncology:General oncology practices manage stable patients on maintenance cytoreduction, referring complex cases to academic centers.
- Palliative Care:Symptom-focused management for advanced disease addresses pruritus, fatigue, and microvascular complications.
- Preventive Care:Thrombotic risk reduction protocols target cardiovascular event prevention in low-risk patient cohorts.
Hematology anchors premium therapy adoption; Oncology captures maintenance volume.
Delivery Mode:
Administration route determines reimbursement channel alignment and patient preference for ambulatory versus facility-based care.
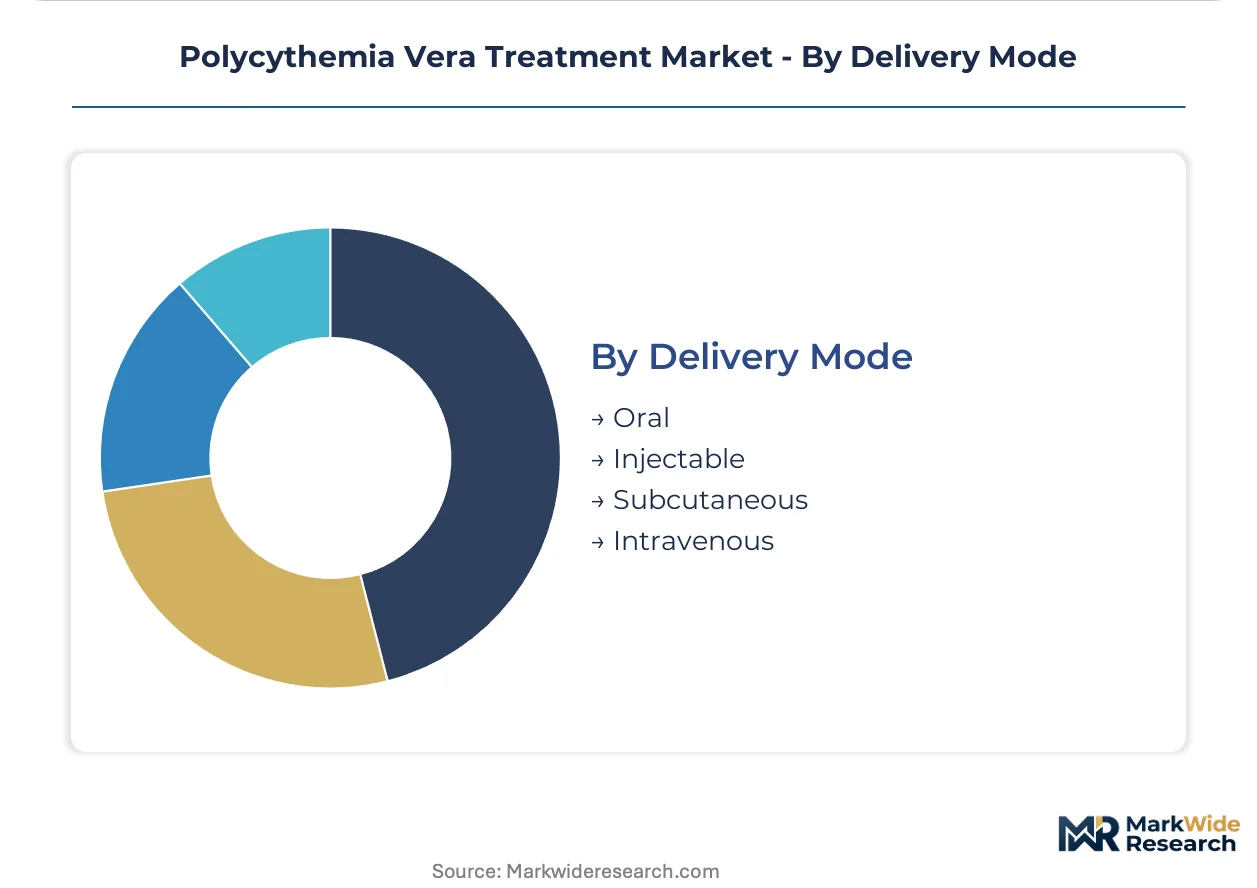
- Oral:Ruxolitinib and hydroxyurea tablets enable self-administration with pharmacy-benefit coverage displacing hospital outpatient department billing. Medicare Advantage penetration in Sun Belt states accelerates this channel rotation.
- Subcutaneous:Pegylated interferon formulations balance efficacy with reduced injection frequency, supporting home administration.
- Injectable:Parenteral cytoreductive agents require clinical monitoring for myelosuppression.
- Intravenous:Hospital-based infusion for acute cytoreduction or salvage therapy in rapidly progressive disease.
Oral delivery is gaining share fastest; Intravenous retains acute-care necessity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hematopathologist talent concentrates at academic medical centers in the United States, Germany, and Switzerland, anchoring premium therapy adoption and molecular diagnostics capacity for myeloproliferative neoplasm care.
United States
Medicare Advantage penetration in Florida and Texas drives pharmacy-benefit-aligned oral oncology dispensing. The IRA's price negotiation provisions compress net pricing for chronic JAK inhibitors. MD Anderson and Memorial Sloan Kettering anchor biomarker-driven patient stratification protocols.
Germany
Community hematology networks in North Rhine-Westphalia expand interferon-based first-line therapy for low-risk patients. EMA PRIME eligibility accelerates assessment timelines for novel myeloproliferative neoplasm programs. Heidelberg and Munich academic centers concentrate molecular monitoring infrastructure.
Switzerland
Basel-region pharmaceutical R&D clusters support interferon formulation development and hematology franchise expansion. Swissmedic maintains alignment with EMA accelerated pathways for orphan hematologic indications. Roche's presence anchors diagnostic-test integration with therapeutic protocols.
Japan
PMDA's sakigake designation system compresses review timelines for JAK inhibitor submissions in Tokyo and Osaka metropolitan treatment centers. Aging demographics elevate thrombotic risk management urgency. National health insurance reimbursement favors oral agents with demonstrated cardiovascular outcome benefits.
United Kingdom
NHS England's specialized commissioning framework concentrates myeloproliferative neoplasm care at London, Manchester, and Birmingham hematology centers. NICE technology appraisals determine JAK inhibitor access thresholds. Academic partnerships in Cambridge and Oxford advance next-generation sequencing adoption for patient selection.
Polycythemia Vera Treatment Market Competitive Landscape
Top-tier vendors anchor the JAK inhibitor segment, while mid-cap specialists and generic manufacturers occupy commodity cytoreductive tiers. Market structure reflects therapeutic class concentration rather than fragmented vendor dispersion. Swiss and U.S.-based pharmaceutical conglomerates exemplify hematology franchise builders, while Taiwan- and U.S.-based biotech specialists represent narrow therapeutic focus strategies. Competitive moves center on regulatory pathway acceleration and biomarker companion diagnostic integration.
Within the JAK inhibitor tier, Incyte Corporation and Novartis AG exemplify contrasting archetypes: the former represents narrow therapeutic specialization sustained by clinical investment density, while the latter anchors portfolio diversification across interferon-based and targeted therapy modalities. Bristol-Myers Squibb Company occupies a position bridging oncology franchise breadth with hematology-specific development capabilities. These three entities collectively illustrate how regulatory science expertise and reimbursement navigation capabilities determine competitive positioning in Medicare- and EMA-governed markets.
| Leading Market Players |
|---|
| Novartis AG |
| Incyte Corporation |
| Bristol-Myers Squibb Company |
| Roche Holding AG |
| AbbVie Inc. |
| Protagonist Therapeutics |
| PharmaEssentia Corporation |
| Pfizer Inc. |
| Amgen Inc. |
| Others |
Value Network & Pricing Analysis
Academic medical center procurement concentration in the United States anchors premium JAK inhibitor pricing through pharmacy-benefit structures, while Medicare Advantage formularies in Florida and Texas enforce tiered access controls that stratify reimbursement across oral oncology tiers.
Pricing Analysis
Bundled service packaging at hospital outpatient departments competes with unbundled pharmacy-benefit dispensing through specialty pharmacies, creating channel-dependent price variation. Price differentiation hinges on therapeutic line positioning and molecular biomarker status, with first-line JAK inhibitor protocols commanding premium access versus salvage hydroxyurea substitution. Cost compression in Medicaid-dominant U.S. states intensifies as generic cytoreductive protocols displace branded alternatives. Community oncology practices exhibit highest price sensitivity; academic centers with dedicated myeloproliferative neoplasm programs demonstrate lowest sensitivity due to protocol standardization.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical sector and China's active pharmaceutical ingredient localization policies are reshaping global sourcing patterns for JAK inhibitor manufacturing. API production concentrates in India, China, and Switzerland, with ruxolitinib intermediates drawing from specialized chemical synthesis clusters. Supply chain vulnerability rests on single-source contract manufacturing dependencies for high-potency oncology compounds. Distribution runs through specialty pharmacy networks in the United States and hospital procurement consortia in Germany and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycythemia vera treatment market functions as a stable compounder, with chronic disease prevalence and sustained Medicare reimbursement anchoring predictable revenue streams across therapeutic classes.
For Market Incumbents: To counter IRA-driven Medicare price negotiation compression, deepen formulary access through biomarker companion diagnostic integration and expand manufacturing capacity in Switzerland to diversify API sourcing beyond Asian contract manufacturers. For New Entrants and Emerging Players: Launch via remote patient monitoring partnerships targeting underpenetrated U.S. community hematology practices outside major academic centers, leveraging telemedicine platforms to displace hospital-based infusion protocols with oral JAK inhibitor regimens. For Investors and Strategic Acquirers: Large-cap hematology franchise builders are the most active acquirer in this space, consolidating narrow-therapeutic-focus biotech specialists with late-stage interferon or next-generation JAK inhibitor pipelines. Acquisition targets should demonstrate EMA PRIME eligibility or FDA orphan drug designation traction. The signal to watch is biomarker-driven patient stratification protocol adoption rates at U.S. News-ranked cancer centers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated FDA pathways for myeloproliferative neoplasm indications compress development timelines for JAK-STAT modulators. |
| Regulatory Approval Pathway | EMA PRIME eligibility designation expedites assessment timelines for interferon-based therapies entering European markets. |
| Licensing Agreement | Companion diagnostic partnerships with Roche anchor biomarker-validated patient selection for premium therapy positioning. |
| Manufacturing Scale-Up | API production expansion in Swiss and German chemical clusters reduces geopolitical exposure to Asian supply concentration. |
| Pipeline Diversification | Next-generation selective JAK inhibitor programs target treatment-naïve patient segments with cytoreduction-symptom unification. |
Research Methodology
Multiple input streams — hematologist interviews, payer formulary analysis, regulatory filing review, and supply chain documentation — were reconciled through bottom-up prescription volume modeling and top-down revenue triangulation. Primary discussions engaged drug development executives at JAK inhibitor sponsors, regulatory affairs leads navigating FDA orphan drug pathways, formulary directors at Medicare Advantage plans, hospital procurement managers at NCI-designated cancer centers, and payer access specialists. Secondary validation drew from FDA approval databases, EMA PRIME designation records, ClinicalTrials.gov myeloproliferative neoplasm protocols, CMS Medicare Part D claims patterns, and hospital 340B drug pricing program disclosures.
Historical prescription trajectories were cross-referenced against expert panel input on reimbursement evolution and therapeutic class substitution dynamics. Segmentation modeling encompassed product type, delivery mode, end-user channel, therapy area specialization, and regional regulatory cluster. CAGRs were derived through log-linear trend fitting adjusted for policy inflection points. Forecast inputs incorporated JAK2 V617F mutation prevalence epidemiology, Medicare Advantage penetration projections, and hematopathologist workforce supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IRA price negotiation implementation speed, geopolitical API supply disruption, and next-generation JAK inhibitor clinical readout timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hematology Analyzers Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Bone Marrow Transplant Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Apheresis Market
Hematology
Venous Blood Collection Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Polycythemia Vera Market
Hematology
Malignant Lymphoma Market
Hematology
Blood Screening Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Non-Hodgkin Lymphoma Treatment Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Febrile Neutropenia Market
Hematology
Small Lymphocytic Lymphoma Market