
 Ophthalmic Microscopes Market | 2026-2036
Ophthalmic Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Microscopes Market Analytics
Multi-source component procurement is realigning how ophthalmic microscope manufacturers manage optical supply chains. Carl Zeiss Meditec AG leverages captive lens grinding capabilities to sustain margin control across premium surgical platforms. Alcon Inc. competes through integrated phacoemulsification-microscope consoles that dominate hospital purchasing committees. Leica Microsystems anchors its position in academic medical centers with modular teaching configurations.
An ophthalmic microscope is a precision optical instrument employing apochromatic objectives, coaxial illumination, and motorized zoom systems to magnify ocular structures during diagnostic examination and microsurgical intervention. Surgical microscopes command the largest installed base, though digital microscopy segments are recording the fastest replacement cycles as hospitals integrate 4K camera heads and heads-up display systems for anterior segment procedures. Fluorescence microscopy technology concentrates margin pools in vitreoretinal applications where indocyanine green angiography modules justify premium pricing.
FDA 510(k) pathways govern optical coherence tomography-integrated microscope platforms in the United States, while the EU Medical Device Regulation mandates clinical evidence packages for Class IIa surgical microscopes entering European markets. ISO 10993 biocompatibility standards constrain material selection for sterilizable microscope components, particularly in reusable ocular contact lenses and draping systems. Stakeholders must monitor how software-as-medical-device classifications reshape regulatory burdens for AI-assisted focusing and image analysis modules.
Market Dynamics
Multi-modal imaging convergence is compressing replacement cycles as hospitals consolidate capital equipment budgets around platforms combining surgical microscopy with intraoperative optical coherence tomography. This technology shift is redrawing competitive boundaries between standalone microscope manufacturers and integrated diagnostic-surgical system vendors.
Growth Catalysts
- FDA 510(k) pathway streamlining:The abbreviated clearance process for OCT-integrated microscopes is accelerating commercialization timelines for multi-functional surgical platforms in the United States.
- University hospital procurement concentration:German academic medical centers are anchoring demand for fluorescence-guided surgical microscopes with indocyanine green angiography modules for vitreoretinal procedures.
- 4K camera head adoption:Heads-up display systems for anterior segment surgery are driving digital microscopy replacement cycles as surgical suites upgrade visualization infrastructure.
Market Restraints
- Apochromatic objective supply concentration:Precision lens grinding capabilities concentrate among a handful of European and Japanese optical specialists, creating input bottlenecks for premium surgical platforms.
- EU MDR clinical evidence requirements:Class IIa surgical microscopes now demand expanded biocompatibility documentation under ISO 10993, extending time-to-market for sterilizable components.
- Software-as-medical-device reclassification:AI-assisted focusing modules face evolving regulatory scrutiny that threatens to fragment compliance pathways across jurisdictions.
Strategic Opportunities
- Modular teaching configurations:Academic medical centers in Germany and Switzerland are requesting customizable microscope architectures that support resident training workflows and multi-surgeon observation.
- Phacoemulsification-microscope console integration:Hospital purchasing committees are consolidating vendor relationships around single-platform cataract surgery systems that reduce operating room footprint.
- Dual carbon alignment:Chinese hospital procurement is beginning to weight energy-efficient LED illumination systems in tender evaluations under national sustainability mandates.
Industry Challenges
- Coaxial illumination calibration expertise:Field service engineer shortages are extending installation timelines and degrading first-case success rates for motorized zoom system deployments.
- Reusable draping system validation:Sterilization cycle documentation for ocular contact lenses is creating certification backlogs that delay equipment commissioning in multi-site health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Microscopes Market |
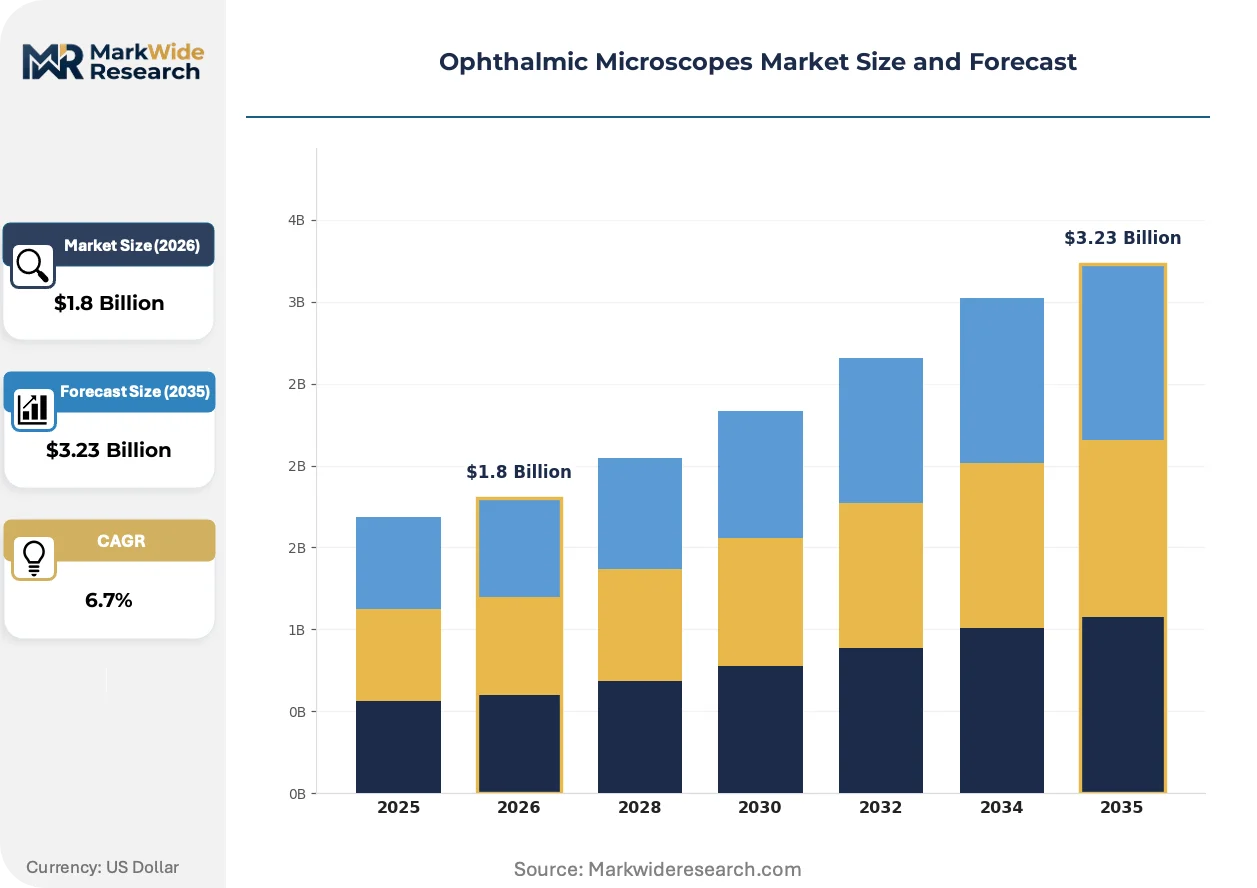
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Microscopes, Surgical Microscopes, Teaching Microscopes, Portable Microscopes End User: Hospitals, Clinics, Research Laboratories, Educational Institutions Application: Cataract Surgery, Retinal Surgery, Optical Coherence Tomography, Fundus Examination Technology: Optical Microscopy, Confocal Microscopy, Fluorescence Microscopy, Electrical Microscopy |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Leica Microsystems, Topcon Corporation, Haag-Streit Holding, Takagi Seiko Co., Ltd., Inami & Co., Ltd., Karl Kaps GmbH & Co. KG, Seiler Instrument Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Microscopes Market Evolving Landscape
Digital visualization layers are displacing conventional eyepiece-dependent workflows as surgical teams demand immersive display environments. This transformation is reordering R&D priorities across the installed base.
Intraoperative optical coherence tomography is integrating directly into surgical microscope platforms, enabling real-time cross-sectional tissue visualization during membrane peeling and subretinal injection procedures. Vitreoretinal surgeons in academic centers are adopting these systems at accelerated replacement cycles compared to anterior segment counterparts. The technology is integrating diagnostic and therapeutic workflows into unified capital equipment purchases that compress standalone microscope demand.
The EU Medical Device Regulation is mandating clinical evidence packages for Class IIa surgical microscopes that exceed predecessor Medical Device Directive requirements. Manufacturers must now submit expanded biocompatibility studies for sterilizable components including reusable ocular contact lenses. European market entry timelines for new fluorescence microscopy modules are extending as notified bodies apply heightened scrutiny to indocyanine green angiography system safety profiles.
Hospital purchasing committees are consolidating capital equipment decisions around integrated phacoemulsification-microscope consoles that reduce vendor management complexity. This concentration is displacing standalone microscope procurement in cataract surgery suites across Germany, Japan, and the United States. Academic medical centers remain the exception, where modular teaching configurations preserve demand for flexible surgical microscopy platforms with multi-observer capabilities.
Ophthalmic Microscopes Market Segmentation
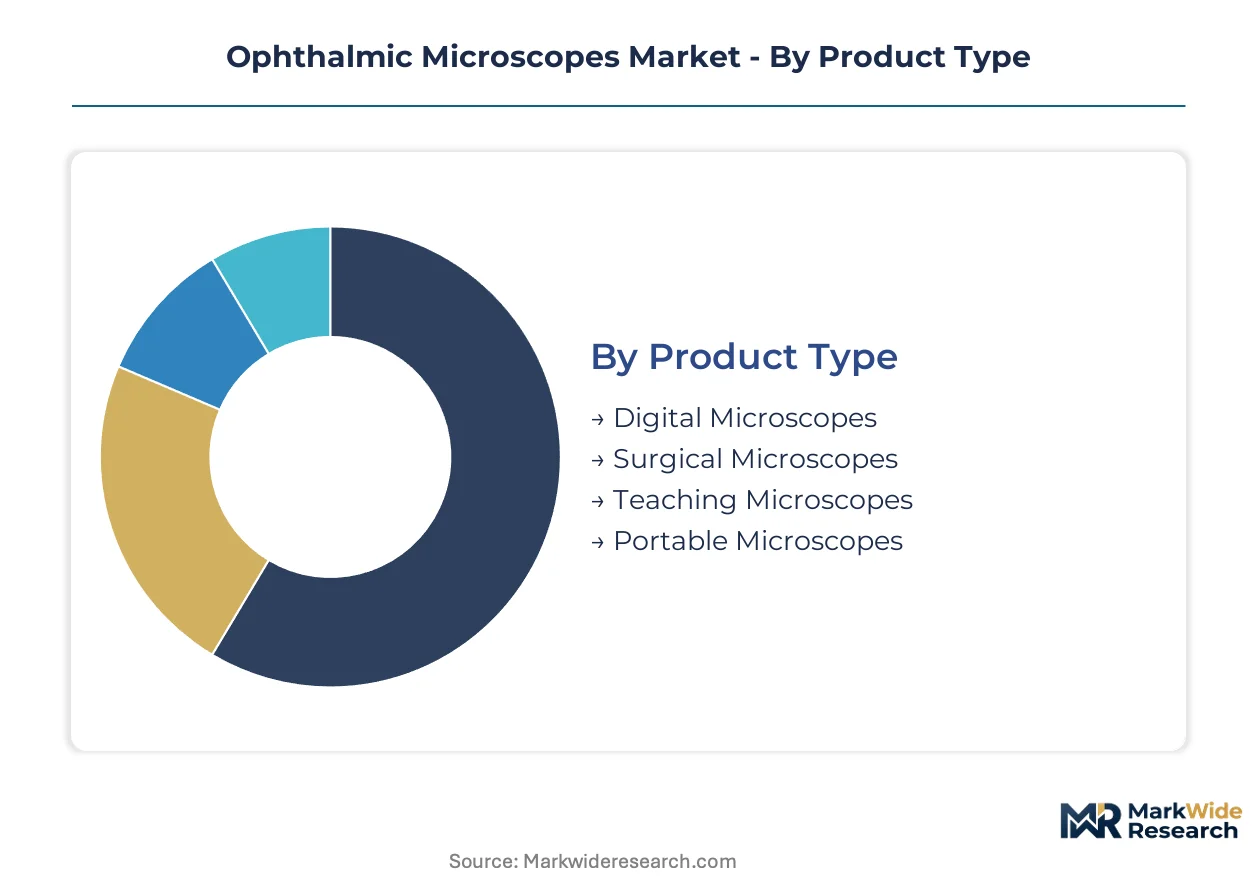
Segmentation in ophthalmic microscopes reveals divergent procurement logics across surgical suites, academic centers, and diagnostic workflows. Buyers prioritize integration depth, teaching modularity, or portability depending on capital budget cycles and procedure mix.
Product Type:
Hospital purchasing committees differentiate platforms by replacement urgency and interoperability requirements rather than optical specifications alone.
- Surgical Microscopes:These platforms deploy apochromatic objectives with coaxial illumination and motorized zoom for anterior and posterior segment procedures. German university hospitals anchor procurement of fluorescence-guided configurations with indocyanine green angiography modules for vitreoretinal surgery.
- Digital Microscopes:Systems integrate 4K camera heads and heads-up displays that eliminate eyepiece dependency during cataract extraction. Replacement cycles are compressing as surgical suites upgrade visualization infrastructure to support immersive display environments.
- Teaching Microscopes:Modular architectures accommodate multi-surgeon observation and resident training workflows in academic medical centers.
- Portable Microscopes:Compact designs serve outreach screening programs and mobile diagnostic units with reduced optical complexity.
Surgical Microscopes lead volumes today; Digital Microscopes are gaining share fastest.
End User:
Procurement authority concentrates differently across facility types, with integrated delivery networks centralizing decisions while academic centers preserve departmental autonomy.
- Hospitals:Surgical suites in Germany and Japan dominate procurement of multi-modal platforms combining microscopy with intraoperative optical coherence tomography. Consolidated capital budgets favor integrated phacoemulsification-microscope consoles that reduce vendor management complexity.
- Clinics:Outpatient ophthalmology practices prioritize standalone digital microscopy for anterior segment diagnostics with lower capital thresholds.
- Research Laboratories:Facilities demand fluorescence microscopy with specialized filter sets for experimental ocular imaging protocols.
- Educational Institutions:Medical schools in Switzerland request customizable microscope architectures that support structured resident training curricula.
Hospitals command the largest installed base; Clinics show the steepest expansion trajectory among outpatient settings.
Application:
Procedure-specific visualization requirements drive divergent technology attachments and software module configurations.
- Cataract Surgery:Phacoemulsification-microscope console integration dominates hospital purchasing committee decisions, compressing demand for standalone surgical microscopy platforms across Germany, Japan, and the United States.
- Retinal Surgery:Vitreoretinal specialists in academic centers adopt intraoperative optical coherence tomography integration at accelerated replacement cycles for membrane peeling and subretinal injection procedures.
- Optical Coherence Tomography:Diagnostic modules attach to surgical platforms for real-time cross-sectional tissue visualization during intervention.
- Fundus Examination:Standard slit-lamp microscopy serves routine posterior pole assessment in primary care ophthalmology settings.
Cataract Surgery anchors current procurement volumes; Retinal Surgery applications are climbing the fastest as OCT integration penetrates vitreoretinal practice.
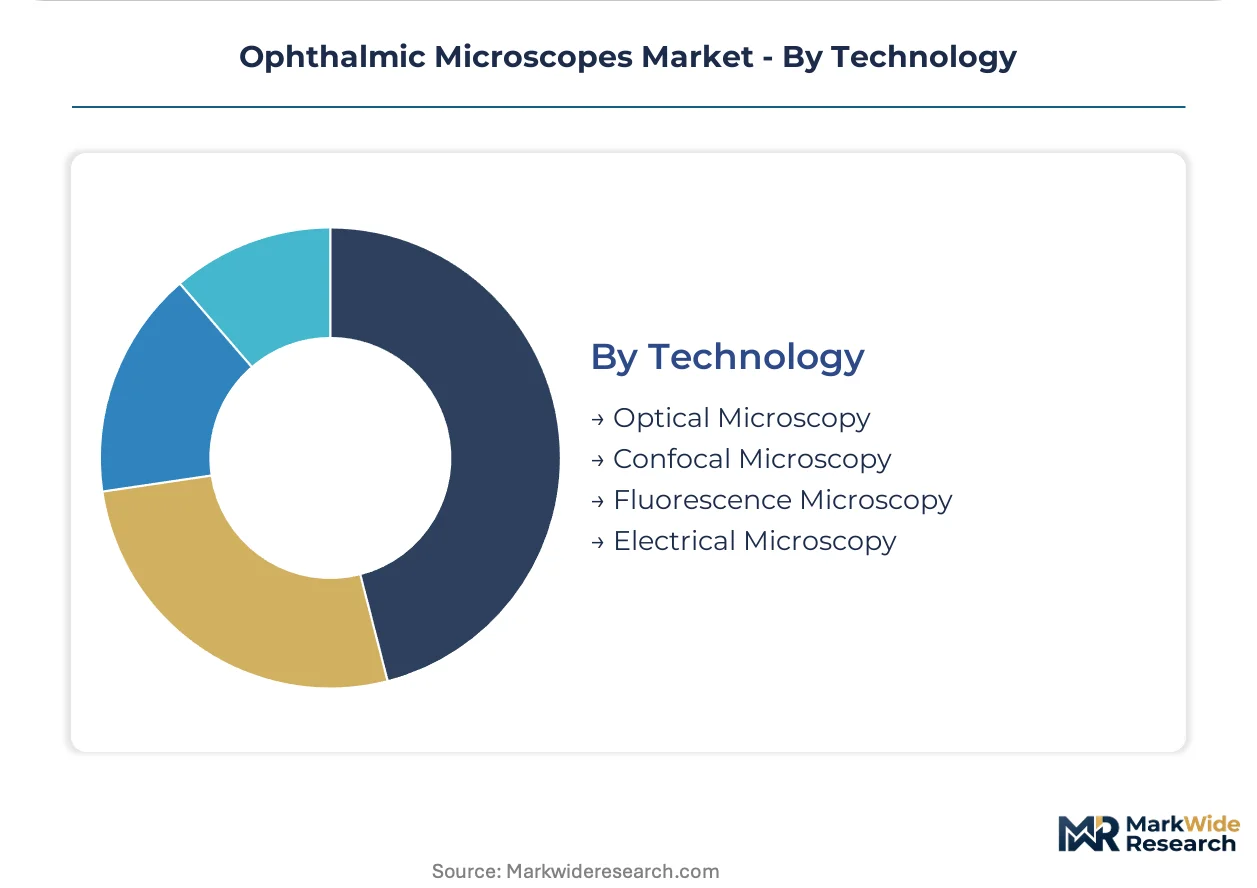
Technology:
Optical sophistication levels separate premium surgical platforms from diagnostic and research instruments.
- Optical Microscopy:Conventional apochromatic systems with coaxial illumination remain the workhorse for anterior segment surgery, though margins compress as digital overlays displace eyepiece-dependent workflows.
- Fluorescence Microscopy:Indocyanine green angiography modules concentrate margin pools in vitreoretinal applications where real-time vascular visualization justifies premium pricing in German academic centers.
- Confocal Microscopy:Specialized configurations serve corneal imaging and research applications with optical sectioning capabilities.
- Electrical Microscopy:Electron beam systems support ultrastructural research in ocular tissue pathology laboratories.
Optical Microscopy retains the dominant installed position; Fluorescence Microscopy commands the steepest pricing tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor procurement concentration for fluorescence-guided surgical microscopes, while regulatory divergence across major markets is fragmenting time-to-market strategies for multi-modal platforms.
Germany
University hospitals in Heidelberg and Tübingen drive demand for indocyanine green angiography modules in vitreoretinal surgery suites. The EU Medical Device Regulation mandates expanded clinical evidence packages for Class IIa surgical microscopes entering European markets. The Baden-Württemberg medical technology corridor concentrates fluorescence microscopy R&D and manufacturing capabilities.
United States
Hospital purchasing committees consolidate capital budgets around integrated phacoemulsification-microscope consoles for cataract surgery workflows. FDA 510(k) pathways govern optical coherence tomography-integrated microscope platforms, accelerating commercialization timelines for multi-functional surgical systems. The Boston-Cambridge cluster anchors academic medical center adoption of heads-up display visualization systems.
Japan
Metropolitan Tokyo hospitals prioritize digital microscopy replacement cycles featuring 4K camera heads for anterior segment procedures. METI standards and PMDA oversight shape domestic approval pathways for AI-assisted focusing modules. The Nagoya medical device manufacturing belt supplies precision motorized zoom systems to regional surgical microscope assemblers.
Switzerland
Academic medical centers in Basel and Zurich request modular teaching configurations supporting resident training workflows and multi-surgeon observation. Swissmedic regulations align with EU MDR requirements for sterilizable component biocompatibility documentation under ISO 10993. The Swiss Romandie region concentrates fluorescence filter set engineering for research laboratory applications.
China
Provincial hospital procurement in Jiangsu and Guangdong provinces weights energy-efficient LED illumination systems under national dual carbon sustainability mandates. NMPA clearance pathways govern domestic manufacturing licenses for surgical microscopy platforms. The Yangtze River Delta medical equipment cluster is expanding captive optical component grinding capabilities to reduce import dependency.
Ophthalmic Microscopes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital visualization overlays and AI-assisted imaging modules. The market exhibits moderate consolidation around integrated surgical platform vendors with captive optical supply chains. Three archetypes dominate: precision optics specialists with lens grinding capabilities, integrated diagnostic-surgical system vendors, and modular teaching configuration providers. Competitive maneuvering centers on backward integration into apochromatic objective manufacturing and strategic partnerships for intraoperative OCT technology licensing.
Among Germany-based precision optics fabricators, Carl Zeiss Meditec AG and Leica Microsystems exemplify the integrated platform archetype. Alcon Inc. represents the consolidated diagnostic-surgical system vendor model. Japanese specialists Takagi Seiko Co., Ltd. and Inami & Co., Ltd. occupy positions within the modular component supplier tier. These named entities anchor competitive positioning without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Leica Microsystems |
| Topcon Corporation |
| Haag-Streit Holding |
| Takagi Seiko Co., Ltd. |
| Inami & Co., Ltd. |
| Karl Kaps GmbH & Co. KG |
| Seiler Instrument Inc. |
| Others |
Value Network & Pricing Analysis
Captive lens grinding capabilities at Carl Zeiss Meditec AG anchor both supply security and premium pricing power across surgical microscope platforms. This backward integration into apochromatic objective manufacturing insulates margin control while competitors confront input bottlenecks from European and Japanese optical specialists.
Pricing Analysis
Apochromatic objective cost pass-through from concentrated European and Japanese suppliers sustains premium pricing tiers for fluorescence-guided surgical microscopes. Price differentiation rests on ISO 10993 certification tier and after-sales service bundling rather than base optical specifications alone. Cost compression in standard optical microscopy intensifies as digital overlays displace eyepiece-dependent workflows. Outpatient clinics exhibit highest price sensitivity; German university hospitals show lowest sensitivity given fluorescence module procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from hospital purchasing committees mandate qualified suppliers for both apochromatic objectives and motorized zoom systems. Manufacturing concentrates in Germany, Japan, and Switzerland for precision optical components. Raw material dependencies span specialized optical glass, rare-earth doped filter substrates, and sterilizable polymer draping systems. Single-source vulnerability persists in indocyanine green angiography module supply. Distribution runs through integrated phacoemulsification-microscope console vendors and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ophthalmic microscopes market functions as a stable compounder anchored by surgical volume expansion and replacement cycle compression from multi-modal imaging convergence.
For Market Incumbents: Deploy backward integration into apochromatic objective manufacturing to defend margin position against standalone digital microscopy entrants. Hospital purchasing committee consolidation around integrated phacoemulsification-microscope consoles threatens standalone microscope demand. Prioritize FDA 510(k) pathway investments for OCT-integrated platforms to accelerate commercialization timelines.
For New Entrants and Emerging Players: Regional hospital procurement offices in China's Jiangsu and Guangdong provinces offer white-space access under dual carbon sustainability mandates weighting LED illumination systems. Portable microscope segments for outreach screening programs remain underpenetrated relative to surgical platform saturation. Pursue software-as-medical-device partnerships for AI-assisted focusing modules to bypass optical component supply constraints.
For Investors and Strategic Acquirers: Consolidation pressure builds where captive lens grinding capabilities intersect with fluorescence microscopy R&D concentration in the Baden-Württemberg corridor. Long-term viability favors vertically integrated platform vendors over modular component suppliers. Monitor EU MDR notified body capacity as inflection indicator for European market entry timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for OCT Integration | Abbreviated clearance pathways accelerate multi-functional surgical platform commercialization timelines in the United States. |
| Backward Integration into Lens Grinding | Captive apochromatic objective production insulates margin control against European and Japanese supply concentration. |
| Hospital System Partnership for Console Integration | Single-platform cataract surgery systems reduce operating room footprint and vendor management complexity. |
| Software Companion Development for AI Focusing | AI-assisted image analysis modules face evolving regulatory scrutiny across FDA and EU MDR jurisdictions. |
| CE Marking Pathway under EU MDR | Expanded ISO 10993 biocompatibility documentation extends time-to-market for sterilizable microscope components. |
Research Methodology
Coverage spans Germany, the United States, Japan, Switzerland, and China, with primary inputs from each market informing demand calibration. The analysis combines interviews with vitreoretinal surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs records for optical component trade flows. Bottom-up installation base modeling and top-down capital equipment spending analysis provide triangulation.
Granularity-level modeling disaggregates volume and value across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs derive from replacement cycle analysis, procurement budget elasticity estimates, and regulatory approval timeline distributions. Industry-specific inputs include intraoperative OCT integration penetration rates and fluorescence microscopy module attach rates in academic medical centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints and software-as-medical-device classification evolution. Deviation in FDA 510(k) pathway streamlining for OCT-integrated platforms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ablation Devices Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Anti-Snore Device Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Alexandrite Gemstone Lasers Market