
 Veterinary Procedure Lights Market | 2026-2036
Veterinary Procedure Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Procedure Lights Market Outlook
Equipment leasing and pay-per-procedure financing is reconfiguring capital access for mid-sized veterinary practices that previously deferred surgical suite upgrades. Midmark Corporation leverages its scale in clinical equipment financing to extend reach into independent animal clinics. Dr. Mach GmbH & Co. KG anchors its position through precision German engineering in surgical-grade LED systems. STERIS plc competes across infection-controlled environments with integrated operating room protocols that bundle illumination with sterilization workflows.
Veterinary procedure lights are specialized medical illumination devices engineered to deliver shadow-free, color-accurate light with color rendering indices exceeding 90 and adjustable color temperatures between 3,500K and 5,000K for tissue differentiation during surgical and diagnostic interventions. LED lights now dominate new installations as halogen systems face phase-out due to thermal load and energy inefficiency, while surgical lights command premium positioning over examination variants. Wireless and portable technologies are gaining fastest among mobile veterinary units and emergency response fleets, though fixed integrated systems retain margin concentration in tertiary veterinary hospitals.
FDA device classification requirements for veterinary medical equipment shape product registration pathways and quality system expectations for manufacturers distributing in the United States. The EU Medical Device Regulation and CE marking obligations govern market access across European veterinary channels, while ISO 13485 quality management standards provide baseline certification for international competitiveness. Stakeholders must monitor evolving energy efficiency mandates and circular economy material requirements that will reshape product design specifications and supplier qualification criteria.
Market Dynamics
LED thermal management advances are collapsing the performance gap between surgical and examination-grade fixtures, forcing tiered pricing structures to reconstitute around wireless connectivity and battery autonomy rather than raw illuminance metrics.
Growth Catalysts
- EU Medical Device Regulation (MDR) compliance deadlines:Veterinary equipment distributors across Germany and France are accelerating CE-marked LED replacements ahead of enforcement milestones, pulling forward upgrade cycles in tertiary hospitals.
- Mobile veterinary emergency fleets:Battery-integrated surgical lights with 4-hour autonomy are penetrating roadside trauma and large-animal field surgery applications previously unserved by fixed infrastructure.
- Color-tunable LED arrays:Precision wavelength control between 3,500K and 5,000K is enabling tissue differentiation protocols that halogen systems cannot replicate, driving replacement demand in oncology and ophthalmology suites.
Market Restraints
- Aluminum heat sink and rare-earth phosphor cost volatility:LED surgical head thermal management components face input price instability from concentrated Chinese rare-earth processing.
- ISO 13485 certification timeline friction:Small manufacturers in Italy and Spain encounter 14-18 month quality system approval delays that freeze market entry.
- Refurbished halogen system secondary markets:Certified pre-owned surgical lights from decommissioned human hospitals are capturing price-sensitive independent clinic demand in Eastern Europe.
Strategic Opportunities
- Rural veterinary service gaps in India:Solar-battery hybrid surgical lights address electrification deficits in tier-3 cities and agricultural belts where grid reliability blocks conventional installation.
- Japan's METI carbon neutrality procurement guidelines:Public veterinary hospitals must achieve 40% energy intensity reductions by 2030, mandating LED retrofits with integrated power monitoring.
- Tele-surgery preparation suites:High-fidelity video capture compatibility is creating demand for 4K-optimized color rendering indices above 95 in academic veterinary centers training remote surgical teams.
Industry Challenges
- Veterinary surgical lighting technician certification gaps:Biomedical equipment specialists trained on human OR systems lack species-specific fixture calibration expertise, extending installation and maintenance timelines.
- Legacy halogen infrastructure lock-in:Ceiling-mounted suspension systems in 1990s-era veterinary hospitals require structural reinforcement to support heavier LED arrays, complicating retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Procedure Lights Market |
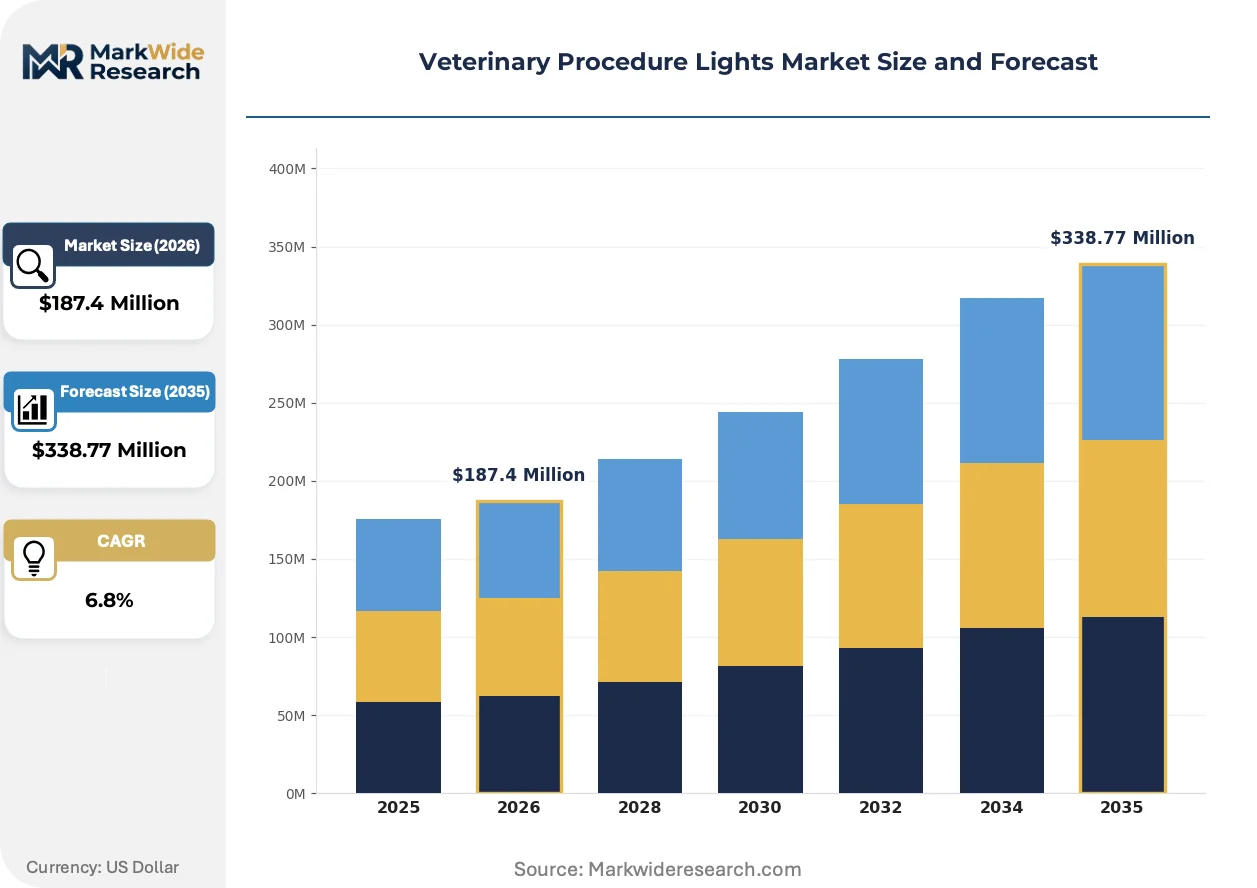
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Halogen Lights, Surgical Lights, Examination Lights Technology: Wireless, Portable, Integrated, Fixed Application: Dental Procedures, Surgical Procedures, Examination, Emergency Care End User: Animal Clinics, Veterinary Hospitals, Research Facilities, Mobile Units |
| Companies Covered | Midmark Corporation, Medical Illumination, ACEM S.p.A, Burtons Medical Equipment Ltd, Avante Animal Health, STERIS plc, Dr. Mach GmbH & Co. KG, Burton Medical Products, Sunnex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Procedure Lights Market Strategic Shifts
Wireless power transmission and solid-state battery chemistry are dissolving the historical trade-off between surgical-grade illuminance and fixture mobility, enabling entirely new deployment architectures.
Adaptive ambient compensation technology is hybridizing camera-integrated surgical lights with real-time tissue recognition algorithms. University veterinary teaching hospitals in the Netherlands and Switzerland are piloting these systems for resident training documentation. The convergence is compressing demand for standalone surgical recording equipment by embedding broadcast-ready video capture directly into illumination heads.
REACH substance restriction amendments targeting halogenated flame retardants are compelling housing material redesigns for surgical light enclosures. German and Polish manufacturers are accelerating glass-reinforced polymer substitutions ahead of 2026 enforcement windows. Tertiary veterinary hospitals with bundled sterilization-illumination contracts from integrated suppliers face compressed requalification timelines.
Subscription-based equipment access models are displacing capital purchase cycles among mid-sized veterinary groups in the United Kingdom and Australia. Monthly per-procedure fees covering maintenance, upgrade rights, and compliance documentation are capturing practices with constrained credit facilities. The shift is most visible in multi-site rollouts where standardization across locations outweighs ownership preferences.
Veterinary Procedure Lights Market Segmentation
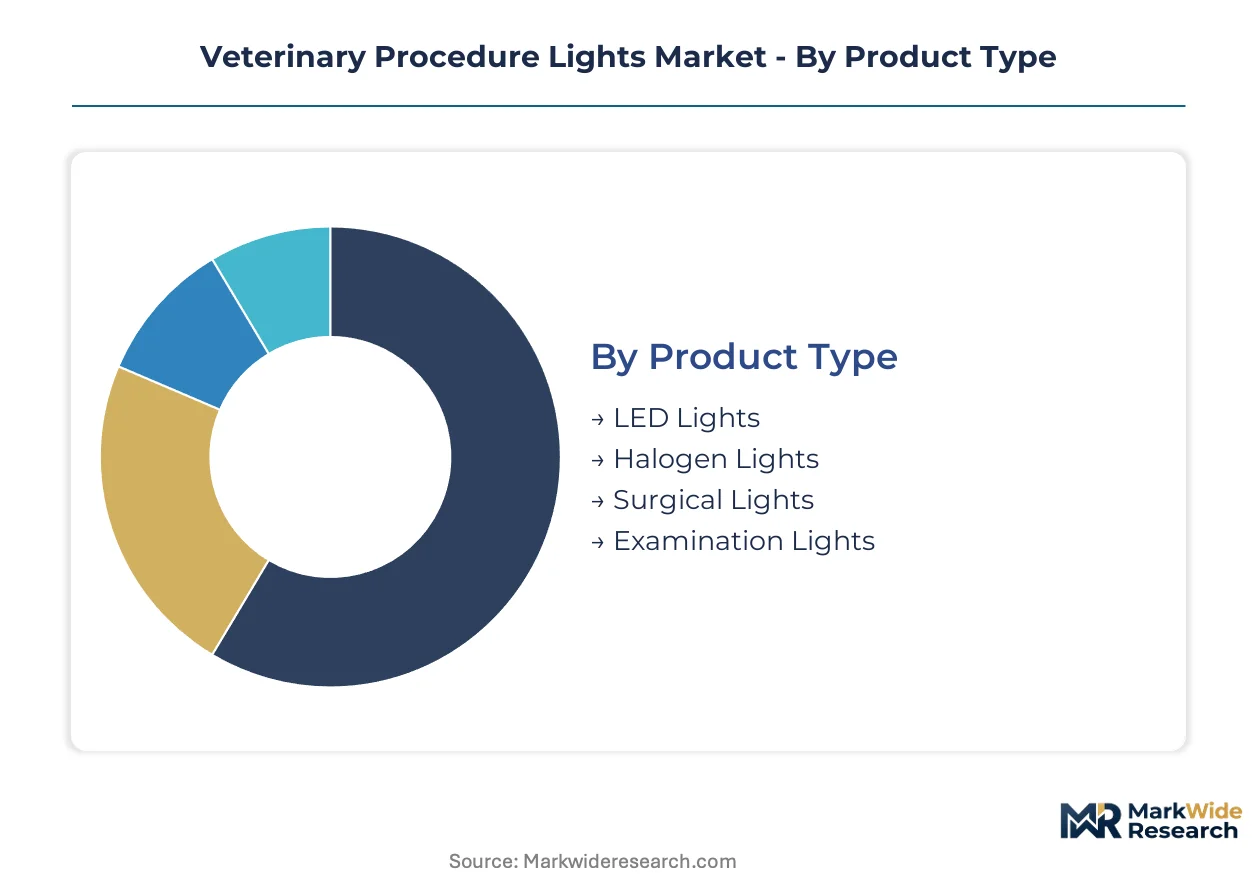
Veterinary procedure lights serve distinct operational contexts ranging from routine wellness checks to complex orthopedic surgeries. Segmentation reveals how fixture specifications, mobility requirements, and end-user scale reshape procurement priorities across the installed base.
Product Type:
The use-case spectrum spans thermal-sensitive small-animal dentistry to heat-intensive large-animal surgery, dictating lumen output, color temperature range, and heat dissipation architecture.
- LED Lights:Solid-state arrays with color rendering indices exceeding 90 and adjustable Kelvin ratings between 3,500K and 5,000K enable tissue differentiation protocols in oncology and ophthalmology suites. Demand concentrates in United States tertiary hospitals where energy efficiency mandates and thermal load reduction drive accelerated halogen replacement cycles.
- Halogen Lights:Tungsten-halogen filaments deliver continuous spectrum illumination prized for color fidelity in dermatological examination, though thermal radiation and energy consumption render these systems economically uncompetitive for new installations. Refurbished units from decommissioned human hospitals capture price-sensitive independent clinic demand in Eastern Europe.
- Surgical Lights:Ceiling-mounted or suspension-arm fixtures with shadow-free optical engineering and sterile handle controls command premium positioning in orthopedic and soft-tissue operating theaters.
- Examination Lights:Lower-lumen mobile units with flexible gooseneck positioning dominate wellness check and minor wound management workflows in general practice settings.
The dominant share belongs to LED Lights, while Surgical Lights is closing the gap fastest as hospitals consolidate multi-specialty capabilities.
Technology:
Cost tier stratification separates capital-intensive infrastructure investments from operational expenditure models favoring flexibility and rapid deployment.
- Wireless:Radio-frequency or infrared control systems eliminate cable clutter in sterile fields and enable remote intensity adjustment during procedures. Battery-integrated variants with 4-hour autonomy penetrate mobile veterinary emergency fleets and large-animal field surgery applications in Australia and the United Kingdom.
- Portable:Self-contained units with solid-state battery chemistry and collapsible mounting systems serve disaster response deployments and rural outreach programs where grid reliability is inconsistent. Solar-battery hybrid configurations address electrification deficits in tier-3 Indian cities.
- Integrated:Ceiling-recessed or boom-mounted systems with HVAC coupling and video capture compatibility anchor new construction in academic veterinary centers.
- Fixed:Hardwired installations with dedicated electrical infrastructure retain margin concentration in tertiary hospitals with bundled sterilization-illumination contracts.
Integrated systems capture the largest revenue pool, yet Portable technology is expanding most quickly as subscription-based equipment access models displace capital purchase cycles among mid-sized veterinary groups.
Application:
Volume concentration tracks procedure complexity and reimbursement intensity, with surgical interventions commanding fixture specifications far exceeding diagnostic workflows.
- Surgical Procedures:Orthopedic, soft-tissue, and neurological interventions require shadow-free illumination exceeding 100,000 lux at the operative field with sterile field compatibility. German and Japanese tertiary hospitals drive specification intensity for 4K-optimized color rendering indices above 95 in tele-surgery preparation suites.
- Emergency Care:Trauma stabilization and critical intervention demand rapid-deployment lighting with battery autonomy and ruggedized housing for transport environments. Mobile veterinary units in the United States and Australia prioritize these specifications for roadside large-animal response.
- Dental Procedures:Compact head-mounted or chair-mounted units with focused beam control address oral surgery and periodontal intervention in small-animal practice.
- Examination:General wellness and diagnostic workflows utilize lower-specification mobile units where cost efficiency outweighs surgical-grade performance.
Surgical Procedures holds the dominant share, though Emergency Care is gaining share fastest as fleet-based veterinary services expand beyond urban centers.
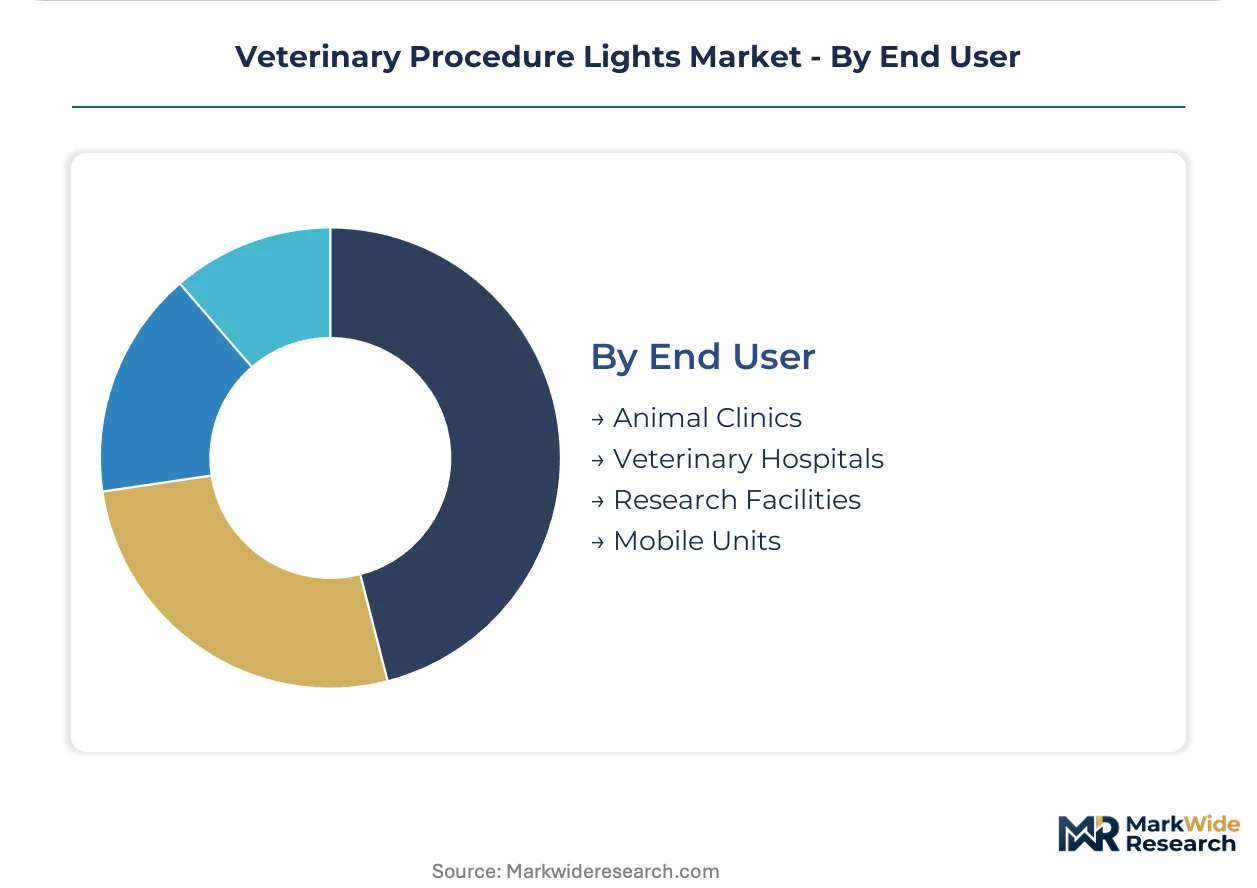
End User:
Customer type determines procurement authority, with consolidated hospital systems driving standardization and independent clinics prioritizing financing flexibility.
- Veterinary Hospitals:Multi-specialty institutions with dedicated surgical suites and residency programs specify integrated systems with video documentation compatibility and compliance documentation packages. Japan's METI carbon neutrality procurement guidelines mandate 40% energy intensity reductions by 2030, accelerating LED retrofit programs in public facilities.
- Animal Clinics:Independent and small-group general practices favor leasing arrangements and per-procedure financing that convert capital expenditure to operational budgets. Mid-sized United Kingdom and Australian groups increasingly adopt subscription-based equipment access covering maintenance and upgrade rights.
- Mobile Units:Fleet-based operators serving agricultural belts and disaster zones prioritize battery autonomy, solar compatibility, and rapid deployment architecture over fixed infrastructure.
- Research Facilities:Academic and pharmaceutical testing environments require calibrated illumination for reproducible imaging and documentation protocols in toxicology and surgical training applications.
Veterinary Hospitals command the dominant share, while Mobile Units is climbing the fastest as rural service gaps and emergency response networks expand across underserved geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary hospitals command pricing premiums for surgical-grade LED systems that German clinics cannot replicate, while Japanese procurement rules compress margins through carbon-neutral mandates. This asymmetry shapes manufacturer geographic prioritization and product mix allocation.
United States
Pet healthcare expenditure climbs steadily as specialty veterinary surgery volume expands in tertiary hospitals. FDA device classification requirements govern product registration pathways and quality system expectations for domestic distribution. California and Texas veterinary medical centers drive specification intensity for integrated operating room protocols.
Germany
Precision engineering standards elevate demand for surgical-grade LED systems with color rendering indices exceeding 95 in university hospitals. EU Medical Device Regulation compliance deadlines accelerate CE-marked replacements ahead of enforcement milestones. Bavarian and North Rhine-Westphalian veterinary clusters anchor German manufacturing and specification leadership.
Japan
METI carbon neutrality procurement guidelines mandate 40% energy intensity reductions by 2030 in public veterinary facilities. JIS standards provide baseline certification benchmarks for domestic and export competitiveness. Tokyo and Osaka academic veterinary centers pilot tele-surgery preparation suites with 4K-optimized illumination.
India
Rural veterinary service gaps create demand for solar-battery hybrid surgical lights in tier-3 cities and agricultural belts. BIS standards and CDSCO oversight shape product registration for imported and domestic equipment. Maharashtra and Gujarat veterinary infrastructure projects address electrification deficits blocking conventional installation.
Australia
Mobile veterinary emergency fleets prioritize battery-integrated surgical lights with 4-hour autonomy for large-animal field surgery. TGA compliance requirements structure market access for imported illumination systems. Queensland and New South Wales fleet operators expand roadside trauma response capabilities beyond urban centers.
Veterinary Procedure Lights Market Competitive Environment
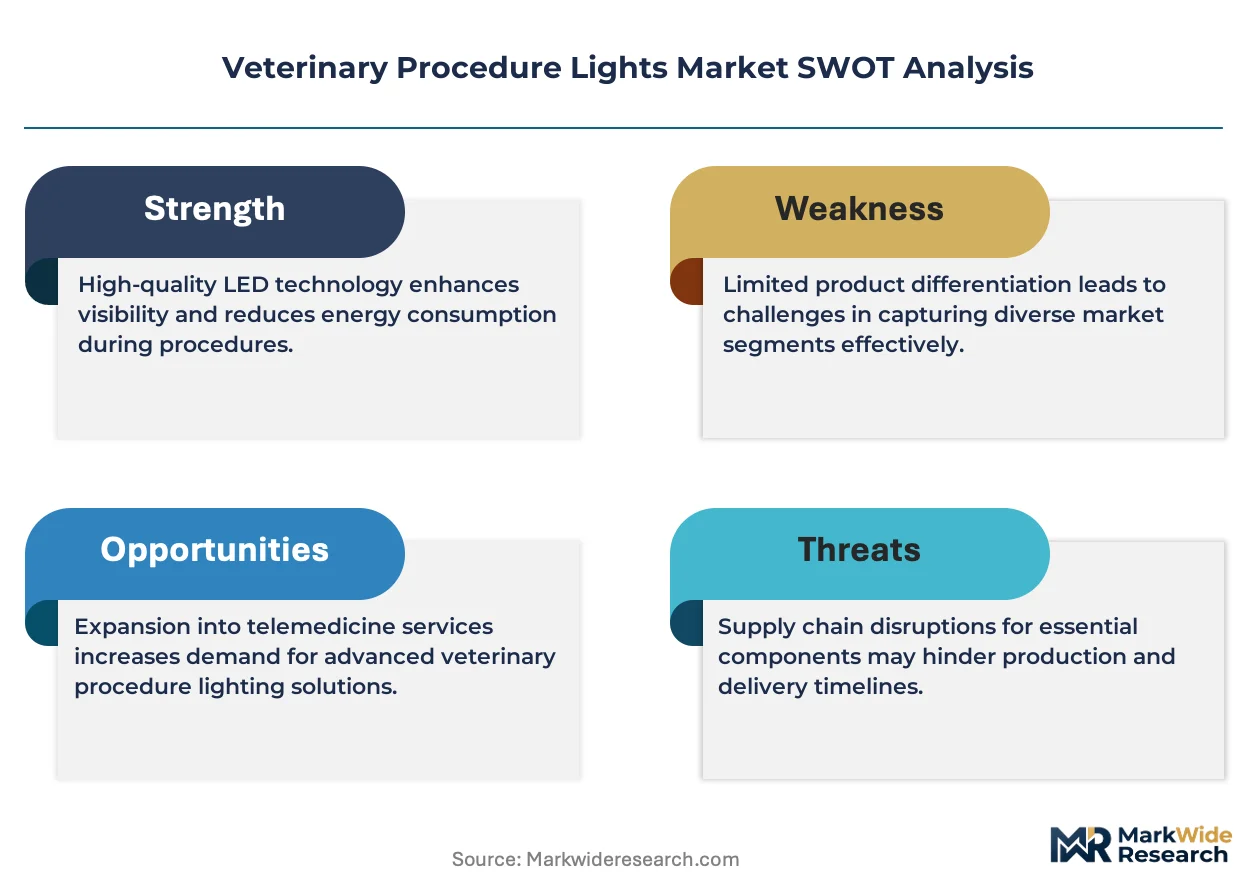
Platform integrators command the system tier; component specialists sit upstream supplying optical arrays and thermal management subassemblies. Market structure concentrates around bundled sterilization-illumination contracts in tertiary hospitals while fragmenting across independent clinic financing channels. Three archetypes dominate: integrated operating room suppliers, precision German engineering houses, and mid-scale clinical equipment financiers. Competitive moves center on subscription-based equipment access models and glass-reinforced polymer housing redesigns ahead of REACH enforcement windows.
Among German engineering specialists, Dr. Mach GmbH & Co. KG exemplifies precision manufacturing archetypes with surgical-grade LED credentials. STERIS plc occupies a position within integrated operating room protocol bundling. Midmark Corporation represents the equipment financing and leasing tier extending reach into independent animal clinics.
| Leading Market Players |
|---|
| Midmark Corporation |
| Medical Illumination |
| ACEM S.p.A |
| Burtons Medical Equipment Ltd |
| Avante Animal Health |
| STERIS plc |
| Dr. Mach GmbH & Co. KG |
| Burton Medical Products |
| Sunnex Group |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific freight corridors from Shanghai to Long Beach transmit rare-earth phosphor and aluminum heat sink cost volatility directly into LED surgical head pricing tiers, concentrating margin pressure on mid-scale manufacturers while enabling tiered differentiation between integrated suppliers and independent clinics.
Pricing Analysis
The customization-premium spread separates configured-to-order surgical-grade LED systems from standard examination fixtures by a factor driven by certification tier and after-sales service bundling. Subscription-based equipment access models are displacing capital purchase cycles among mid-sized veterinary groups, compressing upfront revenue while extending lifetime value. Cost compression in the halogen replacement segment intensifies because refurbished units from decommissioned human hospitals capture price-sensitive independent clinic demand. Mobile veterinary units exhibit highest price sensitivity due to constrained credit facilities, while tertiary academic centers demonstrate lowest sensitivity given bundled sterilization-illumination contracts.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for LED thermal management components, particularly rare-earth phosphor processing concentrated in Chinese refineries. Manufacturing draws from China, Germany, and the United States for optical arrays, thermal management subassemblies, and precision suspension systems respectively. Aluminum heat sink and solid-state battery chemistry dependencies rest on concentrated upstream processing capacity. Single-source vulnerability in rare-earth element supply creates procurement fragility. Distribution runs through integrated operating room suppliers for tertiary hospitals and clinical equipment financiers for independent clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary procedure lights are cycling through a replacement wave as EU Medical Device Regulation compliance deadlines and METI carbon neutrality mandates force accelerated LED retrofits across developed markets.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance algorithms into surgical light firmware, creating switching costs that counter emerging portable-technology entrants. Deepen backward integration into rare-earth phosphor supply through offtake agreements with Australian and Canadian mining ventures to neutralize Chinese processing concentration.
For New Entrants and Emerging Players: Solar-battery hybrid surgical lights for tier-3 Indian cities and agricultural belts represent the most penetrable entry point, addressing electrification deficits that block incumbent fixed-installation models. Mobile veterinary emergency fleets in Australia and the United Kingdom offer secondary white-space opportunity. Pursue subscription-based equipment access models that convert capital expenditure to operational budgets for mid-sized veterinary groups.
For Investors and Strategic Acquirers: EU Medical Device Regulation enforcement milestones reshape the acquisition landscape by freezing market entry for uncertified small manufacturers and consolidating bargaining power among CE-marked incumbents. Five-to-ten year viability favors precision German engineering houses with surgical-grade LED credentials and integrated sterilization-illumination bundling capability. Monitor REACH substance restriction amendments targeting halogenated flame retardants as inflection signal for housing material redesign requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance deadlines pull forward upgrade cycles in German and French tertiary hospitals. |
| Battery Supply Agreement | Solid-state chemistry partnerships secure 4-hour autonomy specifications for mobile veterinary fleets. |
| Hospital System Partnership | Bundled sterilization-illumination contracts with Japanese public veterinary facilities capture METI-mandated retrofit demand. |
| Software Companion Development | Adaptive ambient compensation algorithms enable real-time tissue recognition for tele-surgery training suites. |
| Reimbursement Strategy | Per-procedure financing documentation supports veterinary clinic operational expenditure conversion. |
Study Parameters
Operator-level perspectives from veterinary surgical suite managers, biomedical equipment specialists, GPO contracts managers, and clinical equipment financing officers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA device classification filings, EU Medical Device Regulation submission databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume assumptions across the analysis window.
Scenario-bracketing framed the analytical approach across product type, technology architecture, application intensity, and end-user scale dimensions. CAGRs derived from segment-level growth rate reconciliation against macro veterinary expenditure trends. Forecast inputs incorporated LED thermal management cost curves and rare-earth phosphor price elasticity parameters specific to surgical illumination applications.
Macroeconomic conditions sit as an overlay; deviation in veterinary service demand elasticity or pet healthcare expenditure growth would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Foot Suction Unit Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Low Vision Aids Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Posture Correction Market
Medical Devices
EMG Biosensors Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Smart Patches Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Solar Surgical Light Market