
 Sperm Separation Systems Market | 2026-2036
Sperm Separation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sperm Separation Systems Market Analytics
Trained embryology laboratory staff shortages is reorganizing competitive dynamics across the sperm separation systems landscape. CooperSurgical, Inc. leverages integrated media-instrument bundles to reduce protocol complexity for understaffed clinics. Hamilton Thorne anchors its position through sustained R&D intensity in imaging-guided separation platforms. Vitrolife AB specializes in premium culture media formulations that command loyalty among high-throughput fertility centers.
Sperm separation systems encompass instruments, consumables, media, and kits designed to isolate motile, morphologically normal spermatozoa from seminal plasma through density gradient centrifugation, magnetic-activated cell sorting, or microfluidic channel sorting, typically achieving motility enrichment exceeding 90% for downstream assisted reproduction. These systems serve fertility clinics, hospitals, research institutions, and sperm banks requiring standardized, reproducible specimen preparation for intrauterine insemination, in vitro fertilization, and cryopreservation workflows. Microfluidics technology leads innovation velocity with label-free, low-shear processing that preserves DNA integrity, while density gradient methods dominate installed base and consumable recurring revenue. Fertility clinics represent the deepest end-user margin pool given high procedure volumes and protocol stickiness, whereas research institutions drive adoption of advanced magnetic separation platforms for stem cell and epigenetics applications.
The EU Medical Device Regulation and FDA 510(k) pathway impose distinct clinical evidence and quality management requirements that shape product development timelines and market access costs for manufacturers targeting dual-territory commercialization. ISO 13485 certification and WHO laboratory standards further condition procurement eligibility among public hospital systems and international sperm bank networks. Stakeholders must monitor evolving premarket submission expectations for software-enabled separation devices and anticipate how regulatory convergence between European and North American frameworks reshapes competitive positioning for integrated platform vendors.
Market Dynamics
Microfluidic separation platforms are fragmenting the installed base of density gradient centrifugation systems, compressing protocol times from hours to minutes while preserving DNA integrity for fertility clinics managing high specimen volumes.
Growth Catalysts
- EU Medical Device Regulation harmonization:Streamlined CE marking pathways accelerate product certification timelines for manufacturers targeting multiple member states.
- Magnetic-activated cell sorting (MACS):Research institutions drive adoption for stem cell applications, expanding addressable use cases beyond fertility treatment.
- Germany:Aging demographics and delayed family planning expand the patient pool seeking intrauterine insemination and in vitro fertilization services.
Market Restraints
- Trained embryology laboratory staff shortages:Protocol complexity limits throughput in understaffed clinics, constraining system utilization rates.
- Consumable cost structure:Premium culture media and single-use gradient kits create recurring expense burdens for high-volume fertility centers.
- Technical limitation in shear stress:Conventional centrifugation methods risk DNA fragmentation, limiting suitability for severe male factor infertility cases.
Strategic Opportunities
- Spain:Widening access to assisted reproductive technologies in regional fertility networks creates expansion potential for integrated platform vendors.
- Label-free microfluidic processing:Convergence with imaging-guided separation enables real-time motility assessment without fluorescent staining.
- WHO laboratory standards alignment:Certification eligibility opens procurement pathways in public hospital systems and international sperm bank networks.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation delays market entry for software-enabled separation devices.
- Integration complexity with legacy laboratory information systems:Fertility clinics face workflow disruption when connecting new separation platforms to established electronic medical record infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sperm Separation Systems Market |
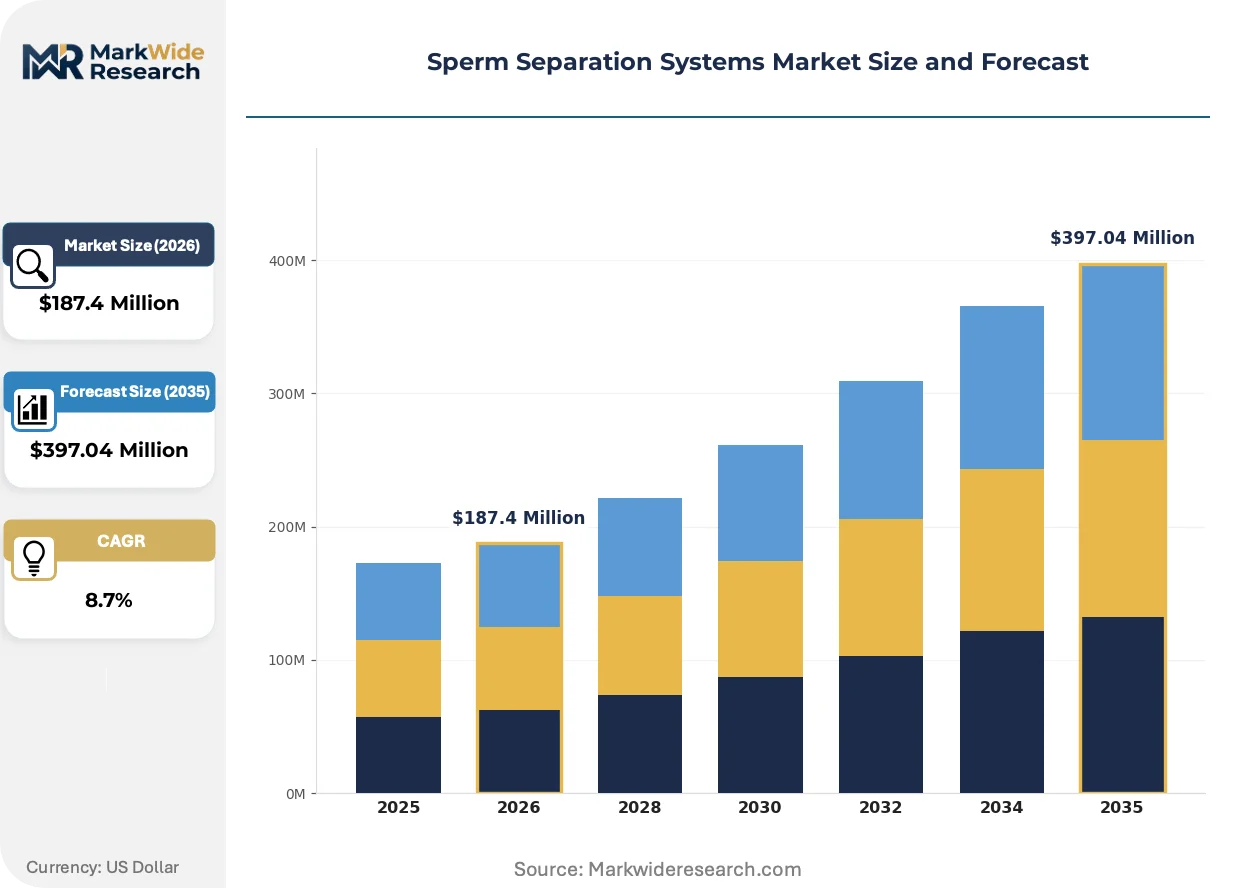
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Density Gradient, Magnetic Separation, Centrifugation, Microfluidics Application: IVF, IUI, Research, Sperm Banking End User: Fertility Clinics, Research Institutions, Hospitals, Sperm Banks Product Type: Consumables, Instruments, Media, Kits |
| Companies Covered | CooperSurgical, Inc., Hamilton Thorne, Memphasys, NidaCon International AB, SAR Healthline Pvt Ltd., Sperm Processor, Vitrolife AB, Eppendorf SE, Esco Micro Pte Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sperm Separation Systems Market Evolving Landscape
Technology convergence between microfluidics and artificial intelligence is compressing operator dependency while regulatory pressure on clinical evidence standards intensifies product development timelines.
Microfluidic channel sorting is fragmenting the dominance of density gradient methods by enabling label-free, low-shear processing that preserves sperm DNA integrity. High-throughput fertility centers in Western Europe are adopting these platforms at accelerating pace to reduce embryologist hands-on time. The technology is fragmenting consumable revenue models by shifting from recurring gradient media purchases toward capital-intensive instrument placements with lower ongoing material costs.
EU MDR clinical evidence requirements are extending premarket submission timelines for manufacturers seeking dual-territory commercialization with FDA 510(k) pathways. Device classification uncertainties for software-enabled separation systems create regulatory friction that shapes competitive positioning. Fertility clinics in Germany and Spain are prioritizing vendors with established notified body relationships to mitigate procurement delays.
Buyer concentration among large fertility center networks is consolidating purchasing power and compressing switching cycles for separation system vendors. Integrated media-instrument bundles are displacing standalone consumable procurement as understaffed clinics seek protocol simplification. This pattern is most visible in Western European markets where aging demographics sustain high procedure volumes.
Sperm Separation Systems Market Segmentation
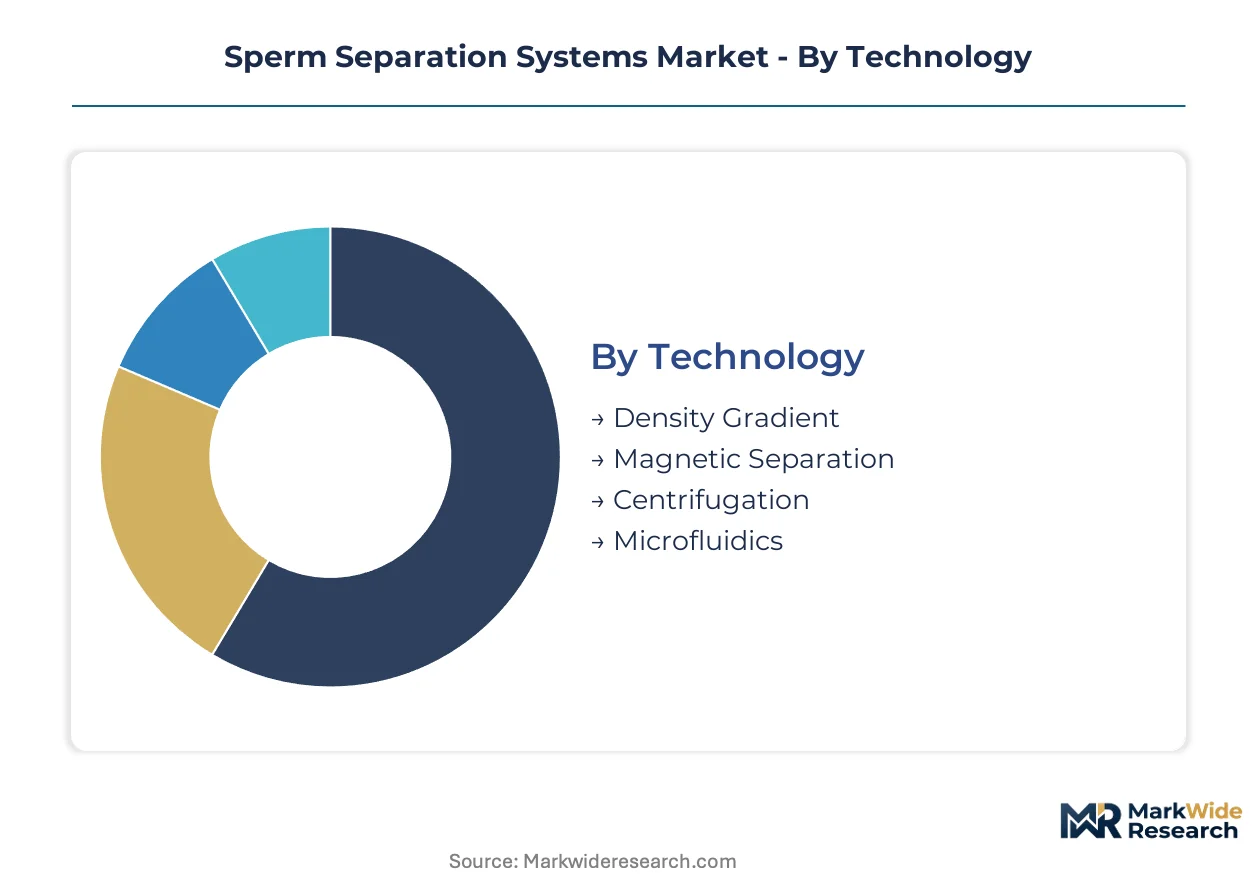
Sperm separation systems fragment across technology platforms, clinical applications, and procurement channels. Each segment carries distinct regulatory pathways, margin profiles, and adoption barriers that shape vendor strategy.
Technology:
EU MDR classification intensity varies by separation mechanism, with software-enabled platforms facing extended clinical evidence requirements.
- Density Gradient:Silica-based colloidal suspensions separate motile spermatozoa through buoyant density differentials. Fertility clinics in Germany rely on standardized two-layer protocols for high-volume IUI workflows, though consumable costs strain operational budgets.
- Microfluidics:Polydimethylsiloxane channels exploit laminar flow physics for label-free, low-shear isolation. Spanish fertility networks adopt these systems fastest to preserve DNA integrity in severe male factor cases while reducing embryologist hands-on time.
- Magnetic Separation:Paramagnetic bead conjugation enables negative selection of apoptotic sperm populations.
- Centrifugation:Conventional swing-bucket rotors remain entrenched in resource-constrained settings.
Density Gradient handles the majority of throughput; Microfluidics is the fastest mover on share.
Application:
Procedure reimbursement rates and clinical outcome accountability determine technology selection across use cases.
- IVF:Intracytoplasmic sperm injection demands morphologically normal, DNA-intact gametes. Western European fertility centers prioritize microfluidic preprocessing to optimize fertilization rates in advanced maternal age patient cohorts.
- IUI:Intrauterine insemination requires rapid, cost-effective motility enrichment. German outpatient clinics favor density gradient methods for same-day specimen processing.
- Research:Stem cell and epigenetics protocols drive magnetic separation adoption.
- Sperm Banking:Cryopreservation workflows emphasize standardized, reproducible quality metrics.
IVF commands the deepest margin pool; Research applications are climbing the fastest on investment intensity.
End User:
Procurement authority concentrates differently across institutional types, from centralized hospital purchasing to specialized fertility center networks.
- Fertility Clinics:High procedure volumes and protocol stickiness create recurring consumable demand. Spain's regional fertility networks negotiate integrated media-instrument bundles to mitigate staff shortage constraints.
- Hospitals:Public hospital systems in Germany require ISO 13485 certification and WHO laboratory standard alignment for vendor eligibility.
- Research Institutions:Academic laboratories drive early adoption of advanced magnetic platforms.
- Sperm Banks:International networks prioritize regulatory harmonization across donor jurisdictions.
Fertility Clinics absorb the dominant share of system placements; Research Institutions show the steepest expansion trajectory for premium platforms.
Product Type:
Revenue model structure diverges sharply between capital equipment and recurring consumable streams.
- Consumables:Single-use gradient kits and separation columns generate predictable recurring revenue. German fertility centers face cost pressure from premium silica suspension pricing.
- Instruments:Capital equipment placements require extended sales cycles and installation support. Microfluidic platform vendors in Spain compete on workflow integration with legacy laboratory information systems.
- Media:Protein-supplemented culture formulations command loyalty among high-throughput centers.
- Kits:Pre-formulated, protocol-ready bundles reduce operator variability.
Consumables anchor the revenue base; Instruments are gaining share fastest on technology replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Medical Device Regulation anchors Western Europe as the dominant geography for sperm separation systems, with notified body relationships determining vendor procurement eligibility across fertility networks.
Germany
Aging demographics and delayed family planning expand patient pools seeking intrauterine insemination and in vitro fertilization services. The Federal Institute for Drugs and Medical Devices enforces MDR compliance timelines that shape product certification pathways. Fertility centers in Bavaria and North Rhine-Westphalia negotiate integrated media-instrument bundles to mitigate embryology staff shortages.
Spain
Widening access to assisted reproductive technologies in regional fertility networks creates expansion potential for integrated platform vendors. The Spanish Agency for Medicines and Health Products aligns with EU MDR harmonization to streamline CE marking processes. Barcelona and Madrid fertility clusters adopt microfluidic systems fastest to reduce embryologist hands-on time.
United States
High-throughput fertility centers drive demand for imaging-guided separation platforms with reduced operator dependency. The FDA 510(k) pathway imposes distinct clinical evidence requirements that extend premarket submission timelines for dual-territory commercialization. Research institutions in Massachusetts and California anchor adoption of magnetic-activated cell sorting for stem cell applications.
United Kingdom
Consolidated purchasing power among large fertility center networks compresses switching cycles for separation system vendors. The Medicines and Healthcare products Regulatory Agency oversees post-Brexit device registration pathways that condition market access. London and Southeast England fertility clinics prioritize vendors with established quality management certifications.
Japan
Advanced maternal age patient cohorts prioritize DNA integrity preservation in sperm preprocessing workflows. The Pharmaceuticals and Medical Devices Agency maintains stringent clinical evidence standards for software-enabled separation devices. Tokyo and Osaka metropolitan fertility centers represent concentrated demand for premium culture media formulations.
Sperm Separation Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sperm separation systems landscape. The vendor base consolidates around integrated platform specialists, consumable-focused suppliers, and imaging technology developers. Three strategic archetypes dominate: bundled solution providers reducing protocol complexity, premium media formulators commanding loyalty among high-throughput centers, and microfluidic innovators displacing density gradient installed bases. Competitive moves concentrate on strategic partnerships for workflow integration and portfolio diversification into adjacent assisted reproductive technology segments.
Within the integrated platform tier, CooperSurgical, Inc. and Hamilton Thorne occupy positions reflecting divergent approaches to laboratory automation. Vitrolife AB exemplifies the premium consumable archetype through specialized culture media formulations. These three entities anchor the competitive structure while Eppendorf SE and Esco Micro Pte Ltd. represent European and Asian equipment manufacturing traditions respectively.
| Leading Market Players |
|---|
| CooperSurgical, Inc. |
| Hamilton Thorne |
| Memphasys |
| NidaCon International AB |
| SAR Healthline Pvt Ltd. |
| Sperm Processor |
| Vitrolife AB |
| Eppendorf SE |
| Esco Micro Pte Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term consumable supply contracts anchor pricing visibility for fertility centers, locking in silica-based gradient media access while insulating high-volume clinics from spot-market volatility in polydimethylsiloxane channel components. German procurement officers leverage these arrangements to stabilize operational budgets against premium culture media pricing fluctuations.
Pricing Analysis
Geographic price spreads widen between Western European fertility networks and resource-constrained settings in Southern Europe, reflecting reimbursement differential impacts on procurement authority. Three-tier pricing structure across premium microfluidic platforms, standard density gradient systems, and economy centrifugation equipment dominates vendor catalogs. Cost compression in consumable tiers intensifies as Spanish regional networks negotiate bundled media-instrument packages. Public hospital systems in Germany exhibit lowest price sensitivity due to centralized GPO contracting, while independent outpatient clinics in emerging fertility markets face acute budget constraints.
Supply Chain Analysis
Specialized polydimethylsiloxane foundry capacity in Germany, Switzerland, and Japan constrains microfluidic channel production scaling for fertility device manufacturers. Supply draws from photolithography-grade silicon wafers, medical-grade elastomer formulations, and precision molding equipment. Single-source vulnerability concentrates in notified body auditing capacity for EU MDR compliance certification. Distribution runs through specialized medical device distributors serving fertility center networks, with direct-to-clinic logistics gaining share for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfluidic label-free processing threatens density gradient incumbents with protocol displacement, forcing established vendors to defend installed base relationships through workflow integration investments.
For Market Incumbents: Consolidate embryology workflow integration capabilities to deepen protocol stickiness against microfluidic substitution threats. Acquire complementary laboratory information system connectivity assets to reduce switching incentives for understaffed fertility clinics. Prioritize CE marking pathway acceleration under EU MDR to maintain procurement eligibility in German public hospital systems. For New Entrants and Emerging Players: Post-procedure support services for understaffed Spanish fertility networks represent the most penetrable white-space target, as incumbent vendors under-serve technical training and protocol optimization needs. Target regional fertility clusters in secondary Spanish cities with bundled installation-training packages. Pursue notified body relationship development as the critical go-to-market enabler for EU market access. For Investors and Strategic Acquirers: Capital is best deployed toward microfluidic platform specialists with established imaging-guided separation IP and regulatory submission momentum. Long-term viability centers on defensible workflow integration positions rather than consumable recurring revenue models. Monitor EU MDR notified body capacity expansion as the signal indicating certification bottleneck relief and accelerated market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance unlocks procurement eligibility across German public fertility networks. |
| Laboratory Information System Integration | Workflow connectivity reduces embryologist training burden in understaffed Spanish clinics. |
| Consumable-Platform Bundling | Integrated media-instrument contracts stabilize recurring revenue against microfluidic displacement. |
| Notified Body Relationship Development | Established auditing partnerships compress certification timelines for software-enabled devices. |
| Regional Fertility Network Partnership | Spanish cluster alliances accelerate microfluidic adoption in high-volume preprocessing workflows. |
Research Methodology
Desk research of regulatory submission databases, hospital procurement records, and fertility center capacity reports preceded structured interviews with embryology laboratory directors, medical device regulatory affairs specialists, GPO contract managers, and fertility clinic operations executives. Primary fieldwork across German and Spanish fertility networks validated technology adoption patterns and pricing negotiation dynamics. Secondary sources encompassed EU MDR notified body guidance documents, WHO laboratory standard protocols, and fertility society procedure volume surveys. Bottom-up demand modeling triangulated against top-down manufacturer revenue analysis.
Variance decomposition across technology platform, application procedure type, and end-user procurement channel shaped the analytical framework over the projection horizon. Segmentation dimensions encompassed separation mechanism, clinical use case, institutional buyer type, and product revenue model. CAGRs derived from procedure volume growth trajectories, technology substitution elasticity estimates, and consumable pricing trend analysis. Fertility center network consolidation patterns and regulatory certification timeline assumptions conditioned regional growth differentials.
Underlying assumptions cover EU MDR implementation stability, fertility procedure reimbursement continuity, and microfluidic manufacturing yield improvements, with deviation risk concentrated in notified body auditing capacity constraints and embryology workforce shortage intensification. Revision becomes warranted when microfluidic platform cost-performance thresholds cross density gradient parity levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Airway Management Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Critical Care Devices Market