
 Global Truck and Trailer Landing Gear Market | 2026-2036
Global Truck and Trailer Landing Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Truck and Trailer Landing Gear Market Intelligence
The substitution of high-strength steel alloys for traditional carbon steel in landing gear manufacturing is restructuring product economics and weight profiles. JOST Werke AG leverages its extensive OEM relationships to drive adoption of its lightweight designs. SAF-HOLLAND SE specializes in integrated axle and suspension systems that incorporate advanced landing gear. BPW Bergische Achsen KG anchors its market position through a focus on durability and performance in heavy-duty applications.
Truck and trailer landing gear is a mechanical or powered support system used to stabilize a semi-trailer when it is detached from its tractor. These devices are rated by static load capacity, typically ranging from 50,000 to 80,000 pounds, ensuring structural integrity during loading and unloading operations. While manual landing gear remains the dominant product type due to cost, the electric landing gear segment is a high-growth area for fleet operators seeking efficiency. Heavy-duty trailers form the largest application segment, though refrigerated trailers show significant growth.
Product design and market access are shaped by a matrix of national and regional safety standards, including those from the US National Highway Traffic Safety Administration (NHTSA) and China's GB standards. In Europe, regulations concerning vehicle dimensions and weights indirectly influence landing gear specifications to maximize payload efficiency. Stakeholder decisions will center on balancing the upfront capital cost of automated systems against the long-term operational benefits and labor savings.
Market Dynamics
The push for greater operational efficiency and enhanced operator safety is the central force shaping the truck and trailer landing gear market. This manifests through the adoption of lightweight materials to increase payload and the integration of automated, electric systems.
Growth Catalysts
- High-Strength Alloys:The use of advanced steel alloys reduces landing gear weight, contributing to higher vehicle payload capacity and improved fuel economy for fleet operators.
- Cold Chain Expansion:A growing global cold chain sector increases demand for specialized refrigerated trailers, which in turn require reliable and often high-capacity landing gear systems.
- Operator Safety Mandates:Regulations from bodies like the US Occupational Safety and Health Administration (OSHA) encourage the adoption of electric landing gear to reduce ergonomic injuries associated with manual cranking.
Market Restraints
- High Capital Cost:The significant upfront investment required for electric and automated landing gear systems presents a barrier for smaller fleet operators and owner-operators compared to lower-cost manual options.
- Input Material Volatility:The market's reliance on specialized high-strength steel alloys exposes manufacturers to price fluctuations and potential supply chain disruptions for these critical raw materials.
- Legacy Fleet Integration:Integrating modern electric landing gear systems with older trailers lacking the necessary power supply or control interfaces creates technical and cost challenges for retrofitting.
Strategic Opportunities
- Telematics Integration:The convergence of landing gear with onboard telematics systems creates opportunities for remote diagnostics, load sensing, and automated coupling/decoupling processes, offering new value-added services.
- Emerging Logistics Hubs:Modernizing logistics infrastructure in developing regions like Southeast Asia and Latin America presents an opportunity for market entry as demand for modern trailer equipment grows.
- Specialized Applications:Designing landing gear for niche, heavy-duty applications such as mobile medical units, broadcast vehicles, or military support platforms opens new, high-margin market segments.
Industry Challenges
- Mechatronics Skill Gap:A shortage of technicians trained to service and repair the electronic and mechatronic components of advanced landing gear systems challenges the after-sales support network.
- Interoperability Standards:The absence of a universal communication protocol between different brands of tractors and smart trailers complicates the seamless integration and functionality of automated landing gear.
- Regulatory Fragmentation:Designing products for a global market is complicated by the diverse and often conflicting vehicle weight and dimension regulations across different national and regional jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Truck and Trailer Landing Gear Market |
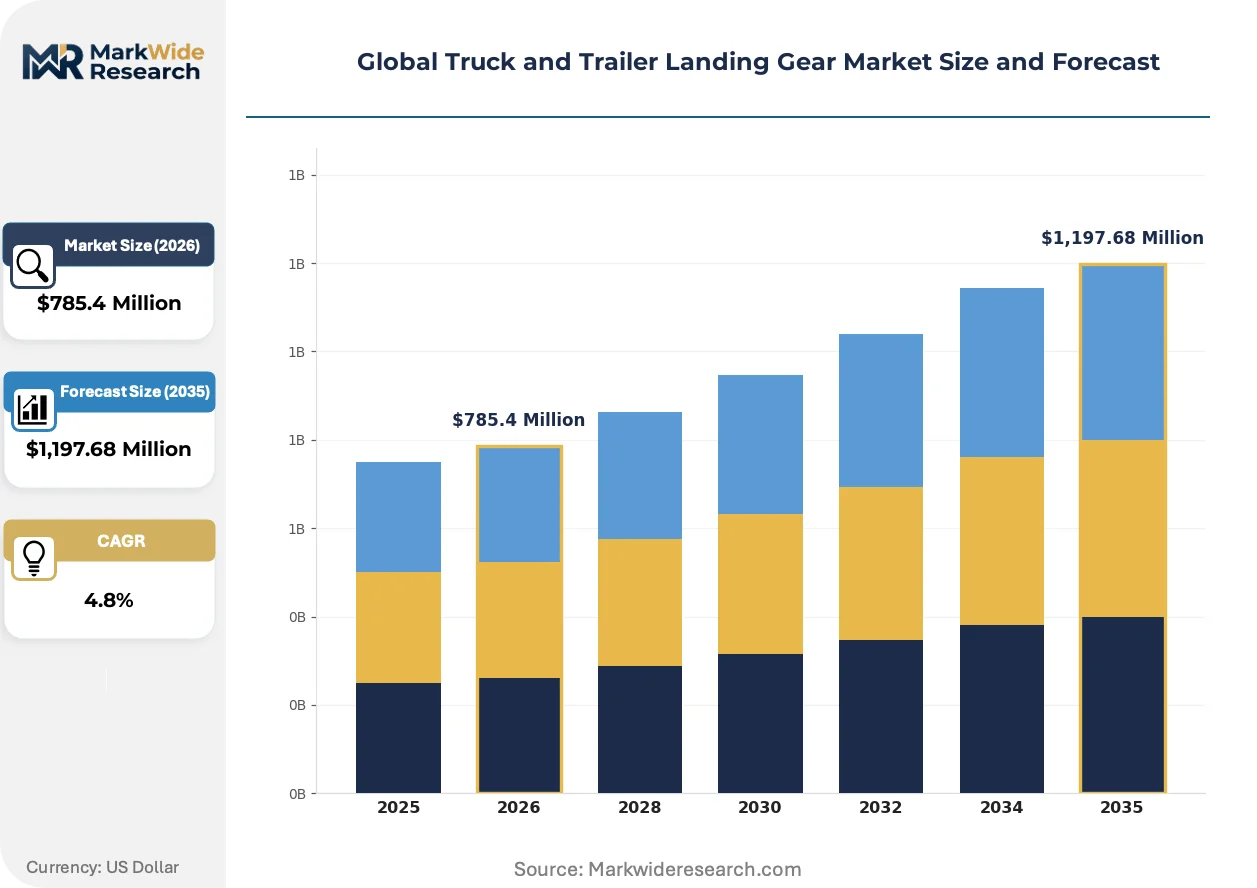
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,197.68 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Landing Gear, Electric Landing Gear, Pneumatic Landing Gear, Hydraulic Landing Gear Application: Heavy-Duty Trailers, Semi-Trailers, Flatbed Trailers, Refrigerated Trailers, Tank Trailers End User: Fleet Operators, Logistics Providers, Freight Forwarders, Leasing Companies Distribution Channel: OEMs, Aftermarket Dealers, Online Retailers, Specialized Distributors |
| Companies Covered | Guangdong Fuwa Engineering Group Co., Ltd., Haacon Hebetechnik GmbH, JOST Werke AG, Yangzhou Tongyi Machinery Co., Ltd., AXN Heavy Duty, SAF-HOLLAND SE, Butler Products Corp., Zhenjiang Baohua Semi-Trailer Parts Co., Ltd., BPW Bergische Achsen KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Truck and Trailer Landing Gear Market Strategic Shifts & Innovations
Intelligent automation and advanced material science are converging, transforming landing gear from a simple mechanical support into a critical data-generating node for fleet management. This evolution is driven by the dual pursuit of operational efficiency and enhanced safety protocols.
Smart landing gear systems incorporate integrated sensors to monitor load status, ground clearance, and extension height. Large fleet operators in logistics-intensive regions like the United States and Germany are the primary adopters of these technologies to improve asset utilization. This integration of sensing and control is modularizing the landing gear, elevating it from a passive component to an active, intelligent node within the trailer's electronic architecture.
European Union regulations concerning vehicle dimensions and weights indirectly incentivize the adoption of lighter components to maximize payload. This regulatory pressure pushes manufacturers to use materials like high-strength steel and aluminum alloys to reduce tare weight, which improves fuel efficiency per ton-kilometer. The heavy-duty trailer segment is most affected, as operators continuously seek to optimize cargo capacity within strict legal frameworks like those enforced by Germany's KBA.
Fleet managers are progressively shifting from reactive, break-fix maintenance cycles toward predictive service schedules for critical trailer components. This behavioral change disrupts the traditional aftermarket parts channel by favoring systems with built-in diagnostics and service-life indicators over simple replacement parts. The trend is most pronounced in North American and European fleets where total cost of ownership (TCO) is a primary consideration in procurement decisions.
Global Truck and Trailer Landing Gear Market Segmentation
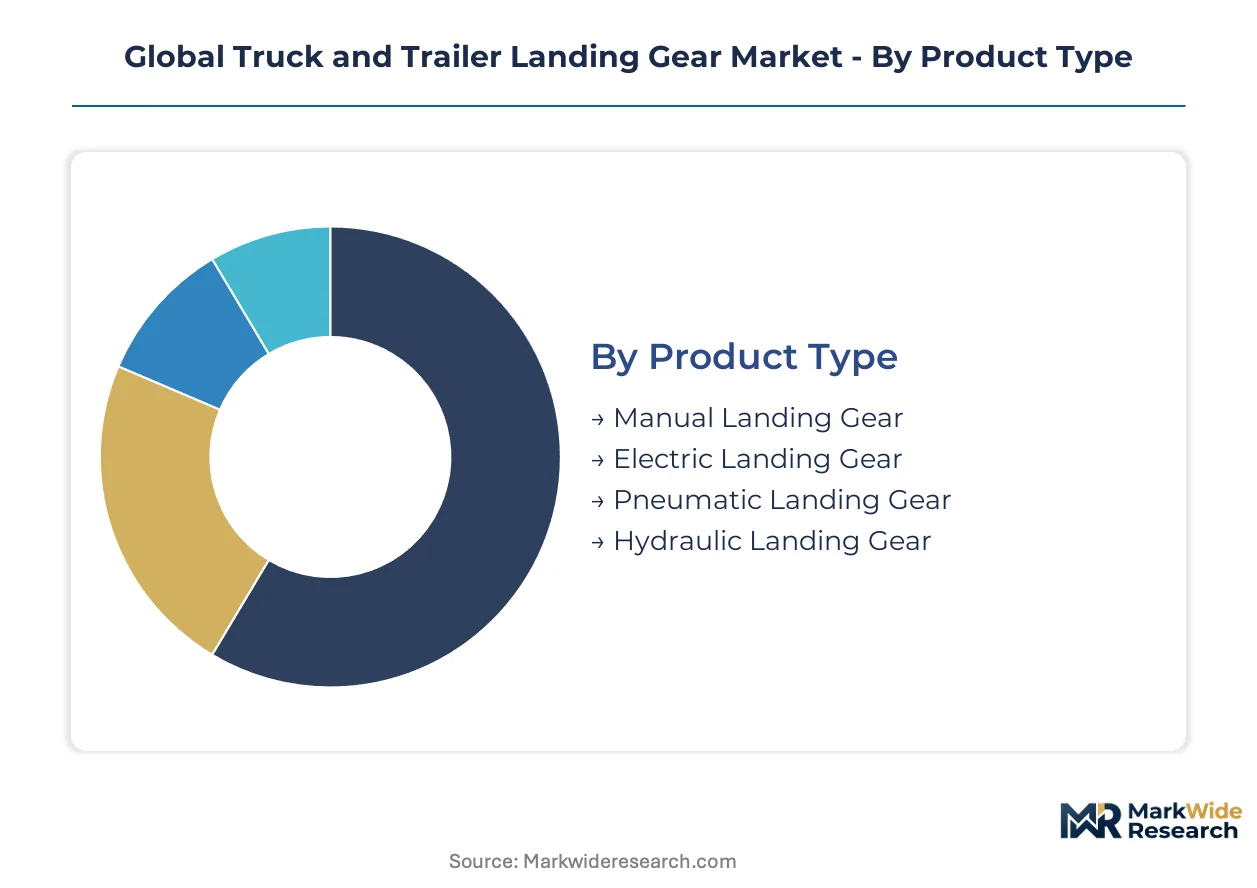
The global truck and trailer landing gear market is inherently segmented by distinct product attributes, application requirements, end-user preferences, and distribution pathways. Understanding these divisions is crucial for manufacturers to tailor product development and market strategies effectively. Each segment presents unique growth drivers and competitive dynamics.
Product Type:
The market for truck and trailer landing gear differentiates significantly based on the balance between high-volume, cost-effective solutions and premium systems offering advanced features and operational benefits.
- Manual Landing Gear:This product type relies on operator physical effort for deployment and retraction, dominating the market due to its lower initial cost and proven reliability in diverse operational settings. Demand remains consistent in smaller fleets and owner-operator segments globally.
- Electric Landing Gear:These systems utilize electric motors for automated operation, enhancing operator safety and reducing labor, particularly in high-volume logistics hubs across the United States and Germany. Efficiency gains and OSHA mandates drive its expanding adoption.
- Pneumatic Landing Gear:Pneumatic systems use compressed air from the truck's air brake system for deployment, offering a semi-automated solution with quicker operation than manual types. These find use in specialized applications where rapid trailer detachment is beneficial.
- Hydraulic Landing Gear:Hydraulic systems provide powerful and precise lifting capabilities, often preferred for very heavy loads or specialized trailers requiring fine control.
Today's leader: Manual Landing Gear. Tomorrow's challenger: Electric Landing Gear.
Application:
Landing gear specifications vary considerably across different trailer applications, reflecting diverse operational requirements and load capacities.
- Heavy-Duty Trailers:This segment includes trailers designed for transporting exceptionally heavy or oversized cargo, requiring landing gear with high static load capacities, often exceeding 80,000 pounds, to ensure stability during loading operations. Demand is robust in construction and industrial sectors in Europe.
- Refrigerated Trailers:Specialized refrigerated trailers, crucial for the expanding cold chain sector, require reliable landing gear capable of supporting temperature-controlled units and their specialized cargo. This segment exhibits significant growth in global logistics corridors.
- Semi-Trailers:Standard semi-trailers represent a broad application segment, utilizing a range of landing gear types depending on payload and operational frequency.
- Flatbed Trailers:Flatbed trailers, used for transporting diverse cargo that does not require enclosure, typically employ robust landing gear to support varied loading conditions.
- Tank Trailers:Tank trailers, designed for liquids or gases, require stable landing gear to manage dynamic shifts in load and prevent tipping during stationary operations.
Refrigerated trailers are expanding most quickly, while heavy-duty applications maintain consistent demand.
End User:
Distinct end-user segments exhibit varied procurement priorities, influencing demand for specific landing gear features and service models.
- Fleet Operators:Large fleet operators prioritize operational efficiency, driver safety, and total cost of ownership, driving the adoption of electric and smart landing gear systems. These operators often seek advanced diagnostic capabilities.
- Logistics Providers:Logistics providers focus on optimizing turnaround times and asset utilization, favoring landing gear solutions that offer quick deployment and robust performance to minimize downtime. German logistics firms are early adopters.
- Freight Forwarders:Freight forwarders, often managing diverse trailer types, seek versatile and durable landing gear that can adapt to various cargo and operational environments.
- Leasing Companies:Leasing companies focus on product longevity, ease of maintenance, and residual value, influencing demand for reliable and widely serviceable landing gear components.
Fleet operators and logistics providers collectively drive significant innovation and adoption within the market.
Distribution Channel:
The supply chain for landing gear is structured around diverse channels, each addressing distinct customer needs and product life cycle stages.
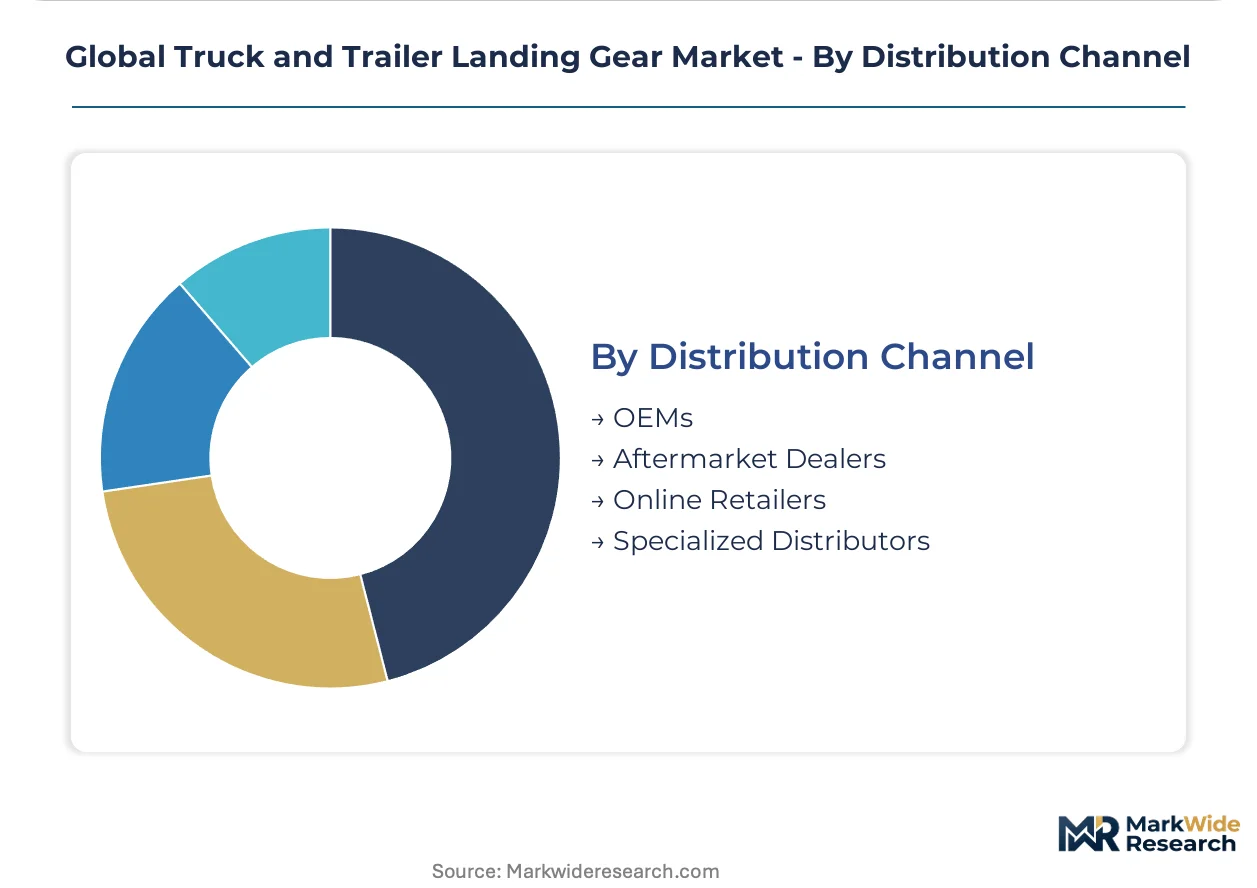
- OEMs:Original Equipment Manufacturers integrate landing gear directly into new trailer builds, influencing design specifications and material choices, particularly for high-volume production. JOST Werke AG leverages extensive OEM relationships.
- Aftermarket Dealers:Aftermarket dealers supply replacement parts and service components for existing trailers, catering to repair and maintenance needs throughout the equipment's operational life. This channel is critical for older fleets.
- Online Retailers:Online platforms offer a convenient channel for purchasing standard landing gear components and accessories, particularly for smaller operators and niche requirements.
- Specialized Distributors:Specialized distributors focus on specific product lines or geographic regions, providing tailored inventory and technical support to a focused customer base.
OEM relationships remain strategically vital, while aftermarket channels increasingly emphasize diagnostic capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major logistics corridors in the United States and Germany drive significant demand for truck and trailer landing gear. Expanding cold chain infrastructure boosts requirements for specialized equipment. Global trade patterns influence reliable support systems.
United States
The United States prioritizes operational efficiency and operator safety, driving electric landing gear adoption. US National Highway Traffic Safety Administration (NHTSA) standards guide product development. Midwest logistics hubs, particularly around Chicago, see substantial adoption for efficient freight handling.
Germany
Germany's heavy-duty applications and payload efficiency needs shape landing gear demand. KBA regulations on vehicle dimensions and weights influence specifications. The Rhine-Ruhr industrial region, home to major automotive suppliers, focuses on advanced material integration for lighter products.
China
China's infrastructure modernization and heavy-duty transport needs boost demand. China's GB standards influence landing gear specifications for domestic and export markets. The Yangtze River Delta manufacturing zone leads in producing high-volume, cost-effective solutions for global consumption.
India
India's expanding logistics networks and economic growth drive equipment requirements. The country's national road transport policies promote durable and robust trailer components. Industrial corridors around Delhi and Mumbai witness increased demand for standard and heavy-duty landing gear as freight volumes rise.
Brazil
Brazil's agricultural logistics and raw material transport sectors require stable gear. Brazil's national transport agency (ANTT) sets standards for vehicle safety and load capacity. The São Paulo industrial belt shows rising adoption due to its extensive road freight operations connecting major centers.
Global Truck and Trailer Landing Gear Market Key Industry Players
Strategic partnerships and technology integration dominate the current landscape, particularly among established players. The market exhibits a tiered structure, with global leaders focusing on advanced systems and regional manufacturers providing cost-effective solutions. Key archetypes include full-line providers, specialized component innovators, and regional volume manufacturers. Companies are pursuing both organic growth through R&D and inorganic expansion via collaborations to enhance product portfolios.
On the premium and integrated solutions vector, JOST Werke AG and SAF-HOLLAND SE exemplify global reach and product sophistication. JOST Werke AG, a German-based company, leverages extensive OEM relationships, representing a strategy focused on deep industry integration. SAF-HOLLAND SE, also from Germany, occupies a position specializing in integrated axle and suspension systems, showcasing a comprehensive approach to trailer components. BPW Bergische Achsen KG, another German entity, anchors its market presence through a focus on durability and heavy-duty performance, catering to demanding applications. These entities collectively underscore the market's emphasis on engineering excellence and robust product offerings.
| Leading Market Players |
|---|
| Guangdong Fuwa Engineering Group Co., Ltd. |
| Haacon Hebetechnik GmbH |
| JOST Werke AG |
| Yangzhou Tongyi Machinery Co., Ltd. |
| AXN Heavy Duty |
| SAF-HOLLAND SE |
| Butler Products Corp. |
| Zhenjiang Baohua Semi-Trailer Parts Co., Ltd. |
| BPW Bergische Achsen KG |
| Others |
Cost & Logistics Intelligence
Large fleet operators and Original Equipment Manufacturers (OEMs) concentrate procurement, driving a contract-based pricing model for landing gear systems. This structure influences long-term supply agreements and incentivizes cost-efficiency throughout the production chain.
Pricing Analysis
Input material volatility, particularly for high-strength steel alloys, directly impacts landing gear manufacturing costs. Pricing stratifies across premium, standard, and economy tiers, reflecting product features and durability. Differentiation drivers include static load capacity, brand reputation from manufacturers like JOST Werke AG, and the integration of advanced features such as electric motors. Pricing pressure stems from intense competition in the manual landing gear segment. Small fleet operators and owner-operators exhibit the highest price sensitivity, while large logistics providers prioritize total cost of ownership and operational uptime.
Supply Chain Analysis
High-strength steel alloy supply rests on specialized producers primarily located in Germany and China, forming critical material dependencies. Electric motors and sensor components for advanced landing gear systems also source from a concentrated global base. Commodity price volatility for steel presents a structural supply chain risk. Downstream, distribution primarily centers on direct integration with trailer OEMs, complemented by a robust aftermarket network of dealers for replacement parts and service components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global truck and trailer landing gear market is a stable compounder, driven by the essential and non-discretionary nature of logistics infrastructure globally.
For Market Incumbents:
Anchor existing market share by deepening OEM relationships and investing in next-generation material science for lighter, more durable products. This strategy helps mitigate the threat of new entrants specializing in niche applications. Invest in advanced certification processes, particularly for regulatory bodies like the US National Highway Traffic Safety Administration (NHTSA) and Germany's KBA, to reinforce product quality and compliance. Expand aftermarket service networks to support the growing complexity of electric and smart landing gear systems.
For New Entrants and Emerging Players:
Online retail platforms offer a viable digital-channel route for market entry, targeting smaller fleet operators seeking cost-effective, easily accessible components. Focus on specialized applications, such as landing gear for mobile medical units or broadcast vehicles, where performance specifications allow for higher margins. Develop modular, retrofit-friendly electric landing gear solutions for older trailers, providing a clear value proposition around labor savings and enhanced operator safety. Emphasize a total cost of ownership approach in marketing to penetrate the mid-tier fleet segment.
For Investors and Strategic Acquirers:
Industrial technology conglomerates are the most active acquirers in this space, seeking to integrate critical trailer components into broader logistics solutions. The market offers sustained demand over the next decade due to continuous freight volume expansion and infrastructure modernization. Target specialized component innovators focusing on mechatronics, sensor integration, or advanced material composites. A signal to watch is the increasing standardization of communication protocols between smart trailers and tractors, indicating readiness for broader adoption of automated systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Electric Landing Gear with Integrated Telematics | This innovation enhances operational efficiency and provides critical data for fleet management, improving asset utilization. |
| Strategic Partnership: OEM Integration with Major Trailer Manufacturers | Securing high-volume contracts ensures market penetration and establishes design influence for new trailer builds. |
| Capacity Expansion: High-Strength Steel Component Manufacturing | This investment mitigates supply chain risks and supports the production of lighter, more durable landing gear systems. |
| Certification Investment: Compliance with EU Vehicle Dimension Regulations | Adhering to strict European standards ensures market access and reinforces product quality for demanding applications. |
| Geographic Expansion: Entry into Southeast Asian Logistics Hubs | Tapping into modernizing infrastructure in developing regions unlocks new demand for advanced trailer equipment. |
Research Approach
Direct dialogue with fleet managers, trailer OEM engineers, logistics operators, and raw material suppliers provided qualitative insights into market dynamics. This primary research was rigorously validated through extensive secondary data analysis. Key secondary sources included US National Highway Traffic Safety Administration (NHTSA) reports, Germany's KBA vehicle registration data, industry association publications, and financial filings of public companies. A combination of bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
The quantitative model produced detailed market sizing, segment growth rates, and future trends across the projection horizon. This analytical framework combined quantitative and qualitative analysis to define market trajectories. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and regional regulatory environments. Compound Annual Growth Rates (CAGRs) were derived through regression analysis and validated against market growth assumptions. Key forecast inputs included raw material price forecasts and global freight volume projections.
The model assumes a particular technology adoption path; alternative pathways for autonomous trucking technology would alter the outlook. Forecasts reflect assumptions documented through expert consensus and historical market performance. Geopolitical trade tensions and rapid shifts in regulatory frameworks present specific risk factors that could revise these forecasts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Child Seats Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Global Bearings Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Engine Components Market
Vehicle Components
Global Air Spring Components Market