
 Trailer Landing Gear Market | 2026-2036
Trailer Landing Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Landing Gear Market Analysis
Electrification of auxiliary trailer systems is fragmenting the traditional manual-gear supply base into three distinct technology tiers. JOST Werke AG leverages its European manufacturing footprint to dominate electric landing gear development for premium fleet contracts. SAF-Holland SE anchors its position through backward integration into gear motor production, securing component availability across volatile supply cycles.
Trailer landing gear comprises the retractable support apparatus mounted at the front of semi-trailers, typically fabricated from high-strength steel with zinc-phosphate surface treatments to withstand cyclic loading and corrosive road environments; its primary function is to stabilize uncoupled trailers during loading, unloading, and parking operations. Steel remains the dominant material category due to its fatigue resistance and repairability, though aluminum gains share in weight-sensitive tanker and refrigerated trailer configurations where payload optimization directly affects freight economics. Electric product types command the fastest expansion trajectory as fleet managers prioritize driver retention through ergonomic improvements, while manual systems retain cost-driven demand in emerging-market logistics and agricultural transport segments.
The Federal Motor Carrier Safety Administration and OSHA jointly shape product safety mandates through trailer equipment inspection protocols and workplace ergonomics standards, compelling fleet operators to document landing gear operational condition during roadside enforcement stops. In Europe, the EU General Safety Regulation and UNECE vehicle type-approval frameworks require electromagnetic compatibility testing for electric landing gear systems, adding certification layers that filter smaller suppliers from cross-border contracts. Stakeholders must monitor the divergence between regional electrification timelines and the residual service life of installed manual gear bases to calibrate replacement revenue forecasts and aftermarket parts provisioning.
Market Dynamics
Electrification of trailer auxiliary systems is compressing replacement cycles as fleet operators reconcile OSHA ergonomic mandates with residual manual gear service life. The collision between regulatory compliance timelines and capital deployment schedules now governs procurement velocity across North American logistics networks.
Growth Catalysts
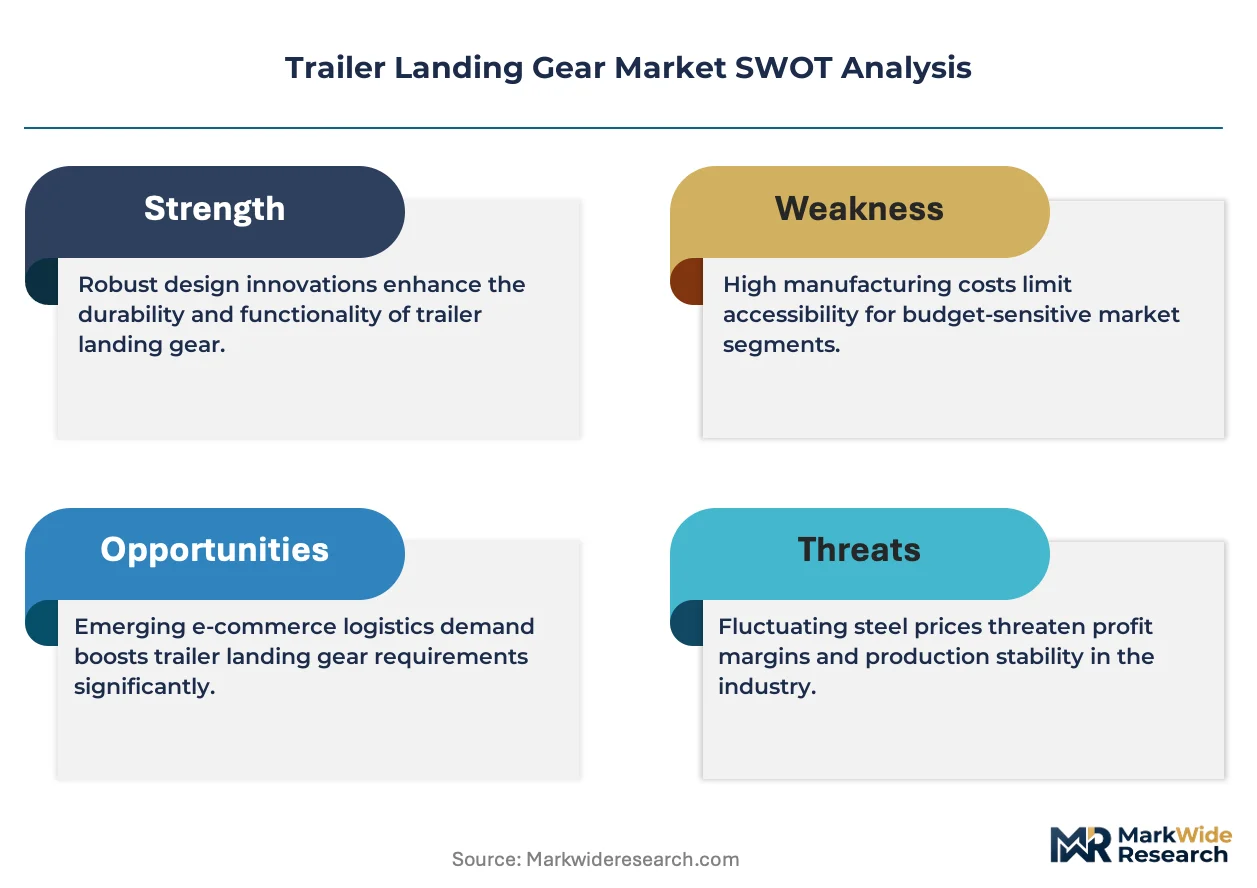
- OSHA workplace safety enforcement:Inspection protocols for trailer equipment operational condition compel documented landing gear maintenance, accelerating replacement of aging manual systems in United States trucking fleets.
- Electric actuation technology:Fleet managers prioritize driver retention through ergonomic improvements, pulling demand toward motorized landing gear configurations that eliminate repetitive cranking injuries.
- Tanker and refrigerated trailer segments:Payload optimization economics in weight-sensitive configurations drives specification of aluminum landing gear variants for freight efficiency gains.
Market Restraints
- High-strength steel price volatility:Cyclic loading requirements for landing gear fabrication tie production costs to commodity steel markets, compressing margin stability for fabricators.
- Electromagnetic compatibility certification:UNECE type-approval frameworks for electric systems impose testing layers that filter smaller suppliers from cross-border European contracts.
- Manual system residual base:Extended service life of installed mechanical gear in agricultural transport and emerging-market logistics delays revenue recognition for electric product lines.
Strategic Opportunities
- Aftermarket parts provisioning:Divergence between regional electrification timelines and installed manual base life creates service revenue pools for replacement gear motors and leg assemblies.
- EU General Safety Regulation alignment:Electromagnetic compatibility mandates open premium fleet contracts for suppliers with pre-certified electric landing gear platforms.
- Telematics integration:Landing gear position sensors and operational data feeds converge with fleet management systems, enabling predictive maintenance service models.
Industry Challenges
- Electromechanical technician scarcity:Hydraulic and electric actuation systems require specialized diagnostic capabilities that outpace vocational training program outputs.
- Legacy trailer integration:Retrofit compatibility with existing kingpin configurations and frame geometries complicates electric landing gear deployment across mixed-age fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Landing Gear Market |
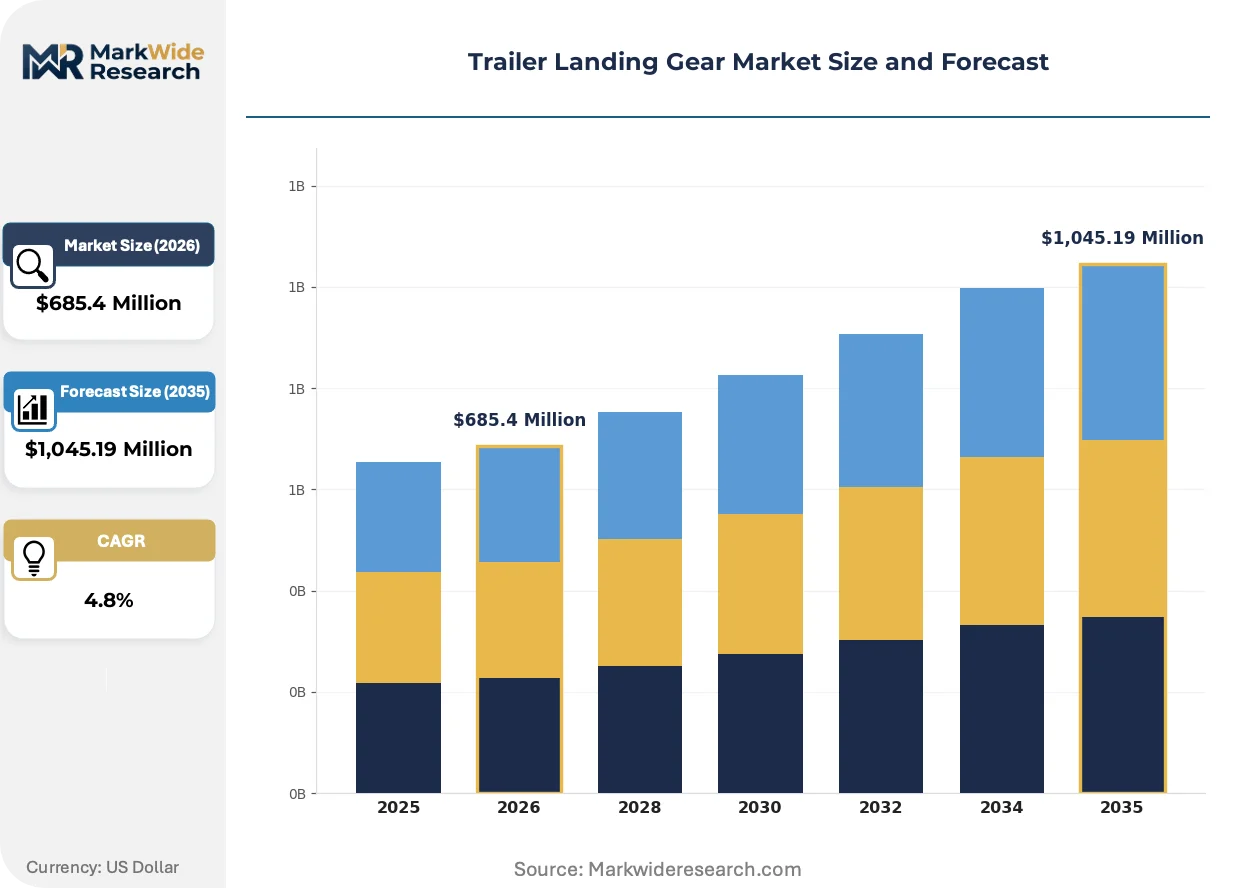
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Hydraulic, Electric, Pneumatic Material: Steel, Aluminum, Composite, Cast Iron Installation Type: Fixed, Retractable, Adjustable, Detachable End User: Logistics, Transportation, Construction, Agriculture |
| Companies Covered | Guangdong Fuwa Engineering Group Co. Ltd, Butler Products, JOST Werke AG, Yangzhou Tongyi Machinery Co. Ltd, Zhenjiang Baohua Semi-Trailer Parts Co. Ltd, SAF-Holland SE, AXN Heavy Duty, Haacon Hebetechnik GmbH, BPW Bergische Achsen KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Landing Gear Market Emerging Trajectories
Technology trajectories in trailer landing gear are converging around three vectors: actuation electrification, materials lightweighting, and connected equipment diagnostics. These developments are compressing traditional product lifecycles while opening new specification categories.
Brushless DC gear motors with integrated position feedback are collapsing the functional gap between manual and electric landing gear price points. Large United States trucking fleets now specify electric actuation as standard equipment on new dry van and refrigerated trailer orders. The technology is collapsing the historical three-tier supply structure into a bifurcated market of premium electric and residual manual demand.
OSHA workplace ergonomics standards and FMCSA equipment inspection protocols are jointly tightening documentation requirements for landing gear operational condition. Fleet operators must now maintain service records accessible during roadside enforcement stops. The United States long-haul segment is responding with telematics-linked maintenance scheduling systems that automate compliance paper trails.
Steel procurement patterns are fragmenting as weight-sensitive tanker and refrigerated trailer operators specify aluminum landing gear variants. Tier-1 fleet buyers now separate specifications by freight category rather than applying uniform equipment standards across trailer pools. This behavior is most visible in United States temperature-controlled logistics, where payload tonnage directly affects per-mile economics.
Trailer Landing Gear Market Segmentation
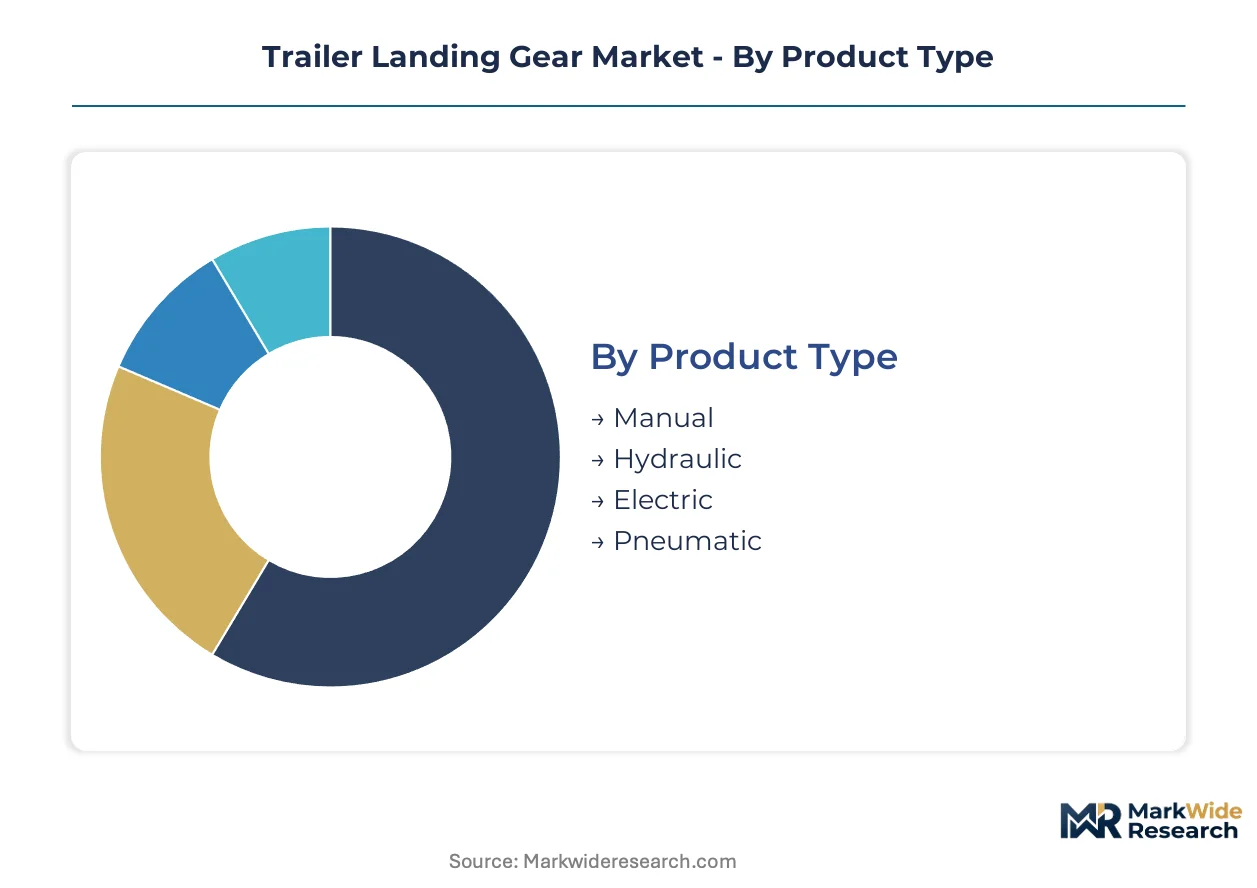
Trailer landing gear specifications fragment across actuation technologies, material grades, and mounting configurations that reflect divergent fleet economics. Procurement patterns now separate premium ergonomic systems from cost-optimized mechanical alternatives based on route profiles and driver retention priorities.
Product Type:
The use-case spectrum spans hand-cranked legacy equipment through fully motorized actuation systems serving distinct labor-cost environments.
- Manual:Mechanical crank mechanisms fabricated from hardened steel with zinc-phosphate coatings dominate agricultural transport and emerging-market logistics where capital constraints override ergonomic concerns. Extended service life of 15-20 years delays replacement revenue recognition for electric alternatives in price-sensitive segments.
- Electric:Brushless DC gear motors with integrated position feedback eliminate repetitive strain injuries and compress dwell time at distribution centers. Large United States trucking fleets now specify electric actuation as standard on refrigerated and dry van trailers to meet OSHA workplace ergonomics mandates.
- Hydraulic:Fluid-power actuation systems deliver high load capacity for heavy-haul and specialized trailer configurations requiring rapid deployment cycles.
- Pneumatic:Compressed-air systems integrate with existing trailer air supply infrastructure in tanker and bulk-haul segments where weight minimization competes with power density requirements.
The dominant share belongs to Manual systems, while Electric is closing the gap fastest.
Material:
Cost tier differentiation separates commodity steel specifications from premium lightweight alloys serving payload-optimization economics.
- Steel:High-strength alloy formulations with fatigue resistance exceeding 100,000 load cycles anchor specifications for general freight and construction trailers. Cyclic loading requirements tie production economics to volatile commodity steel markets, compressing margin stability for fabricators.
- Aluminum:Extruded aluminum leg assemblies reduce unsprung weight by 40-50% compared to steel equivalents, directly improving fuel economy in temperature-controlled logistics where payload tonnage affects per-mile economics.
- Composite:Fiber-reinforced polymer components gain trial placement in corrosion-critical chemical tanker applications.
- Cast Iron:Ductile iron housings provide vibration damping for hydraulic power units in heavy-haul configurations.
Steel commands the largest installed base, though Aluminum is gaining share fastest in weight-sensitive segments.
Installation Type:
Application flexibility requirements separate permanent mounting solutions from reconfigurable systems serving multi-purpose fleet operations.
- Fixed:Welded leg assemblies with non-adjustable stroke lengths dominate dedicated-route dry van operations where trailer geometry remains constant. Standardized kingpin heights across North American logistics networks reduce specification complexity for fixed-mount systems.
- Retractable:Telescoping leg mechanisms with nested tube construction enable ground clearance optimization across uneven loading surfaces. United States construction and agriculture segments specify retractable configurations for off-pavement deployment.
- Adjustable:Variable-height landing gear accommodates multi-customer trailer pools with divergent dock height requirements.
- Detachable:Quick-release mounting systems support seasonal fleet reconfiguration in agricultural harvest logistics.
Fixed installations hold the dominant position, while Retractable systems are expanding most quickly in mixed-terrain applications.
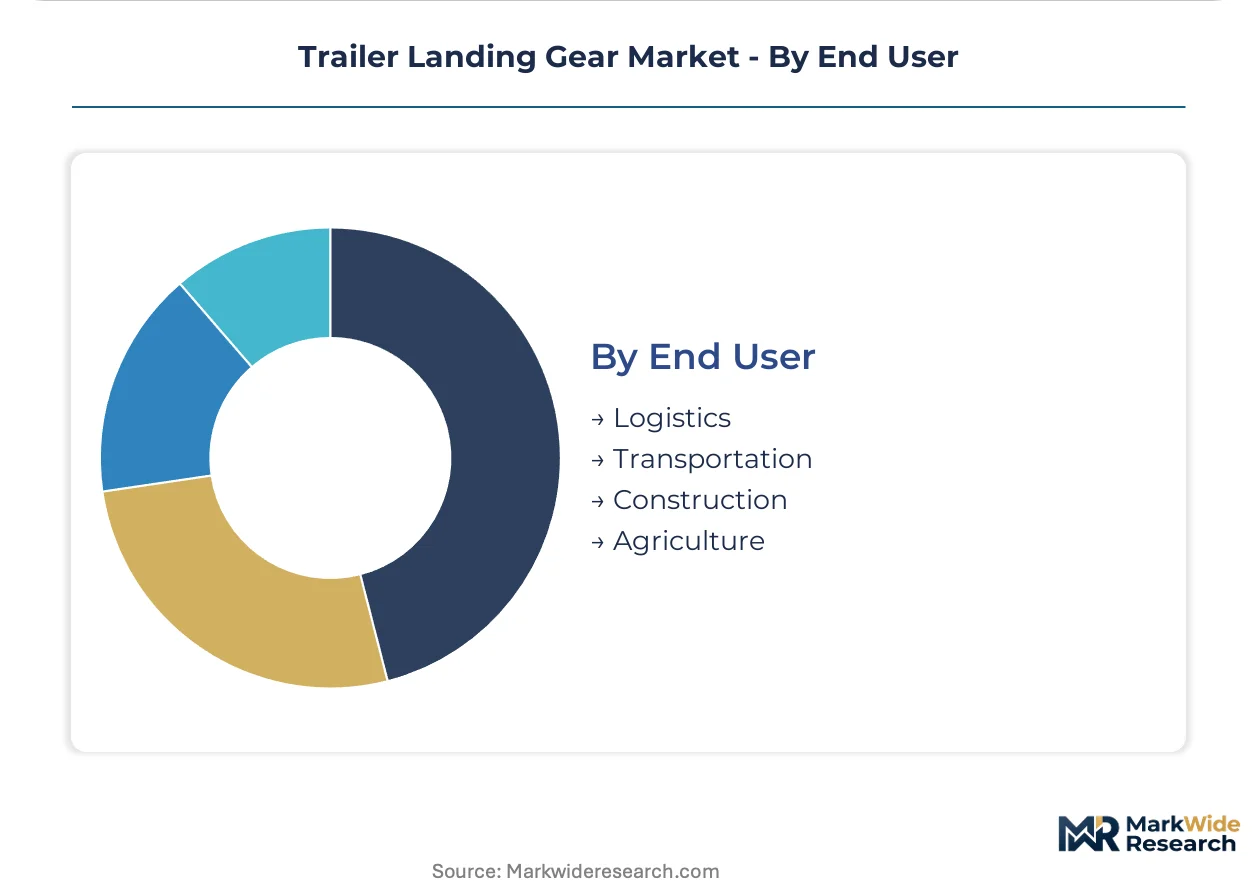
End User:
Customer-type segmentation separates high-velocity logistics networks from seasonal and project-based demand patterns with divergent replacement cycles.
- Logistics:Third-party and dedicated fleet operators prioritize electric actuation and telematics integration to document OSHA compliance and reduce driver turnover. FMCSA equipment inspection protocols compel documented maintenance records accessible during roadside enforcement stops.
- Transportation:For-hire trucking companies balance capital deployment schedules against regulatory compliance timelines, creating procurement velocity governed by residual manual gear service life.
- Construction:Project-based demand cycles and rough-terrain deployment favor retractable hydraulic systems with enhanced ground clearance.
- Agriculture:Seasonal utilization patterns and extended equipment lifecycles sustain manual system demand despite ergonomic disadvantages.
Logistics commands the dominant revenue share, while Transportation is climbing the fastest as compliance mandates accelerate fleet-wide upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators export precision-engineered electric landing gear systems to United States fleet operators modernizing under OSHA workplace safety mandates. Cross-Atlantic component flows now dominate premium electrification contracts.
United States
Large trucking fleets in the United States accelerate replacement cycles for manual landing gear under OSHA ergonomic enforcement. The Federal Motor Carrier Safety Administration mandates documented equipment inspection records accessible during roadside stops. Manufacturing clusters in Michigan and Ohio concentrate stamping and assembly operations for domestic dry van and refrigerated trailer supply.
Germany
German suppliers anchor European electric landing gear development through UNECE type-approval expertise and electromagnetic compatibility certification. The EU General Safety Regulation filters smaller competitors from cross-border fleet contracts. Engineering centers around Munich and Stuttgart drive brushless DC motor integration for premium logistics specifications.
China
Chinese fabricators dominate steel landing gear production for cost-sensitive emerging-market logistics and agricultural transport segments. GB standards and MIIT industrial policy guide domestic manufacturing quality tiers. Production gravity concentrates in Guangdong and Jiangsu provinces serving Southeast Asian and African export demand.
Canada
Canadian fleet operators align procurement with United States OSHA compliance timelines while navigating Health Canada workplace safety guidelines. Cross-border integrated supply chains position Ontario and Quebec as landing gear distribution nodes for North American temperature-controlled logistics networks.
Mexico
Mexican trailer manufacturing hubs in Nuevo León and the Bajío Region supply United States logistics networks under USMCA trade provisions. Domestic fleet modernization lags northern neighbor adoption curves, sustaining manual system demand. Border-state assembly operations integrate German and United States-sourced electric actuation components for export-configured trailers.
Trailer Landing Gear Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three technology tiers. The supply base consolidates around electric actuation platforms while fragmenting in residual manual segments. Strategic archetypes include integrated gear motor producers, steel-forging specialists, and telematics-enabled system integrators. Competitive moves center on backward integration into motor production and electromagnetic compatibility pre-certification for European market access.
Among Germany-based engineering groups, JOST Werke AG and SAF-Holland SE exemplify the integrated-systems archetype. Chinese fabricators including Guangdong Fuwa Engineering Group Co. Ltd occupy positions in the steel-forging tier serving cost-optimized fleet specifications. Specialist producers such as Haacon Hebetechnik GmbH represent the precision-engineering segment focused on heavy-haul and specialized trailer configurations.
| Leading Market Players |
|---|
| Guangdong Fuwa Engineering Group Co. Ltd |
| Butler Products |
| JOST Werke AG |
| Yangzhou Tongyi Machinery Co. Ltd |
| Zhenjiang Baohua Semi-Trailer Parts Co. Ltd |
| SAF-Holland SE |
| AXN Heavy Duty |
| Haacon Hebetechnik GmbH |
| BPW Bergische Achsen KG |
| Others |
Supply Flow & Price Mechanics
The Detroit-Windsor freight corridor compresses pricing power for electric landing gear suppliers as cross-border manufacturing clusters concentrate brushless DC motor production. Cost dynamics in this corridor tether downstream price differentiation to upstream steel procurement volatility and tier-1 fleet volume commitments.
Pricing Analysis
Technology-generation pricing gaps separate legacy manual cranks from brushless DC electric systems and emerging hydraulic-pneumatic hybrids. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in economy-tier steel manual systems is intensifying because Chinese fabricators flood emerging-market channels. Agricultural transport operators exhibit highest price sensitivity; refrigerated fleet managers prioritize ergonomic premiums over unit cost.
Supply Chain Analysis
Extended payment terms from German engineering groups to Michigan stamping suppliers reveal supply-chain finance facilities anchoring cross-Atlantic component flows. Production gravity centers on Germany, China, and the United States. High-strength alloy steel, zinc-phosphate coatings, and brushless DC gear motors constitute critical input dependencies. Single-source vulnerability in electromagnetic compatibility testing laboratories constrains European market entry. Distribution runs through OEM trailer manufacturers and aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical technician scarcity constrains fleet electrification timelines, creating competitive advantage for suppliers with captive diagnostic training pipelines.
For Market Incumbents: Pre-empt emerging Chinese electric actuator entrants by securing UNECE pre-certification capacity and locking multi-year brushless DC motor supply agreements. Backward integration into gear motor production defends margin position against commodity steel volatility. For New Entrants and Emerging Players: Build out aftermarket service networks in United States agricultural regions where manual gear residual base sustains replacement part demand. Telematics integration for predictive maintenance offers the most penetrable go-to-market angle against established parts distributors. For Investors and Strategic Acquirers: Precision-engineering specialists with heavy-haul hydraulic expertise represent compelling acquisition targets as construction and energy logistics electrify. Long-term viability hinges on regulatory divergence between OSHA enforcement timelines and EU General Safety Regulation alignment. Electromagnetic compatibility certification backlog serves as the critical inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gear Motor Production | SAF-Holland SE's captive supply of brushless DC motors insulates against semiconductor cycle volatility. |
| UNECE Electromagnetic Compatibility Pre-Certification | Early certification investment filters smaller competitors from premium European fleet contracts. |
| Telematics-Enabled Predictive Maintenance | Position sensor data feeds integrate with fleet management systems to automate OSHA compliance documentation. |
| Aluminum Landing Gear Platform Development | Weight-sensitive refrigerated trailer operators achieve fuel economy gains through payload optimization. |
| Aftermarket Parts Provisioning Network Expansion | Service revenue pools emerge from divergence between regional electrification timelines and manual gear residual life. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet maintenance directors, OEM trailer procurement managers, aftermarket parts distributors, and electromechanical technicians, then refined against secondary validation. Fleet telematics providers, OSHA enforcement records, FMCSA inspection databases, and UNECE type-approval registries supplied quantitative benchmarks. Bottom-up segment sizing triangulated against top-down industry revenue estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Modeled dimensions span actuation technology, material grade, installation configuration, and end-user segment. CAGRs derived from logistic curve fitting to replacement cycle data and fleet electrification adoption rates. Steel price indices and driver injury claim frequencies served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese actuator manufacturers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Seals Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Engine Valve Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Sideloaders Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
HCV Axles Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Rolling Stock LED Lights Market