
 Hydraulic Actuators Market | 2026-2036
Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Actuators Market Analysis
Direct distribution from OEMs to large end-users is fragmenting as regional system integrators capture mid-tier manufacturing accounts. Bosch Rexroth AG leverages its captive hydraulics portfolio to control specification pipelines for heavy machinery builders. Parker Hannifin Corporation anchors North American aftermarket service networks for linear actuator refurbishment. Moog Inc. specializes in precision servo-hydraulic units for aerospace test rigs and flight simulation platforms.
Hydraulic actuators are fluid-powered mechanical devices that convert pressurized oil flow into linear or rotary motion, typically operating at pressures from 3,000 to 10,000 psi to generate force densities exceeding electromechanical alternatives. They serve critical functions in valve automation, flight control surfaces, heavy press operations, and offshore blowout preventer systems where high force-to-weight ratios and shock tolerance matter. Linear actuators dominate manufacturing and marine applications where stroke length and positional accuracy determine equipment compatibility. Rotary actuators command premium positioning in aerospace flight control and subsea valve actuation where torque density and fail-safe positioning justify higher system cost. Electric-hydraulic actuators represent the fastest-expanding product category as hybrid architectures reconcile hydraulic force output with electric control precision and energy recovery.
ISO 4413 governs hydraulic system safety and cleanliness standards that shape actuator seal design and filtration requirements for international market access. The EU Machinery Directive and CE marking mandate risk assessments for integrated actuator-machinery systems sold across European member states. In the United States, OSHA lockout/tagout regulations and EPA spill prevention rules influence hydraulic power unit placement and actuator maintenance protocols. Stakeholders must monitor evolving carbon border adjustments and embedded emissions accounting, as these mechanisms will increasingly differentiate actuator supply chains by energy intensity and material provenance rather than unit cost alone.
Market Dynamics
The EU F-Gas Regulation is compressing demand for pneumatic alternatives and redirecting capital toward sealed hydraulic architectures across process industries. Offshore operators in the North Sea and Gulf of Mexico are accelerating actuator replacement cycles to meet subsea integrity management mandates.
Growth Catalysts
- Subsea valve automation:Offshore oil and gas platform operators are expanding procurement for blowout preventer and Christmas tree actuation systems operating at depths exceeding 3,000 meters.
- REACH compliance:European manufacturers are reformulating hydraulic fluids and seal compounds to eliminate restricted phthalates and heavy metal additives, creating upgrade demand across installed bases.
- Industrial automation corridors:Germany's Stuttgart-Munich manufacturing belt is concentrating demand for precision linear actuators in automotive press lines and robotic material handling cells.
Market Restraints
- Specialized steel supply concentration:High-strength alloy cylinder barrel production clusters in select European and Japanese forging facilities, creating input bottlenecks during capacity constraints.
- Seal material technical limitations:Fluorocarbon elastomers face temperature-pressure trade-offs in deepwater applications that exceed current compound performance envelopes.
- Electromechanical substitution:Linear motor and ball screw systems are capturing force ranges below 50 kN in packaging and semiconductor automation where precision positioning outweighs power density requirements.
Strategic Opportunities
- India manufacturing expansion:The country's PLI scheme for heavy machinery and defense equipment is attracting actuator system integrators to establish local assembly and testing facilities.
- Energy recovery convergence:Electric-hydraulic hybrid architectures combining servo-motor control with hydraulic force multiplication are opening retrofit opportunities in existing press and injection molding installations.
- Digital distribution channels:Configuration-to-order platforms are enabling mid-tier manufacturers to bypass traditional distributor markups and access OEM specification databases directly.
Industry Challenges
- Embedded systems integration:Actuator-PLC communication protocols vary across Siemens, Rockwell, and Schneider ecosystems, forcing integrators to maintain multiple programming skill sets.
- ISO 4413 certification timelines:Third-party cleanliness verification and pressure testing for international market access extends product launch schedules by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Actuators Market |
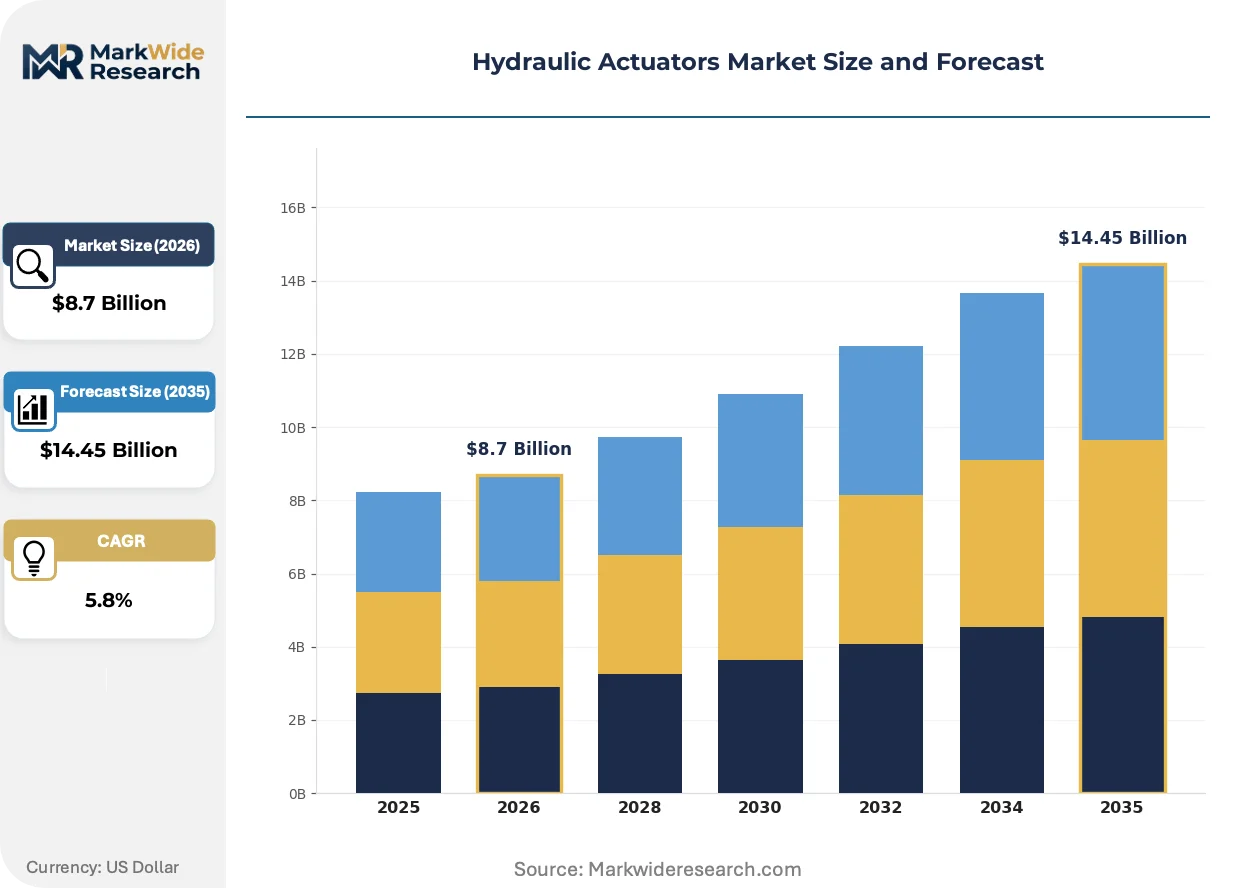
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Mini Actuators, Electric-Hydraulic Actuators Industry Vertical: Aerospace, Manufacturing, Marine, Automotive Power Source: Electric Power, Pneumatic Power, Hydraulic Power, Manual Control Type: Open Loop, Closed Loop, Proportional Control, On/Off Control |
| Companies Covered | Bosch Rexroth AG, Flowserve Corporation, Parker Hannifin Corporation, SMC Corporation, Rotork plc, Eaton Corporation plc, Emerson Electric Co., Curtiss-Wright Corporation, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Actuators Market Emerging Trajectories
Digital twin architectures are virtualizing actuator commissioning and predictive maintenance workflows across heavy machinery and offshore asset portfolios. Three developments are compressing traditional design-to-deployment cycles.
Digital hydraulic valve technology is virtualizing flow control functions through independently operated poppet arrays rather than centralized spool valves. Mining equipment builders in Australia and Chile are piloting these systems for shovel and dragline crowd control. The technology is virtualizing hydraulic system design by enabling software-configurable flow patterns that replace mechanical valve manifold redesigns.
EPA spill prevention rules and OSHA lockout/tagout protocols are mandating double-walled reservoir construction and automated isolation valve integration for hydraulic power units above 1,320 gallons. Industrial facilities in Texas and Louisiana are retrofitting existing skids to meet Secondary Containment requirements. The regulations are forcing capital allocation toward containment infrastructure rather than pure actuator performance upgrades.
Buyer consolidation among defense prime contractors and offshore engineering firms is compressing supplier qualification timelines and unbundling aftermarket service contracts from initial equipment procurement. Original equipment manufacturers in the aerospace test rig segment are responding by establishing captive refurbishment centers rather than ceding service revenue to third-party shops. The shift is most visible in US Department of Energy national laboratory procurement and Norwegian offshore contractor supply chains.
Hydraulic Actuators Market Segmentation
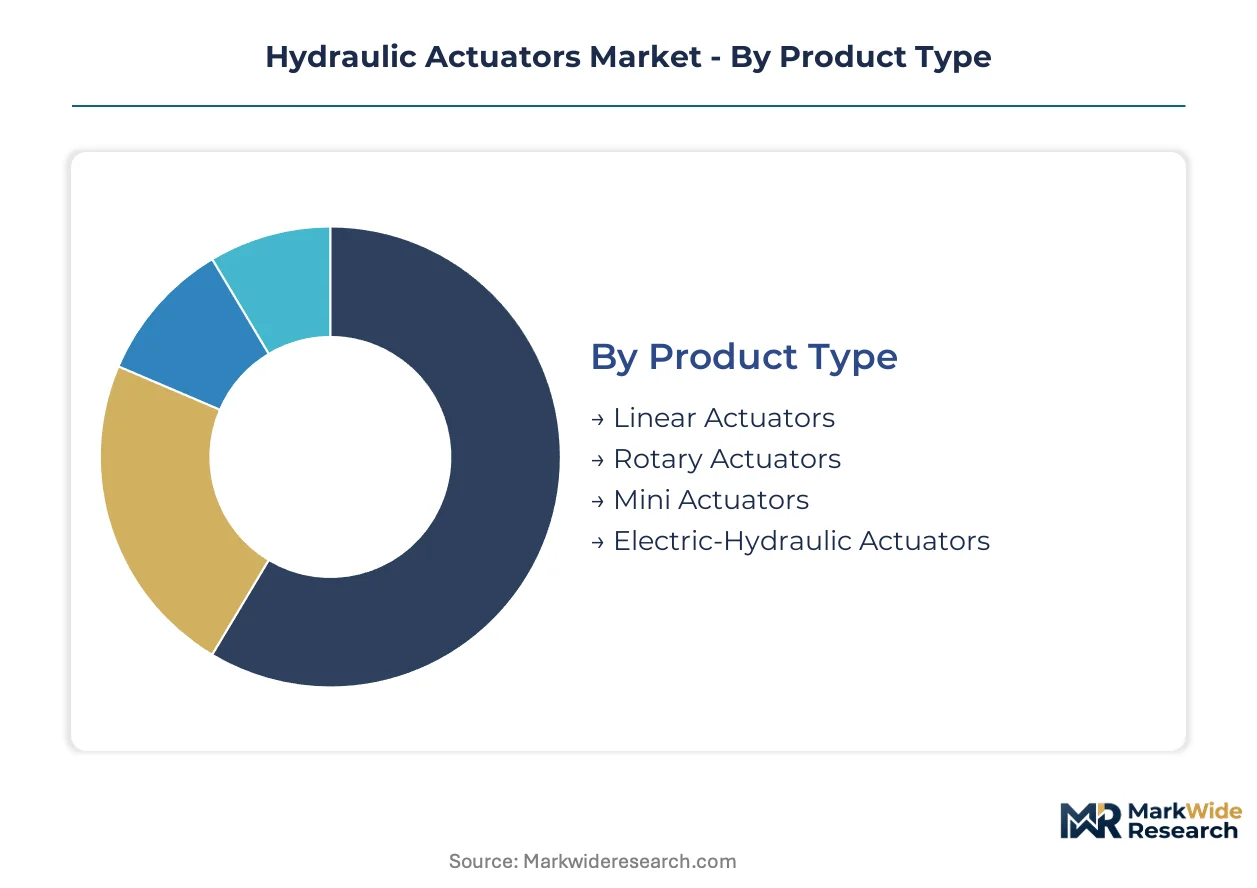
Segmentation in hydraulic actuators reveals distinct service lifecycle patterns. Linear systems in heavy press lines demand intensive refurbishment programs, while aerospace rotary units require precision recalibration contracts. Understanding these service intensity variations shapes margin capture across product categories.
Product Type:
After-sales service intensity varies dramatically by actuator architecture, with subsea rotary systems commanding multi-year maintenance agreements and mini actuators operating on replacement-only economics.
- Linear Actuators:Cylinder-piston configurations dominate manufacturing press lines and marine deck machinery where stroke length precision determines equipment compatibility. Demand concentrates in Germany's Stuttgart-Munich automation corridor for automotive body-in-white press applications, with automotive OEMs specifying ISO 4413 cleanliness certification as a procurement gate. These units require periodic seal replacement and rod re-chroming that sustains aftermarket revenue streams.
- Electric-Hydraulic Actuators:Hybrid architectures combine servo-motor control with hydraulic force multiplication, enabling energy recovery in existing press and injection molding retrofits. These systems are climbing the fastest as European manufacturers seek REACH-compliant fluid systems with lower leakage risk than pure hydraulic alternatives.
- Rotary Actuators:Rack-and-pinion or vane configurations deliver high torque density for subsea valve automation and aerospace flight control surfaces.
- Mini Actuators:Compact units serve semiconductor equipment and medical devices where space constraints override force requirements.
Linear actuators hold the largest share; momentum sits with electric-hydraulic hybrids.
Industry Vertical:
Cost tier stratification separates aerospace qualification requirements from manufacturing volume economics, with marine applications occupying a mid-tier position on total cost of ownership metrics.
- Manufacturing:Press lines, robotic material handling, and metal forming equipment constitute the volume foundation, with automotive stamping plants in Germany and the US specifying long-stroke linear units. These applications prioritize uptime availability and rapid seal kit deployment over absolute precision.
- Aerospace:Flight control surface actuation and test rig applications demand Moog-grade servo-hydraulic precision with fail-safe positioning and FAA certification documentation. North Sea helicopter operators and US Department of Energy national laboratories anchor procurement concentration.
- Marine:Subsea blowout preventer and Christmas tree actuation systems operate at depths exceeding 3,000 meters.
- Automotive:Assembly line automation and powertrain testing equipment represent a distinct demand cluster from manufacturing proper.
Manufacturing captures the greatest volume; aerospace commands the steepest expansion trajectory on test rig modernization.
Power Source:
Application context determines power architecture selection, with mobile equipment favoring self-contained hydraulic circuits and fixed industrial installations accepting centralized power units.
- Hydraulic Power:Centralized pump-and-reservoir systems serve heavy machinery where force density requirements exceed electromechanical alternatives, particularly in mining shovel crowd control and offshore platform valve automation.
- Electric Power:Electromechanical actuators capture force ranges below 50 kN in packaging and semiconductor automation where precision positioning outweighs power density.
- Pneumatic Power:Compressed air systems face compression from EU F-Gas Regulation compliance costs in process industries.
- Manual:Hand-pump or mechanical override systems provide emergency positioning for critical safety valves.
Hydraulic power retains dominant share; electric architectures gain fastest in sub-50 kN force ranges.
Control Type:
Customer type segmentation separates OEM specification control from end-user retrofit demand, with system integrators capturing mid-tier accounts through configuration-to-order platforms.
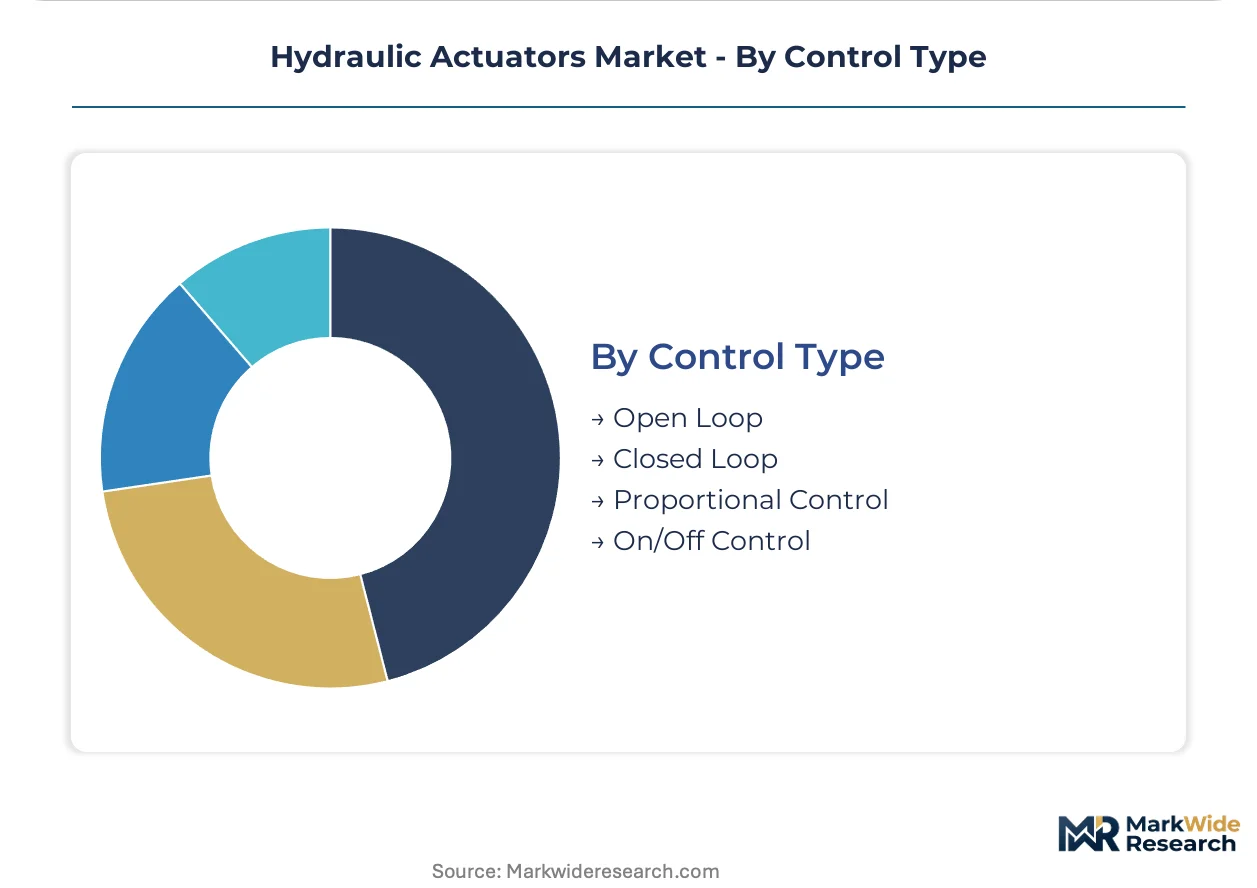
- Closed Loop:Sensor-feedback systems enable positional accuracy to ±0.01 mm for aerospace test rigs and semiconductor manufacturing, with Siemens and Rockwell PLC integration requiring specialized programming skill sets.
- Proportional Control:Variable flow modulation supports smooth acceleration profiles in robotic material handling and flight simulation platforms.
- Open Loop:Simple directional valve control suffices for applications where end-of-travel mechanical stops provide adequate positioning.
- On/Off Control:Binary positioning serves emergency shutdown and isolation valve functions where speed matters more than precision.
Closed loop systems lead on revenue per unit; proportional control expands most quickly on hybrid electric-hydraulic adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German system integrators serving Stuttgart-Munich automotive corridors, while North American distributors absorb margin compression from fragmented procurement channels. This asymmetry reflects divergent industrial automation densities and regulatory enforcement stringencies across manufacturing belts.
Germany
Automotive press line automation and robotic material handling concentrate demand for precision linear actuators. EU F-Gas Regulation enforcement redirects capital from pneumatic toward sealed hydraulic architectures in process industries. The Stuttgart-Munich corridor anchors specification control, with Bosch Rexroth AG leveraging captive hydraulics portfolios to dictate heavy machinery standards.
United States
Offshore blowout preventer replacement cycles and aerospace test rig modernization drive subsea and servo-hydraulic procurement. EPA spill prevention rules mandate double-walled reservoir construction for power units exceeding 1,320 gallons. Gulf Coast facilities in Texas and Louisiana retrofit existing skids to meet Secondary Containment requirements.
China
Mining equipment builders pilot digital hydraulic valve arrays for shovel and dragline crowd control. MIIT industrial upgrading programs accelerate domestic actuator assembly capacity. Yangtze River Delta manufacturing clusters absorb technology transfer from European joint ventures for high-pressure cylinder forging.
Norway
Subsea integrity management mandates accelerate actuator replacement cycles for North Sea platform operators. Petroleum Safety Authority regulations enforce blowout preventer testing frequencies at depths exceeding 3,000 meters. Stavanger-based engineering firms compress supplier qualification timelines and unbundle aftermarket contracts from initial procurement.
India
Defense equipment and heavy machinery PLI schemes attract actuator system integrators to establish local testing facilities. BIS certification requirements for hydraulic system safety create compliance barriers for imported equipment. Maharashtra and Gujarat industrial corridors concentrate assembly operations for mining and construction OEMs.
Hydraulic Actuators Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cylinder barrel and seal manufacturing. The vendor base organizes into three tiers: diversified industrial conglomerates with captive hydraulics portfolios, dedicated motion control specialists, and regional fabricators serving aftermarket refurbishment. Consolidation pressure concentrates at the mid-tier, where scale advantages in ISO 4413 certification timelines favor broader product portfolios. Dominant competitive moves include backward integration into high-strength alloy forging and geographic expansion through India-based assembly joint ventures.
Among diversified industrial conglomerates, Bosch Rexroth AG and Eaton Corporation plc occupy positions spanning specification control through aftermarket service networks. Parker Hannifin Corporation anchors North American linear actuator refurbishment economics. Moog Inc. exemplifies the precision servo-hydraulic specialist archetype, with positioning concentrated in aerospace test rig and flight simulation applications where fail-safe certification requirements create qualification moats.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Flowserve Corporation |
| Parker Hannifin Corporation |
| SMC Corporation |
| Rotork plc |
| Eaton Corporation plc |
| Emerson Electric Co. |
| Curtiss-Wright Corporation |
| Moog Inc. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation exposure on pneumatic alternatives is compressing pricing spreads between sealed hydraulic architectures and conventional systems while simultaneously reshaping supplier qualification timelines across European process industries. This regulatory chokepoint forces buyers to absorb certification premiums for REACH-compliant fluid formulations and ISO 4413 cleanliness verification, widening the gap between configured-to-order actuator procurement and standard catalog pricing.
Pricing Analysis
The customization-premium spread stretches widest between aerospace servo-hydraulic units with FAA certification documentation and standard linear actuators for manufacturing press lines. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and seal material specifications rather than force output alone. Cost compression in mid-tier manufacturing accounts is intensifying because regional system integrators are bypassing traditional distributor markups through configuration-to-order platforms. Automotive OEMs in Germany's Stuttgart-Munich corridor exhibit the lowest price sensitivity due to uptime availability requirements, while packaging and semiconductor automation buyers below 50 kN force ranges demonstrate highest elasticity to electromechanical substitution.
Supply Chain Analysis
High-strength alloy cylinder barrel feedstock draws from concentrated European and Japanese forging facilities, with specialty steel production clustering in Germany, Japan, and select Austrian metallurgical centers. Critical inputs include fluorocarbon elastomer seal compounds, precision-ground piston rods, and servo-valve electronics sourced from aerospace-qualified component streams. Single-source vulnerability sits with deepwater seal material suppliers whose temperature-pressure trade-offs exceed current compound performance envelopes at depths exceeding 3,000 meters. Distribution runs through OEM specification pipelines for heavy machinery builders, regional system integrators capturing mid-tier manufacturing accounts, and captive aftermarket service networks for linear actuator refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: ISO 4413 certification timelines and FAA fail-safe qualification requirements create four-to-eight-month barriers that protect incumbent positions against rapid displacement.
For Market Incumbents: Pre-empt electromechanical substitution below 50 kN by accelerating electric-hydraulic hybrid architectures that combine servo-motor control with hydraulic force multiplication. Backward integration into high-strength alloy forging secures input supply during capacity constraints while compressing third-party cleanliness verification timelines. Channel control through captive specification databases for heavy machinery builders reinforces specification pipeline dominance against regional system integrators.
For New Entrants and Emerging Players: Establish a beachhead in India's defense equipment and heavy machinery PLI scheme corridors where BIS certification requirements create compliance barriers for imported equipment and local assembly joint ventures attract technology transfer partnerships. The most penetrable white space sits with digital hydraulic valve arrays for mining shovel crowd control in Australia and Chile, where software-configurable flow patterns displace mechanical valve manifold redesigns. A configuration-to-order platform targeting mid-tier manufacturing accounts bypasses traditional distributor economics and accesses OEM specification databases directly.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision servo-hydraulic specialists with aerospace test rig positioning and captive refurbishment center networks. Long-term viability over a five-to-ten-year window rests on aftermarket service revenue capture rather than pure equipment sales, with unbundling trends compressing supplier qualification timelines. The signal to watch is Petroleum Safety Authority enforcement intensity on North Sea blowout preventer testing frequencies, as acceleration would trigger replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Secures cylinder barrel supply from European and Japanese metallurgical centers during capacity constraints. |
| Electric-Hydraulic Hybrid Architecture Development | Combines servo-motor control with hydraulic force multiplication for REACH-compliant press retrofits. |
| India-Based Assembly Joint Venture | Captures PLI scheme benefits for defense equipment while meeting BIS certification requirements locally. |
| Digital Hydraulic Valve Platform Launch | Enables software-configurable flow patterns for mining equipment builders in Australia and Chile. |
| Captive Refurbishment Center Network | Retains aftermarket service revenue against third-party shops in US Department of Energy procurement. |
Methodological Framework
A spread of perspectives from maintenance directors at automotive stamping plants, OEM procurement teams specifying ISO 4413 cleanliness certification, aftermarket service heads managing linear actuator refurbishment programs, and plant engineers in offshore platform operations converged on the working assumptions. These primary insights were cross-referenced against customs and trade data for high-strength alloy cylinder barrel movements, SEC filings from diversified industrial conglomerates with captive hydraulics portfolios, petroleum safety authority regulatory enforcement databases, and aerospace test rig procurement records. Bottom-up segment sizing across linear, rotary, electric-hydraulic, and mini actuator architectures was reconciled with top-down market aggregation through iterative triangulation.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation dimensions spanning product type, industry vertical, power source, and control type integration complexity. CAGRs were derived from installed base replacement cycle analysis, subsea integrity management mandate compliance timelines, and industrial automation corridor concentration patterns in Germany's Stuttgart-Munich belt. Forecast inputs incorporated REACH compliance-driven fluid reformulation upgrade demand, EU F-Gas Regulation redirection of capital from pneumatic systems, and embedded emissions accounting mechanisms differentiating supply chains by energy intensity.
Stress conditions across specialized steel supply concentration, seal material technical limitations in deepwater applications, and electromechanical substitution rates in sub-50 kN force ranges were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding offshore platform operator procurement expansion, automotive press line automation intensity, and aerospace test rig modernization trajectories. Cross-checking against Petroleum Safety Authority enforcement disclosure patterns and MIIT industrial upgrading program announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Car Accessories Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
RV Battery Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Motor Lamination Market