
 Engine Air Filter Market | 2026-2036
Engine Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Air Filter Market Intelligence
Commercial vehicle aftermarket demand is restructuring procurement patterns across the engine air filter supply base. Mann+Hummel leverages captive manufacturing scale across European and North American plants to anchor long-haul fleet contracts. Donaldson Company specializes in heavy-duty filtration systems for agricultural and construction applications. K&N Engineering differentiates through performance-oriented washable filter designs targeting enthusiast and racing segments.
An engine air filter is a replaceable porous media element installed at the air intake of internal combustion engines, typically constructed from pleated cellulose paper, synthetic fibers, or foam substrates with filtration efficiency ratings targeting particles above 5-10 microns to protect cylinder walls and piston rings from abrasive wear. Pleated paper filters occupy the highest volume share across passenger vehicle OEM fitments due to cost efficiency and standardized form factors. Nanofiber media filters represent the fastest-expanding technology tier as manufacturers pursue extended service intervals and sub-micron particulate capture for direct-injection engines. Dry air filters dominate commercial truck applications where oil bath maintenance complexity conflicts with fleet uptime requirements.
EPA tailpipe and evaporative emissions standards in the United States mandate sealed intake systems that accelerate filter replacement cycles and validate filtration integrity through onboard diagnostics. The EU F-Gas Regulation and CE marking requirements under the MDR framework shape product compliance pathways for European aftermarket suppliers. Stakeholders must monitor regulatory convergence between emissions enforcement and circular economy mandates as filter material recyclability becomes a procurement criterion for fleet sustainability programs.
Market Dynamics
EPA emissions enforcement is compressing replacement cycles across commercial truck fleets, while nanofiber media adoption extends service intervals in passenger vehicles—creating divergent demand pressures within the same supply base.
Growth Catalysts
- EPA Emissions Mandates:Sealed intake system requirements under tailpipe standards validate filtration integrity through onboard diagnostics, accelerating aftermarket replacement frequency.
- Direct-Injection Engine Proliferation:Gasoline direct-injection architectures demand sub-micron particulate capture to protect high-pressure fuel injectors from carbon deposit formation.
- Midwest Manufacturing Corridor Concentration:Pleated paper filter production clusters around Detroit, Chicago, and Cleveland, reducing logistics costs for domestic OEM fitments.
Market Restraints
- Cellulose Pulp Volatility:Raw material costs for pleated paper substrates fluctuate with forestry harvest cycles and pulp export demand from packaging sectors.
- Single-Source Nanofiber Supply:Electrospun media production concentrates among specialty chemical processors in Germany and Japan, creating import dependency for tier-one filter manufacturers.
- Washable Filter Substitution:Performance enthusiasts in light-duty segments migrate toward cleanable foam and cotton-gauze designs that eliminate recurring purchases.
Strategic Opportunities
- Commercial Fleet Electrification Gaps:Hybrid commercial vehicles retain internal combustion range-extenders requiring specialized high-dust-load filtration for construction and mining sites.
- EU Circular Economy Mandates:The CSRD framework and F-Gas Regulation incentivize recyclable filter media development and closed-loop material recovery programs.
- Telematics-Enabled Predictive Maintenance:Connected intake pressure sensors allow filter vendors to embed usage-based replacement alerts into fleet management platforms.
Industry Challenges
- Electrospinning Talent Scarcity:Nanofiber layer deposition requires polymer science expertise that competes with battery separator and medical textile industries.
- MDR Compliance Timelines:European aftermarket suppliers face extended CE marking documentation periods for filtration products with antimicrobial claims.
- Legacy ERP Integration:Tier-two manufacturers struggle to connect IoT-enabled filter monitoring with established dealer inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Air Filter Market |
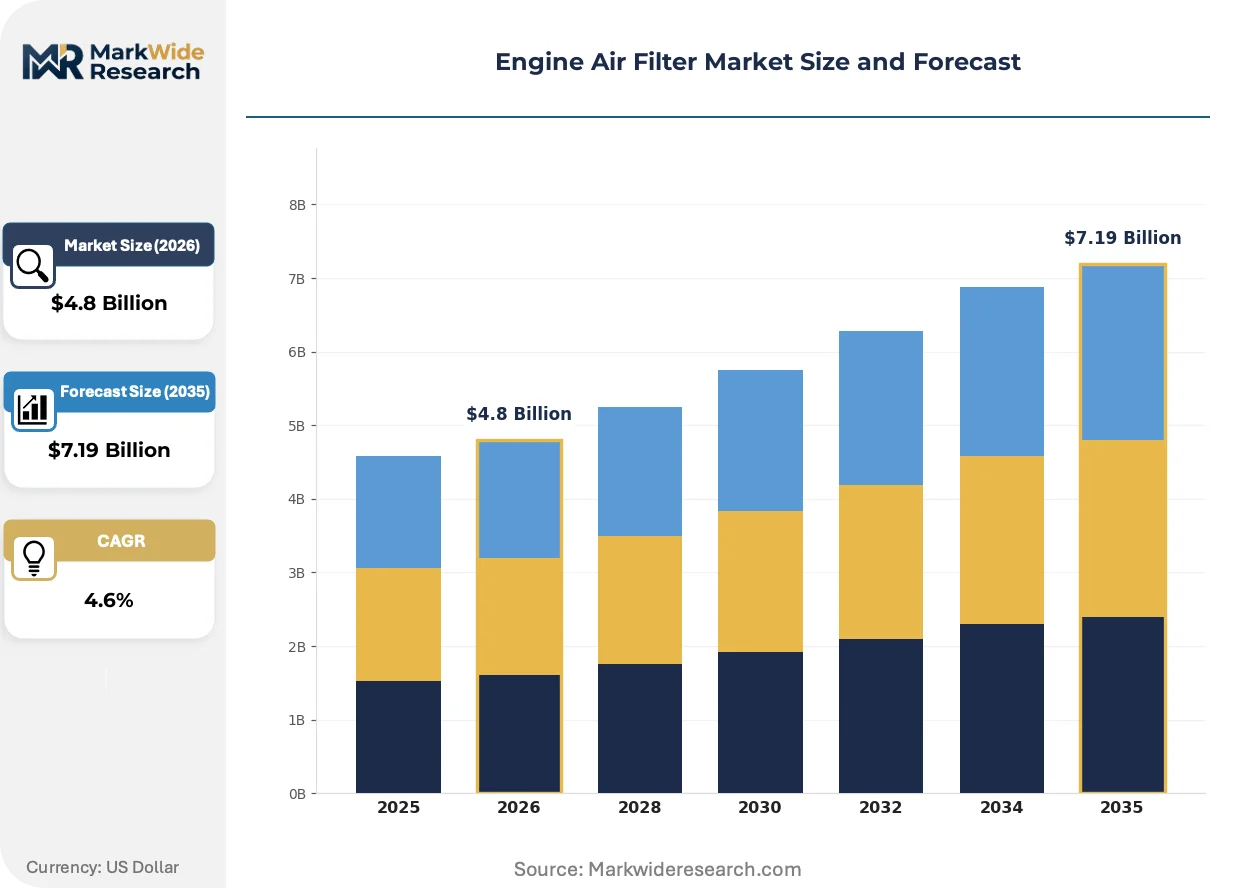
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Filters, Cartridge Filters, Foam Filters, Synthetic Fiber Filters, Pleated Paper Filters Technology: Dry Air Filters, Oil Bath Filters, Electrostatic Filters, Multi-Layer Media Filters, Nanofiber Media Filters Application: Passenger Vehicles, Commercial Trucks, Agricultural Machinery, Construction Equipment, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Fleet Operators, Independent Repair Shops, Vehicle Assemblers |
| Companies Covered | Mann+Hummel, Donaldson Company, MAHLE GmbH, Denso Corporation, K&N Engineering, Robert Bosch GmbH, Sogefi Group, Hengst SE, Baldwin Filters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Air Filter Market Strategic Shifts & Innovations
Filter media architectures are bifurcating between extended-life synthetic designs for passenger vehicles and ruggedized disposable formats for commercial uptime requirements. Material science advances and embedded sensor integration are redefining value capture points in the aftermarket.
Nanofiber surface-loading technology is decentralizing maintenance scheduling across long-haul trucking operations. Electrospun polymeric layers capture sub-micron particulate at the filter surface rather than within depth media, enabling visual inspection protocols that reduce unnecessary replacements. Major fleet operators in Texas and California are piloting condition-based swaps that cut annual filter expenditures while preserving engine protection.
The EPA's evolving greenhouse gas standards for heavy-duty engines are mandating intake air temperature and pressure monitoring as part of emissions certification. This regulatory architecture forces filter housing redesigns to accommodate sensor ports and sealed electrical connections. Aftermarket suppliers serving the US commercial vehicle segment must now engineer retrofit-compatible sensor integration without compromising filtration efficiency.
Fleet procurement departments are consolidating filter purchasing through integrated maintenance contracts that bundle lubricants, fluids, and filtration under single-source agreements. Independent distributors lose shelf space as national leasing companies negotiate direct supply relationships with Mann+Hummel and Donaldson. This concentration is most pronounced among for-hire trucking fleets operating across the I-80 corridor from Illinois to Pennsylvania.
Engine Air Filter Market Segmentation
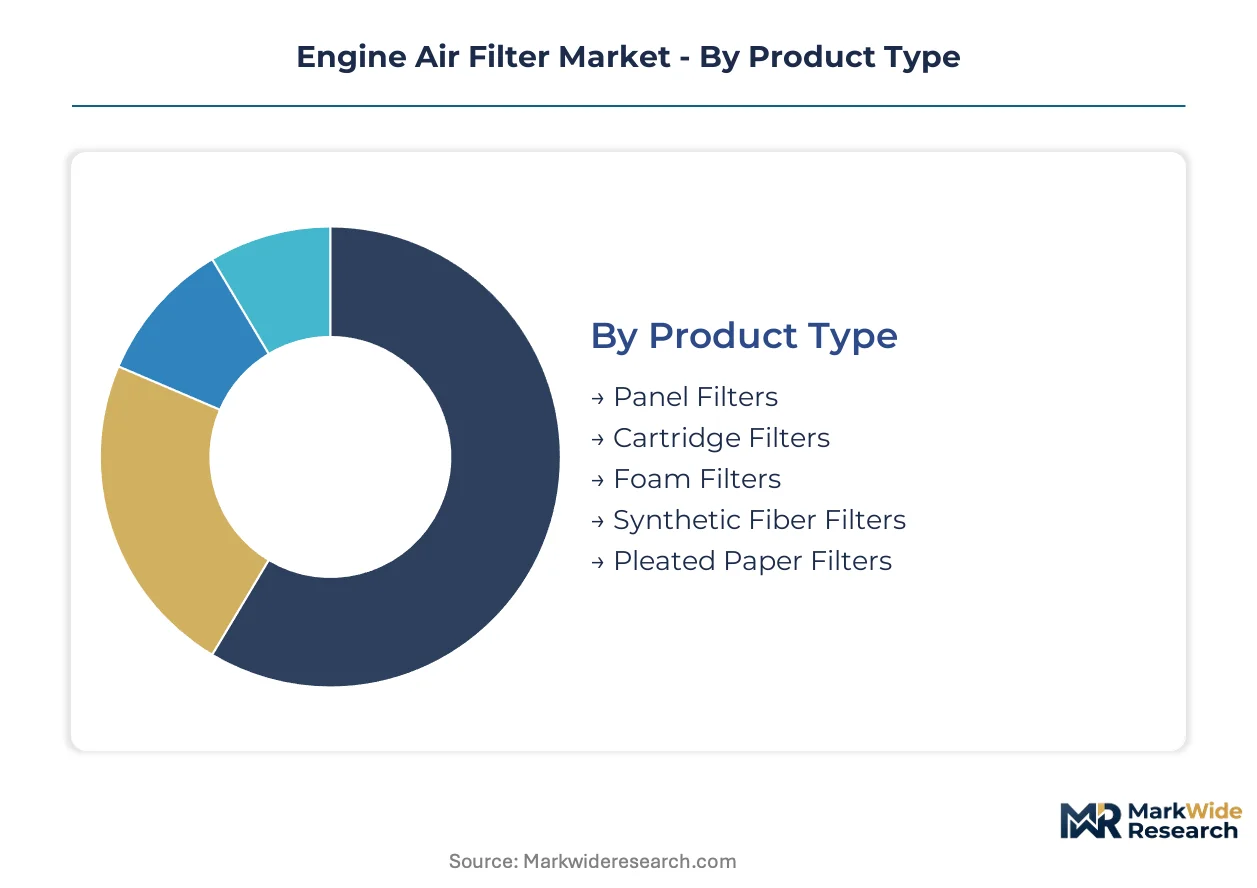
Engine air filter procurement decisions split across technical specifications, maintenance economics, and regulatory compliance requirements. Fleet operators prioritize total cost of ownership while passenger vehicle buyers respond to service interval marketing. Understanding these segment boundaries clarifies where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Cost tier structures the replacement decision for fleet procurement managers and retail consumers alike.
- Pleated Paper Filters:Cellulose-based media with standardized pleat counts deliver filtration efficiency above 99% for particles exceeding 10 microns at the lowest unit cost. Midwest manufacturing clusters around Detroit and Cleveland supply domestic OEM fitments for light-duty vehicles, though pulp price volatility compresses margin stability for tier-two converters.
- Synthetic Fiber Filters:Melt-blown polypropylene and polyester blends extend service intervals through moisture resistance and structural integrity under variable humidity. German and Japanese chemical processors control specialty fiber supply, creating import dependency for North American filter assemblers seeking to match OEM warranty specifications.
- Panel Filters:Rectangular form factors dominate North American and Asian passenger vehicle engine bays with tool-free replacement designs.
- Cartridge Filters:Cylindrical configurations prevail in European OEM applications with integrated housing seals.
- Foam Filters:Open-cell polyurethane reticulation suits small-engine applications and performance aftermarket segments with washable maintenance protocols.
Pleated paper leads on scale; synthetic fiber leads on momentum.
Technology:
Application environment determines whether dust-loading capacity or maintenance simplicity takes priority in specification.
- Dry Air Filters:Disposable pleated media without oil coating eliminates maintenance complexity and contamination risk for intake sensors. Commercial trucking fleets operating across Texas and California interstate corridors specify dry designs exclusively to maximize uptime and eliminate oil bath servicing intervals.
- Nanofiber Media Filters:Electrospun surface layers capture sub-micron particulate through surface-loading mechanics rather than depth filtration, enabling visual inspection protocols. Direct-injection gasoline engines in premium passenger vehicles drive specification as carbon deposit protection becomes a warranty priority for OEMs.
- Oil Bath Filters:Viscous impingement designs persist in agricultural machinery and legacy heavy-equipment installations with extreme dust exposure.
- Electrostatic Filters:Charged fiber matrices enhance capture efficiency without pressure drop penalties in HVAC-integrated intake systems.
- Multi-Layer Media Filters:Gradient density constructions combine pre-filtration and final filtration stages for mining and construction equipment.
Dry air filtration dominates commercial volume; nanofiber deposition commands technology investment priority.
Application:
Vehicle duty cycles create divergent filter performance requirements across operating environments.
- Commercial Trucks:Class 8 long-haul applications demand 50,000-mile minimum service intervals under EPA greenhouse gas certification pressures. Fleet operators along the I-80 corridor from Illinois to Pennsylvania negotiate integrated maintenance contracts bundling filtration with lubricants and fluids.
- Passenger Vehicles:Light-duty OEM fitments emphasize compact packaging and dealer service retention through proprietary form factors. Japanese and Korean automakers specify extended-life synthetic media to differentiate powertrain warranty coverage.
- Agricultural Machinery:Seasonal high-dust exposure in harvest conditions drives seasonal replacement patterns rather than mileage-based scheduling.
- Construction Equipment:Rental fleet operators prioritize disposable ruggedized designs over serviceable configurations to minimize field maintenance.
- Two-Wheelers:Cost-sensitive emerging market applications retain foam and simple pleated paper specifications with frequent replacement intervals.
Commercial trucks anchor aftermarket revenue concentration; passenger vehicles drive media technology migration.
End User:
Procurement authority determines whether specification follows engineering standards or total cost optimization.
- Fleet Operators:National leasing companies and for-hire trucking enterprises consolidate purchasing through direct manufacturer relationships, bypassing traditional distribution. Telematics integration enables predictive replacement scheduling based on intake pressure differential monitoring rather than fixed intervals.
- OEMs:Vehicle assemblers specify filter media during powertrain development to meet emissions certification and warranty cost targets. German and US automakers increasingly require recyclable media content to satisfy circular economy procurement mandates.
- Aftermarket Suppliers:Independent distributors serve fragmented repair shop demand with cross-reference compatible designs.
- Independent Repair Shops:Service bay operators prioritize inventory breadth and same-day availability over brand loyalty.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source private-label filtration for niche applications.
Fleet operators command pricing leverage through volume consolidation; OEMs dictate specification evolution through design integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Chicago-Cleveland manufacturing corridor anchors North American pleated paper filter production, serving domestic OEM fitments with minimized logistics overhead. Commercial fleet density along interstate freight routes and emissions enforcement tightness determine replacement cycle velocity across markets.
United States
Class 8 long-haul fleets operating the I-80 corridor from Illinois to Pennsylvania compress replacement intervals under EPA greenhouse gas certification pressures. The EPA mandates sealed intake systems with onboard diagnostic validation, accelerating aftermarket turnover. Detroit-area manufacturing clusters supply standardized form factors to domestic automakers with just-in-line delivery contracts.
Germany
Electrospun nanofiber media development concentrates around specialty chemical processors serving premium OEM warranty specifications. The EU F-Gas Regulation and CSRD framework incentivize recyclable filter media design through circular economy procurement mandates. Mann+Hummel and MAHLE anchor captive manufacturing scale across Baden-Württemberg and North Rhine-Westphalia plants.
China
Cost-sensitive two-wheeler applications retain foam and simple pleated paper specifications with frequent replacement intervals in emerging market segments. The MIIT enforces GB standards for intake system emissions compliance across domestic vehicle platforms. Yangtze River Delta manufacturing bases supply aftermarket distributors across Southeast Asian export corridors.
Japan
Gasoline direct-injection architectures from Japanese automakers drive sub-micron particulate capture specifications to protect high-pressure fuel injectors. METI coordinates domestic supply chain resilience for synthetic fiber media through JIS standard alignment. Kansai-region chemical processors control specialty polymer supply for extended-life filter designs.
India
Commercial vehicle aftermarket expansion follows highway freight corridor development and tightening BS-VI emissions enforcement. The BIS certifies filtration efficiency standards for domestic OEM fitments and import substitution programs. Maharashtra and Gujarat manufacturing clusters serve replacement demand from Delhi-Mumbai industrial freight routes.
Engine Air Filter Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers retrofit nanofiber deposition lines and sensor-integrated housing designs. The supply base exhibits tiered concentration: multinational filtration specialists with captive chemical processing, regional converters dependent on imported specialty media, and niche performance brands with enthusiast distribution. Strategic archetypes separate extended-interval synthetic media developers from ruggedized disposable specialists and washable reusable designers. M&A activity and telematics partnership formation represent the dominant competitive vectors.
Among German-based filtration conglomerates, Mann+Hummel GmbH and MAHLE GmbH occupy positions exemplifying integrated manufacturing scale across European and North American production networks. Donaldson Company represents the heavy-duty specialization archetype, while K&N Engineering anchors the performance aftermarket tier with washable filter designs. These three named entities illustrate how geographic origin and company structure predict strategic positioning within the supply base.
| Leading Market Players |
|---|
| Mann+Hummel |
| Donaldson Company |
| MAHLE GmbH |
| Denso Corporation |
| K&N Engineering |
| Robert Bosch GmbH |
| Sogefi Group |
| Hengst SE |
| Baldwin Filters |
| Others |
Cost & Logistics Intelligence
Captive manufacturing scale across European and North American plants anchors pricing power for multinational filtration specialists while compressing margin scope for regional converters dependent on imported nanofiber media. Mann+Hummel and Donaldson leverage backward integration into pleated paper production to defend contract positions against pulp price volatility, whereas tier-two assemblers absorb cellulose cost swings without equivalent pass-through leverage.
Pricing Analysis
Cellulose pulp cost pass-through dominates pleated paper tier pricing, with Midwest converters adjusting contract terms quarterly to reflect forestry harvest cycle volatility. Premium-mid-economy pricing differentiation separates nanofiber-equipped synthetic filters from commodity cellulose designs, with OEM warranty specifications commanding brand premiums. Pricing pressure stems from fleet procurement consolidation through integrated maintenance contracts bundling filtration with lubricants. Independent repair shops exhibit highest price sensitivity, while national leasing companies leverage volume scale for contracted rate stability.
Supply Chain Analysis
Regional distribution centers in Detroit, Chicago, and Cleveland feed hub-and-spoke patterns serving domestic OEM just-in-line delivery contracts with minimized logistics overhead. Electrospun nanofiber media production concentrates in Germany and Japan, creating import dependency for North American filter assemblers seeking extended-service-interval specifications. Supply chain risk centers on single-source specialty polymer supply from Kansai-region chemical processors. Distribution runs through national fleet maintenance contracts that displace traditional aftermarket distributor shelf space.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with direct-injection engine proliferation and EPA emissions enforcement accelerating demand-shift toward sub-micron particulate capture specifications.
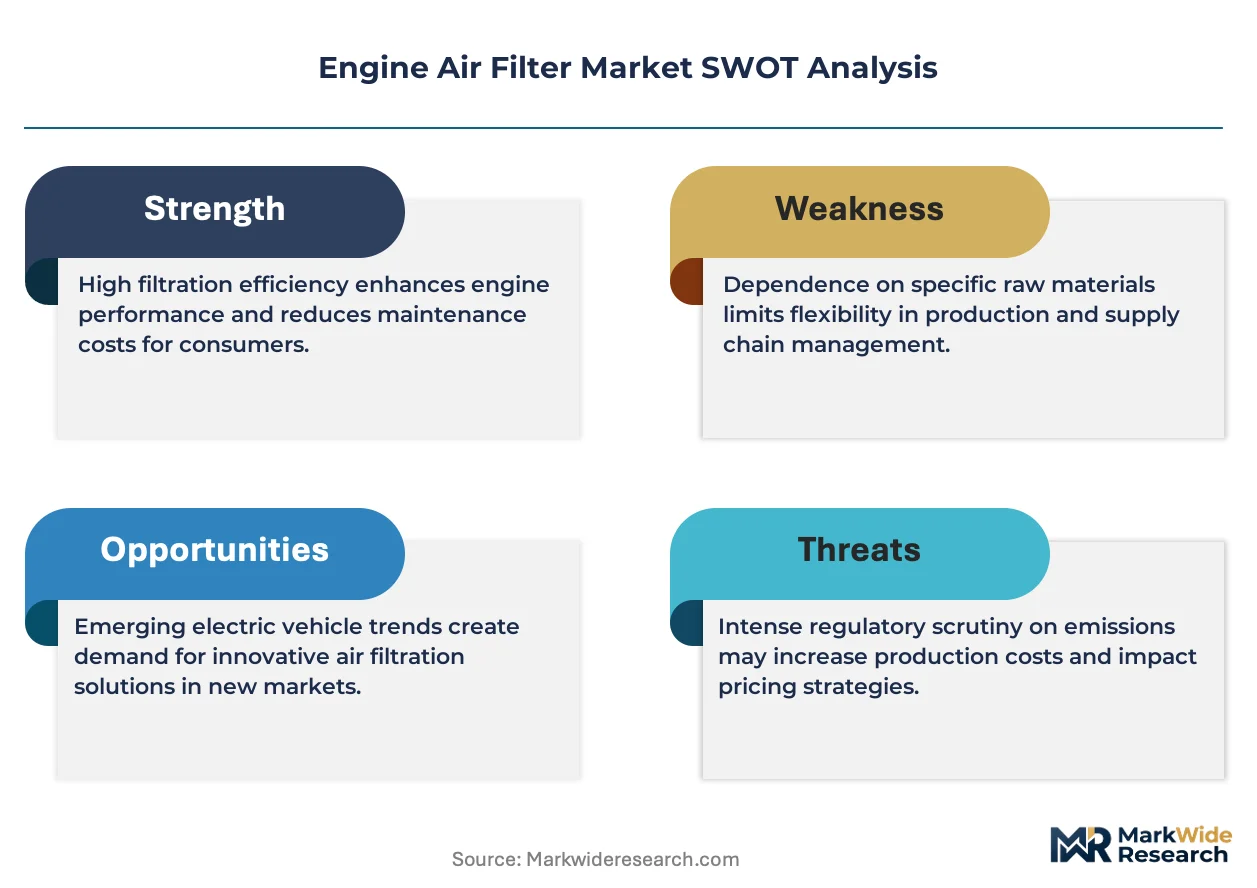
For Market Incumbents: To counter fleet procurement consolidation bypassing traditional distribution, deepen captive manufacturing scale in the Midwest corridor and secure telematics integration partnerships for predictive maintenance platforms. Invest in electrospinning capacity to reduce nanofiber media import dependency. Prioritize M&A of regional converters with established EPA certification pathways. For New Entrants and Emerging Players: Enter via telematics-enabled filter monitoring for mid-size fleet operators underserved by national leasing company direct contracts. Target agricultural machinery seasonal replacement segments where disposable ruggedized designs face limited washable filter substitution. Pursue white-label supply relationships with independent distributors seeking inventory breadth without Mann+Hummel or Donaldson exclusivity constraints. For Investors and Strategic Acquirers: Roll-up economics work for nanofiber deposition specialists because electrospinning talent scarcity and polymer science expertise competition from battery separator industries create durable capability premiums. Five-to-ten-year viability hinges on regulatory convergence between emissions enforcement and circular economy mandates. Watch for CSRD-driven recyclable media procurement criteria as inflection signal for sustainable filter technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Electrospinning Capacity Expansion | Reduces German and Japanese import dependency for sub-micron filtration specifications. |
| Telematics Partnership Formation | Enables predictive replacement alerts embedded in fleet management platforms. |
| Recyclable Media Development | Aligns with EU CSRD framework and F-Gas Regulation circular economy mandates. |
| Backward Integration into Pulp Processing | Defends margin stability against cellulose harvest cycle volatility. |
| Sensor-Integrated Housing Redesign | Accommodates EPA-mandated intake pressure monitoring for heavy-duty certification. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with fleet procurement directors, OEM platform engineers, aftermarket distributor operations heads, and filtration media R&D specialists with secondary validation. Secondary sources include EPA certification filings, EU F-Gas Regulation documentation, vehicle production databases, and customs trade records for cellulose pulp and synthetic fiber imports. Bottom-up unit volume estimates triangulate against top-down market value assessments.
Rate-of-change decomposition separates volume growth from value growth across pleated paper, synthetic fiber, and nanofiber media technology tiers, with vehicle class, propulsion architecture, and fleet operator size as segmentation dimensions. CAGRs derive from regression analysis of historical replacement cycle compression and EPA regulatory phase-in schedules. Industry-specific inputs include commercial truck fleet telematics adoption rates and direct-injection engine platform rollout timelines.
The model holds under sustained EPA enforcement and stable cellulose pulp trade flows; deviation in emissions regulatory rollback or forestry export demand surges would shift replacement frequency and input cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Latin America Automotive Connectors Market