
 Engine Components Market | 2026-2036
Engine Components Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Components Market Analysis
Aluminum is recalibrating product economics across engine architectures as manufacturers displace cast iron to meet weight-reduction targets. Bosch leverages its fuel-injection expertise to anchor European OEM supply chains. Continental AG competes through integrated powertrain electronics that extend its reach beyond mechanical components. Denso Corporation dominates thermal management systems for hybrid powertrains across Japanese and North American assembly plants.
Engine components encompass pistons, crankshafts, valves, and cylinder assemblies that convert thermal energy into mechanical power within internal combustion and hybrid propulsion systems, typically operating at combustion pressures exceeding 150 bar and temperatures surpassing 2,000°C. The automotive application segment sustains the largest revenue pool as passenger and commercial vehicle production requires high-volume sourcing of forged steel crankshafts and aluminum pistons. Composite materials represent the fastest-expanding material category as carbon-fiber-reinforced polymers penetrate valve train components and intake manifolds for weight-critical aerospace and racing applications.
The EPA enforces Corporate Average Fuel Economy standards that compel OEMs to source lighter engine architectures, while the EU Green Deal and F-Gas Regulation constrain fluorinated greenhouse gas use in manufacturing processes. China's MIIT imposes domestic content requirements through GB standards that shape local supplier qualification protocols. Stakeholders must monitor how multi-jurisdictional emissions enforcement cascades through Tier-1 supplier qualification timelines and capital allocation decisions.
Market Dynamics
Aluminum cylinder head adoption is compressing traditional cast iron supply chains as commercial vehicle OEMs pursue mass reduction targets under tightening emissions enforcement. This material transition cascades through forging capacity, thermal management system design, and Tier-1 supplier qualification protocols.
Growth Catalysts
- EPA CAFE Standards:US passenger vehicle OEMs source lighter engine architectures to meet fleet-average fuel economy mandates, accelerating aluminum piston and cylinder head procurement.
- Hybrid Powertrain Scaling:Japanese and North American assembly plants expand thermal management system orders for dual-mode propulsion systems operating across wider temperature bands.
- China Domestic Capacity:MIIT GB standards channel procurement toward local forged crankshaft and valve train suppliers as domestic engine production scales.
Market Restraints
- Aluminum Price Volatility:LME aluminum fluctuations compress margin predictability for cylinder head and piston manufacturers locked into annual supply agreements.
- Scrap Steel Supply Concentration:Turkish and Russian ferrous scrap exporters control input flows for forged steel crankshaft producers, creating geographic supply risk.
- Euro 7 Particulate Limits:The regulation tightens combustion cleanliness thresholds faster than filter technology maturation timelines, forcing premature platform redesigns.
Strategic Opportunities
- India Commercial Vehicle Expansion:Domestic truck and bus production growth outpaces local component supply, opening import substitution windows for aluminum piston specialists.
- Carbon-Fiber Valve Train Components:Aerospace and motorsport applications validate CFRP intake valves and retainers, creating technology transfer paths to premium automotive segments.
- EU F-Gas Regulation Phase-Down:Fluorinated gas restrictions in manufacturing processes incentivize investment in aqueous-based cleaning and coating systems for engine component finishing.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Simultaneous EPA, Euro 7, and China VI qualification requirements stretch engineering validation resources across incompatible test cycles.
- Legacy Cast Iron Capacity Stranded:Existing foundry investments in gray iron cylinder block production face accelerated obsolescence as aluminum architectures dominate new platform awards.
- Thermal Management Integration Complexity:Hybrid powertrain cooling circuits demand combined expertise in combustion heat rejection and electric motor thermal control, compressing supplier capability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Components Market |
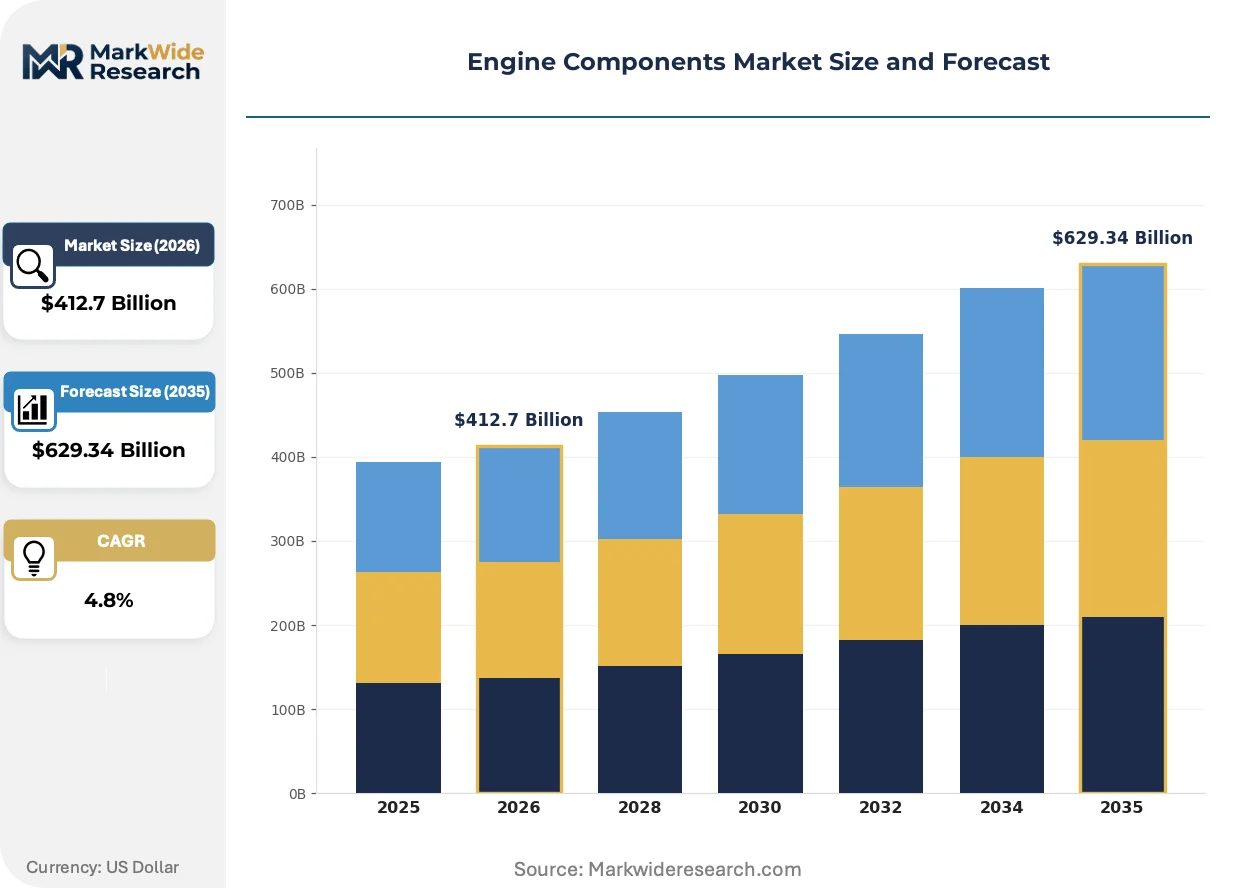
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Cylinders, Pistons, Crankshafts, Valves Material: Aluminum, Steel, Cast Iron, Composite Application: Automotive, Aerospace, Marine, Industrial End User: OEMs, Aftermarket Suppliers, Maintenance Providers, Tier-1 Suppliers |
| Companies Covered | Bosch, Continental AG, Denso Corporation, Schaeffler AG, Eaton Corporation, Mahle GmbH, Tenneco Inc., Aisin Seiki Co. Ltd., Delphi Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Components Market Emerging Trajectories
Material substitution and regulatory compression are restructuring competitive advantage around thermal efficiency and weight reduction rather than scale economics alone. The convergence of electrification pressure and combustion refinement creates bifurcated technology investment requirements.
Additive manufacturing of titanium-aluminide turbine wheels and exhaust valves is overtaking conventional investment casting for low-volume, high-performance applications. Racing teams and aerospace propulsion divisions adopt electron-beam melting to consolidate multi-part assemblies into single printed components. This compression of part count and lead time is overtaking traditional forging and machining supply chains in sub-10,000 unit production runs.
The EU F-Gas Regulation constrains hydrofluorocarbon use in component cleaning and heat-treatment atmospheres, forcing process chemistry overhauls at European foundries and machine shops. Industrial consequence includes accelerated capital deployment in plasma-based surface treatment and aqueous degreasing systems. German and Italian engine component suppliers face the steepest compliance timelines as domestic enforcement precedes neighboring jurisdictions.
Fleet operators now unbundle aftermarket service contracts from initial equipment procurement, compressing traditional captive spare parts revenue streams for OEMs. Independent remanufacturers of crankshafts and cylinder heads capture growing share of commercial vehicle overhaul demand in North America and Western Europe. This channel disintermediation is most visible in long-haul trucking segments where total cost of ownership calculations dominate replacement decisions.
Engine Components Market Segmentation
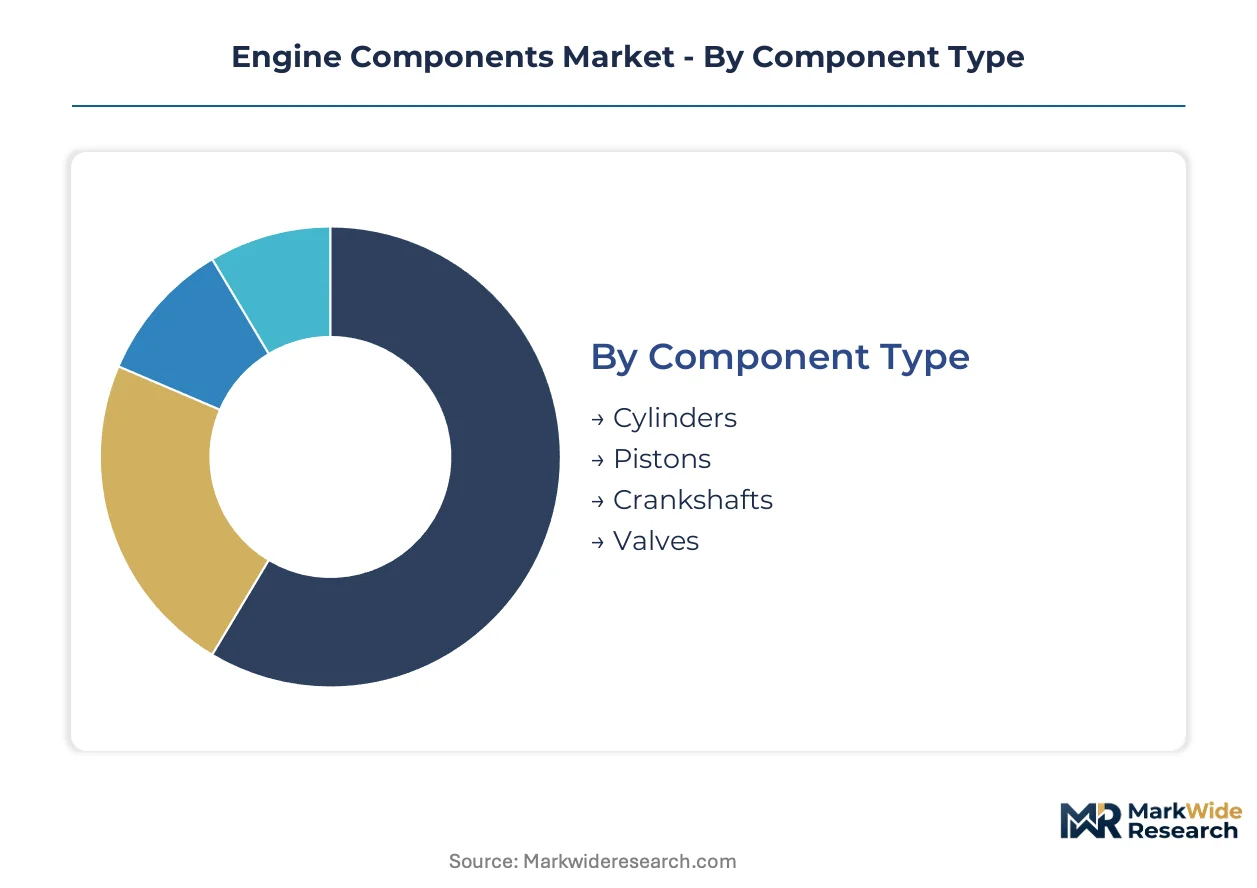
Engine component procurement follows distinct capital allocation patterns across material grades, manufacturing processes, and certification tiers. Each segmentation axis reveals where investment concentrates and where margin compression threatens incumbent positioning.
Component Type:
Capital intensity peaks with crankshaft forging and precision cylinder machining, where tooling amortization spans multiple platform generations.
- Cylinders:Aluminum-silicon alloy cylinder blocks and heads require high-pressure die casting cells exceeding 2,500 tons clamping force. Commercial vehicle OEMs in China and India dominate procurement as domestic engine production scales under MIIT GB standards.
- Pistons:Hypereutectic aluminum pistons with anodized ring grooves withstand combustion pressures above 180 bar. Demand clusters in light-duty diesel applications where Euro 7 particulate limits force tighter tolerance specifications.
- Crankshafts:Forged steel crankshafts demand 8,000-ton press capacity and CNC crank pin machining lines.
- Valves:Hollow-head sodium-filled exhaust valves manage thermal loads in turbocharged architectures.
Most installed capacity flows through Cylinders. Expansion is steepest in Pistons.
Material:
Raw material selection dictates foundry equipment configuration, scrap recycling economics, and thermal management system integration complexity.
- Aluminum:Secondary alloy specifications with 8-12% silicon content enable thin-wall casting for weight reduction targets. Passenger vehicle OEMs source aluminum cylinder heads and pistons to meet EPA CAFE fleet averages, though LME price volatility squeezes margin predictability.
- Steel:Microalloyed forging grades with vanadium or niobium additions eliminate post-forge heat treatment. Crankshaft producers in Germany and Japan control premium supply chains for high-performance engines.
- Cast Iron:Vermicular graphite iron retains exhaust manifold applications where thermal fatigue resistance exceeds aluminum capabilities.
- Composite:Carbon-fiber-reinforced polymers penetrate valve train retainers and intake manifolds in motorsport and aerospace propulsion systems.
Steel commands the largest installed forging base. Aluminum is climbing the fastest as OEMs displace iron architectures.
Application:
End-use diversification spreads demand across incompatible certification cycles, thermal operating regimes, and volume scale requirements.
- Automotive:Passenger and commercial vehicle production sustains high-volume sourcing of forged steel crankshafts and aluminum pistons. Hybrid powertrain scaling in Japanese and North American assembly plants expands thermal management system orders.
- Aerospace:Turbine blade and combustion chamber components demand nickel superalloy investment casting with vacuum arc remelt feedstock.
- Marine:Slow-speed two-stroke engines for container shipping require massive ductile iron bedplates and steel-forged crankshafts.
- Industrial:Stationary power generation and compressor applications specify heavy-duty cylinder liners with plasma-coated running surfaces.
Automotive absorbs the majority of component output. Aerospace is gaining share fastest on unit value expansion.
End User:
Channel structure determines pricing power, inventory liability placement, and aftermarket capture rates across equipment life cycles.
- OEMs:Captive engine divisions and powertrain joint ventures specify components against multi-year platform contracts with annual price-down mechanisms.
- Aftermarket Suppliers:Independent distributors and private-label brands source remanufactured crankshafts and cylinder heads for commercial vehicle overhaul demand.
- Maintenance Providers:Fleet operators and dealer service networks procure replacement pistons and valve train kits through unbundled service contracts.
- Tier-1 Suppliers:Integrated powertrain module suppliers consolidate procurement of pistons, rings, and pins from specialized forging houses.
OEMs command the deepest supplier relationships. Aftermarket Suppliers are expanding fastest as fleet operators unbundle service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors global engine component manufacturing, with Shanghai and Suzhou hosting dense clusters of aluminum die-casting and precision machining facilities serving domestic OEMs and export markets.
China
Domestic engine production capacity expansion drives procurement of forged steel crankshafts and aluminum cylinder heads. MIIT GB standards mandate local content ratios that channel supply toward qualified Chinese suppliers. Zhejiang and Jiangsu provinces concentrate foundry investments for commercial vehicle OEMs scaling under national dual carbon goals.
United States
EPA CAFE fleet-average mandates compel Detroit OEMs to source lighter aluminum architectures for light trucks and passenger vehicles. NHTSA safety regulations intersect with fuel economy enforcement, stretching engineering validation resources. Michigan and Ohio retain deep supplier networks even as southeastern states attract new powertrain assembly investments.
Germany
Euro 7 particulate limits force premature platform redesigns, compressing supplier qualification timelines for combustion cleanliness technologies. KBA enforcement precedes neighboring jurisdictions, steepening compliance curves for foundries in Baden-Württemberg and Bavaria. Stuttgart and Munich anchor premium crankshaft forging and thermal management system development.
Japan
Hybrid powertrain scaling across Toyota and Honda assembly plants expands thermal management system orders for dual-mode propulsion. METI technology roadmaps guide investment in heat rejection and electric motor thermal control integration. Aichi and Shizuoka prefectures concentrate precision piston and valve train manufacturing for domestic and North American supply.
India
Commercial vehicle production growth outpaces local component supply, opening import substitution windows for aluminum piston specialists. BIS certification requirements shape supplier qualification for engine blocks and cylinder heads. Tamil Nadu and Maharashtra host expanding foundry capacity serving domestic truck and bus OEMs.
Engine Components Market Vendor Landscape
Global majors compete with regional champions across material specialization and thermal management integration. The market structures around three tiers: integrated powertrain module suppliers, specialized forging and casting houses, and aftermarket remanufacturers. Strategic archetypes include aluminum architecture specialists displacing cast iron, hybrid cooling system integrators, and carbon-fiber component developers. Dominant competitive moves encompass backward integration into alloy feedstock and strategic partnerships for multi-jurisdictional certification.
Among German-based diversified suppliers, Schaeffler AG and Mahle GmbH exemplify the integrated powertrain archetype spanning mechanical and electronic domains. Denso Corporation anchors the thermal management specialist tier with Japanese and North American assembly plant relationships. Continental AG occupies a position bridging European OEM supply chains with electronics integration capabilities. Bosch represents the fuel-injection and combustion expertise archetype that extends across multiple component categories.
| Leading Market Players |
|---|
| Bosch |
| Continental AG |
| Denso Corporation |
| Schaeffler AG |
| Eaton Corporation |
| Mahle GmbH |
| Tenneco Inc. |
| Aisin Seiki Co. Ltd. |
| Delphi Automotive |
| Others |
Supply Flow & Price Mechanics
LME aluminum ingot contracts flow through annual supply agreements into cylinder head and piston pricing tiers, with volatility in Shanghai futures compressing margin predictability for foundries serving commercial vehicle OEMs. This input-cost transmission shapes how Tier-1 suppliers structure long-term offtake terms against spot market exposure.
Pricing Analysis
Input-cost pass-through dominates engine component contracting, with aluminum price fluctuations absorbed differentially across buyer tiers. Three-tier pricing structure across premium, standard, and economy levels separates OEM platform contracts with annual price-down mechanisms from aftermarket spot procurement. Pricing pressure stems from Euro 7 compliance investments forcing premature platform redesigns. Fleet operators exhibit highest price sensitivity through unbundled service contracts, while aerospace propulsion divisions tolerate premium grades for certified nickel superalloy castings.
Supply Chain Analysis
Remanufacturing flows for crankshafts and cylinder heads now capture growing commercial vehicle overhaul share as independent operators disintermediate OEM captive parts channels. Supply concentrates in China, Germany, and Japan for precision forging and investment casting capacity. Raw material dependencies center on Turkish and Russian ferrous scrap flows, LME aluminum ingots, and vacuum arc remelt nickel superalloys. Single-source vulnerability runs through concentrated ferrous scrap export channels. Distribution runs through Tier-1 integrated powertrain module suppliers consolidating procurement from specialized forging houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Euro 7 particulate limits and EPA CAFE standards simultaneously tighten compliance thresholds and weight-reduction mandates, forcing simultaneous technology investment across incompatible certification cycles.
For Market Incumbents: Hedge aluminum price exposure through backward integration into alloy feedstock or long-term LME hedging instruments. Accelerate thermal management system integration capabilities to capture hybrid powertrain orders from Japanese and North American assembly plants. Defend against carbon-fiber valve train specialists by locking aerospace technology transfer partnerships before motorsport validation completes. For New Entrants and Emerging Players: Independent fleet service operators represent the most underserved buyer archetype as long-haul trucking segments unbundle aftermarket contracts from initial equipment procurement. Target aluminum piston import substitution in India's commercial vehicle expansion, where BIS certification requirements create qualification barriers for established suppliers. Pursue aqueous-based coating system partnerships with European foundries facing F-Gas Regulation compliance deadlines. For Investors and Strategic Acquirers: Roll-up economics work for specialized thermal management integrators because hybrid powertrain scaling demands combined combustion heat rejection and electric motor thermal control expertise that fragments across incumbent supplier bases. Five-to-ten year viability hinges on electrification transition pacing. Monitor EPA and Euro 7 enforcement timelines as inflection indicators for combustion component demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Captive aluminum supply insulates margins from LME volatility for cylinder head producers. |
| Multi-Jurisdictional Certification Partnerships | Shared EPA, Euro 7, and China VI validation resources compress engineering timelines for Tier-1 suppliers. |
| Carbon-Fiber Valve Train Technology Transfer | Motorsport-to-premium-automotive pathways open as aerospace validates CFRP intake valves. |
| Aqueous Coating System Deployment | F-Gas Regulation compliance accelerates plasma-based surface treatment adoption at German foundries. |
| Aftermarket Channel Disintermediation | Independent remanufacturers capture commercial vehicle overhaul share from OEM captive parts networks. |
Methodological Framework
Multiple input streams — OEM platform engineering directors, Tier-1 supplier procurement leads, foundry operations managers, and aftermarket distribution heads — were reconciled against customs trade data, EPA certification filings, MIIT GB standard documentation, and IHS Markit vehicle production databases. Primary fieldwork with thermal management system integrators and aluminum die-casting specialists combined with secondary validation from SEC filings of listed automotive suppliers. Bottom-up component demand modeling and top-down powertrain production forecasts were cross-checked for triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning propulsion architecture, material grade tier, OEM tier classification, and regional production cluster. CAGRs were derived from modeled unit demand and value-per-vehicle content trajectories. Forecast inputs incorporated EPA CAFE enforcement stringency scenarios, Euro 7 implementation pacing assumptions, and China domestic engine capacity expansion schedules.
Inputs from OEM engineering disclosures and supplier contract announcements were available through the study window; gaps in proprietary platform-level component specifications introduce uncertainty bands around content-per-vehicle estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and material substitution elasticities. Practitioners should monitor EPA rulemaking dockets, KBA type-approval precedents, and MIIT GB standard revision cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
RV Battery Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Towing Ropes Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Navigation Light Market
Vehicle Components
EGR Valve Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market