
 4-Wheeled Containers Market | 2026-2036
4-Wheeled Containers Market Size, Share, and Industry Trends Forecast 2026-2036
4-Wheeled Containers Market Outlook
Direct-to-municipality procurement is tilting away from distributor intermediaries across Europe. SSI Schaefer leverages its captive manufacturing footprint in Germany to anchor large-volume contracts with city sanitation departments. IPL Plastics competes through specialized rotationally molded designs that dominate food transport applications in France. Weber GmbH sustains engineering-intensive fabricated container lines that command premium positioning in industrial material handling.
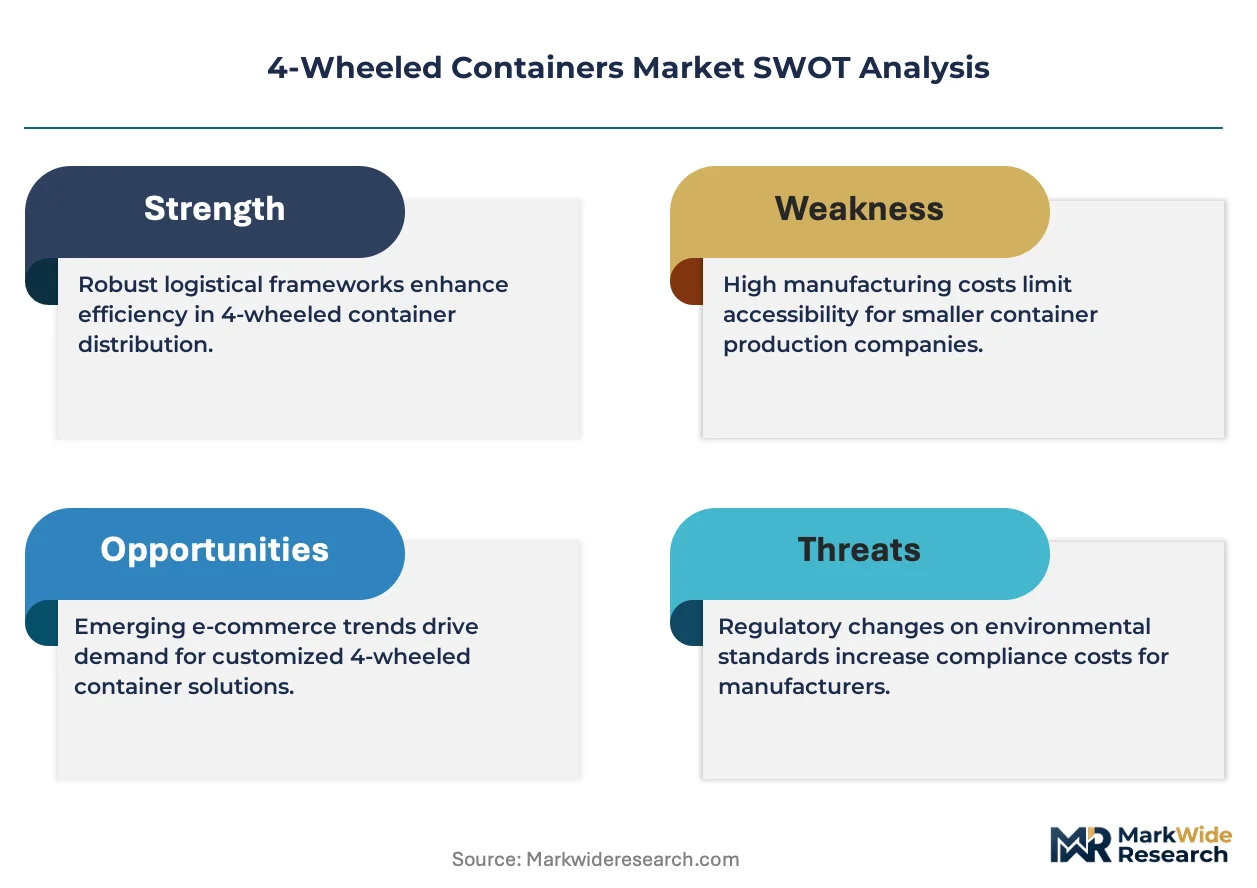
4-wheeled containers are mobile receptacles mounted on castor wheel assemblies, typically fabricated from high-density polyethylene via rotational or injection molding, with load ratings spanning 200 to 1,100 liters for manual or automated lifting compatibility. Their primary purpose centers on safe, ergonomic transport of waste, raw materials, or temperature-sensitive goods across uneven surfaces in urban and industrial environments. Plastic containers lead unit volume due to corrosion resistance and weight advantages, while metal variants retain structural margin pools in heavy-duty cargo transportation. Custom capacity configurations represent the fastest-growing segment as logistics providers demand fleet-specific dimensional optimization.
German KBA transport safety standards and EU REACH chemical compliance frameworks jointly shape material selection and wheel assembly specifications across the value chain. France's ANSM and Germany's ECHA enforcement patterns are tightening recycled content verification requirements for public procurement tenders. Stakeholders must monitor evolving extended producer responsibility schemes and their cascading specification impacts on container design cycles.
Market Dynamics
EU recycling mandates are compressing container replacement cycles as municipalities accelerate fleet modernization ahead of compliance deadlines. The tightening of extended producer responsibility schemes across member states is forcing rapid specification upgrades in waste collection infrastructure.
Growth Catalysts
- REACH chemical compliance:Germany's ECHA enforcement is accelerating HDPE formulation upgrades that improve container durability and recyclability. Municipal buyers now prioritize certified materials in tender specifications.
- Automated lifting systems:Waste management operators in France are retrofitting fleets with DIN-standard compatible castor assemblies. This hardware convergence reduces manual handling injuries and collection cycle times.
- Curb-side sorting infrastructure:Benelux municipalities are expanding multi-stream collection programs that require color-coded container differentiation. Rotationally molded designs dominate this specification tier.
Market Restraints
- HDPE resin volatility:Feedstock cost swings for high-density polyethylene compress margin predictability for molded container producers. Long-term municipal contracts struggle to accommodate raw material index movements.
- German manufacturing concentration:Captive production of wheel assemblies and castor systems clusters in Baden-Württemberg and Bavaria. Supply disruption risks concentrate in this industrial corridor.
- Metal substitution in heavy cargo:Steel and aluminum containers retain structural advantages for loads exceeding 800 kilograms. Plastic designs face technical barriers in industrial material handling above this threshold.
Strategic Opportunities
- Recycled content verification:France's ANSM is piloting blockchain-tracked polymer sourcing for public procurement. Early certification adopters gain preferential tender scoring in municipal RFPs.
- Food transport cold chain:Insulated rotationally molded containers are penetrating pharmaceutical and fresh produce logistics. Temperature stability specifications match passive cooling requirements for last-mile delivery.
- Direct municipality contracting:Digital procurement platforms are disintermediating traditional distributor networks. Container manufacturers can capture margin previously allocated to wholesale channels.
Industry Challenges
- Rotational molding technician scarcity:Specialized oven operation and mold maintenance skills are aging out of the workforce. Training pipeline gaps constrain capacity expansion for complex geometry production.
- Multi-standard certification timelines:Simultaneous KBA transport safety and EU type-approval processes extend product launch cycles. Testing backlog at notified bodies delays fleet deployment schedules.
- Legacy fleet interoperability:Existing container pools use proprietary coupling and lifting interfaces. New automated collection systems require expensive retrofit kits or complete replacement programs.
Report Scope
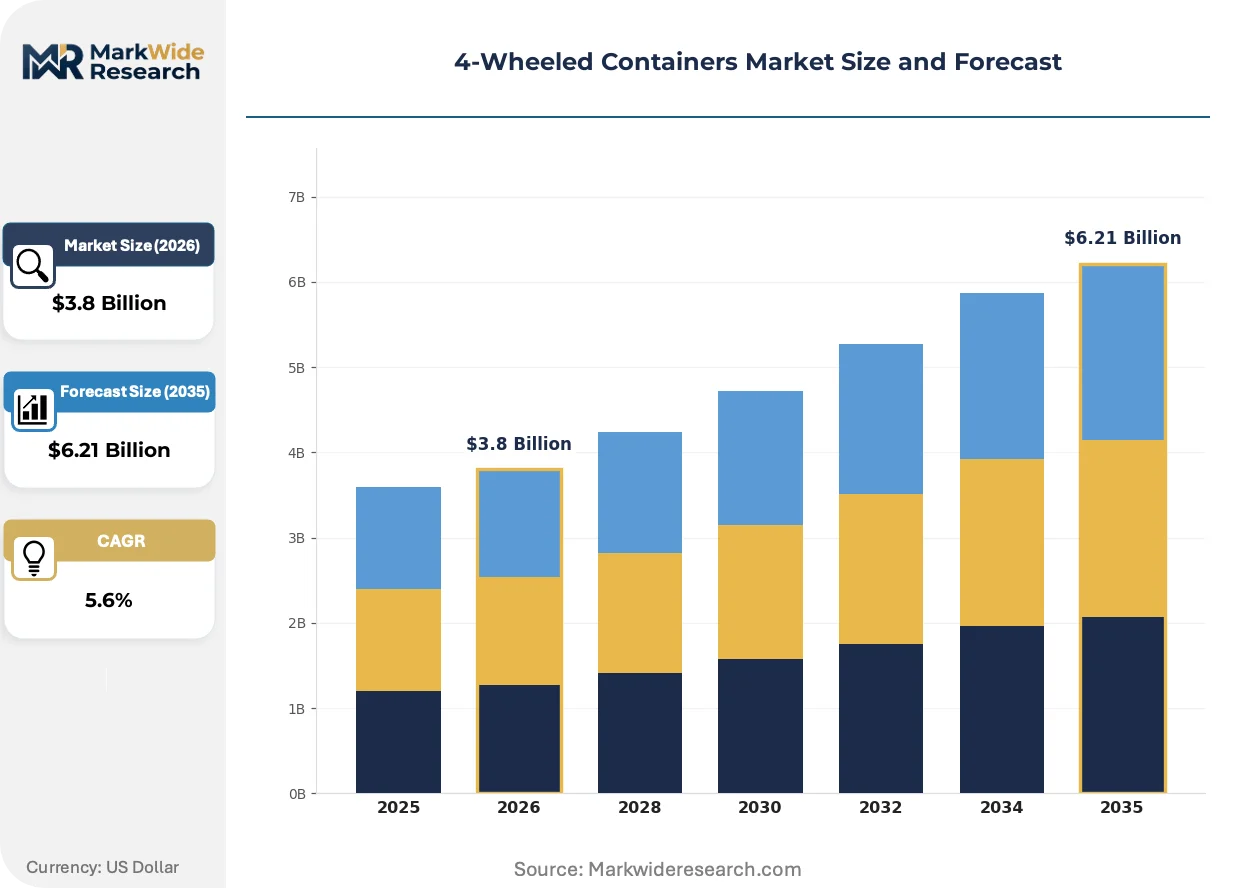
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Wheeled Containers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Metal Containers, Fabricated Containers, Composite Containers Application: Waste Management, Food Transport, Material Handling, Cargo Transportation End User: Retailers, Manufacturers, Logistics Providers, Municipalities Capacity: Small Capacity, Medium Capacity, Large Capacity, Custom Capacity |
| Companies Covered | SSI Schaefer, IPL Plastics, Weber GmbH, SULO, Craemer, ESE World, Toter, Plastika Skaza, Otto Environmental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Wheeled Containers Market Strategic Shifts
Container intelligence is migrating from passive hardware to connected asset systems. Sensor integration and data analytics are reshaping how logistics operators manage fleet utilization, maintenance scheduling, and compliance documentation.
RFID and IoT sensor modules embedded in wheel housings are digitizing container tracking for waste management fleets. German municipalities piloting smart city infrastructure are deploying these units at scale. Real-time fill-level monitoring is compressing collection route optimization cycles and reducing unnecessary truck movements.
REACH recycled content mandates are forcing polymer supply chain reconfiguration across European container manufacturing. ECHA verification requirements now extend to post-consumer feedstock documentation. French and Benelux producers are restructuring supplier relationships to secure certified material streams ahead of tightening enforcement windows.
Municipal procurement departments are consolidating vendor relationships around full-service fleet management contracts. Traditional equipment-only sales are yielding to performance-based agreements covering maintenance, replacement, and regulatory compliance. This shift is most visible in German city sanitation departments with mature automated collection infrastructure.
4-Wheeled Containers Market Segmentation
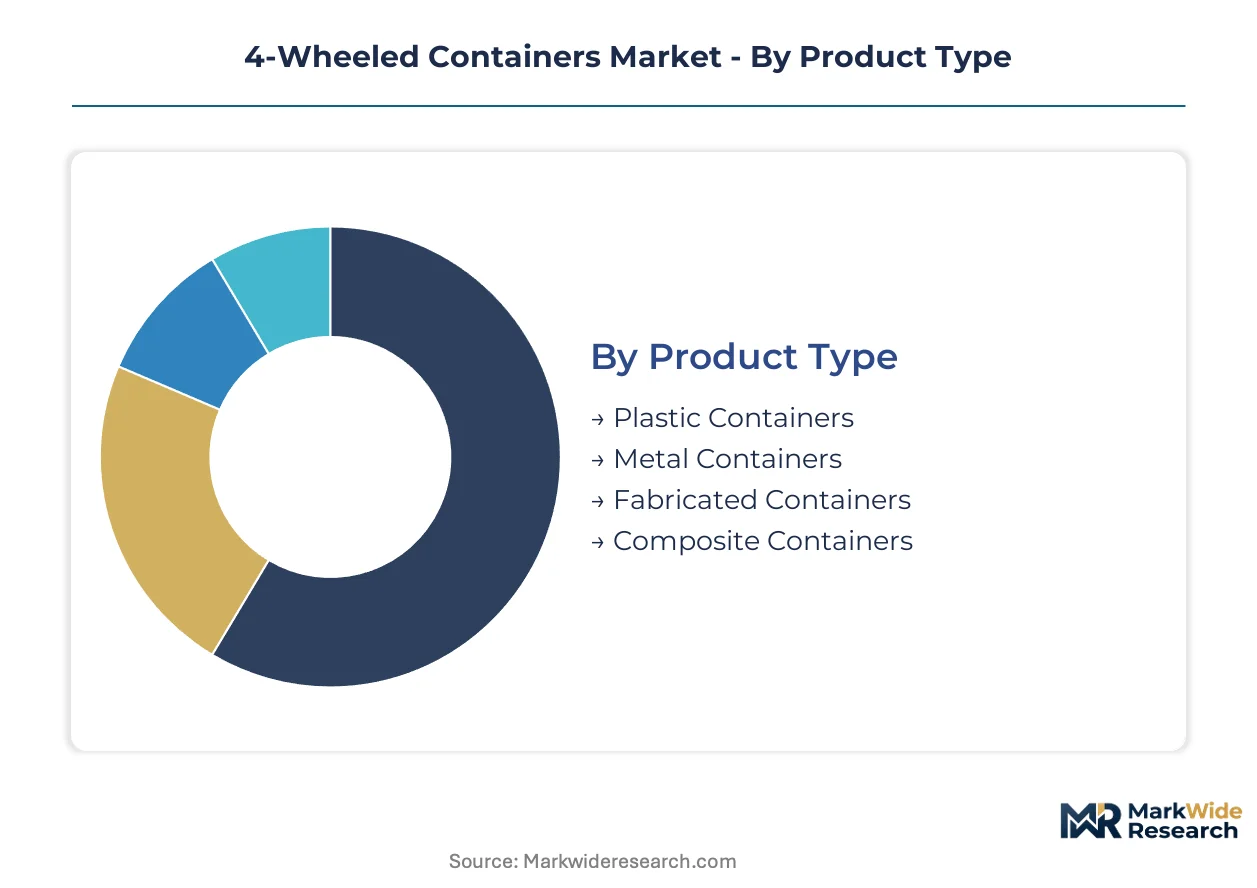
Container manufacturers configure product lines around four intersecting dimensions that determine procurement priorities and margin structures. Municipal tender specifications increasingly demand precise alignment across material type, application environment, and capacity tier.
Product Type:
Mature injection molding processes dominate high-volume production, while emerging composite formulations target performance gaps in temperature-critical logistics.
- Plastic Containers:High-density polyethylene construction via rotational or injection molding delivers corrosion resistance and weight advantages for manual handling. German municipalities prioritize these for automated lifting compatibility under ECHA REACH compliance frameworks.
- Metal Containers:Steel and aluminum fabrication retains structural integrity for loads exceeding 800 kilograms in industrial material handling. French logistics operators specify these for heavy cargo where plastic deformation thresholds constrain deployment.
- Fabricated Containers:Engineering-intensive welded assemblies command premium positioning in custom industrial configurations.
- Composite Containers:Hybrid material constructions address niche thermal insulation requirements in pharmaceutical distribution.
Plastic containers handle the majority of throughput; composite containers are expanding most quickly on share.
Application:
Cost tier differentiation separates commodity waste collection from premium cold-chain logistics where passive cooling specifications justify material investment.
- Waste Management:Curb-side collection infrastructure drives standardized DIN-compatible designs across Benelux and French municipal fleets. Color-coded differentiation for multi-stream sorting programs accelerates rotationally molded container procurement.
- Food Transport:Insulated rotationally molded configurations penetrate fresh produce and pharmaceutical last-mile delivery. Temperature stability specifications match passive cooling requirements without active refrigeration infrastructure.
- Material Handling:Industrial manufacturing floors demand wheel assemblies rated for uneven surfaces and repetitive loading cycles.
- Cargo Transportation:Long-haul freight applications prioritize stackability and lifting interface standardization.
Waste management absorbs the largest equipment volumes; food transport is climbing the fastest on specification intensity.
End User:
Customer type determines contract structure, with municipalities favoring long-term fleet agreements and logistics providers demanding rapid configuration flexibility.
- Municipalities:City sanitation departments consolidate procurement around full-service performance contracts covering maintenance, replacement, and regulatory compliance. German KBA transport safety standards shape tender specifications for automated collection system compatibility.
- Logistics Providers:Third-party operators prioritize fleet-specific dimensional optimization and rapid asset redeployment across contract portfolios.
- Retailers:Distribution center operations require standardized container pools for reverse logistics and store replenishment cycles.
- Manufacturers:In-plant material handling demands proprietary lifting interfaces and integration with existing production line configurations.
Municipalities dominate absolute unit procurement; logistics providers are gaining share fastest on fleet modernization intensity.
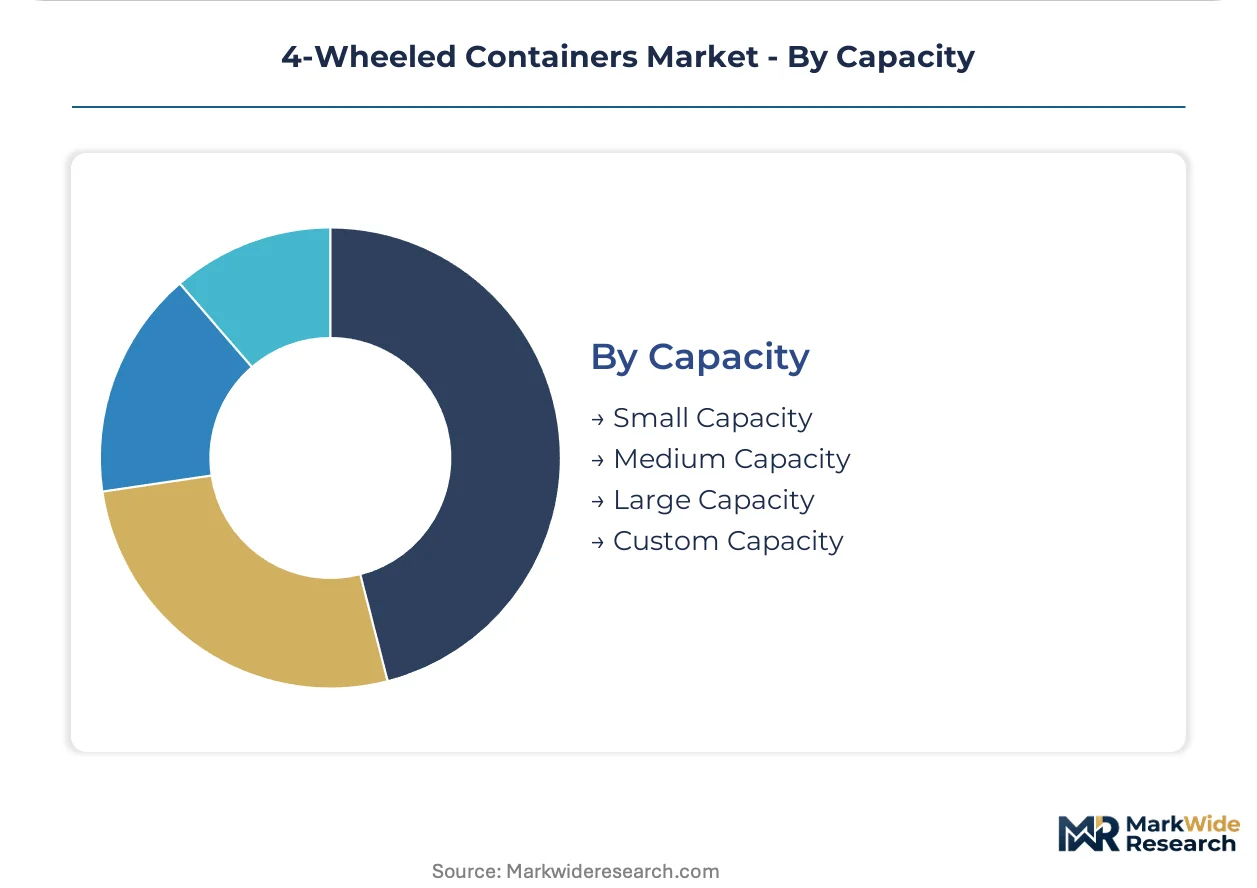
Capacity:
Volume concentration varies by geography, with dense European urban cores favoring compact configurations and industrial zones specifying maximum load ratings.
- Custom Capacity:Fleet-specific dimensional optimization represents the steepest expansion trajectory as logistics operators demand precise cubic utilization for route efficiency. Mold design flexibility enables rapid reconfiguration without complete tooling replacement.
- Large Capacity:800-1,100 liter ratings serve industrial material handling and automated waste collection systems with mechanical lifting infrastructure.
- Medium Capacity:400-700 liter configurations balance manual maneuverability with payload efficiency in mixed urban environments.
- Small Capacity:200-350 liter designs address retail back-of-house and confined-space manufacturing floor requirements.
Custom capacity configurations command the highest margin tier; large capacity maintains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement across Germany anchors European regulatory momentum for container material compliance. Municipal procurement specifications now embed chemical safety verification as a baseline tender requirement.
Germany
Automated waste collection fleet modernization accelerates in Baden-Württemberg and Bavaria under tightened EU recycling mandates. KBA transport safety standards dictate DIN-compatible castor assembly specifications for mechanical lifting systems. Stuttgart and Munich sanitation departments consolidate procurement around full-service performance contracts.
France
ANSM's blockchain-tracked polymer sourcing pilots reshape public procurement scoring for recycled content verification. Curb-side sorting infrastructure expansion in Île-de-France drives color-coded container differentiation requirements. Lyon and Marseille logistics operators specify rotationally molded designs for multi-stream collection programs.
Netherlands
Benelux municipalities scale multi-stream collection infrastructure fastest across the European Union. Extended producer responsibility enforcement tightens specification cycles for waste handling equipment. Rotterdam and Amsterdam sanitation authorities prioritize fleet-specific dimensional optimization in tender awards.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification pathways for container imports from continental suppliers. Local authority procurement consolidation favors vendors with captive manufacturing footprints. Greater Manchester and Birmingham waste partnerships drive standardization around automated lifting compatibility.
Italy
Lombardy and Emilia-Romagna industrial zones sustain demand for heavy-duty material handling configurations. CE marking alignment with EU type-approval processes streamlines cross-border equipment deployment. Milan logistics providers specify custom capacity tiers for route efficiency optimization.
4-Wheeled Containers Market Competitive Environment
Integrated manufacturing conglomerates and specialized molding specialists split the market along capability depth versus scale vectors. Vendor relationships concentrate around long-term municipal fleet contracts with embedded maintenance obligations. Three archetypes dominate: captive polymer processors with backward raw material control, rotationally molded design specialists, and engineering-intensive fabricated container fabricators. Competitive positioning hardens through direct municipality contracting platforms and recycled content certification pre-qualification.
Among German-based industrial equipment groups, SSI Schaefer and Weber GmbH exemplify divergent strategic positions within the premium tier. SSI Schaefer occupies a manufacturing footprint anchored position for large-volume municipal awards. Weber GmbH represents engineering-intensive fabricated lines commanding specification intensity in industrial material handling. IPL Plastics sits within the rotationally molded specialist archetype, with French market presence aligning with curb-side sorting infrastructure scaling.
| Leading Market Players |
|---|
| SSI Schaefer |
| IPL Plastics |
| Weber GmbH |
| SULO |
| Craemer |
| ESE World |
| Toter |
| Plastika Skaza |
| Otto Environmental |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's captive manufacturing corridor for wheel assemblies and castor systems concentrates upstream capacity, granting integrated producers pricing leverage over distributors locked into long-term municipal contracts with limited raw material pass-through clauses.
Pricing Analysis
German-French price spreads for DIN-standard containers widen by certification tier, with ECHA REACH-compliant HDPE formulations commanding premiums over baseline grades. Three-tier pricing structure across premium certified, standard industrial, and economy municipal tiers reflects after-sales service bundling and recycled content verification levels. Pricing pressure stems from HDPE resin volatility that outpaces index adjustment clauses in multi-year sanitation awards. Municipal buyers exhibit highest price sensitivity due to fixed budget cycles, while pharmaceutical logistics operators accept premium positioning for cold-chain specifications.
Supply Chain Analysis
Rotational molding specialists in France, Germany, and the Benelux region hold contract-manufacturing capacity for complex geometry production, with oven operation and mold maintenance skills constraining expansion timelines. HDPE resin supply draws from petrochemical complexes in Germany and the Netherlands, while wheel assembly components hinge on steel forging clusters in Bavaria. Single-source vulnerability concentrates in Baden-Württemberg's castor manufacturing corridor where transport disruption would cascade across automated lifting system deployments. Distribution runs through direct-to-municipality digital procurement platforms that disintermediate traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability standardization around DIN-compatible lifting interfaces is transforming container procurement into platform economics, with fleet management contracts consolidating vendor relationships around data-driven performance guarantees rather than equipment-only transactions.
For Market Incumbents: Insulate municipal contract renewals by embedding maintenance obligations and regulatory compliance services into full-service performance agreements. Backward integration into certified recycled HDPE feedstock secures preferential ANSM tender scoring against distributor-dependent challengers. Capacity retention in Baden-Württemberg preserves KBA transport safety certification speed-to-market despite geographic concentration risk.
For New Entrants and Emerging Players: Italian industrial zones outside Lombardy's saturated material handling corridor offer underpenetrated demand for custom capacity configurations with proprietary lifting interfaces. Food transport cold-chain specifications in pharmaceutical distribution present specification intensity gaps where insulated rotationally molded designs penetrate without legacy fleet interoperability burdens. Digital procurement platform partnerships with mid-size logistics providers bypass entrenched municipal distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized container divisions lacking recycled content certification infrastructure. Long-term viability centers on compliance service bundling rather than commodity equipment manufacturing. Monitor ECHA enforcement intensity and blockchain-tracked polymer sourcing pilot expansion as inflection indicators for preferential tender access.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | ANSM blockchain-tracked sourcing pilots reward early adopters with preferential municipal tender scoring. |
| Direct-to-Municipality Platform Integration | Digital procurement disintermediation captures margin previously allocated to wholesale distributor networks. |
| Rotational Molding Technician Pipeline Development | Specialized oven operation skills aging out constrain capacity expansion for complex geometry production. |
| Full-Service Fleet Management Contracting | Performance-based agreements covering maintenance and compliance replace equipment-only sales in German sanitation departments. |
| Cold-Chain Insulated Container Line Extension | Passive cooling specifications match pharmaceutical last-mile delivery requirements without active refrigeration infrastructure. |
Study Parameters
Operator-level perspectives from municipal sanitation procurement officers, waste management fleet managers, rotational molding plant engineers, logistics provider asset directors, and HDPE resin procurement leads anchored the qualitative base. Primary interview findings triangulated against customs trade data for container imports, ECHA REACH compliance filings, KBA transport safety certification records, and municipal tender documentation databases. Bottom-up unit economics modeling across capacity tiers and end-use segments converged with top-down market sizing from production capacity assessments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning material type, application environment, capacity configuration, and end-user contract structure. CAGRs derived from weighted capacity expansion schedules, replacement cycle compression under EU recycling mandates, and penetration rate assumptions for automated lifting system compatibility. Industry-specific inputs included ECHA enforcement intensity indices and municipal fleet modernization budget allocations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated polymer processors or platform-native entrants would shift outcomes beyond modeled ranges. Quarterly review of ANSM blockchain pilot expansion, KBA certification backlog durations, and HDPE resin price volatility indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Towing Equipment Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Passenger Air Brake Market