
 Crash Lock Box Market | 2026-2036
Crash Lock Box Market Size, Share, and Industry Trends Forecast 2026-2036
Crash Lock Box Market Outlook
Capital-intensity divergence between corrugated specialists and metal fabricators is redrawing competitive boundaries in crash lock box manufacturing. Smurfit Kappa Group leverages its European recycled fiber network to dominate paper-based protective packaging. DS Smith anchors its position through continuous flute design R&D for automated packing lines. Mondi Group specializes in high-strength kraft solutions that compete directly with rigid plastic alternatives in parcel transit.
A crash lock box is a self-erecting corrugated or rigid container with interlocking base flaps that automatically secure upon assembly, typically constructed from double-wall kraft linerboard or micro-flute corrugated fiberboard measuring 1.5–6 mm in thickness, designed to eliminate tape or adhesive sealing in high-velocity fulfillment operations. Fixed lock boxes in steel and composite materials capture the bulk of margin pools in commercial security applications where asset protection outweighs unit cost. Portable lock boxes in aluminum and reinforced plastic represent the fastest-growing material-product intersection, driven by last-mile delivery contractors requiring lightweight, returnable asset carriers. Biometric lock boxes remain a nascent premium tier, with fingerprint-enabled latches commanding specialized supply chains distinct from standard corrugated workflows.
The EU Packaging and Packaging Waste Regulation and REACH compliance requirements for chemical content in adhesives and coatings shape material selection and recyclability claims across European crash lock box supply chains. The US EPA and OSHA jointly influence workplace safety standards for manual assembly ergonomics in high-volume distribution centers. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to internalize collection infrastructure or partner with third-party reverse logistics operators before compliance thresholds tighten.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for corrugated crash lock boxes, forcing converters to eliminate adhesive-dependent sealing methods ahead of 2030 material recovery mandates. E-commerce fulfillment velocity demands are simultaneously pulling automated assembly compatibility into procurement specifications.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recycled content thresholds for paper-based containers are pulling fiber recovery investments into kraft linerboard supply chains ahead of 2035 compliance deadlines.
- Last-mile logistics automation:Parcel sortation hubs in Germany and the Netherlands are specifying tape-free bottom closure to match robotic packing line speeds.
- Micro-flute substitution:1.5–3 mm F- and N-flute profiles are displacing rigid plastic totes in pharmaceutical cold chain distribution.
Market Restraints
- Recycled fiber cost volatility:OCC (old corrugated containers) price swings in European spot markets compress margin predictability for double-wall kraft producers.
- Adhesive chemistry constraints:REACH restrictions on formaldehyde-based resins limit bonding options for high-moisture resistance grades.
- Steel lock box substitution:Fixed metal containers retain preference in commercial security applications where asset protection outweighs unit cost.
Strategic Opportunities
- Biometric latch integration:Fingerprint-enabled portable lock boxes for high-value parcel delivery are opening premium tiers distinct from standard corrugated workflows.
- Returnable aluminum formats:Reinforced portable designs for last-mile contractors in France and Italy address lightweight, multi-use asset carrier demand.
- EPR infrastructure partnerships:Extended producer responsibility schemes in Germany create collection network opportunities ahead of mandatory participation thresholds.
Industry Challenges
- Automated line integration complexity:Retrofitting legacy fulfillment centers for self-erecting box formats requires capex coordination with warehouse management system upgrades.
- Ergonomic compliance timelines:OSHA manual handling standards for high-velocity distribution centers demand assembly force testing protocols that extend product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crash Lock Box Market |
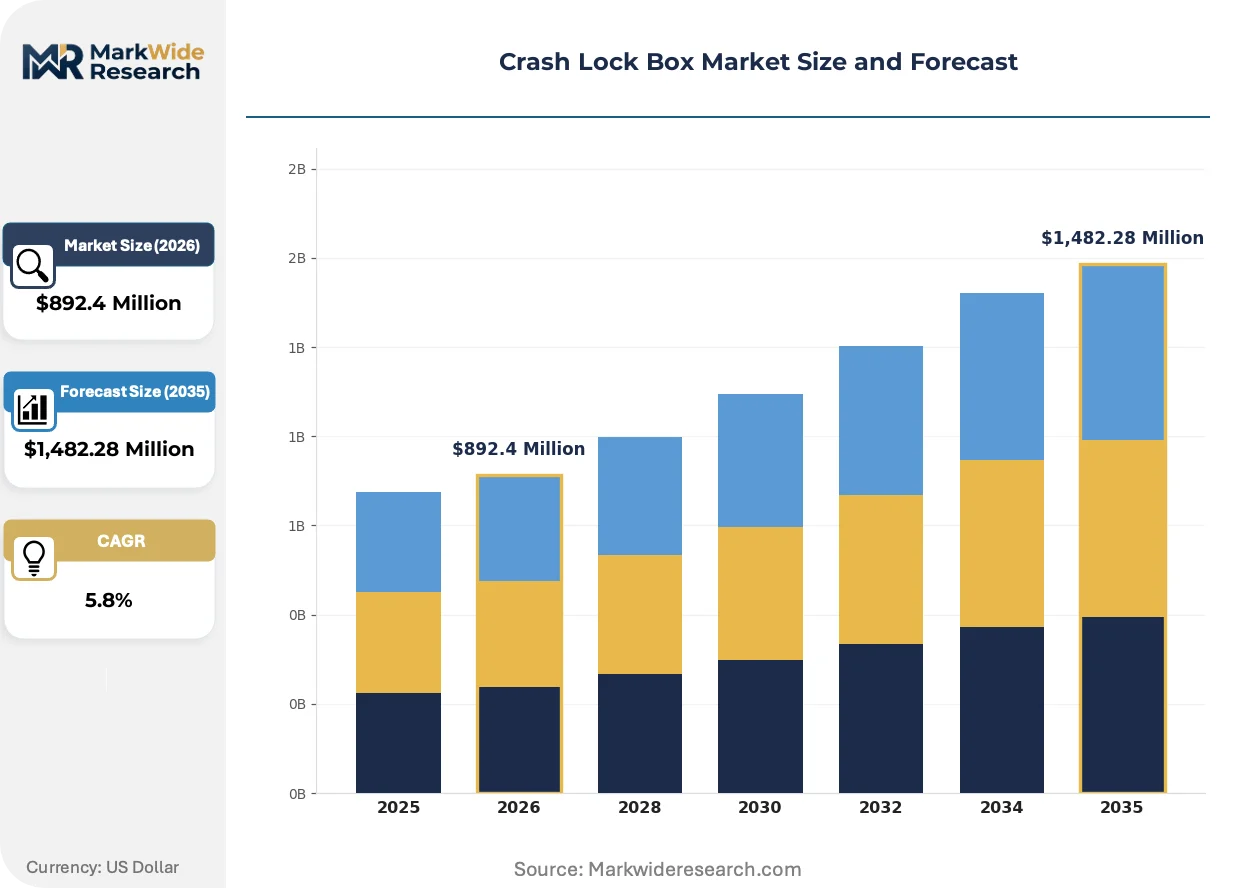
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Lock Box, Fixed Lock Box, Biometric Lock Box, Key Lock Box End User: Households, Commercial Businesses, Transportation Services, Emergency Services Material: Steel, Aluminum, Plastic, Composite Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Smurfit Kappa Group, DS Smith, WestRock Company, International Paper Company, Sealed Air Corporation, Sonoco Products Company, Georgia-Pacific LLC, Mondi Group, FP International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crash Lock Box Market Strategic Shifts
Material science convergence and regulatory chemistry constraints are actively restructuring how crash lock box specifications travel from converter to end-user, with fiber-based and metal-composite formats diverging on performance claims.
Micro-flute corrugated fiberboard is fragmenting traditional protective packaging hierarchies. Pharmaceutical distributors in the Benelux region are adopting 2–3 mm N-flute profiles for temperature-controlled parcel transit at accelerating contract volumes. This substrate shift is fragmenting established supplier relationships as paper specialists capture specifications previously held by rigid plastic molders.
REACH compliance deadlines for adhesive content disclosure are compressing formulation transparency across European supply chains. Industrial converters must now document chemical composition in coatings and bonding agents to maintain recyclability certifications. German automotive parts logistics operations are responding by specifying water-based, starch-adhesive alternatives in procurement tenders.
Consolidated buying by pan-European e-commerce platforms is compressing supplier qualification cycles. Third-party logistics operators in Poland and the Czech Republic are unbundling box specification from freight contracts, creating direct procurement relationships with corrugated specialists. This channel restructuring is most visible in Central European parcel hubs where volume concentration supports dedicated production lines.
Crash Lock Box Market Segmentation
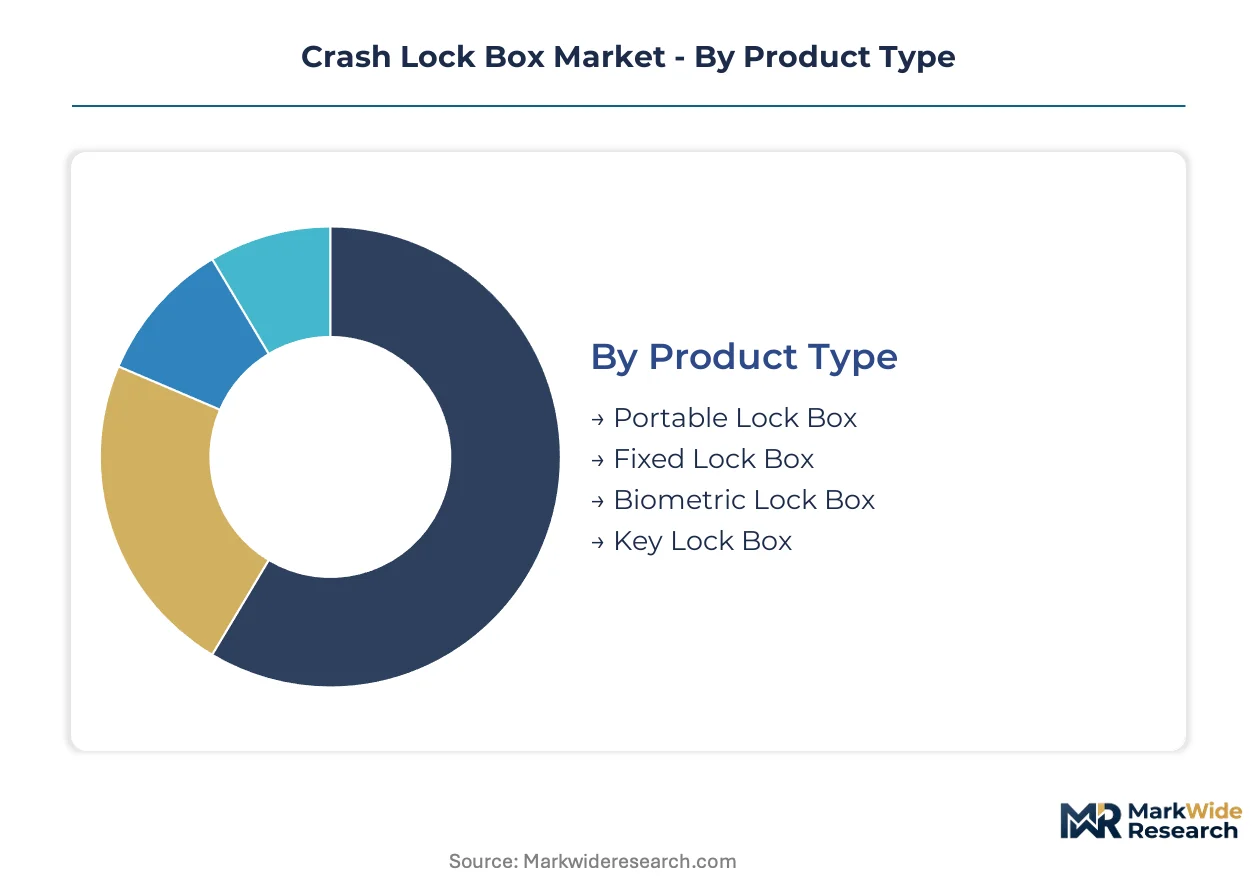
Segmentation in crash lock box markets reveals how regulatory chemistry constraints, automation compatibility demands, and asset protection requirements split procurement specifications across divergent material-product combinations. Understanding these divisions exposes where margin pools concentrate versus where volume scales fastest.
Product Type:
REACH adhesive disclosure mandates and EU Green Deal recovery targets are forcing divergence between corrugated fiber formats and metal-composite security designs.
- Portable Lock Box:Reinforced aluminum and high-impact polymer constructions dominate last-mile contractor fleets. E-commerce logistics operators in Germany and the Netherlands specify lightweight, returnable formats for high-value parcel delivery where asset tracking outweighs unit cost.
- Fixed Lock Box:Steel and composite wall-mounted units anchor commercial security installations. Banks and jewelry retailers in France retain preference for tamper-evident metal enclosures where insurance underwriting mandates physical barrier specifications.
- Biometric Lock Box:Fingerprint-enabled latches command premium tiers in pharmaceutical cold chain distribution.
- Key Lock Box:Mechanical override designs persist in emergency services applications.
Established volume favors fixed lock boxes; emerging adoption favors portable lock boxes.
End User:
Cost tier stratification separates specification authority between centralized procurement teams and distributed purchasing decisions.
- Commercial Businesses:Pan-European e-commerce platforms and third-party logistics operators in Poland and the Czech Republic are unbundling box procurement from freight contracts. Automated packing line compatibility now dominates tender specifications ahead of unit price.
- Transportation Services:Last-mile delivery contractors across France and Italy drive fastest expansion in returnable aluminum formats. Driver-owned fleet models concentrate demand for lightweight, multi-use asset carriers with integrated tracking.
- Households:Direct-to-consumer channels show preference for self-erecting corrugated formats in home office organization.
- Emergency Services:Municipal fire departments and ambulance operators specify rapid-access mechanical designs.
Procurement centralization favors commercial businesses; fleet decentralization favors transportation services.
Material:
Supply concentration in recycled fiber networks versus primary metal extraction shapes regional cost structures and carbon accounting claims.
- Steel:Cold-rolled and stainless grades dominate fixed security installations. German automotive parts logistics operations specify water-based coating alternatives to maintain REACH recyclability certifications.
- Aluminum:Extruded and cast alloys enable the lightest returnable portable formats. Italian last-mile contractors are adopting reinforced aluminum designs for multi-drop delivery routes where payload efficiency determines fuel economics.
- Plastic:High-density polyethylene competes in moisture-resistant pharmaceutical distribution.
- Composite:Fiber-reinforced polymer hybrids occupy niche ballistic-rated applications.
Margin stability favors steel; weight-driven substitution favors aluminum.
Distribution Channel:
Channel restructuring in Central European parcel hubs is fragmenting traditional supplier relationships and compressing qualification cycles.
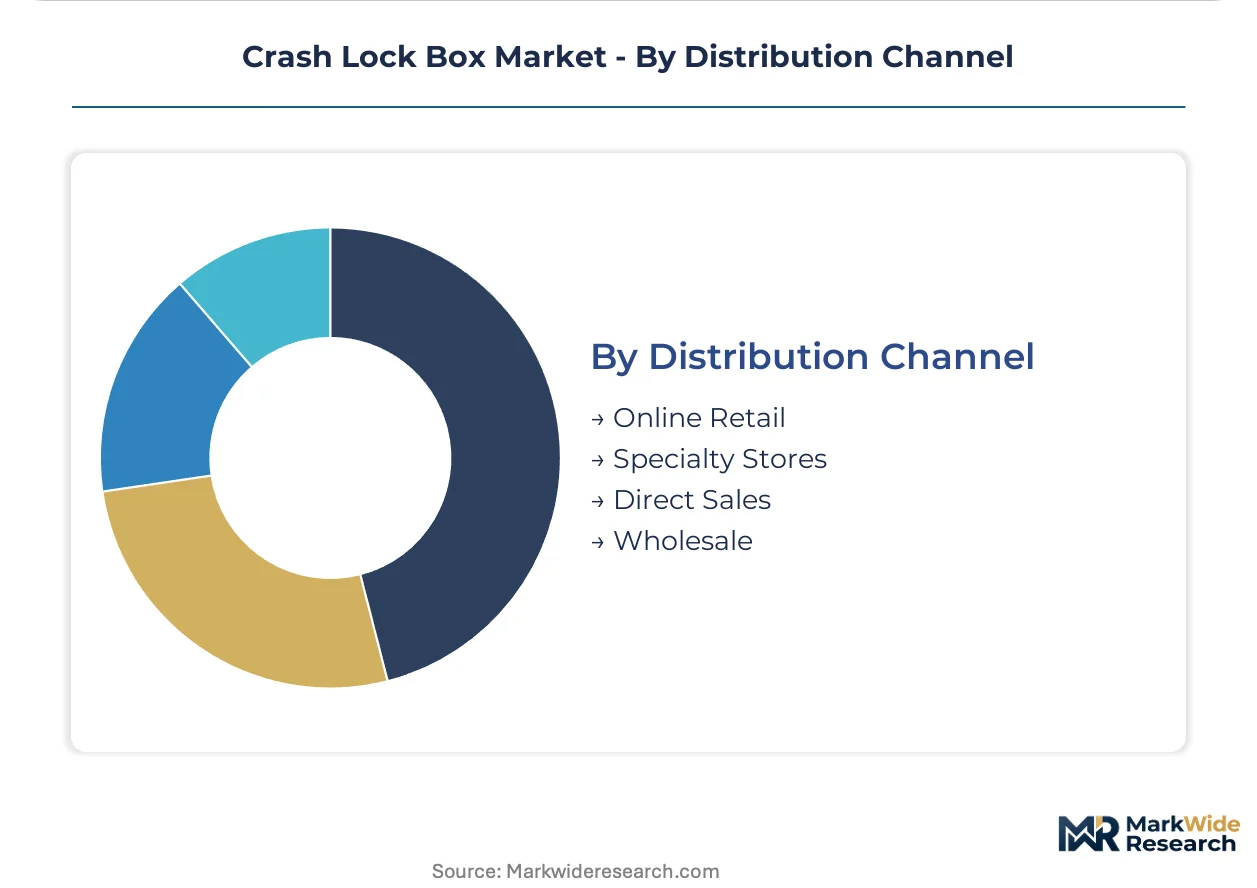
- Direct Sales:Corrugated specialists in Germany's industrial corridor are building dedicated production lines for volume concentration at pan-European e-commerce platforms. Direct relationships bypass traditional packaging distributors and capture specification authority earlier in procurement workflows.
- Online Retail:Self-erecting fiberboard formats move through Amazon Business and specialized MRO platforms. Small commercial buyers in Benelux pharmaceutical distribution source micro-flute profiles through digital channels with rapid specification comparison.
- Specialty Stores:Security equipment retailers retain fixed metal lock box sales.
- Wholesale:Traditional packaging distributors serve legacy fulfillment centers.
Relationship control favors direct sales; transaction velocity favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive logistics buyers prioritize automated assembly compatibility over unit cost, while Italian last-mile contractors weight payload efficiency above all else.
Germany
Automotive parts distributors and pharmaceutical cold chain operators drive specification authority for tape-free bottom closure designs. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that pull fiber recovery investments into kraft linerboard supply chains. The industrial corridor spanning North Rhine-Westphalia and Hesse hosts dedicated production lines for pan-European e-commerce platforms.
France
Banks and jewelry retailers retain preference for tamper-evident metal enclosures where insurance underwriting mandates physical barrier specifications. REACH restrictions on formaldehyde-based resins limit bonding options for high-moisture resistance grades in corrugated formats. The Île-de-France region concentrates procurement teams for luxury goods logistics operations.
Netherlands
Parcel sortation hubs specify tape-free bottom closure to match robotic packing line speeds in high-velocity fulfillment operations. The EU Green Deal packaging targets compress design cycles for adhesive-dependent sealing methods ahead of 2030 mandates. Rotterdam's logistics cluster anchors specification development for automated assembly compatibility.
Italy
Last-mile delivery contractors adopt reinforced aluminum designs for multi-drop delivery routes where payload efficiency determines fuel economics. Driver-owned fleet models concentrate demand for lightweight, returnable asset carriers with integrated tracking. Northern industrial zones around Milan and Turin host aluminum fabricators serving transportation services procurement.
Poland
Third-party logistics operators unbundle box specification from freight contracts, creating direct procurement relationships with corrugated specialists. Central European parcel hubs support volume concentration for dedicated production lines. The Warsaw-Łódź corridor attracts packaging distributors serving legacy fulfillment center retrofits.
Crash Lock Box Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in crash lock box manufacturing. Corrugated giants with captive recycled fiber networks control paper-based protective packaging, while metal fabricators anchor commercial security applications. Two strategic archetypes dominate: fiber-integrated converters leveraging European OCC recovery infrastructure, and aluminum specialists serving returnable last-mile formats. Competitive moves center on M&A for regional capacity consolidation and strategic partnerships for EPR infrastructure sharing.
Among Ireland-based paper packaging conglomerates, Smurfit Kappa Group and Mondi Group exemplify the fiber-integrated archetype with positions spanning kraft linerboard supply chains. DS Smith, a UK-registered converter, represents continuous design R&D investment for automated packing line compatibility. These three entities anchor the tier where recycled content mandates and fulfillment velocity specifications intersect.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| WestRock Company |
| International Paper Company |
| Sealed Air Corporation |
| Sonoco Products Company |
| Georgia-Pacific LLC |
| Mondi Group |
| FP International |
| Others |
Value Chain & Pricing Dynamics
REACH adhesive disclosure mandates gate both supplier qualification and price differentiation simultaneously. Converters must document chemical composition in coatings and bonding agents to maintain recyclability certifications, compressing margin pools for non-compliant producers while rewarding documented transparency with procurement access at pan-European e-commerce platforms.
Pricing Analysis
After-sales service contracts for returnable aluminum formats drive lifetime value capture. Three-tier pricing structure across premium biometric-enabled, standard reinforced portable, and economy single-use corrugated levels separates procurement specifications. Price differentiation rests on REACH certification tier and automated line compatibility grade. Cost compression in fiber-based tiers is intensifying because OCC spot market volatility compresses double-wall kraft margin predictability. Third-party logistics operators in Central Europe show highest price sensitivity; pharmaceutical cold chain buyers demonstrate lowest.
Supply Chain Analysis
Rhine River barge transit through Rotterdam anchors European kraft linerboard distribution. Supply concentration centers on Germany, Poland, and the Netherlands for corrugated conversion. Raw material dependencies draw from Swedish and Finnish pulp networks, German OCC recovery streams, and Chinese aluminum extrusion. Single-source vulnerability in adhesive chemistry formulations poses structural risk. Distribution runs through direct sales relationships with pan-European e-commerce platforms and specialized packaging distributors serving legacy fulfillment retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
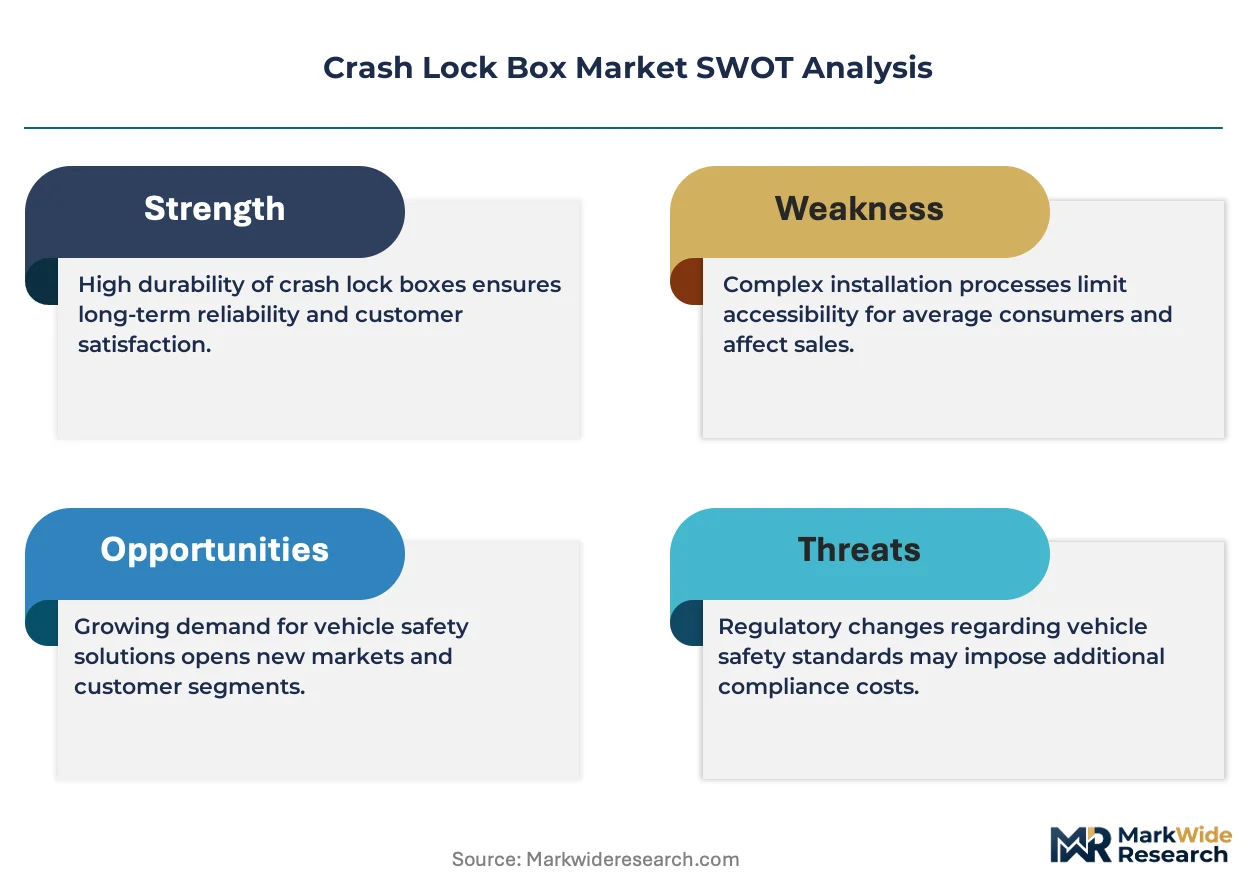
The EU Green Deal packaging targets constitute a high-growth disruption. Mandatory recycled content thresholds and tape-free bottom closure specifications are rewiring procurement authority toward fiber-integrated converters with captive recovery infrastructure.
For Market Incumbents: Secure backward integration into European OCC recovery networks ahead of tightening EPR participation thresholds. Add dedicated production capacity in Germany's North Rhine-Westphalia corridor to match volume concentration at pan-European platforms. Biometric latch specialists threaten premium tier margins; defend through continuous flute design R&D investment for automated packing line compatibility.
For New Entrants and Emerging Players: Last-mile contractor fleet services represent a service-layer gap where incumbents under-serve driver-owned operations in France and Italy. Target aluminum portable formats with integrated tracking for multi-drop delivery routes. White-space exists in water-based starch-adhesive alternatives for German automotive parts logistics. Go-to-market through direct procurement relationships unbundled from freight contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across micro-flute corrugated fiberboard as automated line integration spreads. Long-term viability favors fiber-integrated converters with regional OCC infrastructure control over metal fabricators facing steel substitution pressure. Acquisition target archetype: mid-cap corrugated specialists with REACH-certified adhesive workflows and established e-commerce platform relationships. Monitor biometric-enabled portable adoption rates as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Recovery | Captive fiber supply secures margin stability under EU Green Deal recycled content mandates. |
| Automated Line Compatibility Certification | Tape-free bottom closure specifications from Rotterdam parcel hubs drive procurement authority. |
| Biometric Latch R&D Partnership | Fingerprint-enabled designs open premium tiers distinct from standard corrugated workflows. |
| EPR Infrastructure Joint Venture | German extended producer responsibility schemes create collection network opportunities ahead of mandatory thresholds. |
| Water-Based Adhesive Formulation Transition | REACH-compliant starch alternatives maintain recyclability certifications for automotive logistics buyers. |
Study Parameters
Initial hypotheses were tested against primary input from corrugated plant managers, e-commerce logistics procurement leads, adhesive R&D directors, and last-mile fleet operators and refined through secondary validation. Primary fieldwork combined structured interviews with European converter executives and distribution channel partners. Secondary sources drew from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance databases, customs trade data for kraft linerboard flows, and SEC disclosures from integrated paper packaging conglomerates. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use segments.
Variance decomposition across product type, material grade, end-use industry, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled included portable versus fixed versus biometric lock box formats, fiber-based versus metal-composite materials, and commercial business versus transportation services procurement patterns. CAGRs were derived through trend extrapolation of e-commerce fulfillment velocity and regulatory compliance timelines. Industry-specific forecast inputs incorporated pharmaceutical cold chain adoption curves and last-mile contractor fleet replacement cycles.
Material uncertainties — OCC spot price volatility, REACH adhesive chemistry restrictions, and EPR scheme implementation timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about automated packing line penetration and recycled content threshold enforcement. Practitioners should keep alternative scenarios live as EU Green Deal packaging target revisions and biometric latch cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Rear Axle Market