
 Thrust Bearings Market | 2026-2036
Thrust Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Thrust Bearings Market Analytics
China's capacity build-out in precision bearing manufacturing is reshaping competitive dynamics for thrust bearing supply chains. SKF Group leverages its integrated steel-to-assembly operations across Nordic and Asian facilities to sustain premium positioning in aerospace-qualified product lines. Timken Company anchors North American heavy-industry demand through specialized tapered roller thrust designs for metallurgical and mining equipment. Schaeffler Group differentiates via ceramic hybrid thrust bearings targeting electric powertrain thermal management requirements.
A thrust bearing is an axial-load rotary bearing engineered to transmit force parallel to the shaft axis while constraining lateral movement, typically manufactured from through-hardened alloy steel with cage-guided rolling elements and precision-ground raceways achieving ISO P5 or better geometric tolerances. Its primary industrial purpose is to support vertical shafts, propeller assemblies, and turbine rotors where radial loads are secondary to axial force containment. Roller thrust bearings dominate heavy-load industrial machinery applications due to superior line-contact load distribution and fatigue resistance under continuous operation. Ceramic material adoption is accelerating in aerospace and electric vehicle segments where reduced friction density and extended grease life offset higher unit costs. Ball thrust bearings occupy mature, price-sensitive markets including small appliance and light automotive auxiliary systems where load requirements remain modest.
The EPA enforces lubricant discharge standards that constrain open-system thrust bearing designs in US marine and hydropower installations, while REACH and RoHS frameworks in Europe restrict cadmium and hexavalent chromium in bearing surface treatments and cage materials. China's GB standards and MIIT industrial quality certifications create dual compliance obligations for multinational suppliers serving domestic wind turbine and rail infrastructure programs. Stakeholders must monitor evolving material restrictions and regional certification reciprocity to align product development roadmaps with divergent regulatory timelines.
Market Dynamics
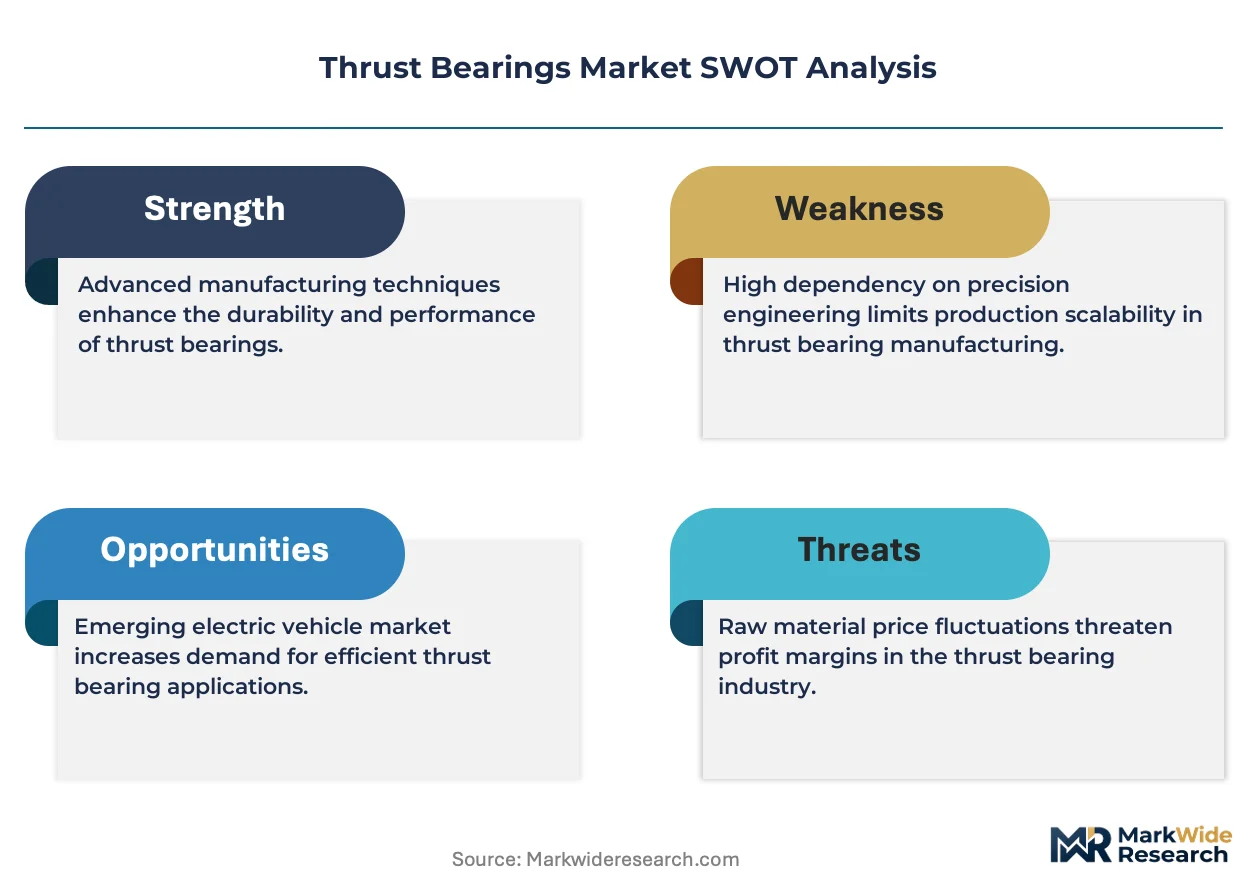
Wind turbine OEM procurement of heavy-load roller thrust bearings for offshore installations is concentrating demand among precision engineering clusters, while EU F-Gas Regulation and REACH compliance tighten material specifications across lubricant and coating supply chains.
Growth Catalysts
- Offshore Wind Scale-Up:Next-generation turbine platforms above 15MW capacity require oversized thrust bearings with enhanced fatigue resistance. German precision clusters around Stuttgart and Schweinfurt are expanding dedicated production lines for these specifications.
- REACH Material Mandates:The EU F-Gas Regulation is phasing down hydrofluorocarbon-based lubricants, forcing reformulation toward synthetic esters and ionic liquids that extend bearing service intervals in continuous-duty industrial machinery.
- Ceramic Hybrid Adoption:Silicon nitride rolling elements are penetrating aerospace-qualified product lines where reduced friction density and thermal stability justify premium positioning against conventional steel bearings.
Market Restraints
- Alloy Steel Input Volatility:Through-hardened bearing-grade steel prices fluctuate with nickel and molybdenum commodity markets, compressing margin predictability for precision-ground raceway manufacturers.
- Supply Concentration Risk:Integrated steel-to-assembly operations in Nordic and Asian facilities dominate premium aerospace-qualified production, creating bottleneck exposure for tier-two suppliers seeking certification.
- Technical Limitation in Scaling:ISO P5 geometric tolerances require specialized grinding equipment with 18-month lead times, constraining rapid capacity expansion for heavy-load industrial machinery demand spikes.
Strategic Opportunities
- Electric Powertrain Thermal Management:Ceramic hybrid thrust bearings address heat rejection challenges in high-speed motor applications, opening white space in electric vehicle gearbox and drivetrain assemblies.
- India Rail Infrastructure:The country's PLI scheme for advanced manufacturing is attracting bearing suppliers to establish domestic production for high-speed rail and metro expansion programs.
- Condition Monitoring Convergence:Integration of vibration sensors and edge computing into bearing housings enables predictive maintenance contracts, shifting revenue from unit sales to performance-based service models.
Industry Challenges
- Metrology Skill Shortage:Precision grinding of ISO P5 raceways requires specialized technicians with 5+ year apprenticeships; training pipelines lag replacement demand in Stuttgart and Schweinfurt clusters.
- Dual Certification Burden:China's GB standards and MIIT industrial quality certifications create parallel compliance obligations for suppliers serving domestic wind turbine programs alongside EU REACH frameworks.
- Legacy System Integration:Retrofitting ceramic hybrid thrust bearings into existing turbine and metallurgical equipment requires redesigned housings and lubrication circuits, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrust Bearings Market |
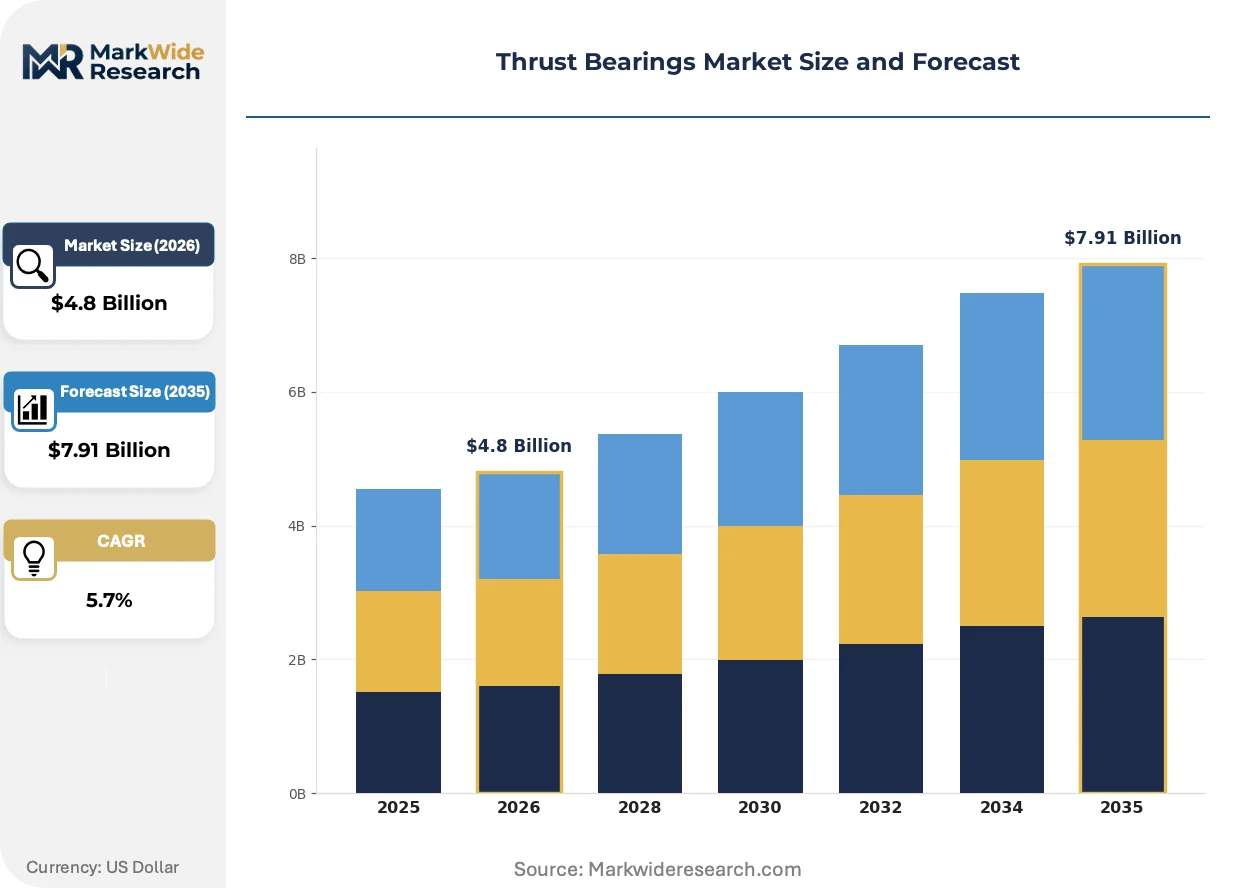
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Thrust Bearings, Roller Thrust Bearings, Angular Contact Thrust Bearings, Fluid Thrust Bearings Material: Steel, Ceramic, Polymer, Composite Application: Aerospace, Automotive, Marine, Industrial Machinery Load Capacity: Light Load, Medium Load, Heavy Load, Extra Heavy Load |
| Companies Covered | SKF Group, Timken Company, NSK Ltd., Schaeffler Group, NTN Corporation, JTEKT Corporation, NACHI-Fujikoshi Corp., Auburn Bearing & Manufacturing, Hartford Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrust Bearings Market Evolving Landscape
Additive manufacturing of bearing cages and customized raceway profiles is compressing prototyping timelines and enabling geometry optimizations impossible with conventional machining workflows.
Silicon nitride ceramic rolling elements deliver 40% lower friction density than hardened steel equivalents while extending grease life by a factor of three. Aerospace propulsion system OEMs are qualifying these materials for main shaft thrust bearings in next-generation turbofan programs. The technology is rendering obsolete conventional steel bearing specifications for applications above 200°C operating temperatures.
The EU F-Gas Regulation mandates 79% phasedown of hydrofluorocarbon consumption by 2030, eliminating common bearing lubricant base stocks. Lubricant formulators are accelerating synthetic ester and polyalkylene glycol development to maintain viscosity stability across -40°C to 150°C operating windows. Wind turbine OEMs in Germany and Denmark are conducting accelerated life testing on reformulated greases to validate 20-year service projections.
Direct procurement relationships between wind turbine OEMs and precision bearing manufacturers are displacing traditional distributor channels for offshore installation contracts. Vestas and Siemens Gamesa are negotiating multi-year supply agreements with dedicated production capacity allocations. This pattern concentrates most visibly in Denmark and northern Germany, where turbine final assembly and bearing manufacturing clusters overlap geographically.
Thrust Bearings Market Segmentation
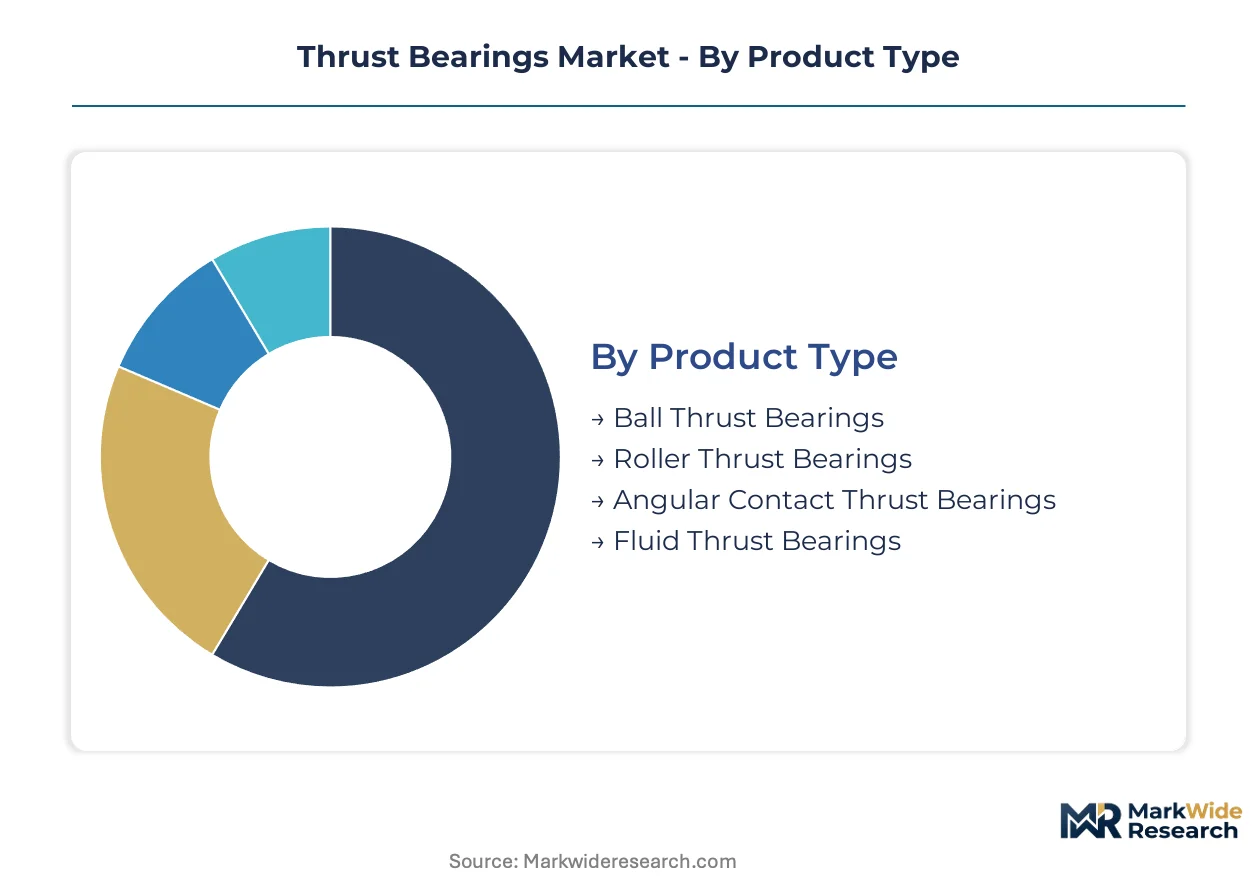
Thrust bearing procurement cycles vary dramatically by segment. Roller bearings for wind turbines operate on 20-year replacement schedules, while ball bearings in automotive auxiliaries turn over every 3-5 years. Material and load specifications further stratify inventory velocity across industrial supply chains.
Product Type:
Replacement cycles stretch from months in light automotive to decades in offshore wind infrastructure, dictating entirely different commercial relationships and service attach rates.
- Roller Thrust Bearings:Line-contact geometry distributes axial loads across cylindrical or tapered rolling elements. Demand concentrates in German precision clusters supplying Vestas and Siemens Gamesa for 15MW+ offshore turbine main shafts, where fatigue resistance under continuous rotation justifies premium pricing.
- Ball Thrust Bearings:Point-contact design suits moderate loads with reduced friction coefficients. Automotive auxiliary systems in Stuttgart supply chains dominate procurement, though electric powertrain simplification is compressing addressable volume in this mature segment.
- Angular Contact Thrust Bearings:Combined radial-axial load capacity serves machine tool spindles and precision rotary tables. Japanese and German machine builders specify these for ISO P5 tolerance maintenance in high-speed cutting operations.
- Fluid Thrust Bearings:Hydrodynamic oil films support extreme loads without metal-to-metal contact. Marine propulsion and hydroelectric turbine applications in US and Scandinavian installations specify these for vibration damping in multi-megawatt power transmission.
Roller thrust bearings dominate installed base tonnage. Angular contact designs are where expansion concentrates for precision machinery rebuild programs.
Material:
Cost tiers separate commodity steel specifications from ceramic hybrids commanding 4-6x unit premiums, with polymer and composite intermediates carving niche positions in corrosive environments.
- Steel:Through-hardened alloy grades remain the volume foundation across industrial machinery. REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers toward alternative passivation chemistries.
- Ceramic:Silicon nitride rolling elements reduce friction density 40% below steel equivalents. Aerospace propulsion qualification programs at Safran and Rolls-Royce are validating these for main shaft applications above 200°C operating temperatures.
- Polymer:PTFE and PEEK matrix bearings resist seawater corrosion without lubrication. Marine stern tube and desalination pump installations specify these where metal fatigue and electrolysis risk overlap.
- Composite:Fiber-reinforced thermoset cages and raceways reduce mass in racing and UAV applications. Formula 1 gearbox suppliers and drone propulsion OEMs drive prototype volumes.
Steel commands installed base volume. Ceramic silicon nitride is climbing the fastest as thermal management requirements intensify across electric powertrain and aerospace segments.
Application:
Customer concentration patterns diverge sharply: aerospace demands qualified dual-source redundancy while automotive pushes for single-source cost compression at massive scale.
- Industrial Machinery:Metallurgical equipment, mining crushers, and cement mills consume heavy-load roller designs. Timken anchors North American demand through tapered roller thrust configurations purpose-built for continuous shock loading.
- Aerospace:Turbofan main shaft and propulsion system bearings require FAA/EASA dual certification. SKF sustains premium positioning through integrated steel-to-assembly operations with full material traceability.
- Automotive:Electric powertrain reduction gears and motor support bearings are displacing legacy transmission applications. Schaeffler targets thermal management requirements with ceramic hybrid designs for 20,000+ RPM motor speeds.
- Marine:Controllable pitch propeller hubs and azimuth thrusters specify corrosion-resistant specifications. EPA lubricant discharge standards constrain open-system designs in US territorial waters.
Industrial machinery dominates installed base. Aerospace is where expansion concentrates for margin-accretive qualified production.
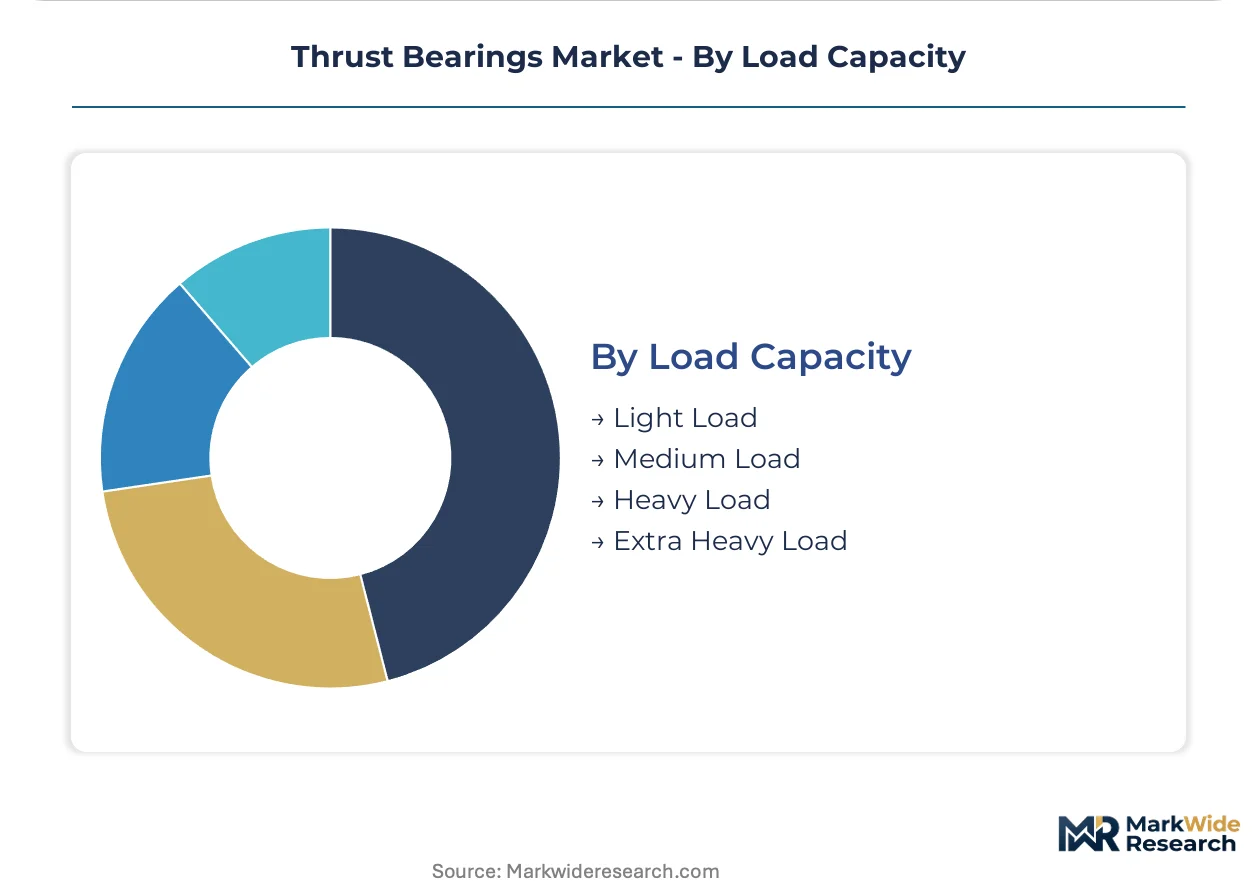
Load Capacity:
Volume tiers invert against margin structure: light-load segments compete on price while extra heavy-load specifications sustain technical premiums through engineering service bundling.
- Heavy Load:50-500 kN axial capacity serves wind turbine main shafts and large industrial gearboxes. German precision clusters around Schweinfurt dedicate grinding capacity to ISO P5 raceway tolerances for this specification band.
- Extra Heavy Load:Above 500 kN capacity supports hydroelectric turbines and ship propulsion shafts. Specialized foundry partnerships in Nordic facilities control billet supply for these forgings.
- Medium Load:10-50 kN range covers general industrial pumps and compressors. Distributor channels dominate procurement with standard catalog specifications.
- Light Load:Below 10 kN capacity serves small appliances and automotive auxiliaries. Chinese manufacturing clusters compete aggressively on cost in this commoditized tier.
Heavy load specifications dominate installed base. Extra heavy load is gaining share fastest as offshore wind platforms scale beyond 15MW capacity ratings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes thrust bearings differently than China or the United States. German procurement prioritizes precision-ground raceways for continuous-duty industrial machinery, while Chinese demand concentrates on volume-scale wind turbine installations and US buyers emphasize aerospace-qualified dual-source redundancy.
United States
EPA lubricant discharge standards constrain open-system thrust bearing designs in marine and hydropower installations. FAA certification requirements for aerospace propulsion systems sustain premium-tier demand for material-traceable production. Connecticut and Ohio host precision grinding clusters serving turbofan main shaft programs.
Germany
REACH and EU F-Gas Regulation mandates are phasing down hydrofluorocarbon-based lubricants, forcing synthetic ester reformulation. Stuttgart and Schweinfurt precision engineering clusters supply tier-one automotive and industrial machinery builders with ISO P5 tolerance bearings. Vestas and Siemens Gamesa negotiate multi-year supply agreements with dedicated capacity allocations.
China
MIIT industrial quality certifications and GB standards create dual compliance obligations for multinational suppliers. Yangtze River Delta manufacturing bases are expanding precision bearing capacity for domestic wind turbine and rail infrastructure programs. Ningbo and Wuxi clusters compete on cost for light-load automotive auxiliary specifications.
Japan
METI industrial policy supports ceramic hybrid bearing development for electric powertrain thermal management. Nagoya and Osaka precision manufacturing zones supply machine tool spindle applications requiring combined radial-axial load capacity. JIS standards alignment facilitates aerospace component exports to EASA-qualified programs.
India
PLI scheme incentives for advanced manufacturing are attracting bearing suppliers to establish domestic production. Mumbai-Pune and Chennai industrial corridors target high-speed rail and metro expansion programs. BIS certification requirements create compliance adaptation costs for European and Japanese entrants.
Thrust Bearings Market Competitive Landscape
Capability concentration sits with integrated steel-to-assembly specialists; scale advantage sits with precision grinding clusters serving standardized industrial specifications. The market structures around three tiers: aerospace-qualified dual-source suppliers, automotive-dedicated volume producers, and regional cost competitors. Strategic moves center on ceramic hybrid technology licensing and captive supply of through-hardened alloy steel billets.
Among Nordic and Asian integrated producers, SKF Group and NSK Ltd. exemplify the aerospace-qualified tier with full material traceability. Timken Company occupies a position within the heavy-industry specialist archetype, serving North American metallurgical and mining equipment demand. Schaeffler Group represents the automotive-electric powertrain convergence vector, targeting thermal management requirements in high-speed motor applications.
| Leading Market Players |
|---|
| SKF Group |
| Timken Company |
| NSK Ltd. |
| Schaeffler Group |
| NTN Corporation |
| JTEKT Corporation |
| NACHI-Fujikoshi Corp. |
| Auburn Bearing & Manufacturing |
| Hartford Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
The Hamburg-Rotterdam maritime corridor carries through-hardened alloy steel billets from Nordic foundries to German precision grinding clusters, with freight cost volatility amplifying margin compression for ISO P5 tolerance producers while reinforcing price premiums for captive steel-to-assembly operations serving aerospace-qualified product lines.
Pricing Analysis
Long-term offtake contracts dominate procurement between wind turbine OEMs and precision bearing manufacturers, with Vestas and Siemens Gamesa negotiating multi-year supply agreements that lock dedicated capacity allocations. Pricing stratifies across aerospace-qualified, automotive-dedicated, and regional cost tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in light-load automotive specifications is intensifying because Chinese manufacturing clusters compete aggressively on standard catalog bearings. Automotive auxiliary buyers exhibit highest price sensitivity, while offshore wind OEMs prioritize fatigue resistance and 20-year service intervals over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for multinational bearing suppliers serving dual compliance markets. Manufacturing concentration rests on Germany, China, and Japan, with through-hardened alloy steel, silicon nitride ceramic powder, and synthetic ester lubricants as critical input dependencies. Single-source vulnerability persists for specialized grinding equipment with 18-month lead times, constraining rapid capacity expansion. Distribution runs through direct procurement relationships for offshore wind contracts, while distributor channels handle standard industrial specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FAA/EASA dual certification and REACH material traceability requirements creates structural barriers that protect incumbent positioning against price-based competition.
For Market Incumbents: Harden supply security through captive billet supply partnerships with Nordic foundries, insulating against nickel and molybdenum commodity volatility. Deepen certification moats by accelerating silicon nitride qualification programs with Safran and Rolls-Royce before emerging ceramic specialists achieve aerospace propulsion approval. Channel control through direct procurement relationships with Vestas and Siemens Gamesa locks out tier-two competitors from offshore wind growth.
For New Entrants and Emerging Players: India's PLI scheme for advanced manufacturing offers the most penetrable geographic entry point, with Mumbai-Pune and Chennai industrial corridors targeting high-speed rail and metro expansion programs where BIS certification requirements create manageable compliance adaptation costs. Target electric powertrain thermal management as the fastest-climbing application segment, where ceramic hybrid bearings for 20,000+ RPM motor speeds command 4-6x unit premiums against steel equivalents. Pursue technology licensing partnerships with established lubricant formulators to shortcut synthetic ester development timelines.
For Investors and Strategic Acquirers: Precision grinding specialists with ISO P5 capability and established apprentice training pipelines represent the most defensible acquisition archetype, given the 5+ year technician development cycle that cannot be replicated through capital deployment alone. Monitor ceramic hybrid adoption curves in aerospace propulsion qualification programs as the critical inflection signal, with Safran and Rolls-Royce validation timelines indicating when thermal management premiums will expand from electric powertrains into mainstream industrial applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Technology Licensing | Accelerates market entry for silicon nitride bearing formulations without internal R&D infrastructure. |
| Backward Integration into Alloy Steel Billets | Secures material traceability for FAA/EASA dual certification requirements in aerospace propulsion systems. |
| Condition Monitoring Convergence | Shifts revenue from unit sales to predictive maintenance contracts with vibration sensor integration. |
| Long-term Supply Agreement with Wind OEMs | Locks dedicated grinding capacity for 15MW+ offshore turbine main shaft specifications. |
| Geographic Expansion to India PLI Corridors | Captures high-speed rail and metro procurement under domestic production incentives. |
Research Methodology
Initial hypotheses were tested against primary input from wind turbine procurement directors, precision bearing plant managers, metallurgical equipment maintenance directors, and aerospace propulsion system engineers, and refined through secondary validation against customs trade data, SEC 10-K filings, MIIT industrial quality certification records, and ECHA REACH substance restriction updates. Bottom-up demand modeling across product type, material, application, and load capacity dimensions was triangulated against top-down macroeconomic indicators.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeling across roller versus ball versus ceramic hybrid product architectures, steel versus silicon nitride material tiers, and wind turbine versus aerospace versus automotive application clusters. CAGRs were derived from installed base replacement cycle analysis and new capacity absorption rates, incorporating alloy steel price elasticity and REACH compliance cost pass-through assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese precision grinding clusters or accelerated ceramic hybrid adoption curves would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Wheel Chocks Market
Vehicle Components
Brake Hoses Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Wheel Spindle Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Bicycle Frames Market