
 Exterior Car Accessories Market | 2026-2036
Exterior Car Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Exterior Car Accessories Market Analysis
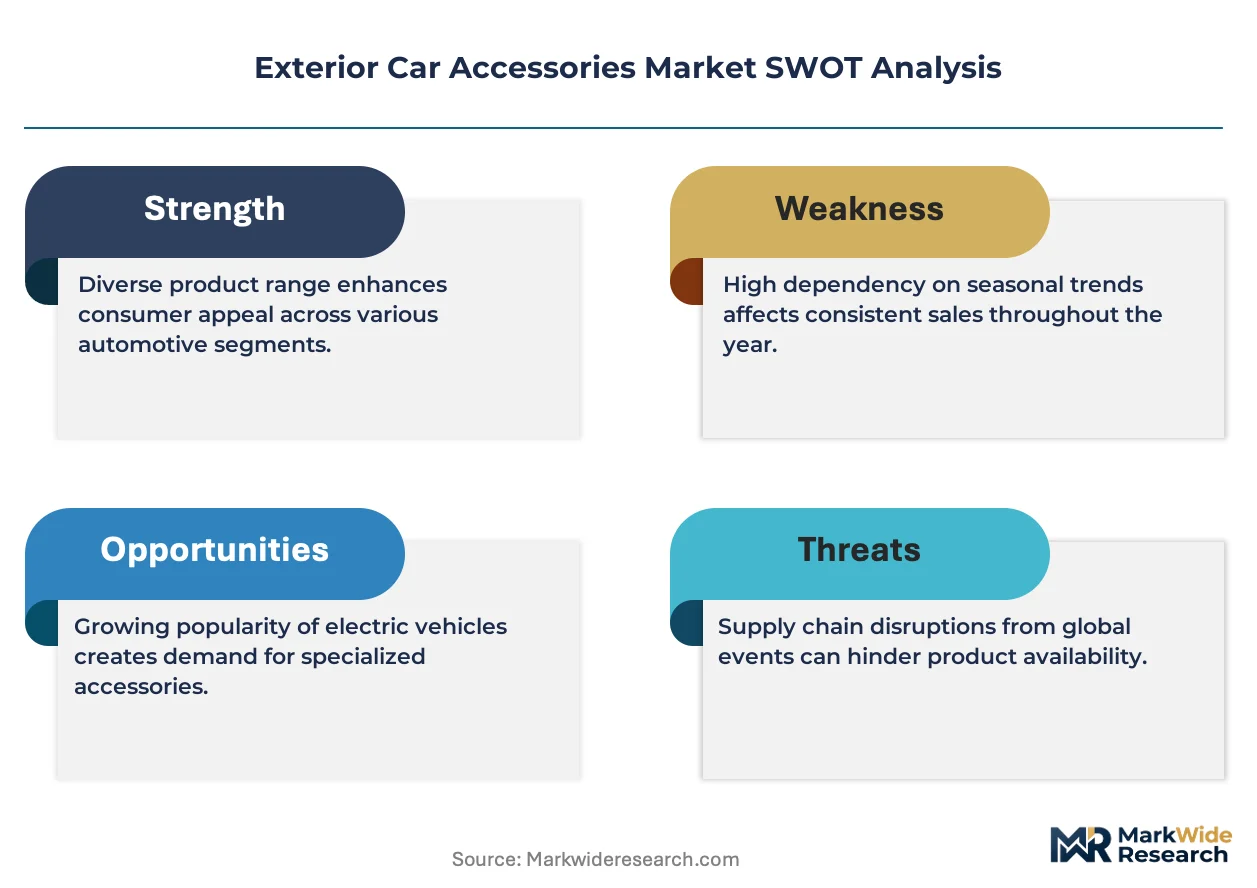
Modular bundling of roof racks with crossbars and cargo boxes is repositioning how consumers evaluate utility upgrades. Thule Group leverages its Nordic engineering heritage to dominate premium cargo management systems across European and North American retail channels. Lund International anchors its competitive stance through deep specialization in truck bed protection and exterior styling for the North American pickup segment. WeatherTech sustains manufacturing scale through in-house production of floor liners and window deflectors, extending its brand into exterior protection categories.
Exterior car accessories encompass add-on components—bumpers, spoilers, roof racks, side steps—fabricated from injection-molded ABS plastics, stamped aluminum alloys, or pre-preg carbon fiber laminates, designed to enhance aerodynamic performance, payload utility, or vehicle aesthetics without altering factory powertrain architecture. Carbon fiber spoilers command premium positioning due to weight reduction and motorsport-derived aesthetics, while fiberglass maintains economy-tier penetration through lower mold costs and repairability. Off-roading applications in roof racks and side steps represent the fastest-growing application cluster as overlanding participation expands, whereas DIY installation methods face margin compression against professional fitment requirements for advanced driver-assistance system recalibration.
NHTSA Federal Motor Vehicle Safety Standards govern bumper impact absorption and pedestrian injury criteria in the United States, while ECE R58 and ECE R78 regulations in Europe mandate rear underrun protection and brake-system compatibility for accessory-integrated vehicles. China's GB standards administered by MIIT impose material recyclability thresholds and exterior protrusion limits that constrain spoiler and guard geometries. Stakeholders must monitor diverging regional compliance pathways as electrification shifts vehicle front-end architecture and load-bearing specifications for accessory mounting systems.
Market Dynamics
Electrification is compressing front-end vehicle architecture and forcing accessory manufacturers to redesign mounting systems around battery thermal management zones and pedestrian-impact crumple zones.
Growth Catalysts
- Overlanding participation:North American and Australian consumers are equipping SUVs and trucks with roof-top tents, recovery boards, and auxiliary lighting for remote terrain traversal.
- ECE R58 rear underrun mandates:European commercial vehicle operators must install certified rear guards, creating pull-through demand for compatible passenger vehicle accessories.
- Carbon fiber pre-preg layup:Motorsport-derived manufacturing is lowering unit costs for performance spoilers and diffusers, expanding accessibility beyond luxury tiers.
Market Restraints
- Aluminum alloy price volatility:Stamping operations for side steps and running boards face margin pressure from London Metal Exchange fluctuations.
- ABS resin supply concentration:Injection molders depend on petrochemical feedstock clusters in the US Gulf Coast and Northeast Asia for bumper-grade polymer.
- ADAS recalibration requirements:NHTSA guidelines mandate professional fitment for accessories affecting radar or camera fields, constraining DIY channel growth.
Strategic Opportunities
- India pickup market emergence:Mahindra and Tata commercial vehicle expansion is creating first-mover positioning for bed liner and tonneau cover suppliers.
- Vehicle-to-load (V2L) integration:Electric pickup auxiliary power outlets enable powered accessory categories—refrigerated cargo boxes, tool charging stations.
- China GB standard recyclability thresholds:MIIT material mandates favor domestic manufacturers with closed-loop polymer recovery, disadvantaging import-dependent competitors.
Industry Challenges
- Composite technician scarcity:Carbon fiber spoiler production requires skilled laminators and autoclave operators in short supply across manufacturing regions.
- Homologation timeline compression:ECE R78 brake-system compatibility testing for integrated accessories extends product launch cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exterior Car Accessories Market |
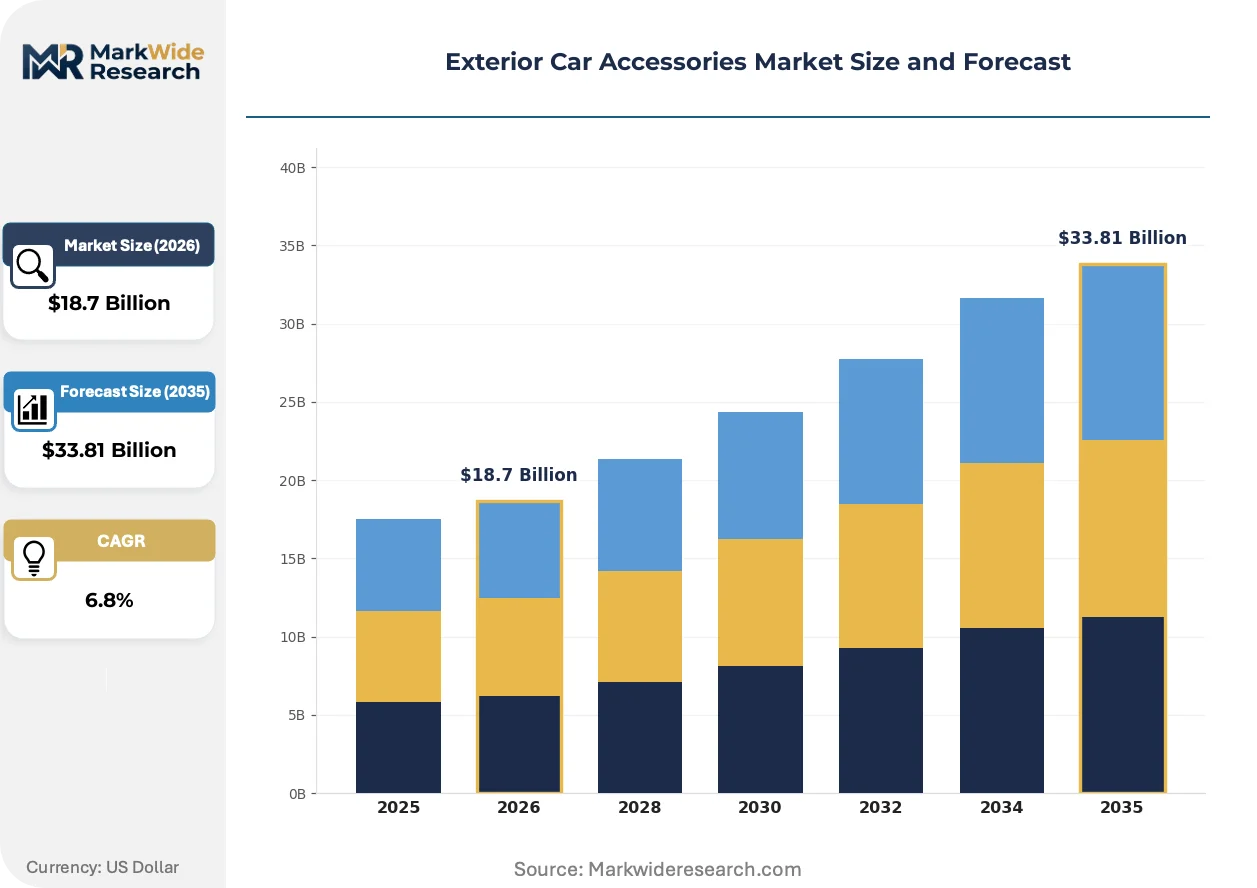
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bumpers, Spoilers, Roof Racks, Side Steps Material: Plastic, Metal, Carbon Fiber, Fiberglass Application: Off-Roading, Aesthetic Enhancement, Protection, Cargo Management Installation: DIY, Professional, Modular, Fixed |
| Companies Covered | Thule Group, Lund International, Covercraft Industries, WeatherTech, HEL LA KGaA Hueck & Co., Oakmore Pty Ltd, Car Mate MFG.CO., LTD., Magna International, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exterior Car Accessories Market Emerging Trajectories
Accessory design is pivoting from universal fitment toward vehicle-specific digital modeling, with 3D scanning and parametric CAD enabling rapid prototyping for fragmented EV platform geometries.
Additive manufacturing is decentralizing tooling investment for low-volume spoiler and guard production. Specialty tuners in Germany and Japan are adopting fused deposition modeling for ABS prototypes, compressing design iteration cycles from weeks to days and enabling batch sizes below 500 units economically.
REACH chemical substance restrictions are forcing reformulation of chrome-plated ABS exterior trim. ECHA SVHC candidate list expansion targets hexavalent chromium in decorative molding, compelling suppliers to transition toward physical vapor deposition aluminum finishes or painted alternatives by 2026.
Direct-to-consumer configuration platforms are displacing traditional retail assortment models. Thule Group and competing cargo specialists now offer online rack configurators that generate BOM-specific installation quotes, capturing buyer preference data while reducing SKU proliferation in brick-and-mortar channels—most advanced in Scandinavian and US markets.
Exterior Car Accessories Market Segmentation
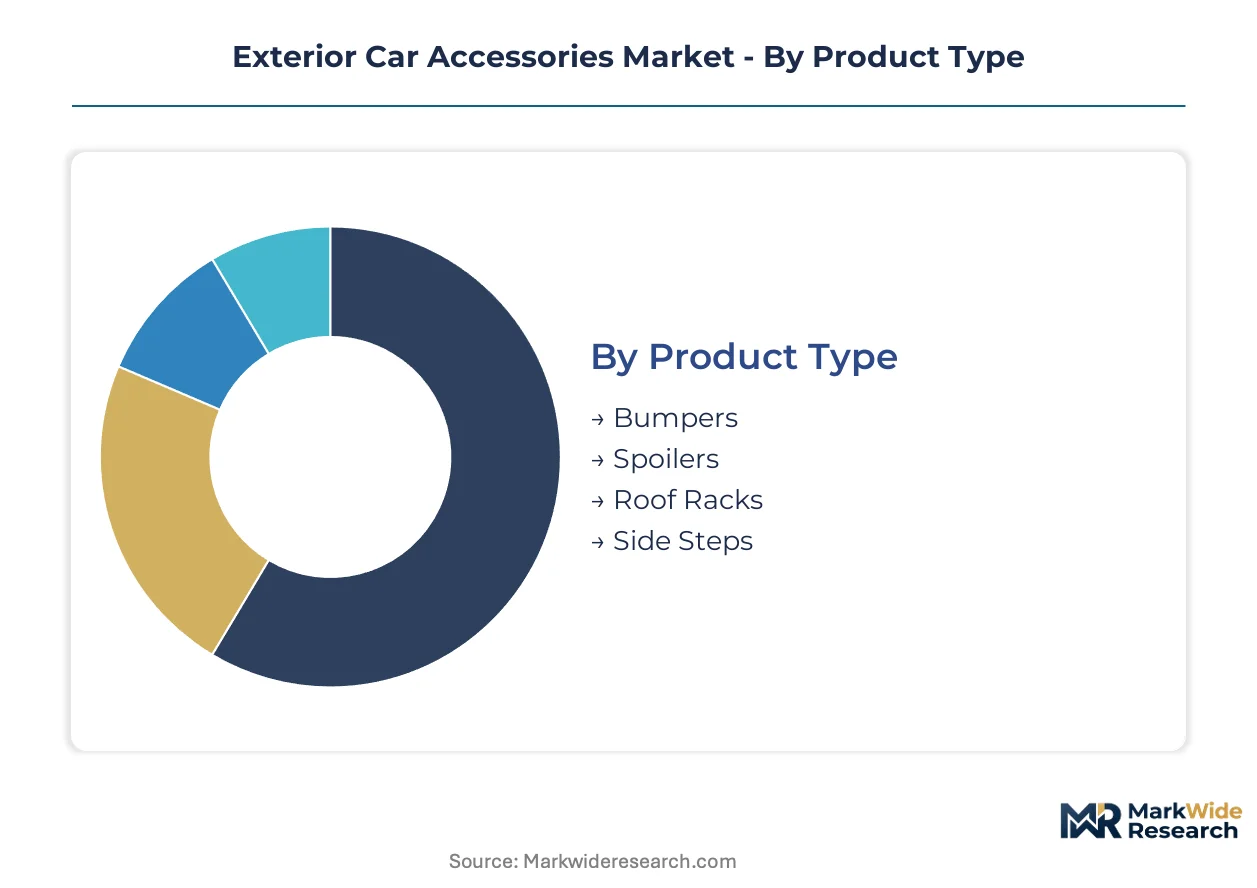
Exterior car accessories manufacturers must align production assets with divergent capital requirements across product architectures. Material selection and installation complexity create distinct margin profiles that reshape competitive positioning within each segment cluster.
Product Type:
Capital intensity peaks with roof rack systems requiring multi-axis CNC bending and weather-sealing validation, while bumper programs demand lower mold investments but higher homologation spending.
- Roof Racks:Aluminum extrusion and aerodynamic wind-tunnel testing dominate production economics. Demand clusters in the United States and Germany as overlanding participation drives cargo management upgrades.
- Spoilers:Pre-preg carbon fiber layup or injection-molded ABS construction depending on performance tier. Germany's motorsport aftermarket and China's EV personalization segment absorb premium volumes.
- Bumpers:Stamped steel or polymer assemblies designed for NHTSA pedestrian-impact absorption. Professional fitment channels dominate due to ADAS recalibration requirements.
- Side Steps:Tubular steel or aluminum extrusions with powder-coat finishing. North American pickup and SUV applications drive volume concentration.
Roof racks absorb the bulk of installed capacity; spoilers are expanding most quickly.
Material:
Raw material procurement patterns separate commodity-grade suppliers from specialized composite houses with captive autoclave capacity.
- Plastic:ABS and polypropylene injection molding serves economy-tier bumpers and trim. Gulf Coast petrochemical feedstock dependency creates supply concentration risk.
- Metal:Stamped aluminum alloys and steel tubing for side steps and running boards. London Metal Exchange price volatility compresses margins for independent stampers.
- Carbon Fiber:Motorsport-derived pre-preg layup and autoclave curing for performance spoilers and diffusers. Technician scarcity constrains output expansion across manufacturing regions.
- Fiberglass:Lower mold costs and repairability sustain economy-tier spoiler penetration. Hand-layup methods dominate small-batch production.
Plastic commands the greatest production volume; carbon fiber is climbing the fastest.
Application:
End-use purpose determines distribution channel selection and installation service bundling.
- Off-Roading:Recovery boards, auxiliary lighting, and roof-top tent mounting systems. Australian and United States consumers equip SUVs for remote terrain traversal.
- Cargo Management:Crossbar systems, cargo boxes, and bike carriers. Modular bundling repositions utility upgrade evaluation in Scandinavian and North American retail channels.
- Protection:Bumper guards, hood deflectors, and door edge trim. WeatherTech extends manufacturing scale into exterior protection from floor liner dominance.
- Aesthetic Enhancement:Chrome delete kits, body-colored mirror caps, and decorative molding. REACH chemical restrictions force hexavalent chromium phase-out toward physical vapor deposition alternatives.
Cargo management absorbs the bulk of installed capacity; off-roading is gaining share fastest.
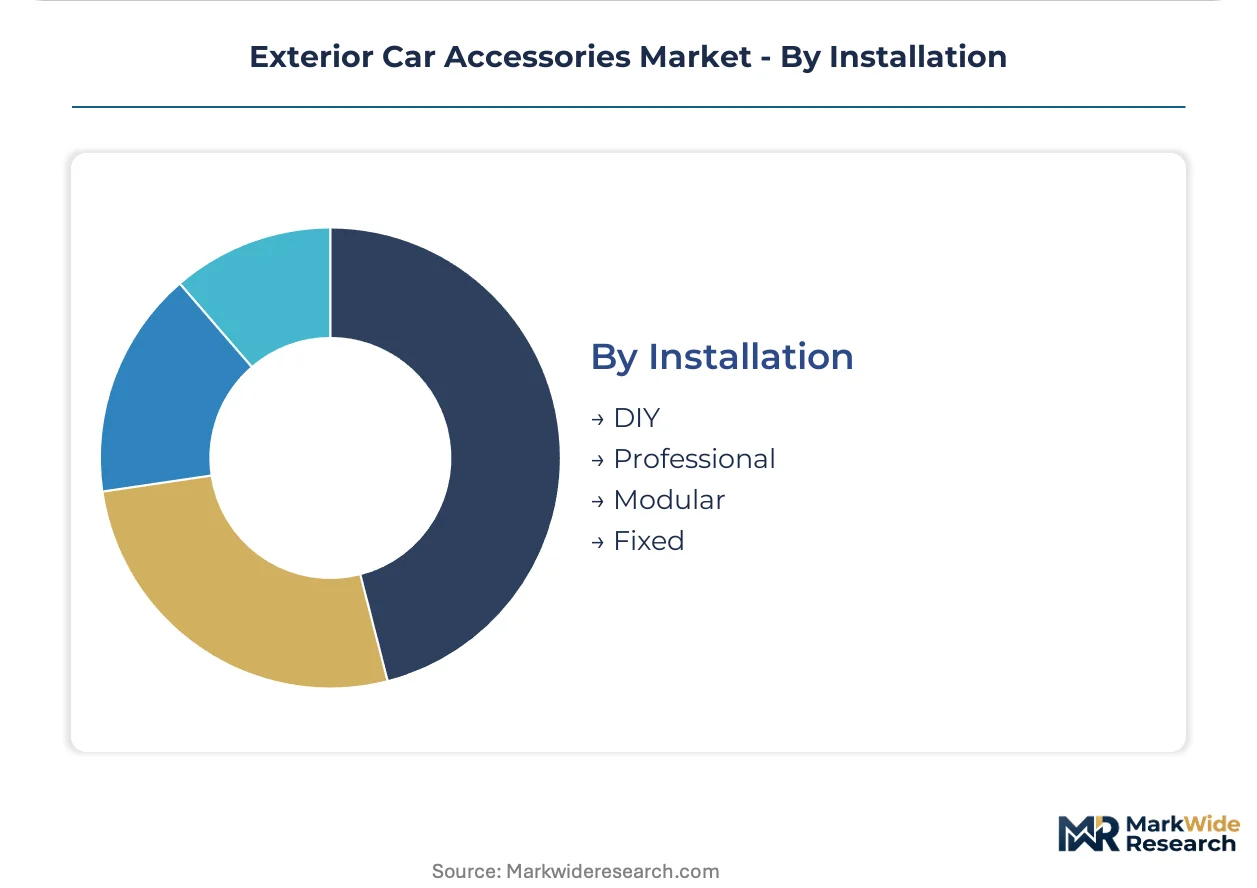
Installation:
Fitment method selection constrains channel economics and customer acquisition costs.
- Professional:Required for accessories affecting radar or camera fields per NHTSA guidelines. Brake-system compatibility testing under ECE R78 extends launch cycles.
- DIY:Clip-on window deflectors and adhesive trim face margin compression against professional fitment growth. Online configurators reduce SKU proliferation in brick-and-mortar channels.
- Modular:Crossbar-and-cargo-box bundling enables upgrade pathing. Thule Group dominates premium cargo management through Nordic engineering positioning.
- Fixed:Permanent welded or bolted installations for commercial vehicle rear guards under ECE R58 mandates.
Professional installation absorbs the bulk of service capacity; modular systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of exterior car accessories clusters in manufacturing corridors serving domestic consumption hubs, with assembly plants concentrated near automotive OEM clusters and aftermarket distribution networks radiating toward high-vehicle-density metropolitan zones.
United States
Overlanding participation in the Rocky Mountain and Pacific Northwest regions drives demand for roof racks and auxiliary lighting systems. NHTSA Federal Motor Vehicle Safety Standards govern bumper impact absorption and pedestrian injury criteria for all aftermarket installations. Detroit's automotive supplier corridor hosts stamping operations for side steps and running boards serving the domestic pickup segment.
Germany
Motorsport-derived personalization among performance vehicle owners sustains premium spoiler and diffuser demand. ECE R58 rear underrun protection mandates and ECE R78 brake-system compatibility requirements shape accessory homologation timelines. Stuttgart's automotive engineering cluster anchors carbon fiber composite production for aerodynamic components.
China
EV platform proliferation creates fragmented geometries requiring vehicle-specific digital modeling for accessory fitment. MIIT-administered GB standards impose material recyclability thresholds and exterior protrusion limits constraining spoiler designs. Shanghai's Yangtze River Delta manufacturing belt concentrates injection molding capacity for bumper-grade ABS polymers.
Australia
Remote terrain traversal culture supports robust uptake of roof-top tents, recovery boards, and auxiliary lighting for SUVs and trucks. The country's national automotive safety regulator enforces design rules for frontal protection systems and pedestrian safety. Melbourne's industrial suburbs house fabrication facilities for tubular steel side steps serving domestic and Asia-Pacific export markets.
India
Mahindra and Tata commercial vehicle expansion creates first-mover positioning for bed liner and tonneau cover suppliers targeting emerging pickup adoption. BIS certification requirements govern automotive component quality and safety standards for domestic sale. Pune-Nashik automotive corridor attracts injection molders serving the utility vehicle aftermarket.
Exterior Car Accessories Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans multinational automotive suppliers with captive accessory divisions, regional manufacturing specialists with deep material expertise, and direct-to-consumer brands leveraging digital configuration platforms. Three strategic archetypes dominate: Nordic engineering-positioned cargo management specialists, North American truck aftermarket pure-plays, and diversified automotive component conglomerates with accessory portfolios. Competitive moves center on modular product bundling and in-house manufacturing scale expansion.
Among Nordic-origin specialists, Thule Group exemplifies the premium cargo management archetype through its engineering heritage positioning. Lund International occupies a position within the North American truck-focused specialist tier. WeatherTech anchors the direct-to-consumer manufacturing scale archetype with in-house production capabilities. These three represent distinct competitive vectors: geographic heritage branding, segment specialization depth, and vertical manufacturing control.
| Leading Market Players |
|---|
| Thule Group |
| Lund International |
| Covercraft Industries |
| WeatherTech |
| HELLA KGaA Hueck & Co. |
| Oakmore Pty Ltd |
| Car Mate MFG.CO., LTD. |
| Magna International |
| 3M |
| Others |
Supply Flow & Price Mechanics
Aluminum alloy feedstock from London Metal Exchange contracts cascades through stamped side-step manufacturers into three-tier pricing structures across premium, standard, and economy levels, with Gulf Coast ABS resin concentration forcing molders to absorb petrochemical volatility or pass through to aftermarket distributors serving price-sensitive DIY installers.
Pricing Analysis
Margin tightening in economy-tier bumper programs reflects ABS resin supply concentration along the US Gulf Coast and Northeast Asian petrochemical corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon fiber layup certification versus injection-molded polymer grades. Pricing pressure accelerates in metal-stamped categories as LME aluminum volatility compresses independent stamper margins. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity; overlanding enthusiasts and motorsport personalization segments accept premium positioning.
Supply Chain Analysis
Carbon fiber pre-preg supply rests on Japanese and US specialty composite producers with captive autoclave capacity, while injection-molded ABS draws from China and South Korean polymer compounders. Raw material dependencies span petrochemical feedstocks, aluminum alloy billet, and epoxy resin systems. Single-source vulnerability concentrates in skilled laminator labor pools across manufacturing regions. Distribution runs through OEM captive channels, aftermarket distributor networks, and direct-to-consumer configuration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA pedestrian-safety standards and ECE R58 rear-impact mandates erect compliance moats that favor incumbent suppliers with homologation infrastructure and testing capital, disadvantaging import-dependent competitors lacking certified guard and bumper programs.
For Market Incumbents: Extend homologation-tested product architectures into emerging EV platform geometries before battery thermal management zones solidify mounting standards. Defend position by capturing closed-loop polymer recovery capabilities under China's GB recyclability thresholds. Prioritize technician training pipelines for carbon fiber autoclave operations where labor scarcity constrains output expansion. For New Entrants and Emerging Players: The mid-tier price-point gap between Thule-engineered cargo systems and economy-channel clip-on alternatives offers white-space positioning for digitally native configurators. Target India's emerging pickup segment ahead of Mahindra and Tata bed liner supply maturation. Pursue additive manufacturing prototyping services for low-volume spoiler production serving German and Japanese specialty tuners. For Investors and Strategic Acquirers: ECE R78 brake-system compatibility testing timeline extensions are the leading indicator that homologation-capable suppliers will command scarcity premiums. Long-term viability favors vertically integrated manufacturers with in-house molding and stamping assets over import-dependent assemblers. Monitor MIIT GB standard enforcement intensity as signal for domestic Chinese supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Vehicle-Specific Digital Modeling Investment | 3D scanning and parametric CAD capabilities capture fragmented EV platform geometries ahead of competitor tooling cycles. |
| Closed-Loop Polymer Recovery Buildout | Captive ABS reprocessing infrastructure satisfies China MIIT recyclability mandates while insulating margin from virgin resin volatility. |
| Direct-to-Consumer Configurator Launch | Online rack and cargo system configurators reduce brick-and-mortar SKU proliferation while capturing buyer preference data. |
| Technician Training Pipeline Development | Autoclave operator and composite laminator certification programs address scarcity constraints limiting carbon fiber spoiler output expansion. |
| ECE R58 Homologation Pre-Certification | Pre-validated rear guard designs compress launch cycles for European commercial vehicle operators facing underrun protection mandates. |
Methodological Framework
Multi-period observation of vehicle registration patterns, aftermarket sales velocities, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributor operations heads, and composite manufacturing technicians. Secondary validation drew from NHTSA FMVSS documentation, ECE regulation transcripts, MIIT GB standard publications, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrix modeling connected raw material cost indices, manufacturing capacity utilization, and end-use demand drivers across product type, material, application, and installation method dimensions. CAGRs were derived from segmented growth trajectory analysis incorporating electrification adoption curves, overlanding participation rates, and regulatory phase-in schedules. Forecast inputs included OEM platform launch timelines and petrochemical feedstock price band assumptions.
Inputs from regulatory filing databases and industry trade associations were available through the study window; gaps in real-time composite technician labor pool sizing introduce uncertainty bands around carbon fiber segment output assumptions. Forecasts reflect documented scenario assumptions regarding EV platform standardization and regional trade policy stability. NHTSA ADAS recalibration guideline evolution, ECE R78 testing protocol revisions, and China GB enforcement intensity constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market