
 Global Air Spring Components Market | 2026-2036
Global Air Spring Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Spring Components Market Analysis
The EU Green Deal's commercial vehicle decarbonization targets is realigning procurement criteria across European freight operators. Continental AG leverages captive rubber compounding technology to sustain margin leadership in convoluted bellows manufacturing. Firestone Industrial Products anchors North American aftermarket distribution through certified dealer networks spanning Class 8 truck service bays. Guangzhou Guomat Air Spring competes on cost-adjusted rolling sleeve output for domestic bus OEMs in China's eastern manufacturing belt.
Air spring components are elastomeric bellows assemblies reinforced with textile cord layers and bead rings, pressurized with compressed air to provide variable-rate spring force for vehicle suspension isolation and height control. The rolling sleeve configuration dominates premium passenger car applications due to its lateral stability envelope and compact packaging geometry. Within application segmentation, rail transit systems represent the fastest-expanding demand pool as urban metro operators specify air suspension for vibration-sensitive track corridors. The automotive OEM channel occupies the deepest margin pool, where specification lock-in with platform engineering teams creates multi-year supply commitments.
The EPA enforces heavy-duty vehicle greenhouse gas Phase 2 standards that mandate aerodynamic and suspension efficiency improvements, directly shaping air spring specification thresholds for on-highway tractors. China's MIIT administers commercial vehicle fuel consumption limits that compel domestic manufacturers to adopt lightweight air suspension architectures. The EU's F-Gas Regulation restricts fluorinated greenhouse gas use in pneumatic systems, redirecting material selection toward natural rubber and thermoplastic elastomer compounds. Stakeholders must monitor evolving brake-to-spring integration standards as electromechanical chassis platforms redefine component interfaces across passenger and commercial vehicle architectures.
Market Dynamics
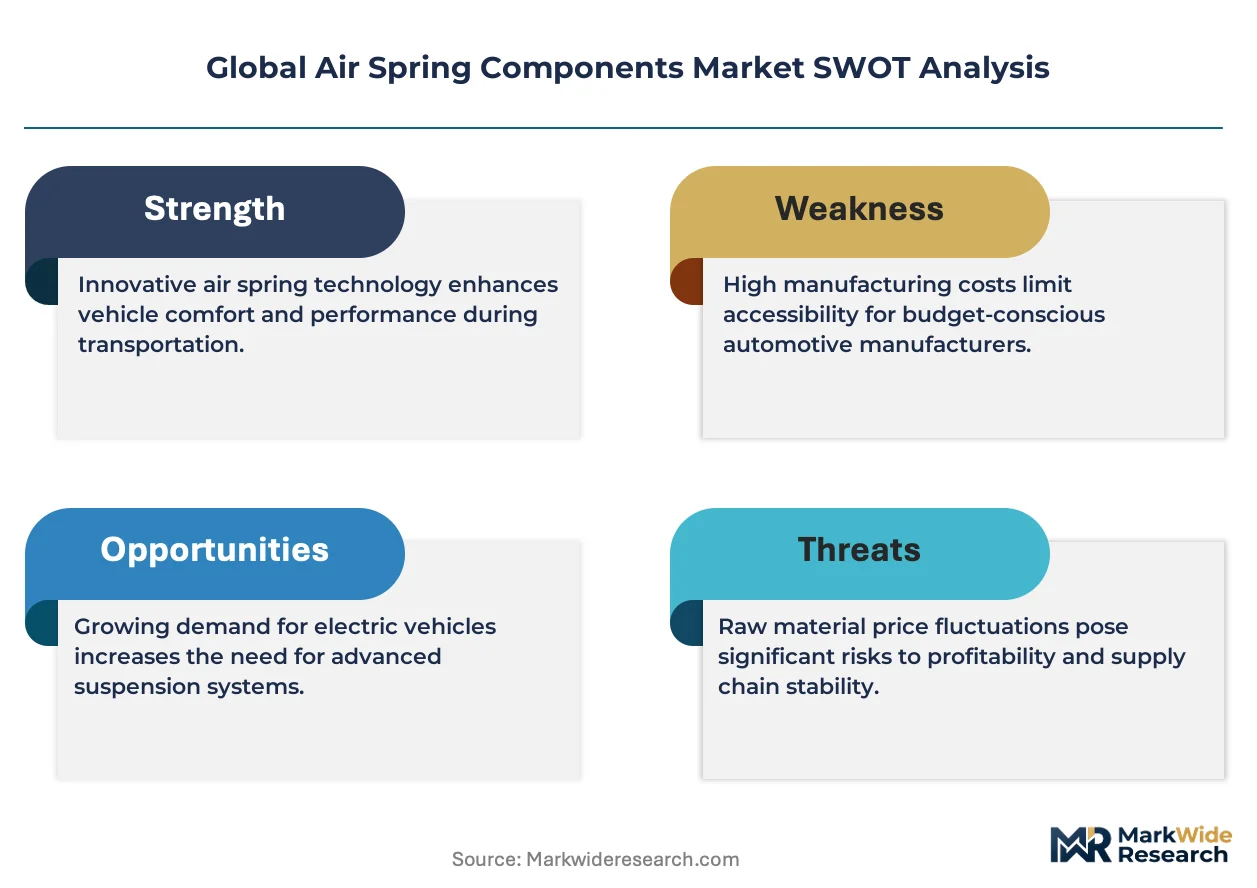
Electrification of commercial and passenger vehicle platforms is compressing suspension packaging envelopes and forcing air spring manufacturers to engineer lighter, thermally stable bellows configurations that integrate with battery-heavy chassis architectures.
Growth Catalysts
- EPA Phase 2 greenhouse gas standards:Mandates for aerodynamic and suspension efficiency improvements compel Class 8 truck operators to specify air spring systems for compliance.
- Rolling sleeve air springs:Rail transit operators in vibration-sensitive urban corridors are specifying this configuration for metro expansion projects across multiple continents.
- EU Green Deal commercial vehicle decarbonization:Freight operators are realigning procurement criteria toward low-emission suspension technologies.
Market Restraints
- Natural rubber price volatility:Raw material cost swings compress margin predictability for convoluted bellows producers.
- Supply concentration in East Asian textile cord:Reinforcement fabric sourcing clusters create geographic vulnerability for tier-two manufacturers.
- Fluorinated compound restrictions:The EU's F-Gas Regulation limits pneumatic sealing materials and redirects R&D toward thermoplastic elastomer alternatives.
Strategic Opportunities
- India's commercial vehicle fleet modernization:Bus and truck OEMs present underpenetrated demand for cost-optimized rolling sleeve architectures.
- Brake-to-spring electromechanical integration:Convergence of chassis control systems creates specification openings for smart air spring modules.
- Brazil's ANVISA medical transport regulations:Ambulance and patient transfer vehicle mandates are accelerating air suspension adoption for ride quality compliance.
Industry Challenges
- Multi-physics simulation expertise gap:Air spring OEMs struggle to recruit engineers capable of modeling coupled fluid-structure-thermal bellows behavior.
- ISO 9001/IATF 16949 certification timelines:Extended audit cycles delay supplier qualification for automotive platform engineering teams.
- Legacy mechanical suspension replacement protocols:Fleet maintenance departments face retraining burdens when retrofitting air spring systems onto existing vehicle architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Spring Components Market |
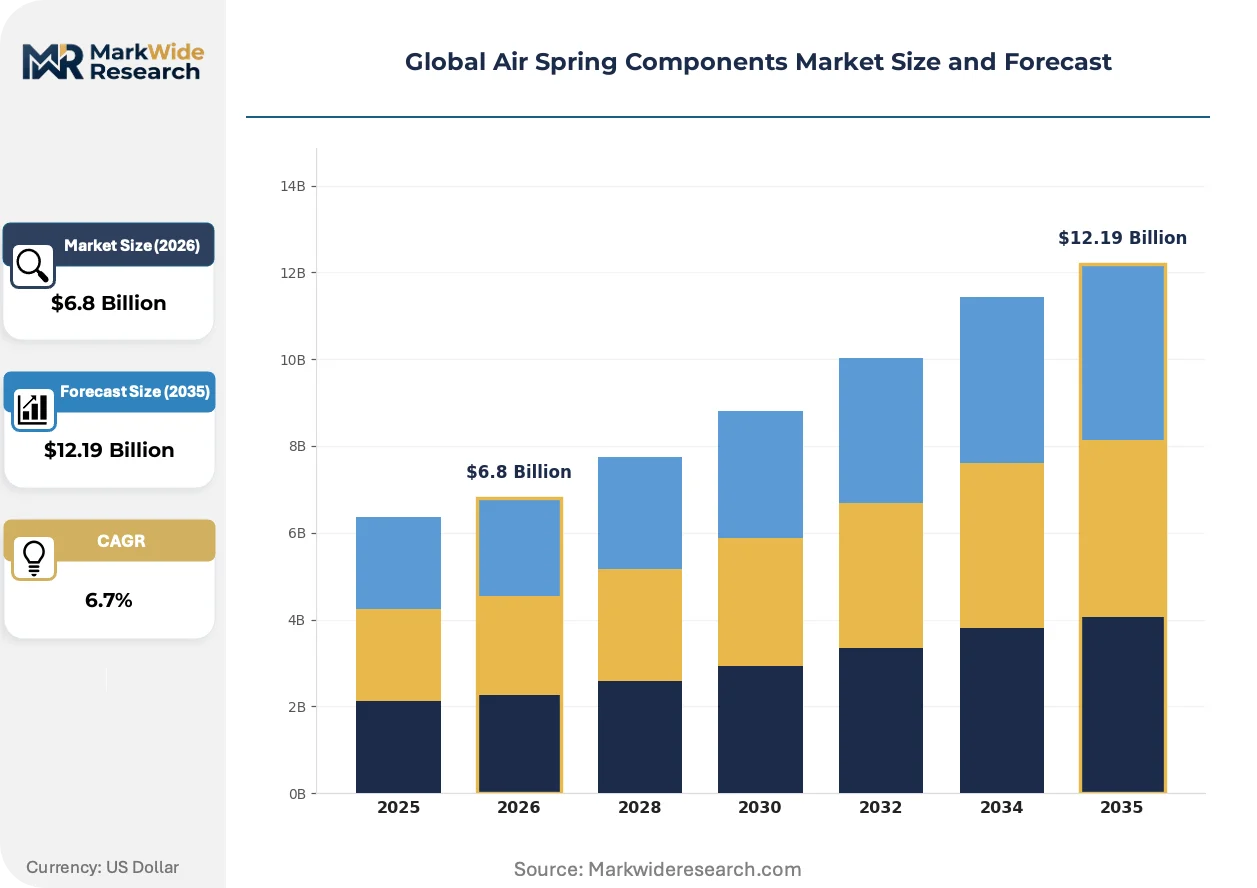
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convoluted, Double Convoluted, Rolling Sleeve, Other Application: Automotive, Aerospace, Rail, Industrial End User: OEMs, Aftermarket, Distribution, Repair Services Installation Type: On-road, Off-road, Heavy-duty, Light-duty |
| Companies Covered | Vibracoustic, Dunlop Systems and Components, Continental AG, STEMCO Products, BWI Group, Firestone Industrial Products, WABCO Holdings, Guangzhou Guomat Air Spring, Hendrickson USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Spring Components Market Emerging Trajectories
Material science advances and regulatory pressure on vehicle emissions are converging to reshape how air spring components are engineered, specified, and integrated across passenger and commercial platforms.
High-performance thermoplastic elastomer compounds are absorbing the thermal and chemical stresses that previously degraded natural rubber bellows in battery-electric vehicle applications. Premium passenger car OEMs in Germany and South Korea are specifying these materials for platform weight reduction targets. The shift is compressing traditional rubber compounding capacity and forcing suppliers to retool extrusion and molding lines.
The EU's F-Gas Regulation is restricting fluorinated greenhouse gas use in pneumatic actuation systems and redirecting material selection toward bio-based elastomers and advanced thermoplastics. Manufacturers serving the European market are reformulating bead ring adhesives and cord dip compounds to eliminate perfluorinated substances. Rail transit operators in France and Spain are now specifying F-Gas-compliant air suspension for new metro rolling stock procurements.
Fleet operators are consolidating supplier relationships and demanding lifecycle cost guarantees rather than unit-based pricing for air spring replacement programs. This behavioral shift is disintermediating traditional aftermarket distributors in North America and compressing margins for non-certified service providers. Long-haul trucking fleets in the US and Canada are piloting subscription-based suspension maintenance models that bundle component supply with predictive replacement scheduling.
Global Air Spring Components Market Segmentation
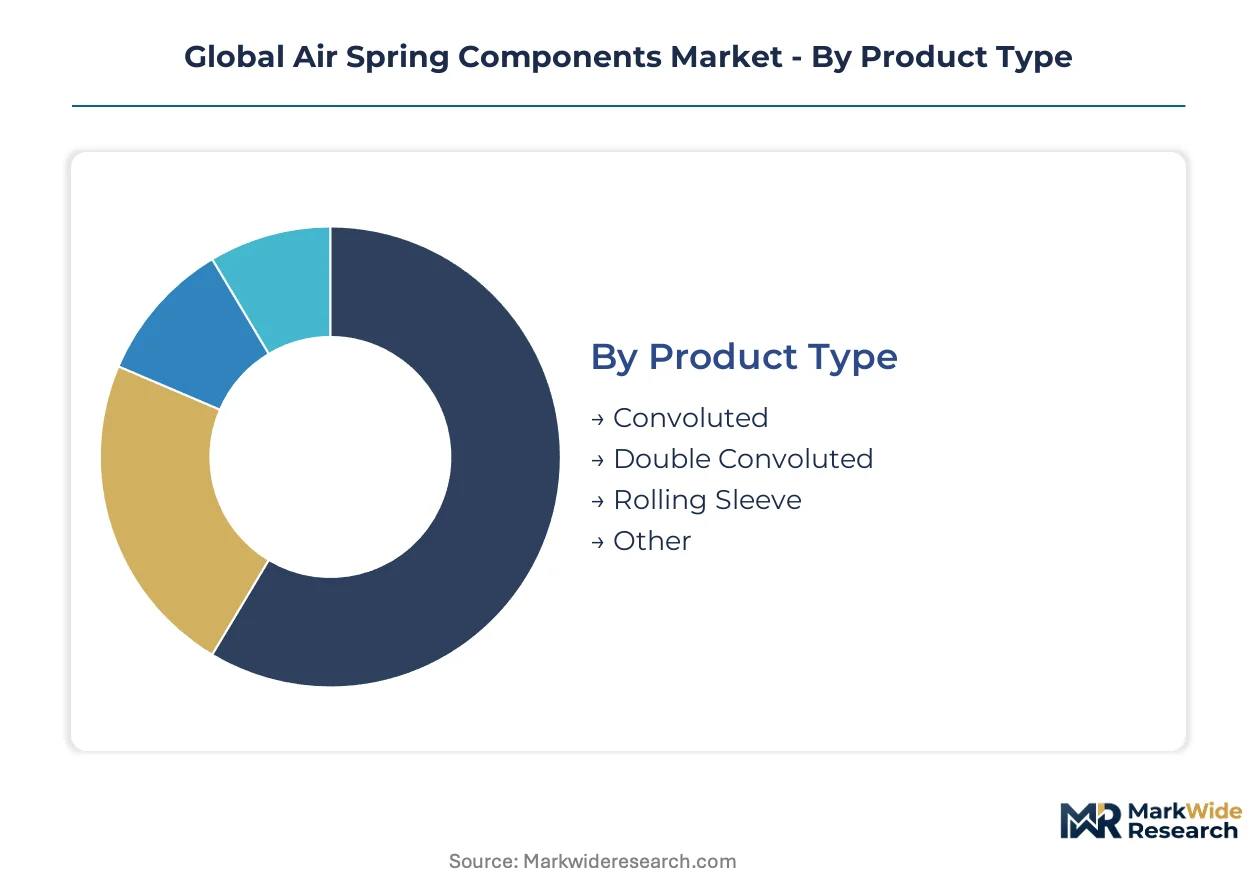
Air spring component specifications diverge sharply based on whether they serve as standalone suspension modules or integrate into broader chassis control architectures. Product configuration, application environment, and channel economics each reshape procurement criteria and margin structures across the value chain.
Product Type:
Standalone bellows assemblies dominate replacement channels, while embedded rolling sleeve configurations integrate directly into OEM platform engineering.
- Convoluted:These multi-ply elastomer bellows with crimped bead rings deliver high load capacity for commercial vehicle axles. Demand clusters in Germany's heavy-duty truck manufacturing corridor, where OEMs specify convoluted architectures for durability under sustained highway loading.
- Double Convoluted:Stacked dual-chamber designs provide progressive spring rates for vibration-sensitive applications. Rail transit operators in France and Spain are specifying this configuration for metro rolling stock procurements subject to F-Gas Regulation compliance deadlines.
- Rolling Sleeve:Compact cylindrical designs with bonded fabric reinforcement suit premium passenger car packaging constraints. South Korean electric vehicle platforms are absorbing expanded rolling sleeve volumes for battery-heavy chassis weight distribution.
- Other:Hybrid configurations and specialty bellows for aerospace landing gear and medical transport applications.
Volume placements concentrate in Convoluted configurations; the faster expansion belongs to Rolling Sleeve as electrification compresses suspension envelopes.
Application:
Cost tier segmentation separates commodity replacement demand from specification-locked OEM platform supply.
- Automotive:Passenger car and commercial vehicle suspension systems represent the deepest specification engagement with platform engineering teams. China's MIIT fuel consumption mandates are accelerating domestic production of lightweight air spring architectures for bus and truck OEMs.
- Rail:Metro and intercity rolling stock operators specify air suspension for vibration attenuation in sensitive track corridors. Urban transit authorities in Brazil are expanding procurement for ride quality compliance under ANVISA medical transport regulations.
- Aerospace:Landing gear isolation and cabin pressure systems require certified elastomer compounds meeting FAA and EASA material standards.
- Industrial:Vibration isolation for manufacturing equipment and material handling systems operates on shorter replacement cycles with less specification lock-in.
Revenue concentration sits with Automotive; Rail is climbing the fastest as urban metro expansion accelerates across multiple continents.
End User:
Customer type determines pricing architecture and relationship duration, from multi-year platform commitments to transactional replacement purchases.
- OEMs:Original equipment manufacturers command specification authority and multi-year supply agreements tied to vehicle platform lifecycles. North American Class 8 truck producers are embedding air spring suppliers into EPA Phase 2 compliance engineering.
- Aftermarket:Independent distributors and dealer networks serve fleet maintenance departments with replacement inventory. Consolidating procurement patterns among US long-haul operators are compressing margins for non-certified service providers.
- Distribution:Tier-two wholesalers buffer inventory between manufacturers and end-service points, absorbing working capital requirements.
- Repair Services:Direct-to-bay installation providers face retraining burdens when retrofitting air systems onto legacy mechanical suspension architectures.
Margin depth pools with OEMs; Aftermarket channels are gaining share fastest as fleet operators consolidate supplier relationships.
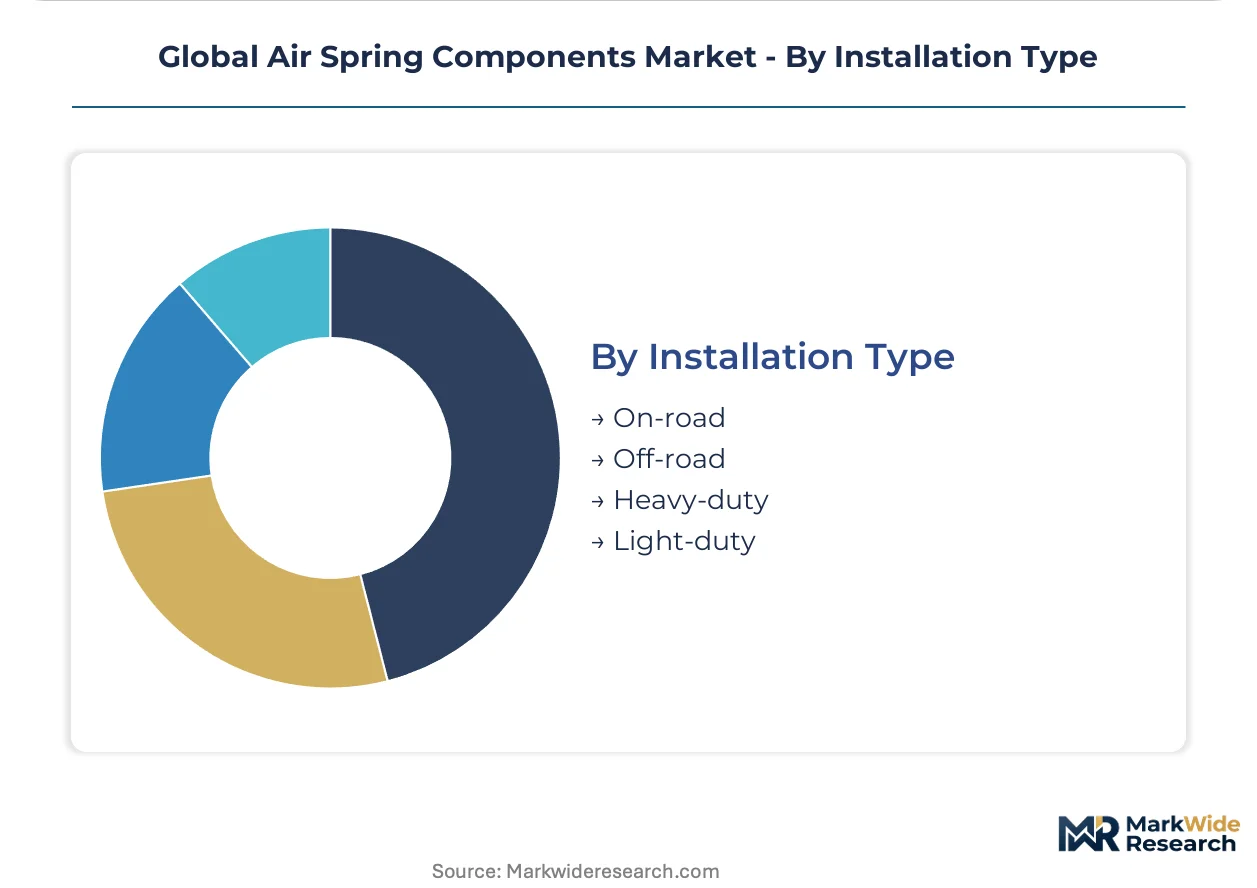
Installation Type:
Operating environment severity dictates material specification and replacement frequency, separating highway-optimized from terrain-resistant designs.
- On-road:Highway-optimized bellows prioritize aerodynamic efficiency and thermal stability under sustained speed operation. German premium automotive OEMs are specifying on-road configurations for luxury electric vehicle platforms.
- Off-road:Abrasion-resistant compounds and reinforced cord layers withstand debris impact and irregular loading. Mining and construction equipment operators in Australia and Canada are absorbing expanded off-road specification volumes.
- Heavy-duty:High-load architectures for Class 8 tractors and multi-axle trailers integrate with brake systems and height control modules. India's commercial vehicle fleet modernization is opening underpenetrated demand for cost-optimized heavy-duty rolling sleeve designs.
- Light-duty:Compact packaging for passenger cars and light commercial vehicles emphasizes ride quality and NVH performance over absolute durability.
Specification activity concentrates in Heavy-duty; Light-duty applications are expanding most quickly as electrification reshapes passenger car chassis packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global air spring engineering density, hosting platform specification teams from Mercedes-Benz and Porsche that embed suppliers into multi-year electric vehicle chassis programs.
United States
Class 8 truck manufacturers in Michigan and Ohio are absorbing expanded air spring volumes to meet EPA Phase 2 greenhouse gas compliance deadlines. The EPA mandates aerodynamic and suspension efficiency thresholds that reshape procurement criteria for on-highway tractors. Detroit's automotive engineering corridor concentrates specification authority with platform engineering teams.
Germany
Premium passenger car OEMs in Bavaria and Baden-Württemberg specify rolling sleeve configurations for luxury electric vehicle platforms. The EU Green Deal's commercial vehicle decarbonization targets redirect freight operator procurement toward low-emission suspension technologies. Stuttgart's manufacturing belt hosts captive rubber compounding operations serving convoluted bellows production.
China
Domestic bus and truck OEMs in Shanghai and Guangdong provinces are scaling rolling sleeve output to satisfy MIIT fuel consumption mandates. MIIT-administered commercial vehicle limits compel lightweight air suspension adoption across eastern manufacturing belts. Guangzhou's component cluster supplies cost-optimized architectures for domestic fleet modernization.
South Korea
Battery-electric vehicle platforms from Hyundai and Kia are compressing suspension packaging envelopes and specifying thermally stable bellows configurations. METI-aligned industrial policy supports automotive supplier qualification for platform engineering integration. Seoul's capital region concentrates R&D activity for electromechanical chassis control convergence.
Brazil
Urban transit authorities in São Paulo and Rio de Janeiro are expanding air suspension procurement for metro rolling stock under ANVISA medical transport regulations. ANVISA mandates accelerate adoption for ambulance and patient transfer vehicle ride quality compliance. The southeastern industrial corridor hosts assembly operations serving Latin American aftermarket channels.
Global Air Spring Components Market Vendor Landscape
The competitive structure tilts toward integrated tier-one suppliers with captive material capabilities and long-cycle platform relationships. Convoluted bellows manufacturing demands specialized rubber compounding expertise that filters the vendor base toward vertically capable participants. Two archetypes dominate: German-Japanese precision engineering houses with OEM specification lock-in, and Chinese cost-optimized fabricators serving domestic fleet replacement cycles. Capacity expansion and backward integration into textile cord supply represent the dominant competitive vectors.
Among German engineering houses, Continental AG exemplifies the premium-tier archetype through captive rubber technology and platform specification authority. Firestone Industrial Products anchors North American aftermarket distribution through certified dealer network relationships. Guangzhou Guomat Air Spring occupies the cost-optimized fabrication tier, serving domestic bus OEMs with rolling sleeve output calibrated to MIIT compliance requirements.
| Leading Market Players |
|---|
| Vibracoustic |
| Dunlop Systems and Components |
| Continental AG |
| STEMCO Products |
| BWI Group |
| Firestone Industrial Products |
| WABCO Holdings |
| Guangzhou Guomat Air Spring |
| Hendrickson USA |
| Others |
Supply Flow & Price Mechanics
Rubber compounding engineers in Stuttgart's manufacturing belt command wage premiums that compress margin spreads between premium and economy-tier air spring producers. Labor-cost differentials between German captive facilities and Chinese rolling sleeve fabricators sustain a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Lifecycle cost guarantees anchor pricing models as fleet operators shift from unit-based transactions to subscription maintenance contracts. Price differentiation hinges on ISO 9001/IATF 16949 certification tier and captive textile cord compounding capability. Cost compression in aftermarket channels is intensifying because consolidated US long-haul operators are bypassing non-certified distributors. Bus OEMs in China's eastern manufacturing belt exhibit highest price sensitivity; German luxury electric vehicle platform teams show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Direct-to-OEM channels handle platform engineering integration for German and South Korean automotive manufacturers. Raw material sourcing draws from Thailand and Indonesia for natural rubber, China and Taiwan for textile cord reinforcement, and Germany for specialty elastomer compounds. Single-source vulnerability concentrates in East Asian bead ring adhesive suppliers serving F-Gas Regulation-compliant formulations. Distribution runs through certified dealer networks for North American Class 8 truck aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over rubber compounding and textile cord supply determines margin sustainability. Players are pursuing backward integration into reinforcement fabric manufacturing to defend specification authority.
For Market Incumbents: Hedge against thermoplastic elastomer displacement by securing multi-year platform commitments with South Korean battery-electric vehicle OEMs. Deepen captive rubber technology investments in Stuttgart's manufacturing corridor to sustain convoluted bellows margin leadership against Chinese cost-optimized competitors. Prioritize IATF 16949 certification maintenance to preserve automotive OEM channel access. For New Entrants and Emerging Players: Launch via certified dealer network partnerships serving India's commercial vehicle fleet modernization. Target cost-optimized rolling sleeve architectures for domestic bus OEMs in China's eastern manufacturing belt. Pursue brake-to-spring electromechanical integration modules as the most penetrable specification opening in next-generation chassis platforms. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier fabricators possessing IATF certification gaps but strong regional OEM relationships, given accelerating EPA Phase 2 compliance deadlines in North America. Long-term viability favors suppliers with demonstrated multi-physics simulation expertise and platform engineering integration track records. Monitor F-Gas Regulation enforcement intensity in France and Spain as the signal indicating thermoplastic elastomer substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Textile Cord | Captive reinforcement supply insulates margin from East Asian sourcing concentration risks. |
| Thermoplastic Elastomer Formulation | F-Gas Regulation compliance in EU rail procurements redirects material R&D investment. |
| Platform Engineering Integration | Multi-year supply commitments with German OEMs lock out non-certified competitors. |
| Subscription Maintenance Models | US long-haul fleet consolidation creates recurring revenue pools for certified providers. |
| Multi-Physics Simulation Capability | Fluid-structure-thermal modeling expertise scarcity filters vendor base toward integrated houses. |
Methodological Framework
Document review covered customs trade data, MIIT fuel consumption filings, EPA regulatory dockets, and vehicle production databases, complemented by interviews with OEM platform engineers, aftermarket distributor operations heads, rubber compounding technical directors, and fleet procurement managers. Secondary validation drew from SEC 10-K filings, IHS Markit registration data, and industry association technical standards. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Segment-level outputs across the projection horizon reflect product configuration, application environment, end-user channel, and installation severity dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA Phase 2 compliance timelines, MIIT mandate enforcement, and EU Green Deal procurement realignment. Industry-specific inputs included platform engineering cycle lengths, IATF certification audit timelines, and natural rubber futures price volatility indices.
Regulatory enforcement delays, raw material supply disruptions, and electromechanical chassis convergence velocity are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions regarding specification lock-in durability and certification barrier maintenance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Navigation Light Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Global Undercarriage Components Market