
 Gas-Powered Chainsaw Market | 2026-2036
Gas-Powered Chainsaw Market Size, Share, and Industry Trends Forecast 2026-2036
Gas-Powered Chainsaw Market Analysis
Professional forestry and land-clearing contractors are repositioning their equipment procurement toward higher-displacement gas chainsaws as commercial logging cycles intensify in temperate hardwood zones. Husqvarna AB leverages its Nordic manufacturing heritage to dominate professional-grade distribution across Scandinavia and Central Europe. ANDREAS STIHL AG and Co. KG anchors its competitive stance through deep dealer networks and captive engine production. Makita Corp. competes on compact professional chassis designs that reduce operator fatigue during extended felling operations.
A gas-powered chainsaw is a portable, internal-combustion-driven cutting tool utilizing a two-stroke engine typically displacing 30 to 120 cubic centimeters, driving a looped cutting chain around a guide bar at speeds exceeding 20 meters per second for severing timber and woody biomass. Engine capacity segmentation stratifies around medium-displacement units, which capture the bulk of contractor demand for mixed hardwood and softwood duty cycles, while extra-high-capacity models concentrate margin pools in industrial clear-cutting and emergency storm-response applications. Use case segmentation shows land clearing and tree felling commanding the largest volume share, with pruning applications representing a specialized niche where lighter chassis configurations sustain premium positioning.
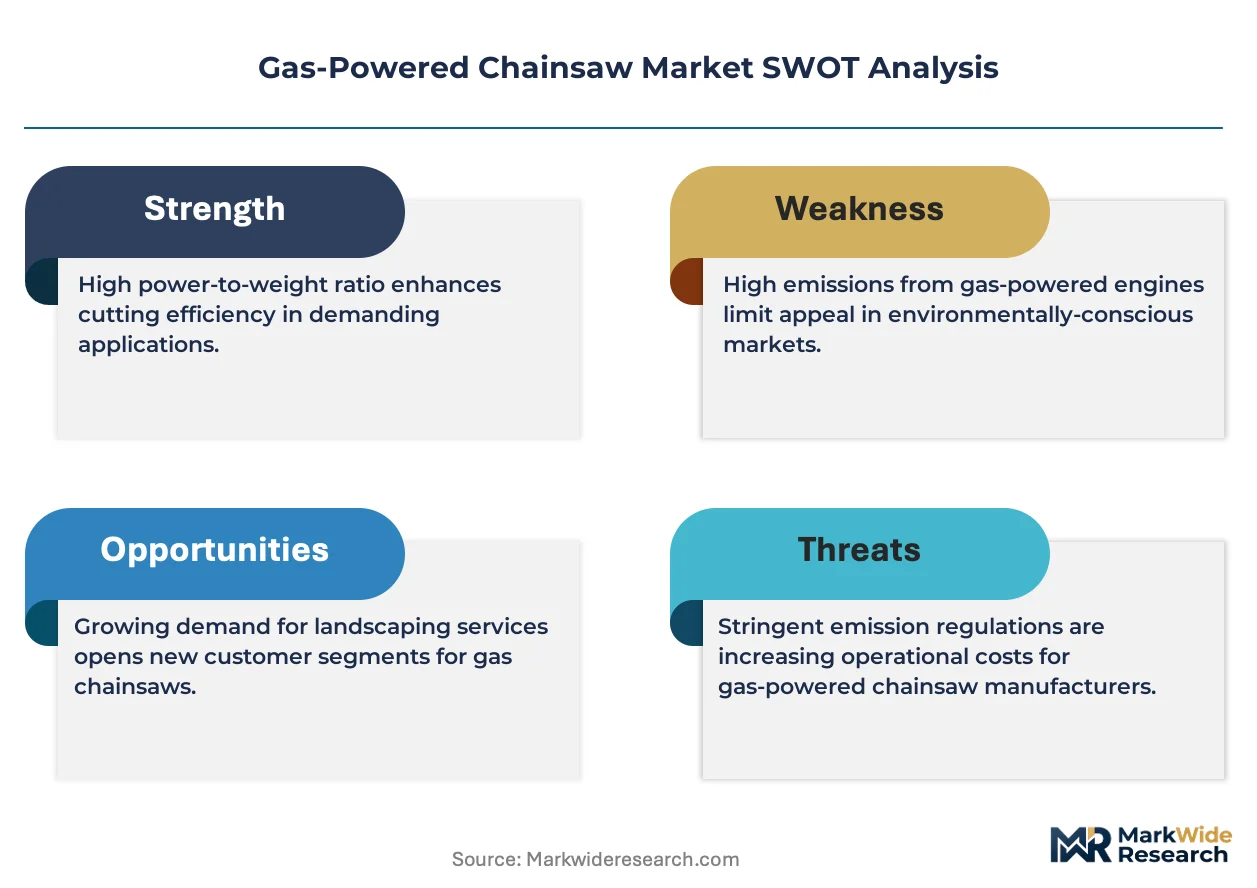
EPA emission standards in the United States and EU F-Gas Regulation alongside machinery noise directives in Europe constrain two-stroke engine architecture and exhaust after-treatment design, compelling manufacturers to invest in catalytic converter integration and precision fuel injection. OSHA logging safety standards and corresponding EU machinery directives further shape operator protection equipment bundling and chain brake response thresholds. Stakeholders must monitor regulatory convergence between North American and European exhaust protocols, as divergence would fragment engine platform development and inflate compliance costs across export-dependent supply chains.
Market Dynamics
Professional logging contractors are consolidating equipment procurement around higher-displacement two-stroke platforms as EU F-Gas Regulation and machinery noise directives tighten exhaust and acoustic performance thresholds across European forestry operations.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Emissions compliance deadlines are accelerating replacement cycles among German and Scandinavian logging contractors operating aging equipment fleets.
- Storm Response Infrastructure:Municipal emergency services in temperate hardwood zones are expanding dedicated arborist units for climate-intensified windfall clearance.
- Precision Fuel Injection:Electronic carburetion systems are reducing fuel consumption rates and extending duty cycles for remote felling operations without refueling logistics.
Market Restraints
- Platinum Group Metal Volatility:Catalytic converter substrate costs fluctuate with palladium and rhodium spot markets, compressing margin on emission-compliant models.
- Two-Stroke Engine Architecture Limits:Thermal efficiency ceilings near 20 percent constrain power-to-weight improvements without displacing proven crankcase-scavenging designs.
- Battery-Electric Substitution:Lithium-ion chainsaw platforms are capturing pruning and light-duty felling applications below 40cc equivalent displacement.
Strategic Opportunities
- Central European Dealer Network Gaps:Professional-grade distribution remains underdeveloped in Poland and Czech Republic relative to contractor density.
- Integrated Exhaust After-Treatment:Compact catalytic converter modules paired with acoustic damping chambers address dual compliance without chassis redesign.
- Rental Fleet Penetration:Short-term equipment leasing is displacing ownership models among seasonal land-clearing contractors in France and Italy.
Industry Challenges
- Certified Technician Scarcity:EFI diagnostics and catalytic converter servicing require training pipelines that dealer networks have not scaled.
- Homologation Timeline Compression:Concurrent EPA and EU exhaust protocol revisions are forcing parallel certification tracks that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas-Powered Chainsaw Market |
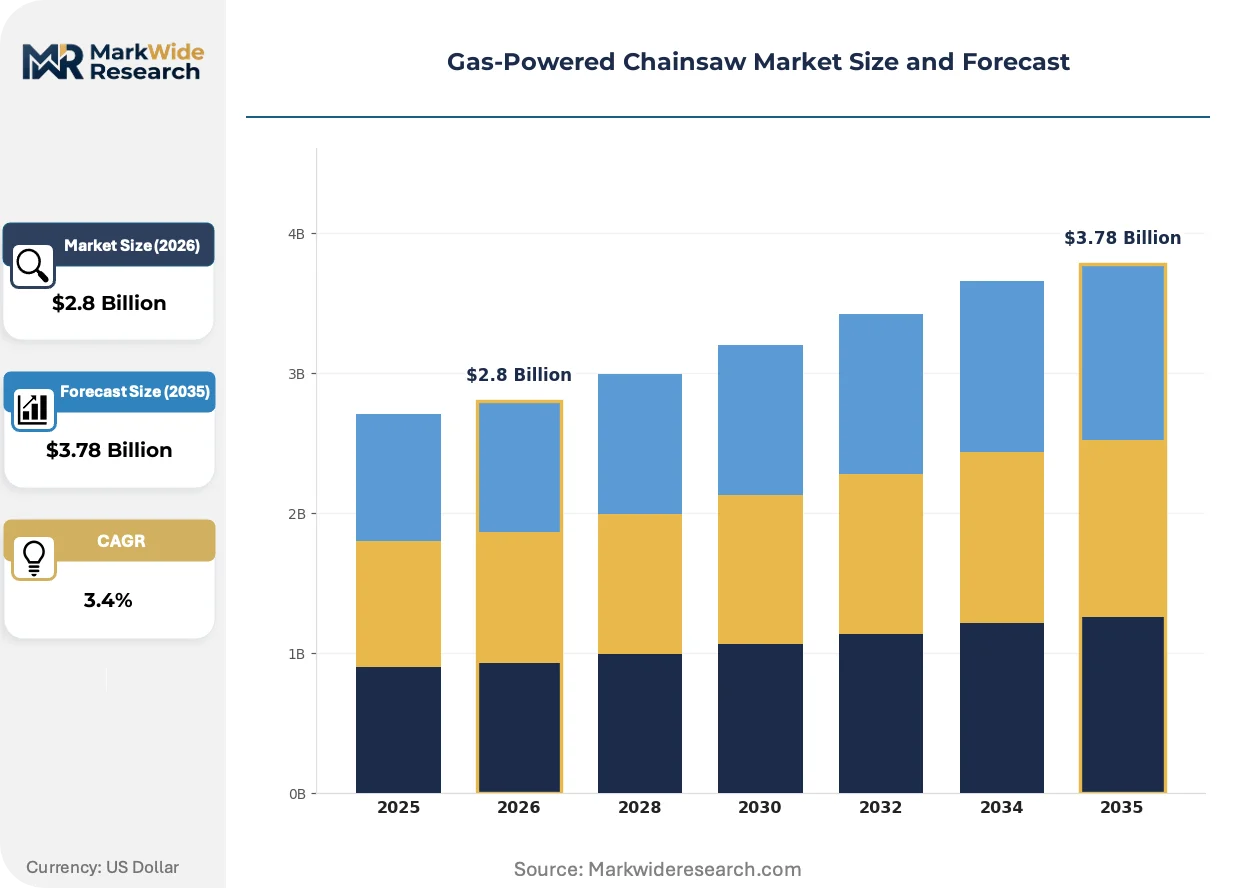
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Residential, Urban, Wilderness Engine Capacity: Low, Medium, High, Extra High Use Case: Tree Felling, Pruning, Land Clearing, Firewood Cutting End User: Contractors, Landscapers, Forestry Professionals, Homeowners |
| Companies Covered | Husqvarna AB, ANDREAS STIHL AG and Co. KG, Makita Corp., Robert Bosch GmbH, Briggs and Stratton Corp., Yamabiko Corp., Techtronic Industries Co. Ltd., Einhell Germany AG, The Toro Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas-Powered Chainsaw Market Emerging Trajectories
Powertrain engineering is pivoting toward emission-compliant architectures while distribution models fragment between traditional dealer networks and equipment rental platforms serving seasonal contractors.
Electronic fuel injection is expanding into professional-grade two-stroke platforms as a direct replacement for diaphragm carburetors in 50cc and above displacement classes. German and Austrian logging contractors are specifying EFI-equipped units for high-altitude felling operations where air density variations degrade conventional fuel metering. This technology is expanding into price tiers previously served by mechanical induction systems, compressing the premium positioning of legacy carbureted models.
EU machinery noise directives are mandating acoustic power level reductions below 100 dB(A) for handheld forestry equipment operated in residential interface zones. Manufacturers are integrating resonant chamber mufflers and composite chain brake covers that attenuate high-frequency mechanical noise without adding chassis mass. Professional arborist segments in Benelux and northern France are prioritizing compliant models for urban tree surgery contracts where municipal procurement specifications enforce strict acoustic thresholds.
Contractor purchasing behavior is fragmenting between capital-intensive fleet ownership and short-term rental arrangements for storm-response and seasonal clearing contracts. Equipment rental platforms in France and Italy are unbundling maintenance and insurance from daily rates, attracting small-scale land-clearing operators who lack dedicated service infrastructure. This shift concentrates in Mediterranean climates where fire prevention clearing creates concentrated but irregular demand spikes that ownership economics cannot justify.
Gas-Powered Chainsaw Market Segmentation
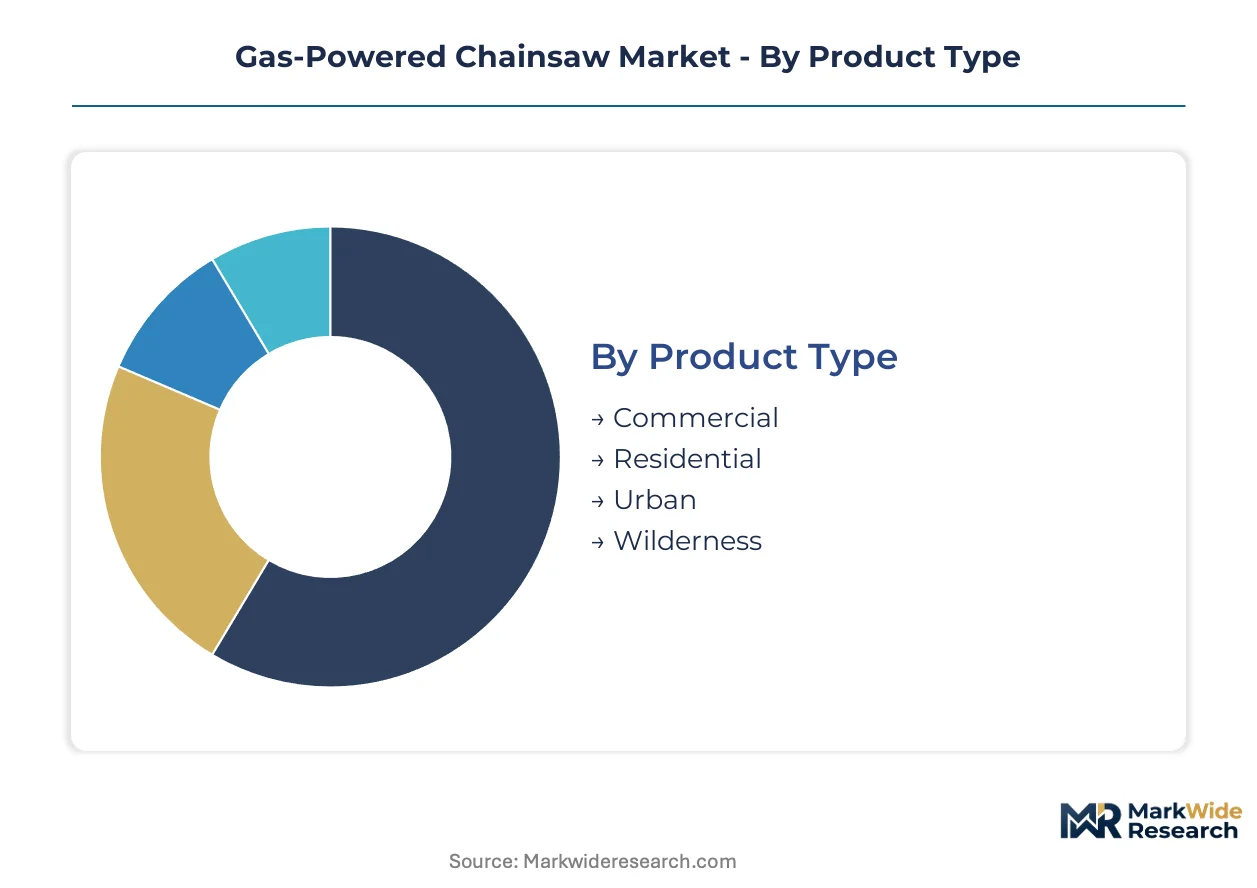
Equipment segmentation in the gas-powered chainsaw market reflects divergent duty cycles, operator skill levels, and regulatory exposure across professional and consumer tiers. Manufacturers configure engine displacement, chassis weight, and exhaust after-treatment specifications to match distinct procurement criteria between municipal contractors and seasonal homeowners.
Product Type:
Buyers differentiate by operational intensity and regulatory compliance requirements rather than price sensitivity alone.
- Commercial:Heavy-duty two-stroke platforms displace 50cc to 120cc for sustained felling operations. German logging contractors specify these units for dense hardwood duty cycles where EPA and EU F-Gas Regulation exhaust thresholds mandate catalytic converter integration.
- Residential:Compact chassis designs prioritize ergonomic handling and reduced vibration for intermittent firewood cutting. Demand clusters in rural North American markets where seasonal homeowners prioritize storage footprint and cold-start reliability over displacement.
- Urban:Acoustic-dampened configurations with resonant chamber mufflers address EU machinery noise directives below 100 dB(A). Municipal arborist contracts in Benelux and northern France specify these models for residential interface zones.
- Wilderness:Lightweight magnesium crankcases and simplified field-serviceable ignition systems serve remote backcountry operations. Forest fire suppression crews in western US jurisdictions prioritize these specifications for helicopter-portable rapid response.
Commercial equipment leads volumes today; Urban configurations are gaining share fastest.
Engine Capacity:
Displacement tiers align with timber density and duty cycle duration rather than operator preference.
- Low:Units below 35cc serve pruning and light limbing with reduced fuel consumption. Scandinavian landscaping contractors deploy these for maintenance contracts on ornamental hardwoods where maneuverability outweighs cutting speed.
- Medium:The 35cc to 55cc bracket dominates mixed hardwood-softwood operations. Polish and Czech Republic contractor fleets concentrate procurement here as replacement cycles accelerate under tightening EU emissions deadlines.
- High:55cc to 80cc platforms address storm-response and land-clearing contracts requiring sustained power output. French rental platforms stock these heavily for fire prevention clearing spikes.
- Extra High:Displacement exceeding 80cc targets industrial clear-cutting and emergency windfall clearance. Margin pools concentrate here despite limited unit volumes, as catalytic converter and precision fuel injection costs distribute across larger engine platforms.
Medium displacement anchors procurement volumes; Extra High configurations command the steepest expansion trajectory.
Use Case:
Application segmentation tracks seasonal demand patterns and equipment utilization rates.
- Tree Felling:Professional-grade platforms with rapid chain brake response and heated handles for cold-climate operations. German forestry professionals specify these for commercial logging cycles in temperate hardwood zones.
- Pruning:Top-handle and pole-saw configurations prioritize operator balance at height. Italian municipal arborists drive specification for low-vibration models in urban canopy management contracts.
- Land Clearing:High-displacement units with reinforced guide bars for embedded debris and rocky soil conditions. Seasonal contractors in Mediterranean climates favor rental arrangements for irregular demand spikes.
- Firewood Cutting:Economy-tier carbureted models serve intermittent residential use with minimal maintenance infrastructure. Austrian and Swiss alpine homeowners sustain demand for cold-start optimized ignition systems.
Tree Felling generates the largest revenue pool; Land Clearing is climbing the fastest as climate-intensified storm damage accelerates replacement cycles.
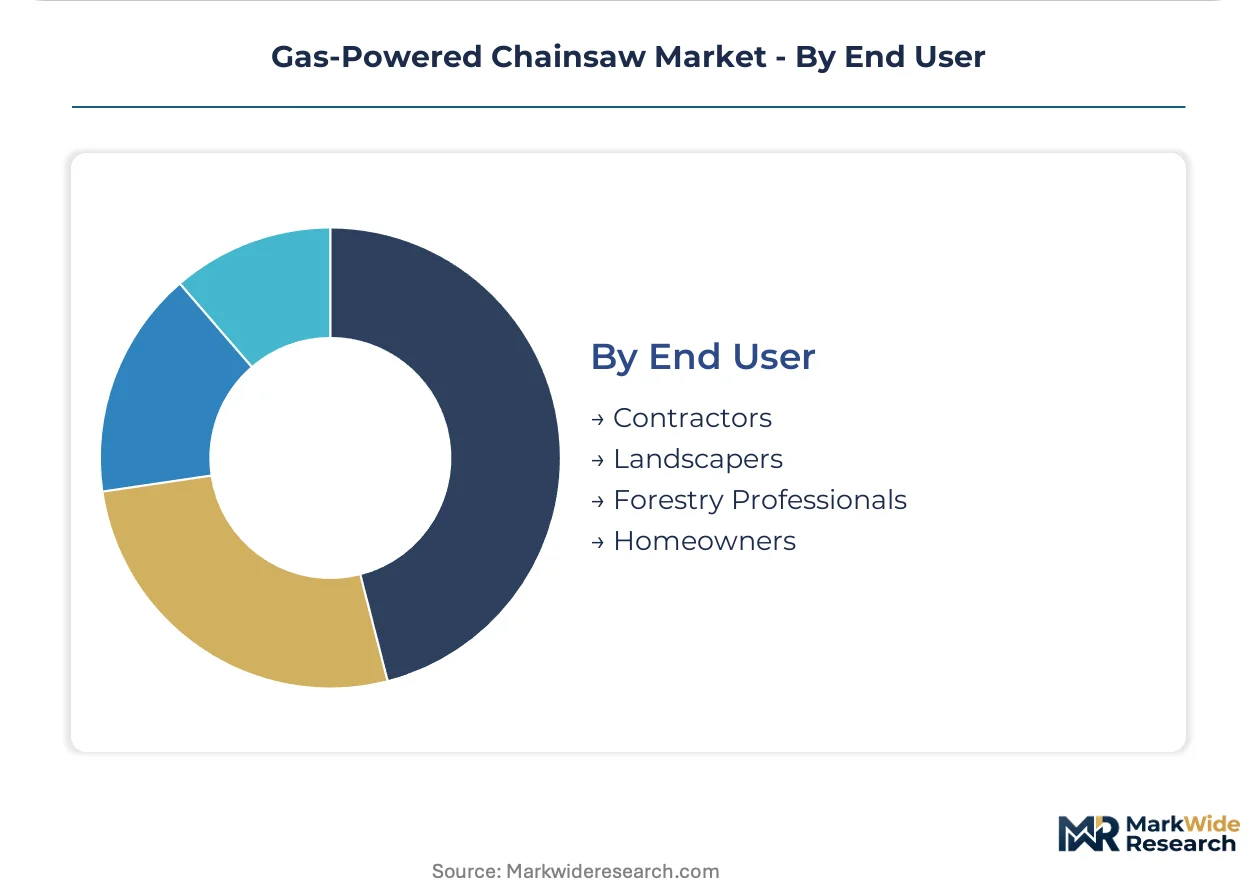
End User:
Procurement authority and technical sophistication determine specification complexity and service bundling requirements.
- Contractors:Fleet purchasers negotiating volume discounts and captive maintenance agreements. Scandinavian logging contractors consolidate around EFI-equipped platforms for high-altitude fuel metering precision.
- Landscapers:Mixed professional-consumer tier requiring versatility across pruning and light felling. Czech and Polish dealer networks report growing specification for acoustic-compliant models as urban interface work expands.
- Forestry Professionals:Certified operators with dedicated service infrastructure and homologation expertise. German contractors drive adoption of integrated exhaust after-treatment modules addressing concurrent EPA and EU protocol revisions.
- Homeowners:Price-sensitive intermittent users prioritizing storage and starting reliability over displacement. North American big-box retail channels concentrate volume here with minimal dealer service attachment.
Forestry Professionals anchor premium positioning; Landscapers are expanding specification fastest as urban green infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German forestry equipment clusters around Stuttgart and Bavaria anchor professional-grade demand as EU F-Gas Regulation deadlines accelerate replacement procurement across temperate hardwood zones.
Germany
Professional logging contractors in Baden-Württemberg and Bavaria are consolidating fleet procurement around EFI-equipped platforms for dense hardwood operations. The EU F-Gas Regulation phase-down mandates catalytic converter integration on all new professional equipment. Stuttgart-based distribution networks report strongest specification for 55cc to 80cc displacement tiers as municipal storm-response contracts expand.
United States
Western US fire suppression agencies are expanding helicopter-portable rapid-response inventories with lightweight magnesium crankcase designs. EPA emission standards constrain two-stroke exhaust architecture and drive catalytic converter adoption. Pacific Northwest contractor clusters around Portland and Seattle prioritize field-serviceable ignition systems for remote backcountry access.
France
Mediterranean fire prevention clearing creates concentrated demand spikes that rental platforms in Provence-Alpes-Côte d'Azur and Occitanie are capturing through unbundled maintenance contracts. EU machinery noise directives below 100 dB(A) shape municipal arborist procurement in Paris and Lyon metropolitan zones. Northern France urban tree surgery contractors specify acoustic-dampened configurations for residential interface work.
Sweden
Scandinavian logging contractors are specifying EFI platforms for high-altitude felling where air density degrades conventional fuel metering. Nordic manufacturing heritage supports professional-grade distribution density around Stockholm and Gothenburg. The country's national forestry regulator enforces strict exhaust compliance timelines that compress replacement cycles.
Poland
Contractor fleet density in Masovian and Silesian Voivodeships exceeds professional-grade distribution network coverage, creating procurement friction for medium-displacement units. Polish dealers report accelerating specification for acoustic-compliant models as urban green infrastructure investment expands. EU emissions deadlines are forcing parallel certification tracks that strain regional engineering bandwidth.
Gas-Powered Chainsaw Market Vendor Landscape
Dealer network consolidation dominates the current landscape as manufacturers defend professional-grade channel control against rental platform encroachment. The vendor base separates into three tiers: Nordic heritage specialists with captive engine production, Japanese precision-tool conglomerates competing on chassis ergonomics, and diversified industrial equipment portfolios with backward integration into powertrain components. Strategic moves concentrate on geographic distribution gaps and integrated exhaust after-treatment development.
Among Nordic heritage specialists, Husqvarna AB and ANDREAS STIHL AG and Co. KG exemplify the dealer-anchored archetype with deep professional-grade penetration across Central European forestry clusters. Makita Corp. occupies a position within the precision-tool tier, competing through compact chassis configurations that reduce operator fatigue during extended felling cycles. These three manufacturers represent divergent responses to emission compliance pressure: captive engine production, integrated exhaust modules, and ergonomic differentiation respectively.
| Leading Market Players |
|---|
| Husqvarna AB |
| ANDREAS STIHL AG and Co. KG |
| Makita Corp. |
| Robert Bosch GmbH |
| Briggs and Stratton Corp. |
| Yamabiko Corp. |
| Techtronic Industries Co. Ltd. |
| Einhell Germany AG |
| The Toro Co. |
| Others |
Supply Flow & Price Mechanics
Palladium and rhodium spot volatility in catalytic converter substrates cascades through professional-grade chassis pricing, compressing margins on EU F-Gas Regulation-compliant models while German logging contractors absorb premiums for EFI-equipped platforms.
Pricing Analysis
Distributor margin layers stratify around captive service bundling, with dealer-anchored networks in Scandinavia and Central Europe commanding 15-20 point markups on integrated exhaust after-treatment modules. Three-tier pricing structure across premium, standard, and economy levels separates EFI-equipped professional units from carbureted legacy models and entry-tier residential configurations. Pricing pressure stems from platinum group metal cost volatility in catalytic converter substrates, forcing manufacturers to unbundle after-sales service contracts. Residential homeowners in North American big-box channels exhibit highest price sensitivity; German forestry professionals show lowest sensitivity due to fleet-scale procurement and regulatory compliance mandates.
Supply Chain Analysis
Refurbishment flows for medium-displacement rental fleet units in France and Italy create secondary parts demand that feeds back into OEM service parts pricing. Manufacturing concentration centers on Sweden, Germany, and Japan for professional-grade engine platforms, with magnesium crankcase forging and precision fuel injection componentry drawing from Austrian and Swiss precision machining suppliers. Single-source vulnerability sits with palladium and rhodium substrate suppliers concentrated in South African and Russian mining operations. Distribution runs through captive dealer networks in Central Europe and diversified rental platforms in Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas-powered chainsaw market reads as a late-cycle quality story as professional contractors consolidate procurement around emission-compliant EFI platforms that command sustained premium positioning despite battery-electric substitution at the low-displacement margin.
For Market Incumbents: Extend captive engine production backward into precision fuel injection componentry to defend margin pools against platinum group metal volatility in catalytic converter substrates. Deepen dealer service infrastructure in Poland and Czech Republic where contractor density exceeds professional-grade distribution coverage, insulating against rental platform encroachment in seasonal clearing segments. For New Entrants and Emerging Players: Launch via unbundled rental platform partnerships targeting Mediterranean fire prevention clearing spikes in Provence-Alpes-Côte d'Azur and Occitanie, where irregular demand patterns favor short-term leasing over ownership economics. Prioritize acoustic-dampened urban configurations for municipal arborist contracts in Benelux and northern France, where EU machinery noise directives below 100 dB(A) enforce strict procurement specifications with limited incumbent specialization. For Investors and Strategic Acquirers: Consolidation pressure builds where dealer network gaps in Central European contractor clusters intersect with EFI diagnostic capability scarcity and homologation bandwidth constraints. Long-term viability favors targets with integrated exhaust after-treatment engineering and established captive maintenance agreements with German forestry professionals. Monitor parallel EPA and EU exhaust protocol revision timelines for early signals of certification divergence that would fragment engine platform development and inflate compliance costs across export-dependent supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Exhaust After-Treatment Development | Compact catalytic converter modules paired with acoustic damping chambers address concurrent EPA and EU F-Gas Regulation compliance without chassis redesign. |
| Electronic Fuel Injection Platform Expansion | EFI systems displace diaphragm carburetors in 50cc and above displacement classes, compressing premium positioning of legacy mechanical induction models. |
| Central European Dealer Network Expansion | Professional-grade distribution density in Poland and Czech Republic lags contractor fleet concentration, creating procurement friction for medium-displacement units. |
| Rental Fleet Partnership Structuring | Unbundled maintenance and insurance contracts in France and Italy attract small-scale land-clearing operators lacking dedicated service infrastructure. |
| Certified Technician Training Pipeline Scaling | EFI diagnostics and catalytic converter servicing competency gaps strain dealer network service capacity for emission-compliant platforms. |
Methodological Framework
Coverage spans Germany, United States, France, Sweden, and Poland, with primary inputs from each market combining structured interviews with forestry equipment procurement managers, dealer network operators, municipal arborist contract supervisors, and rental platform fleet managers alongside secondary validation from EPA emission standard filings, EU F-Gas Regulation implementation directives, SEC 10-K disclosures from listed manufacturers, and customs trade data on two-stroke engine componentry. Bottom-up equipment shipment triangulation against top-down contractor fleet replacement cycle analysis anchors volume estimates.
Rate-of-change decomposition separates volume growth from mix-shift toward higher-margin extra-high-displacement and EFI-equipped configurations across the analysis window. Segmentation dimensions modeled include product type tier, engine capacity bracket, use case intensity, and end-user procurement sophistication, with regional regulatory cluster overlay for EPA versus EU exhaust protocol exposure. CAGRs derive from logistic diffusion curves fitted to replacement cycle acceleration patterns under tightening emissions deadlines, incorporating platinum group metal price trajectory scenarios and battery-electric substitution elasticity estimates for sub-40cc equivalent applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under concurrent EPA and EU protocol revision divergence or extended palladium supply disruption. Practitioners should monitor EFI platform adoption rates in high-altitude German and Austrian logging operations and rental platform market share penetration in Mediterranean fire prevention clearing segments for early signals of structural demand shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
EGR Coolers Market
Vehicle Components
Chassis Leveling Valves Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Car Modification Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
High Precision Heavy Load Bearings Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Vehicle Exhaust Hose Market