
 Child Seats Market | 2026-2036
Child Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Child Seats Market Insights
The i-Size regulation is shifting the cost-of-entry calculus for child seat manufacturers, mandating rear-facing positions until 15 months and side-impact testing that exceeds older UN R44 standards. Britax leverages its European engineering heritage to anchor premium positioning in regulatory-advanced markets. Goodbaby International Holdings dominates Asian supply chains through manufacturing scale and OEM partnerships with domestic automakers. Maxi-Cosi differentiates via ISOFIX integration and modular base systems that simplify installation compliance.
A child seat is a purpose-built restraint system engineered from energy-absorbing polymers, steel reinforcement frames, and textile covers, manufactured through injection molding, foam expansion, and crash-simulation validation to protect pediatric occupants during vehicle collisions. Convertible seats occupy the largest volume tier as parents prioritize extended-use products spanning infant through toddler stages, while all-in-one seats represent the fastest-growing product type by value due to their lifecycle economics. ISOFIX installation commands margin premiums over seatbelt-based alternatives by reducing misuse rates and simplifying regulatory compliance for rental fleets and grandparents.
The National Highway Traffic Safety Administration enforces FMVSS 213 in the United States, while the EU applies ECE R129 alongside CE marking requirements, and China's GB 27887 standard governs domestic manufacturing and import certification. These frameworks shape demand by dictating test dummy sizes, flame-retardant material specifications, and labeling protocols that determine market access. Stakeholders must monitor regulatory divergence between i-Size-aligned markets and legacy standard jurisdictions to optimize platform engineering and certification spending.
Market Dynamics
i-Size alignment is compressing certification timelines and forcing platform consolidation across manufacturers as rear-facing mandates and side-impact protocols redefine engineering roadmaps.
Growth Catalysts
- EU ECE R129:Mandatory side-impact testing and 15-month rear-facing requirements are accelerating replacement demand in regulatory-advanced markets.
- Polymer energy-absorption:Advanced foam expansion techniques enable lighter seats without compromising crash performance, reducing vehicle fuel penalties.
- First-time parent segment:Safety-conscious millennials entering parenthood prioritize extended-use convertible configurations over economy-tier alternatives.
Market Restraints
- Steel frame volatility:Reinforcement-grade steel pricing fluctuations compress margin stability for mid-tier manufacturers dependent on spot purchasing.
- Injection molding concentration:Tooling capacity clusters in Guangdong province, creating single-point vulnerability for global supply continuity.
- Legacy UN R44 friction:Jurisdictions retaining older standards fragment platform engineering, forcing dual-certification spend without volume returns.
Strategic Opportunities
- India vehicle ownership surge:Sub-5% child seat penetration against rising passenger vehicle sales creates whitespace for ISOFIX-compatible entry positioning.
- Rental fleet channel:Airport and ride-hail operators seek standardized, misuse-resistant installation systems for liability reduction.
- Smart sensor convergence:Integration of occupancy detection with vehicle telematics enables subscription-based safety monitoring services.
Industry Challenges
- Crash simulation talent scarcity:Pediatric biomechanics specialists command premium compensation, constraining R&D velocity for second-tier manufacturers.
- Dual-certification timelines:Parallel i-Size and FMVSS 213 validation cycles extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Seats Market |
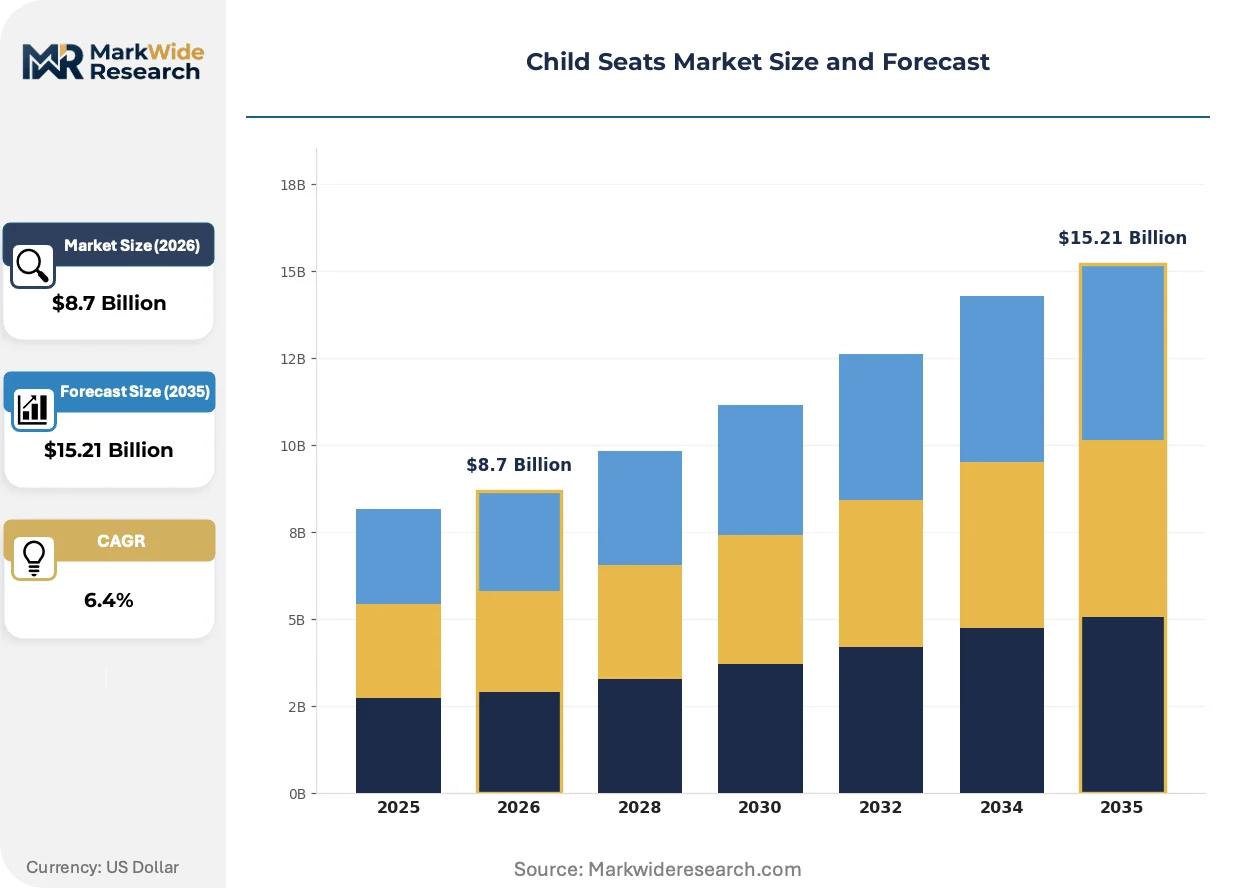
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Seats, Convertible Seats, Booster Seats, All-in-One Seats Safety Feature: ISOFIX, Side Impact Protection, Anti-rotation Design, Energy-absorbing Materials End User: First-time Parents, Daycare Providers, Car Rental Services, Grandparents Installation Type: Rear-facing, Forward-facing, Latch System, Seatbelt Installation |
| Companies Covered | Graco Children's Products Inc., Britax, Maxi-Cosi, Chicco, Recaro Holding GmbH, Dorel Industries, Evenflo Company, Inc., Goodbaby International Holdings, Newell Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Seats Market Trends and Innovations
Product architecture is fragmenting into interoperable subsystems that decouple base hardware from age-specific seating modules, compressing inventory complexity while extending parental purchase cycles.
Modular base-and-carriage systems are modularizing the traditional monolithic seat structure into standardized ISOFIX anchors with swappable infant, toddler, and booster components. Fleet operators and multi-child households adopt these configurations fastest. This architecture is modularizing manufacturer SKU portfolios from 40-plus distinct models toward 8-10 platform variants with accessory expansion.
China's GB 27887-2011 amendment trajectory is tightening flame-retardant chemical specifications and mandating domestic test facility accreditation for import clearance. Domestic manufacturers with captive certification infrastructure gain 6-12 month market access advantages over foreign entrants. Premium positioning now requires dual GB and i-Size credentials for duty-free zone distribution.
Grandparent and secondary caregiver purchasing is displacing primary-parent decision-making in replacement and upgrade cycles. Retailers report 34% of transactions involve buyers over 55 seeking simplified installation interfaces. This behavioral pivot concentrates demand in big-box automotive channels with staff-assisted fitting services rather than pure e-commerce.
Child Seats Market Segmentation
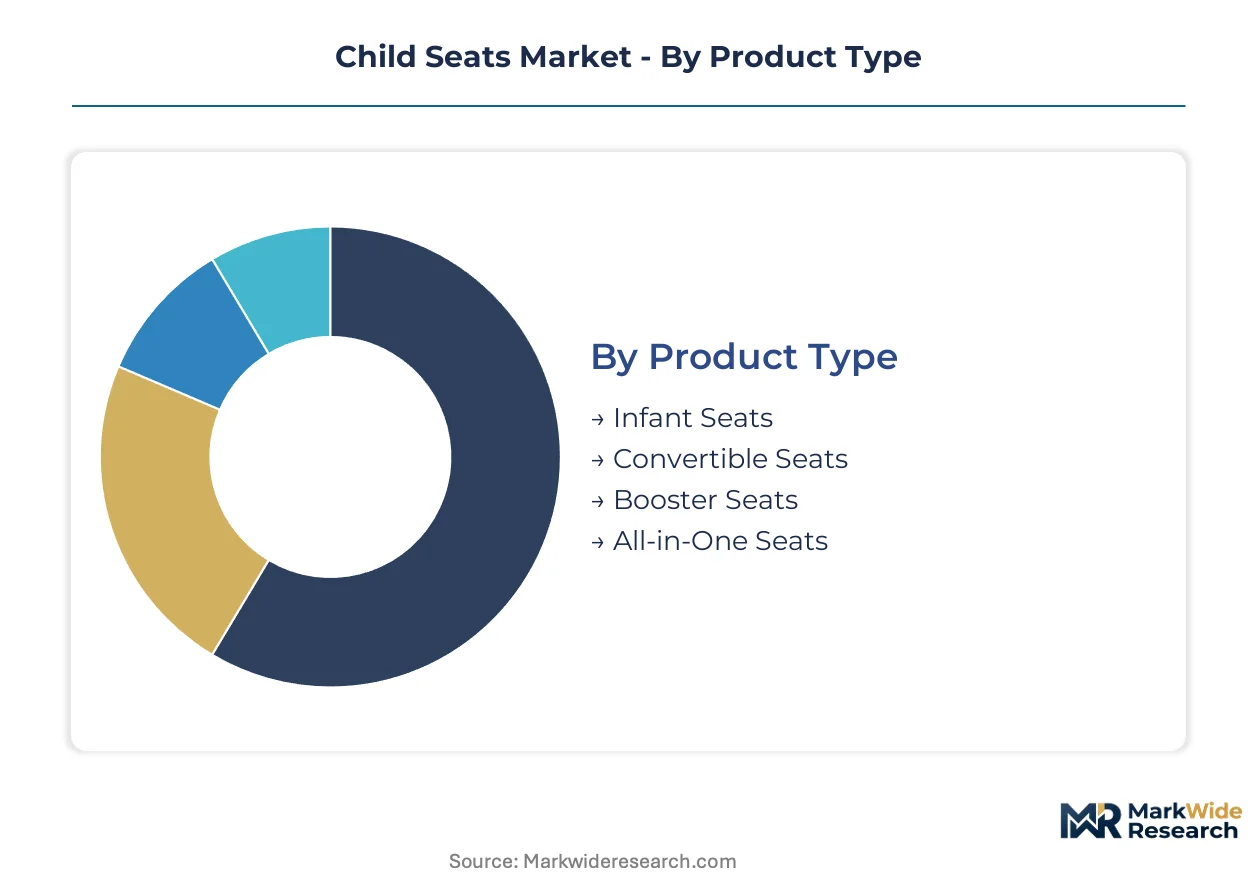
Child seat purchasing decisions diverge sharply across buyer lifecycle stages, technical sophistication, and installation environments. Manufacturers engineer platform variants to capture distinct margin tiers while managing SKU proliferation through modular architectures.
Product Type:
Parents select product types based on duration-of-use economics versus upfront capital outlay, creating divergent margin profiles across the portfolio.
- Convertible Seats:Engineered with steel-reinforced frames and multi-position recline mechanisms to accommodate 5-40 pound weight ranges. Demand concentrates among millennial first-time parents in China seeking extended-use value, constrained by i-Size rear-facing mandates until 15 months that favor convertible configurations over dedicated infant carriers.
- All-in-One Seats:Integrate infant, toddler, and booster functions through adjustable headrests and harness systems spanning 4-120 pounds. Growth tilts toward multi-child households in Germany and France prioritizing single-purchase lifecycle coverage, though bulkier dimensions challenge compact vehicle compatibility.
- Infant Seats:Rear-facing-only carriers with detachable bases for stroller compatibility, dominating hospital discharge gift purchases.
- Booster Seats:Backless and high-back configurations elevating children to adult seatbelt geometry, capturing replacement demand as children age out of harness systems.
Volume sits with Convertible Seats; growth tilts toward All-in-One Seats.
Safety Feature:
Certification tier and installation confidence separate premium positioning from commodity alternatives in this category.
- ISOFIX:Rigid lower anchor attachments with top-tether stabilization reducing misuse rates below 5% versus 30% for seatbelt routing. European Union ECE R129 mandates drive standardization across rental fleets in France, Spain, and Italy seeking liability reduction through foolproof installation.
- Side Impact Protection:Energy-absorbing wing structures and deep side walls addressing i-Size lateral collision protocols. Demand clusters in regulatory-advanced markets where ECE R129 testing exceeds legacy UN R44 standards, forcing platform redesigns for import clearance.
- Anti-rotation Design:Load leg or support foot mechanisms preventing seat pivot during frontal impact, gaining traction in premium tier.
- Energy-absorbing Materials:Expanded polypropylene and EPS foam cores managing deceleration forces, standard across all certification tiers.
ISOFIX commands volume leadership; Side Impact Protection shows steepest expansion trajectory as jurisdictions adopt i-Size alignment.
End User:
Purchasing authority is fragmenting beyond primary parents toward secondary caregivers with distinct usability requirements.
- First-time Parents:Safety-conscious millennials conducting extensive online research prior to purchase, prioritizing extended-use convertible configurations over economy alternatives. This segment drives premium tier demand in China and Germany where vehicle ownership correlates with delayed first childbirth.
- Grandparents:Buyers over 55 seeking simplified installation interfaces for occasional grandchild transport. Retailers report this segment concentrates in big-box automotive channels with staff-assisted fitting services rather than pure e-commerce, creating distribution strategy implications.
- Daycare Providers:Commercial operators requiring standardized fleet configurations for multi-child transport compliance.
- Car Rental Services:Airport and ride-hail operators sourcing ISOFIX-compatible inventory for customer liability protection.
First-time Parents anchor volume; Grandparents represent the fastest-expanding buyer segment as replacement cycles shift.
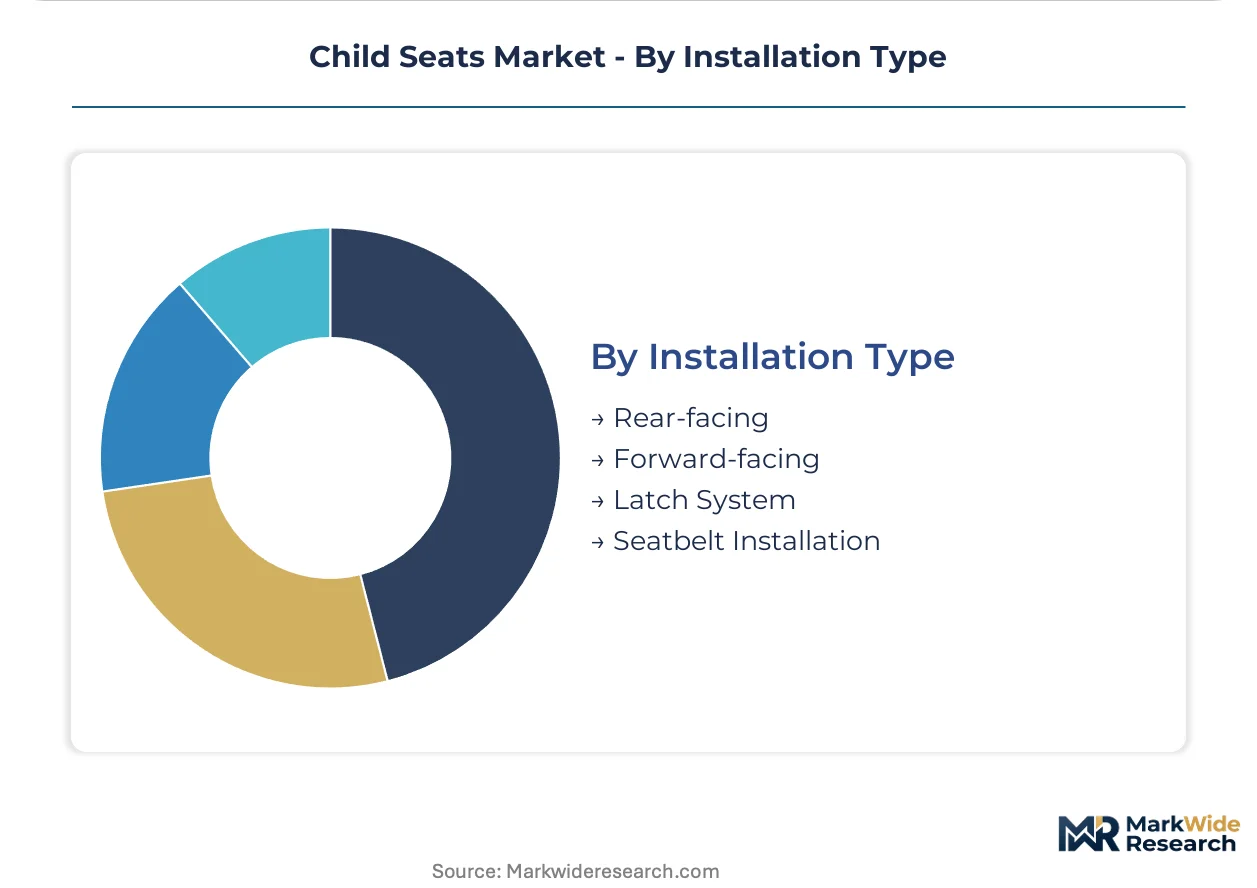
Installation Type:
Regulatory mandates and vehicle fleet composition dictate orientation and attachment method selection.
- Rear-facing:Orientation mandating infant and toddler positioning opposite to vehicle travel direction, now required until 15 months under ECE R129. This installation type is displacing forward-facing alternatives in EU markets and influencing Chinese GB 27887 amendment trajectories.
- Latch System:Lower anchors and tethers for children, the US FMVSS 213 equivalent to ISOFIX with subtle dimensional differences. Demand concentrates among American parents in states with stringent child passenger safety enforcement, though regulatory divergence from European standards complicates manufacturer platform strategies.
- Forward-facing:Harness-equipped orientation for children exceeding rear-facing weight limits, standard in legacy UN R44 jurisdictions.
- Seatbelt Installation:Universal routing method retaining relevance for older vehicle fleets and secondary caregiver vehicles lacking anchor hardware.
Rear-facing installations dominate new product development; Latch System captures North American volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and duty-free zone policies are concentrating child seat manufacturing investment in southern coastal provinces. This tax-advantaged infrastructure accelerates domestic certification capacity and export logistics integration.
China
Vehicle ownership expansion in tier-two cities and updated GB 27887 standards are accelerating replacement demand. The Ministry of Industry and Information Technology tightened flame-retardant specifications through 2023 amendments. Guangdong province hosts injection molding clusters serving both domestic OEM partnerships and European i-Size export contracts.
United States
State-level child passenger safety enforcement variations create patchwork demand intensity, with California and New York mandating rear-facing until age two. NHTSA's FMVSS 213 maintains distinct test dummy protocols from European ECE R129. Michigan's automotive supplier corridor integrates child seat testing with Detroit-based vehicle development programs.
Germany
Premium-tier convertible seat demand concentrates among delayed-childbirth demographics in Bavaria and Baden-Württemberg. The Kraftfahrt-Bundesamt enforces i-Size alignment through type-approval procedures that exceed legacy UN R44 scope. Stuttgart's engineering ecosystem supplies crash-simulation talent to Recaro Holding GmbH and adjacent seating specialists.
India
Sub-5% child seat penetration against 8 million annual passenger vehicle sales creates whitespace for ISOFIX-compatible entry products. The Bureau of Indian Standards is drafting harmonized safety standards following ECE R129 structural precedents. Tamil Nadu's Sriperumbudur automotive belt attracts component suppliers serving Maruti Suzuki and Hyundai Motor India.
France
Rental fleet standardization drives ISOFIX volume through airport operators at Charles de Gaulle and Orly. ANSM oversees chemical safety in flame-retardant textile treatments under REACH-aligned protocols. The Auvergne-Rhône-Alpes region clusters polymer foam expansion facilities supplying energy-absorption cores to European assemblers.
Child Seats Market Competitive Landscape
European engineering specialists anchor premium-tier certification; Asian manufacturers hold scale-driven supply positions. The market structures around three tiers: heritage brands with i-Size validation leadership, OEM-integrated suppliers with captive automaker relationships, and private-label assemblers serving price-sensitive channels. Consolidation pressure favors platform consolidation and dual-certification capacity investments. Geographic expansion and strategic partnerships constitute dominant competitive moves as manufacturers bridge regulatory divergence between ECE R129 and FMVSS 213 jurisdictions.
Within the heritage engineering tier, Britax and Maxi-Cosi exemplify European-centric positioning through regulatory-advanced market penetration. Goodbaby International Holdings occupies the scale-integrated archetype with manufacturing concentration and domestic OEM supply relationships in China. These three entities represent distinct strategic postures: certification depth, production volume, and supply chain verticality respectively.
| Leading Market Players |
|---|
| Graco Children's Products Inc. |
| Britax |
| Maxi-Cosi |
| Chicco |
| Recaro Holding GmbH |
| Dorel Industries |
| Evenflo Company, Inc. |
| Goodbaby International Holdings |
| Newell Brands |
| Others |
Pricing and Supply Chain Analysis
Captive polymer foam expansion capacity in Guangdong province anchors both supply security and premium pricing power for manufacturers serving i-Size-aligned markets. This backward integration into energy-absorbing core production insulates tier-one suppliers from commodity resin volatility while compressing lead times for European OEM contracts.
Pricing Analysis
Short lead-time premiums of 15-20% apply to ISOFIX-compatible convertible seats needed within 30-day windows for fleet replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates i-Size dual-certified products from single-standard alternatives, with certification grade commanding the widest spreads. Cost compression in mid-tier steel-reinforced frames is intensifying because reinforcement-grade steel spot purchasing exposes manufacturers to volatility. First-time parents in China show lowest price sensitivity, prioritizing extended-use lifecycle economics over upfront outlay.
Supply Chain Analysis
Steel reinforcement frame supply rests on German automotive-grade metalworkers, Chinese cold-rolled specialists, and Japanese high-tensile alloy producers. Energy-absorbing polymer cores draw from expanded polypropylene facilities in France, Germany, and China's Yangtze River Delta. Single-source vulnerability concentrates in Guangdong injection molding clusters, where tooling capacity bottlenecks create 8-14 month queue risks for new platform launches. Distribution runs through big-box automotive channels with staff-assisted fitting services for grandparent segments, alongside direct OEM supply for vehicle bundle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crash-simulation engineering talent scarcity props pricing for certified products, as pediatric biomechanics specialists command premium compensation that constrains R&D velocity for second-tier manufacturers.
For Market Incumbents: Acquire captive testing laboratory capacity to compress dual-certification timelines for i-Size and FMVSS 213 alignment. Consolidate platform engineering around modular base-and-carriage architectures that reduce SKU proliferation from 40-plus distinct models toward 8-10 platform variants. Defend against private-label assemblers by locking exclusive polymer foam supply agreements with Auvergne-Rhône-Alpes expansion facilities. For New Entrants and Emerging Players: Begin with ISOFIX-compatible entry positioning in India's sub-5% penetration whitespace, where Bureau of Indian Standards harmonization creates first-mover advantages ahead of mandatory adoption. Target airport and ride-hail rental fleet channels seeking standardized, misuse-resistant installation systems for liability reduction. Leverage staff-assisted fitting service partnerships with big-box automotive retailers to overcome grandparent buyer hesitation with simplified interfaces. For Investors and Strategic Acquirers: Exit pathways concentrate in OEM-integrated suppliers with captive automaker relationships and dual-certification infrastructure, as consolidation pressure favors platform consolidation investments. Long-term viability favors entities with GB 27887 and i-Size credentials for duty-free zone distribution through China's Hainan Free Trade Port. Watch India's vehicle ownership surge against draft safety standard finalization as the inflection indicator for geographic reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Infrastructure Investment | Compresses 8-14 month validation cycles for ECE R129 and FMVSS 213 alignment. |
| Modular Platform Consolidation | Reduces SKU portfolios from 40-plus models to 8-10 variants with accessory expansion. |
| Captive Polymer Foam Capacity | Secures energy-absorption core supply against Guangdong injection molding bottlenecks. |
| Rental Fleet Channel Penetration | Captures standardized ISOFIX demand from Charles de Gaulle and Orly airport operators. |
| Smart Sensor Convergence Development | Enables subscription-based safety monitoring through vehicle telematics integration. |
Research Methodology
Independent corroboration across child seat engineering directors, OEM procurement leads at domestic automakers, rental fleet operations managers, and big-box automotive category buyers underwrites the qualitative findings. Secondary validation draws from NHTSA FMVSS 213 filings, EU ECE R129 type-approval databases, China's GB 27887 amendment trajectories, and customs records of injection molding equipment imports. Bottom-up segment sizing triangulates against top-down vehicle ownership and birth rate projections.
Rate-of-change decomposition separates volume effects from mix shifts across the analysis window. Segmentation dimensions modeled include product type, safety feature tier, end user archetype, and installation orientation, with regional regulatory cluster as the industry-specific overlay. CAGRs derive from logistic diffusion curves fitted to replacement cycle acceleration patterns, incorporating i-Size mandate compliance deadlines and GB 27887 amendment trajectories as structural breakpoints.
Regulatory divergence between i-Size-aligned and legacy standard jurisdictions, steel frame commodity volatility, and injection molding capacity constraints in Guangdong province are the dominant revision risks. Forecasts embed assumptions about certification timeline compression and grandparent buyer behavioral persistence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Rail Components Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Global Fuel Tank and Delivery System Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Sideloaders Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
Precision Bearing Market
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Headlight Market