
 Global Car Accessories Market | 2026-2036
Global Car Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Accessories Market Analysis
Commercial fleet operators is bifurcating demand away from purely individual consumer purchases as enterprise procurement standardizes around durability-rated accessories. Bosch leverages its sensor-integration expertise to embed intelligent monitoring into cabin add-ons. Continental AG anchors its position through captive supply relationships with European OEM assembly lines. Denso Corporation specializes in climate-controlled seating modules that bridge the accessory and component boundary.
Car accessories encompass supplementary products manufactured from plastic, fabric, rubber, or vinyl substrates that attach to or protect vehicle interiors and exteriors without altering factory-engineered mechanical systems. These items typically undergo injection molding, die-cutting, or thermoforming processes to achieve precise fitment against OEM dimensional tolerances, serving primarily to preserve residual value and enhance occupant comfort during the vehicle ownership cycle. Floor mats and seat covers represent mature margin pools where brand premiums have compressed, while cargo liners capture faster expansion as crossover utility vehicles proliferate across consumer and fleet segments. Online retail channels are displacing department stores for replacement-cycle purchases, though specialty stores retain dominance for first-fit bundling at automotive dealerships.
The EPA regulates volatile organic compound emissions from interior materials under its broader air quality mandates, while REACH restricts phthalate and heavy metal content in vinyl and rubber formulations sold across European member states. China's GB standards, administered by SAMR, mandate flame-retardancy thresholds for cabin accessories in domestic-market vehicles. Stakeholders must monitor regulatory divergence between jurisdictions to avoid dual-certification cost burdens that erode cross-border product economics.
Market Dynamics
Enterprise fleet procurement standardization is compressing retail margins while forcing suppliers to engineer durability-rated SKUs that withstand commercial utilization cycles. This structural pull from B2B buyers is reshaping product development roadmaps across the value chain.
Growth Catalysts
- REACH compliance mandates:European ECHA enforcement of phthalate restrictions in vinyl formulations is accelerating reformulation investments toward bio-based polymer alternatives that command price premiums in aftermarket channels.
- Crossover utility vehicle proliferation:Cargo liner demand from fleet operators and family buyers is expanding addressable volume for thermoformed polyethylene accessories designed for expanded load floors.
- Sensor-embedded cabin monitoring:Intelligent seat covers integrating pressure and occupancy detection are creating new attach-rate opportunities as OEMs bundle connected interior packages.
Market Restraints
- Petrochemical input volatility:Polypropylene and ABS resin prices tied to crude oil benchmarks create margin compression for injection-molded floor mat manufacturers without long-term supply contracts.
- Chinese domestic supplier concentration:Zhejiang and Guangdong provinces host captive mold-making capacity that limits European and North American molders' access to cost-competitive tooling.
- Substitution by integrated OEM solutions:Factory-installed all-weather flooring packages from automakers are capturing first-fit demand that previously flowed to aftermarket retailers.
Strategic Opportunities
- India's PLI scheme for auto components:Component-grade accessory manufacturing qualifies for production-linked incentives that reduce effective tax burdens for localized thermoforming operations.
- Subscription-based accessory refresh models:Fleet management platforms are piloting seat cover and mat replacement programs tied to mileage triggers rather than ownership cycles.
- Climate-controlled module convergence:Ventilated seating surfaces bridging component and accessory classifications capture higher per-vehicle revenue than passive protection products.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel EPA VOC testing, REACH SVHC screening, and SAMR flame-retardancy validation extend product launch cycles by 8-14 months.
- Legacy ERP integration friction:Tier-2 molders struggle to connect production scheduling systems with Amazon Vendor Central and Shopify Plus APIs demanded by digital-native retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Accessories Market |
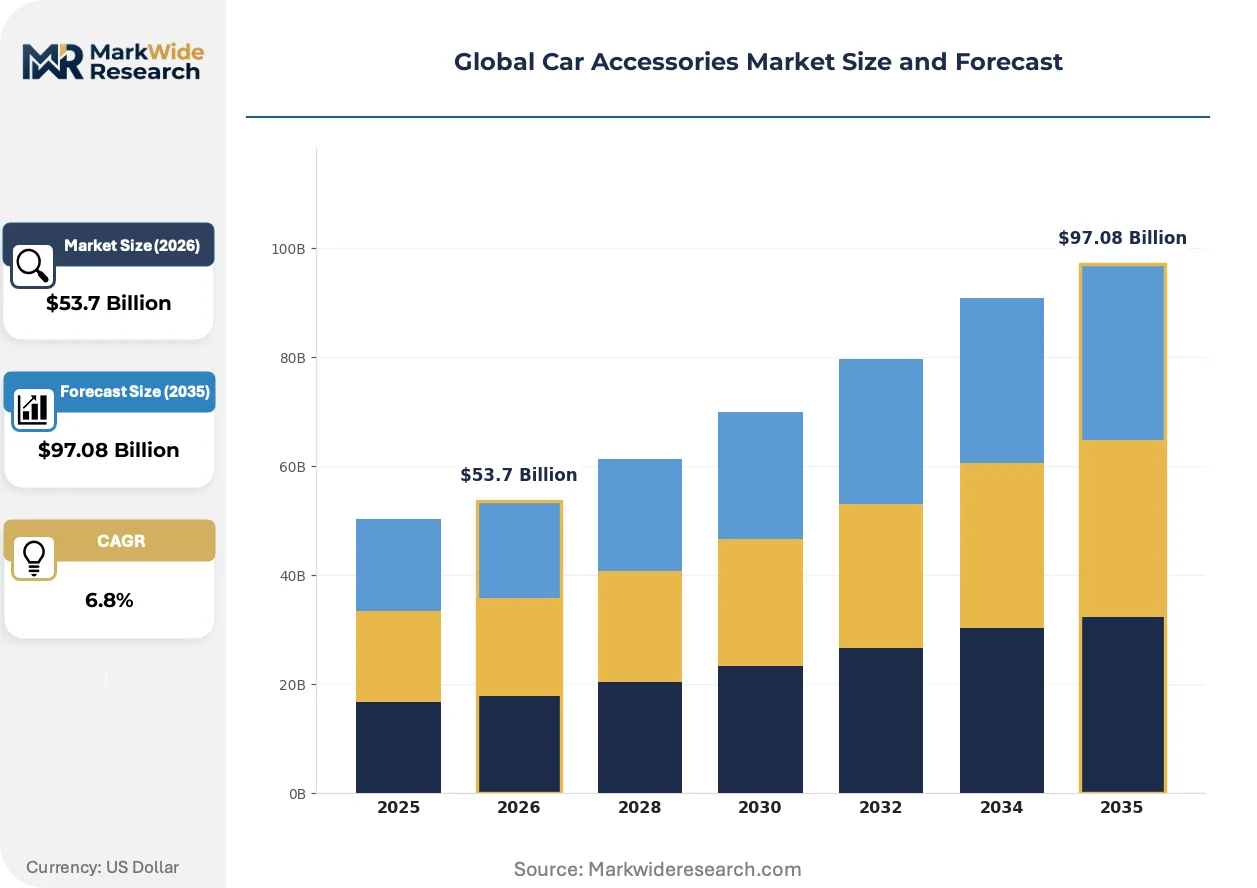
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $97.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Mats, Seat Covers, Car Covers, Cargo Liners Distribution Channel: Online Retail, Specialty Stores, Department Stores, Trade Shows End User: Individual Consumers, Commercial Fleets, Vehicle Rental Services, Automotive Dealerships Material: Plastic, Fabric, Rubber, Vinyl |
| Companies Covered | Bosch, Denso Corporation, Continental AG, Magna International, Valeo, Lear Corporation, Pioneer Corporation, Faurecia, Aisin Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Accessories Market Emerging Trajectories
Digital retail infrastructure is fragmenting traditional dealer-centric distribution while material science advances enable functional differentiation beyond cosmetic customization. These shifts are compressing legacy margin pools and opening new value-capture mechanisms.
Recycled ocean-bound polyethylene terephthalate is displacing virgin polypropylene in premium cargo liner formulations. Sustainability-focused fleet operators in California and Nordic markets specify recycled-content thresholds in RFPs. This material transition is displacing conventional thermoformed products in the premium tier while compressing margins for undifferentiated virgin-material competitors.
EPA Tier 3 emission standards for volatile organic compounds now extend to aftermarket interior materials through state-level adoption by California Air Resources Board. Manufacturers must reformulate adhesives and vinyl topcoats to meet 50-microgram-per-cubic-meter cabin air quality thresholds. The seat cover segment bears the highest compliance burden, with suppliers accelerating water-based coating transitions ahead of 2025 enforcement windows.
Direct-to-consumer configurators are capturing replacement-cycle demand that previously flowed through auto parts retailers. Younger vehicle owners in Germany and South Korea design custom-fit accessories via 3D scanning apps before factory fulfillment. This channel shift is most pronounced among EV owners, who demonstrate higher willingness-to-pay for interior personalization than internal combustion vehicle cohorts.
Global Car Accessories Market Segmentation
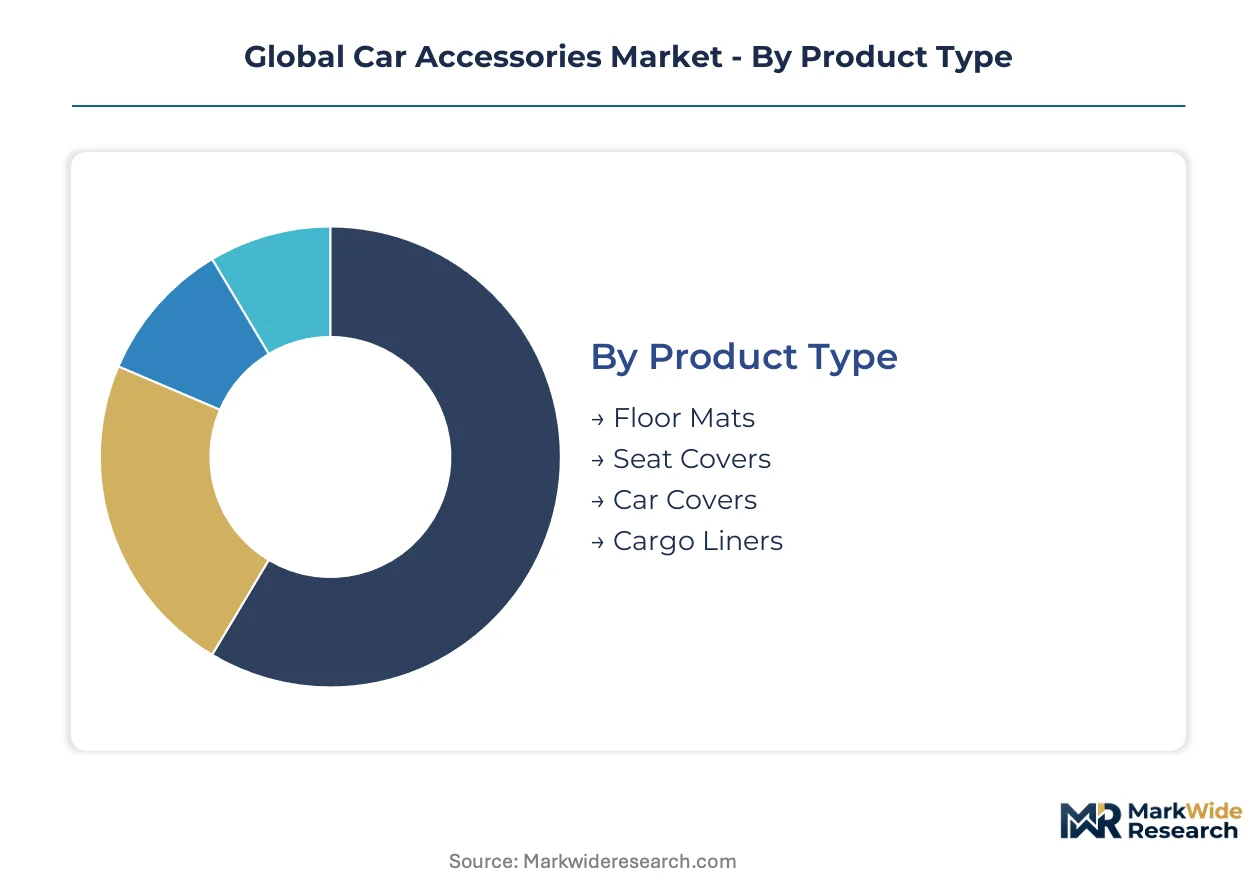
Accessory suppliers engineer distinct SKU portfolios across each dimension to capture value at divergent price points and regulatory thresholds. Segmentation discipline separates commodity replacement cycles from premium first-fit bundling opportunities.
Product Type:
REACH phthalate restrictions and EPA VOC thresholds create divergent compliance burdens across interior accessory categories, forcing suppliers to maintain parallel formulation tracks.
- Floor Mats:Injection-molded polypropylene and thermoplastic elastomer constructions dominate volume production. Commercial fleet procurement in Germany and California specifies all-weather durability ratings above 150,000 abrasion cycles, compressing margins for undifferentiated suppliers while rewarding compound innovators.
- Seat Covers:Fabric and vinyl substrates integrate pressure sensors for occupancy detection in premium tiers. China's GB flame-retardancy mandates for domestic-market vehicles drive reformulation costs that price out smaller regional molders.
- Car Covers:Multi-layer breathable membranes protect against UV degradation and acid rain.
- Cargo Liners:Thermoformed polyethylene formulations tailored to crossover utility vehicle load floors.
Established volume favors floor mats; emerging adoption favors cargo liners.
Distribution Channel:
Channel economics separate high-frequency replacement purchases from low-consideration first-fit bundling, with digital infrastructure capturing divergent customer cohorts.
- Online Retail:Amazon Vendor Central and Shopify Plus APIs enable direct-to-consumer configurators with 3D fitment visualization. Younger EV owners in South Korea and Germany drive premium personalization attach rates through digital-native interfaces.
- Specialty Stores:Dealer-affiliated channels retain first-fit bundling dominance for OEM-approved accessory packages. Captive supply relationships with European assembly lines anchor Continental AG's positioning in this channel.
- Department Stores:Mass-market floor mat and seat cover volume faces displacement from digital competitors.
- Trade Shows:B2B fleet procurement standardization concentrates at SEMA and Automechanika events.
Procurement consolidation favors specialty stores; digital migration favors online retail.
End User:
Utilization intensity separates consumer durability expectations from commercial cycle requirements, with fleet standardization rewriting supplier qualification protocols.
- Individual Consumers:Aesthetic customization and residual value preservation drive replacement-cycle purchasing. Water-based coating transitions for EPA Tier 3 compliance add cost premiums that compress mass-market affordability.
- Commercial Fleets:Enterprise procurement mandates durability-rated SKUs with unified branding across vehicle classes. Rental operators in the United States specify recycled-content thresholds that favor ocean-bound PET formulations.
- Vehicle Rental Services:High-turnover interior protection requires rapid-install modular systems.
- Automotive Dealerships:First-fit bundling captures margin through finance-and-insurance product attachment.
Volume concentration favors commercial fleets; margin expansion favors individual consumers.
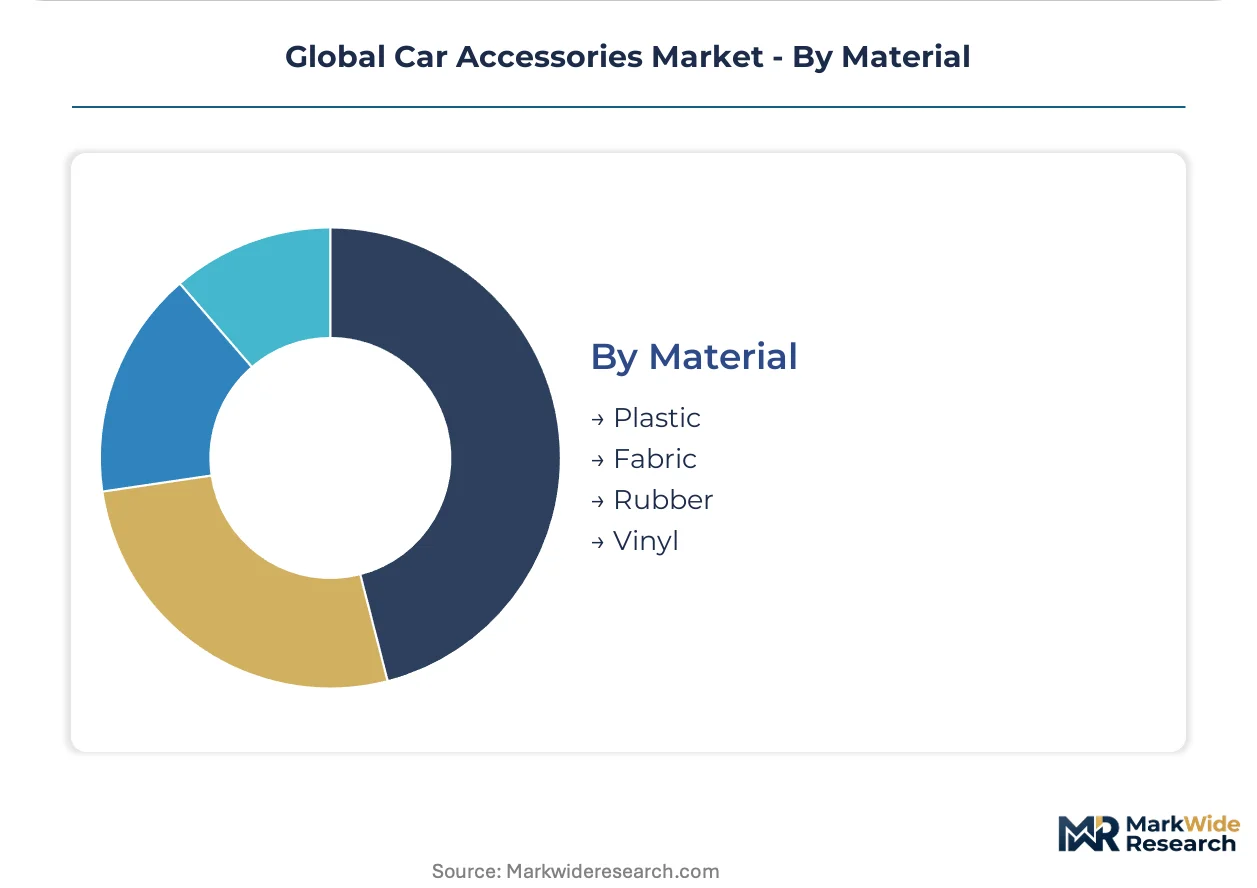
Material:
Substrate selection locks suppliers into distinct regulatory pathways and petrochemical exposure profiles across jurisdictions.
- Plastic:Polypropylene and ABS resins face crude oil price volatility without long-term supply contracts. India's PLI scheme for auto components reduces effective tax burdens for localized thermoforming operations using these substrates.
- Fabric:Woven and non-woven textiles enable sensor integration for intelligent cabin monitoring.
- Rubber:Natural and synthetic elastomers provide all-weather traction performance.
- Vinyl:Phthalate-dependent formulations face ECHA enforcement acceleration across European member states.
Cost efficiency favors plastic; regulatory headwinds favor fabric alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Guangdong provinces export thermoformed polyethylene cargo liners to fleet operators in California and Germany, anchoring the dominant trade-flow corridor for injection-molded accessories.
United States
Commercial fleet procurement from rental operators and last-mile delivery services concentrates demand for durability-rated floor mats. EPA Tier 3 VOC standards enforced by California Air Resources Board mandate water-based coating transitions for seat cover suppliers. Detroit's automotive supplier corridor hosts captive mold-making operations serving domestic OEM bundling programs.
Germany
REACH phthalate restrictions accelerate bio-based polymer reformulation for vinyl accessories across aftermarket channels. ECHA enforcement timelines compress product launch cycles for cross-border suppliers. Stuttgart's engineering cluster anchors Continental AG's captive supply relationships with European assembly lines.
China
Domestic automakers scale accessory bundling with new vehicle sales, concentrating volume in state-backed procurement frameworks. SAMR-administered GB standards mandate flame-retardancy thresholds for cabin accessories in domestic-market vehicles. Guangdong's thermoforming belt supplies cost-competitive tooling that limits European molder market access.
India
The PLI scheme for auto components reduces effective tax burdens for localized thermoforming operations using polypropylene substrates. Component-grade accessory manufacturing qualifies for production-linked incentives that attract regional molders. Maharashtra's automotive component corridor hosts expanding injection-molding capacity for domestic fleet replacement cycles.
South Korea
Younger EV owners demonstrate higher willingness-to-pay for interior personalization through direct-to-consumer digital configurators. MFDS-equivalent consumer safety frameworks govern material specifications for cabin accessories. Seoul's mobility-tech cluster pilots 3D scanning apps for custom-fit accessory fulfillment before factory production.
Global Car Accessories Market Vendor Landscape
Listed leaders compete with private specialists across sensor-embedded and climate-controlled product lines, producing a tiered structure where scale-driven OEM suppliers anchor premium tiers while regional molders capture aftermarket volume. Three archetypes dominate: integrated electronics specialists leveraging sensor expertise, captive supply partners locked into assembly-line relationships, and material-science innovators commanding sustainability premiums. Competitive moves concentrate on strategic partnerships for digital retail integration and capacity expansion in India under PLI incentive frameworks.
Among sensor-integration specialists, Bosch exemplifies the electronics-leveraging archetype through intelligent cabin monitoring embedded in seating modules. Denso Corporation occupies a position bridging component and accessory classifications with climate-controlled seating systems. Continental AG anchors the captive-supply tier through European OEM assembly line relationships. These three represent distinct strategic positions rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Bosch |
| Denso Corporation |
| Continental AG |
| Magna International |
| Valeo |
| Lear Corporation |
| Pioneer Corporation |
| Faurecia |
| Aisin Seiki |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between commercial fleet operators and injection-molding suppliers lock in polypropylene resin access while stabilizing unit economics against crude oil volatility. These contracts compress spot-market exposure for German and California-based buyers sourcing thermoformed cargo liners from Zhejiang molders.
Pricing Analysis
Sensor-embedded seat covers command substantial premiums over passive vinyl alternatives, while conventional floor mats face price erosion from virgin-material competitors. Three-tier pricing structure across premium, standard, and economy levels separates intelligent cabin monitoring systems from durability-rated fleet SKUs and undifferentiated mass-market offerings. Cost compression in commodity thermoforming is intensifying because Chinese domestic suppliers leverage captive mold-making capacity in Guangdong. Fleet procurement teams exhibit lowest price sensitivity due to standardized enterprise contracts, whereas individual replacement-cycle buyers demonstrate highest elasticity.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for thermoformed polyethylene cargo liners bound for California rental operators. Manufacturing gravity centers on China, Germany, and the United States, with Zhejiang and Guangdong provinces hosting dominant injection-molding capacity. Raw material flows draw from polypropylene resin producers, ABS compounders, and bio-based polymer innovators. Single-source vulnerability concentrates in Chinese mold-making equipment, where European and North American molders face limited alternative sourcing. Distribution runs through dealer-affiliated specialty stores for first-fit bundling and Amazon Vendor Central for replacement-cycle fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as subscription-based accessory refresh models pilot among fleet management platforms, converting one-time purchases into recurring revenue streams.
For Market Incumbents: Fortify captive supply relationships with European OEM assembly lines against integrated factory-installed flooring packages that capture first-fit demand. Deepen backward integration into bio-based polymer formulation to offset REACH phthalate restriction compliance costs. Prioritize certification investment for EPA Tier 3 water-based coating transitions ahead of state-level enforcement windows. For New Entrants and Emerging Players: Lead with direct-to-consumer digital configurators targeting younger EV owners in South Korea and Germany who demonstrate elevated willingness-to-pay for interior personalization. Penetrate India's component-grade accessory manufacturing under PLI scheme incentives that reduce effective tax burdens for localized thermoforming operations. Deploy 3D scanning app technology as the primary go-to-market angle for custom-fit fulfillment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-embedded cabin monitoring specialists bridging component and accessory classifications. Long-term viability favors material-science innovators commanding sustainability premiums from recycled ocean-bound PET formulations. Acquisition targets should display captive mold-making capacity or bio-based polymer IP. Watch fleet procurement standardization velocity at SEMA and Automechanika as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Product Development | Bosch leverages pressure-detection expertise to capture intelligent cabin monitoring attach rates. |
| Bio-Based Polymer Reformulation | REACH phthalate restrictions accelerate investments commanding aftermarket price premiums. |
| Direct-to-Consumer Digital Launch | 3D scanning apps displace auto parts retailers among younger EV owner cohorts. |
| India PLI Manufacturing Footprint | Localized thermoforming operations reduce effective tax burdens for polypropylene substrate processing. |
| Fleet Subscription Model Pilot | Mileage-triggered replacement programs convert ownership-cycle purchases into recurring revenue streams. |
Methodological Framework
Cross-validation between primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads anchors the qualitative findings against secondary validation from vehicle production databases, IHS Markit registration data, EPA VOC compliance filings, and ECHA REACH substance screening records. Bottom-up SKU-level modeling triangulates with top-down market sizing across the analysis window.
Sensitivity analysis tests forecast robustness across propulsion architecture segmentation, content-per-vehicle assumptions, and regional production cluster variations throughout the projection horizon. The analytical framework models vehicle class, material substrate, distribution channel, and end-user utilization intensity dimensions. CAGRs derive from historical trajectory analysis adjusted for fleet procurement standardization and regulatory compliance timeline impacts.
The analysis sits within stated boundaries; outcomes outside sustained crude oil price stability, REACH enforcement acceleration, or Chinese domestic automaker bundling scale would require recalibration. Forecasts reflect documented assumptions regarding petrochemical input costs, multi-jurisdiction certification timelines, and digital channel migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Rear Axle Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Engine Air Filter Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Railway Brake Pads Market