
 Global Bearings Market | 2026-2036
Global Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bearings Market Analysis
Predictive maintenance subscriptions is pivoting the bearings value proposition from unit sales to uptime guarantees. SKF leverages digital diagnostics platforms to anchor recurring revenue streams. Schaeffler Group sustains R&D intensity across sensor-integrated bearing systems. Timken Company dominates high-performance tapered roller configurations for heavy-industry applications.
Bearings are precision-engineered mechanical components that constrain relative motion to desired movement and reduce friction between rotating surfaces, typically manufactured through hardened steel ring grinding, raceway superfinishing, and controlled clearance assembly. Their primary purpose spans power transmission, load support, and rotational accuracy across industrial machinery, transportation equipment, and energy systems. Roller bearings command the largest installed base due to radial load capacity in mining and construction gearboxes, while ceramic material variants capture expanding margin pools in aerospace motors and semiconductor pumps where thermal stability and corrosion resistance outweigh cost premiums.
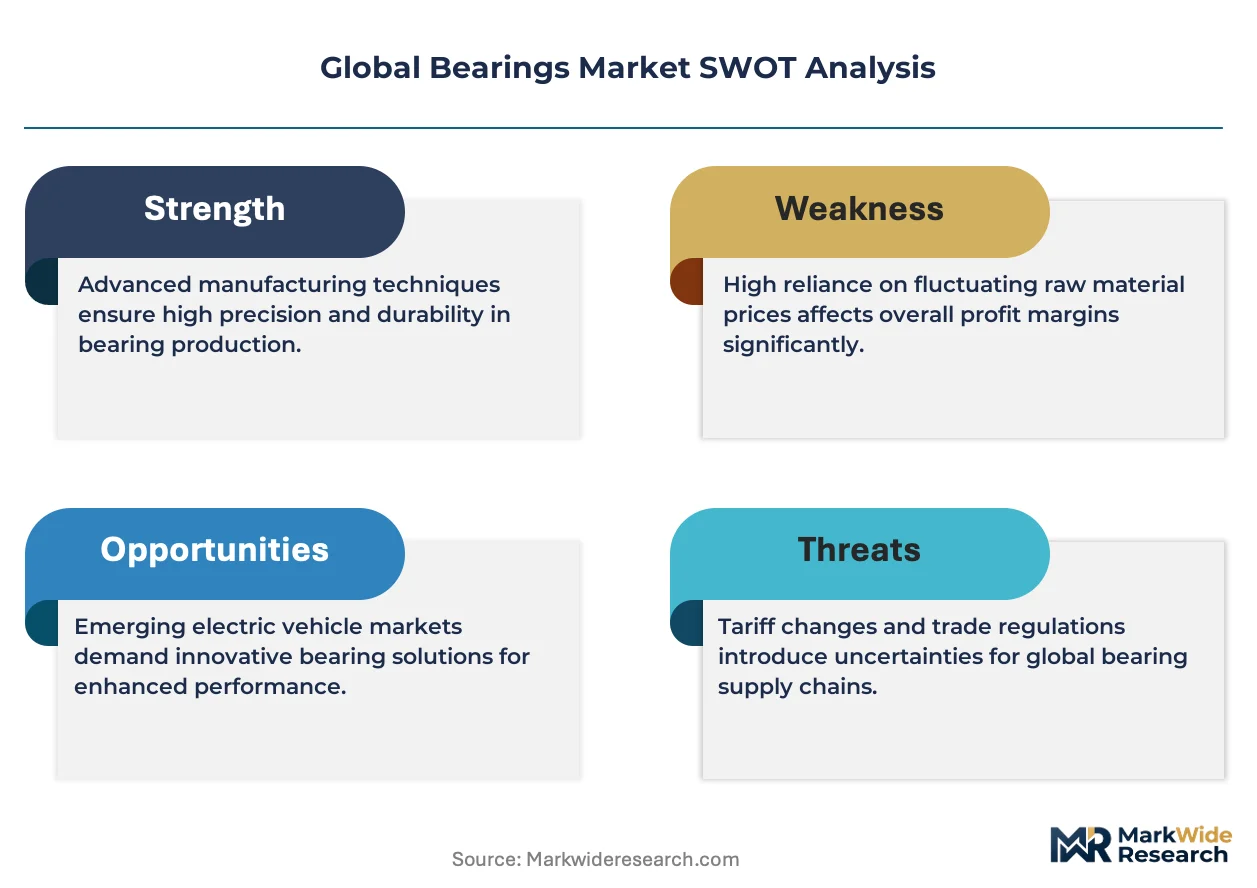
FDA device-quality standards, EPA emissions frameworks, and REACH chemical restrictions collectively shape bearing material selection, lubricant formulation, and supplier qualification protocols across regulated end-use sectors. The EU Green Deal and CSRD disclosure rules are forcing lifecycle transparency into procurement specifications, favoring suppliers with verified carbon accounting. Stakeholders must monitor how dual carbon goals in China and India's PLI scheme for advanced manufacturing reshape sourcing geography and certification requirements.
Market Dynamics
Electric vehicle powertrain architectures are forcing bearing suppliers to redesign load-bearing geometries for higher rotational speeds and reduced lubrication tolerance, compressing traditional product lifecycles.
Growth Catalysts
- EU Green Deal lifecycle mandates:CSRD disclosure rules and REACH chemical restrictions accelerate ceramic bearing substitution in semiconductor pumps and aerospace motors where thermal stability commands premium positioning.
- India PLI scheme for advanced manufacturing:Production-linked incentives attract precision component capacity expansion, concentrating supply chain investment in Tamil Nadu and Gujarat industrial corridors.
- Sensor-integrated bearing systems:Embedded vibration and temperature monitoring enable predictive maintenance subscriptions, anchoring recurring revenue streams for industrial automation buyers.
Market Restraints
- Specialized steel alloy cost volatility:Vacuum-degassed bearing steel and rare-earth ceramic feedstock expose margins to commodity swings and energy-intensive processing tariffs.
- Supply concentration in East Asian forging:China dominates seamless steel ring production, creating single-source vulnerability for European and North American precision grinders.
- Technical limitation in hybrid ceramic-steel interfaces:Differential thermal expansion coefficients constrain high-speed spindle applications below 50,000 RPM thresholds.
Strategic Opportunities
- Underpenetrated wind turbine offshore maintenance:Floating platform installations in North Sea and Baltic clusters demand corrosion-resistant bearing retrofits with 25-year service intervals.
- Regulatory tailwind from China dual carbon goals:MIIT energy efficiency mandates favor magnetic bearing adoption in compressed air systems across steel and cement plants.
- Technology convergence of additive manufacturing with topology optimization:3D-printed cage geometries reduce weight 15-30% for robotics and drone propulsion systems.
Industry Challenges
- Precision grinding skill scarcity:Raceway superfinishing and controlled clearance assembly require multi-year apprenticeship pipelines that industrial training programs struggle to fill.
- Certification timeline compression:ISO 9001 and AS9100 aerospace qualification cycles extend 18-24 months, delaying new product commercialization for automotive and aviation tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bearings Market |
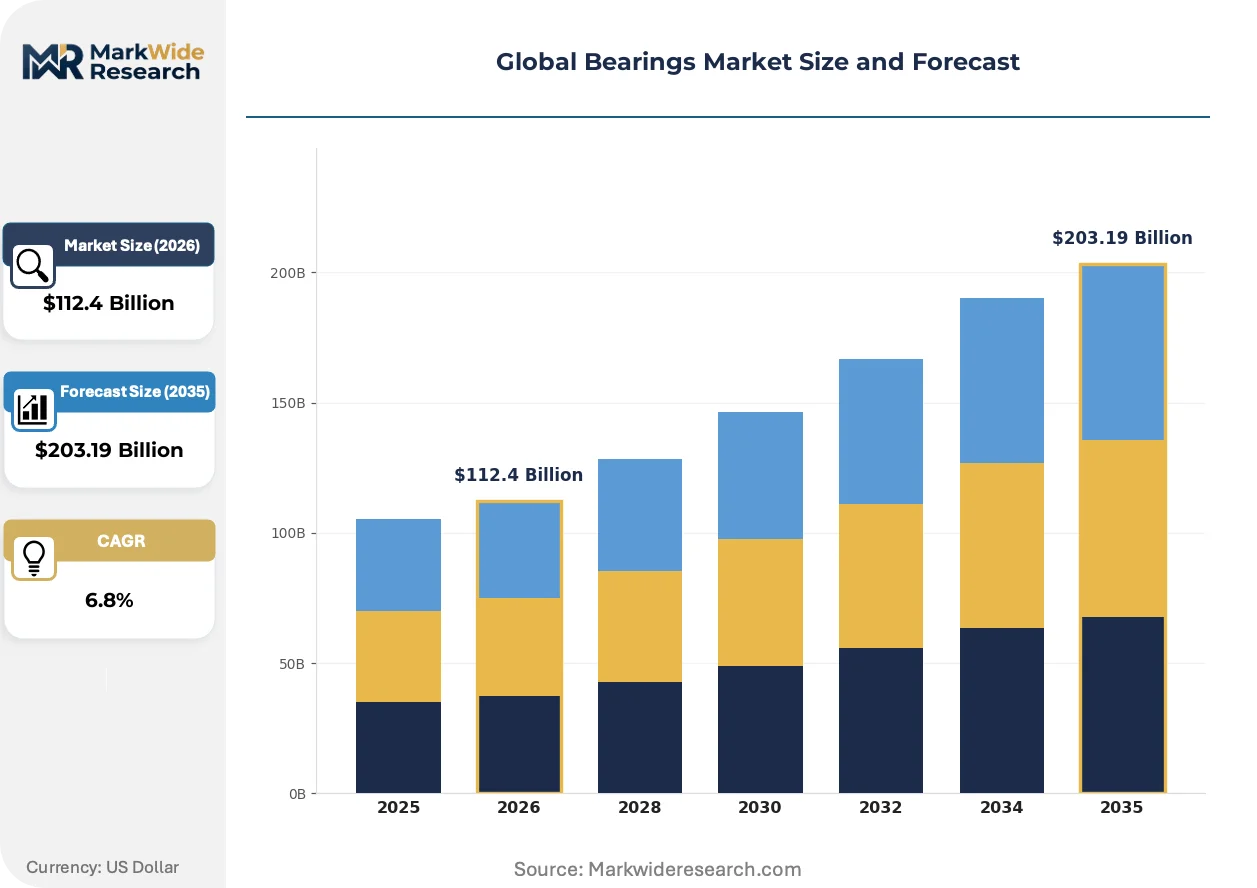
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Fluid Bearings, Magnetic Bearings Industry Vertical: Automotive, Aerospace, Construction, Manufacturing Material: Steel, Ceramic, Plastic, Composite Application: Motors, Gearboxes, Pumps, Compressors |
| Companies Covered | SKF, Schaeffler Group, NSK Ltd., NTN Corporation, Timken Company, JTEKT Corporation, MinebeaMitsumi Inc., Nachi-Fujikoshi Corp., RBC Bearings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bearings Market Emerging Trajectories
Solid lubrication technologies and AI-enabled condition monitoring are collapsing maintenance intervals while regulatory chemistry bans force material science reinvention across the value chain.
Hybrid ceramic ball bearings with silicon nitride rolling elements is converging with high-frequency inverter motor drives in semiconductor vacuum pumps and medical imaging equipment. Japanese and German machine tool builders specify these configurations for 40% speed advantage over conventional steel. The technology is converging with predictive analytics platforms to enable zero-unplanned-downtime guarantees in 24-hour continuous process industries.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) eliminate long-chain fluoropolymer greases from bearing lubrication formulations. ECHA enforcement timelines force reformulation toward ionic liquid and graphene-based alternatives by 2026. Aerospace and food processing sectors face the steepest compliance curves, with Swiss and Dutch certification bodies issuing accelerated approval pathways for PFAS-free bearing systems.
Aftermarket service unbundling separates hardware procurement from predictive maintenance subscriptions, compressing traditional distributor markups. Industrial buyers in German automotive supply chains now contract uptime guarantees directly with bearing manufacturers, bypassing regional distributors. This pattern replicates in South Korean shipbuilding and Brazilian mining equipment markets where total cost of ownership contracts displace unit-price negotiations.
Global Bearings Market Segmentation
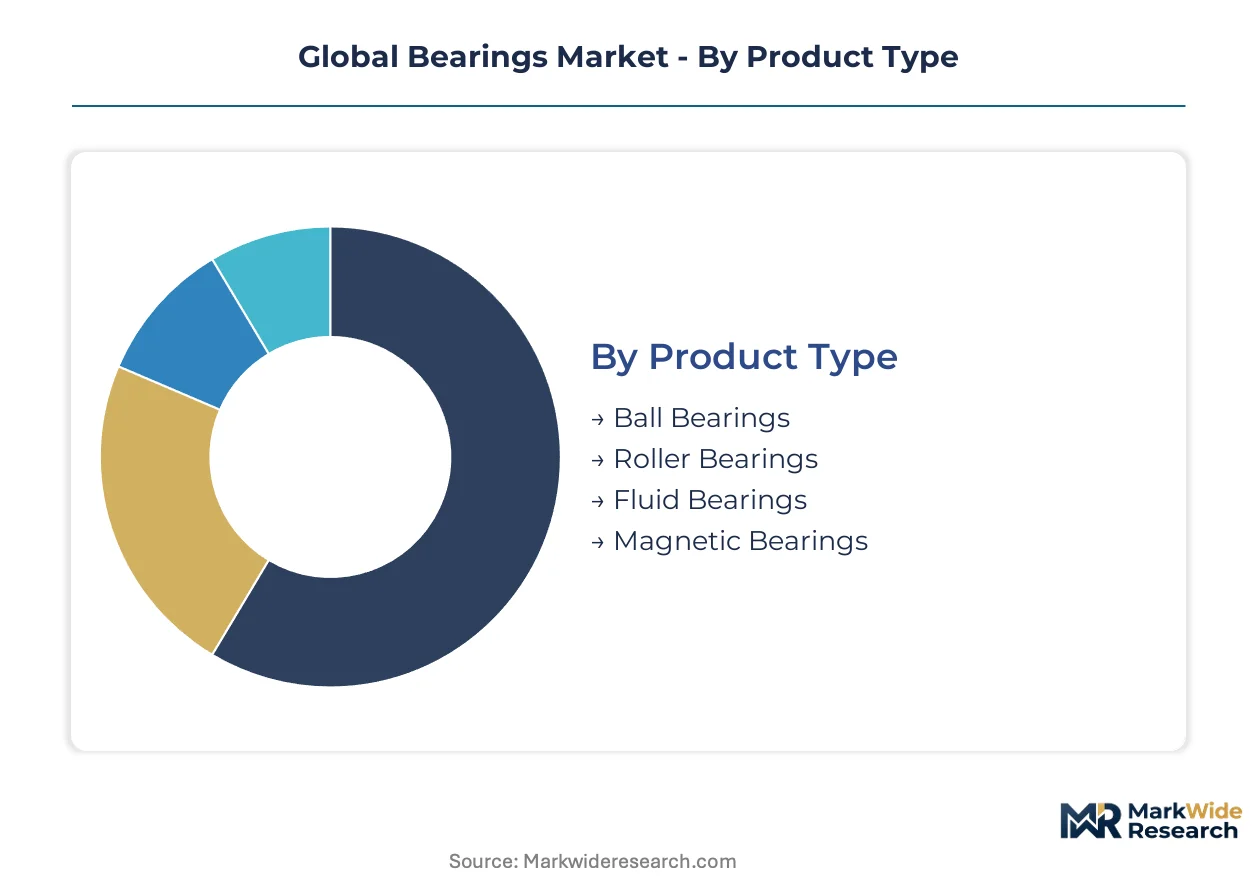
Bearing selection hinges on load geometry, thermal envelope, and lifecycle cost tradeoffs that vary sharply across equipment categories. Upgrade cycles in heavy industry and electrification mandates in automotive are reconfiguring segment priorities faster than historical replacement patterns.
Product Type:
Replacement cycles diverge dramatically between commodity steel configurations and precision ceramic systems with extended service intervals.
- Roller Bearings:Cylindrical and tapered configurations handle radial and combined loads through line contact geometry. Mining haul trucks in Western Australia and cement mills in Rajasthan drive demand for spherical roller variants that tolerate shaft misalignment under shock loading.
- Ball Bearings:Point-contact geometry enables higher rotational speeds with lower friction coefficients than roller equivalents. German machine tool spindles and Japanese semiconductor manufacturing equipment specify angular-contact ball bearings for positioning accuracy below five microns.
- Fluid Bearings:Hydrodynamic oil films eliminate metal-to-metal contact in high-speed turbomachinery. Power generation turbines in Texas and petrochemical compressors along the US Gulf Coast deploy these for vibration damping above ten thousand RPM.
- Magnetic Bearings:Electromagnetic levitation removes mechanical wear entirely from the rotating assembly. Chinese steel plants under MIIT energy efficiency mandates and Norwegian offshore gas compression platforms adopt these for twenty-five-year maintenance-free operation.
Volume placements concentrate in Roller Bearings; the faster expansion belongs to Magnetic Bearings.
Industry Vertical:
Margin structures separate regulated aerospace qualification cycles from automotive scale economics and construction aftermarket parts.
- Automotive:Powertrain electrification demands bearings rated for inverter-induced electrical pitting and reduced lubrication volumes. Battery electric vehicle production lines in Shanghai and Stuttgart specify ceramic hybrid configurations for motor speeds exceeding fifteen thousand RPM.
- Aerospace:AS9100 certification and FAA airworthiness directives govern every design change. Landing gear actuators and engine accessory drives in Toulouse and Seattle assembly plants use vacuum-melted steel with ultrasonic inspection protocols.
- Construction:Contaminated operating environments prioritize sealed units with relubrication intervals measured in operating hours rather than calendar time. Excavator final drives and crane slewing rings in São Paulo and Jakarta job sites consume tapered roller assemblies in high volumes.
- Manufacturing:General industrial machinery spans the widest specification range from precision ball screws to heavy-duty conveyor rollers. Food processing lines in the Netherlands and textile mills in Vietnam specify stainless steel or polymer variants for washdown compliance.
Revenue concentration sits with Automotive; Aerospace captures the steepest expansion trajectory.
Material:
Cost tiers separate commodity carbon steel from ceramic alternatives with five-to-ten-year payback periods through reduced downtime.
- Steel:Through-hardened chrome alloy and case-carburized grades dominate installed base economics. Wind turbine main shaft bearings in Denmark and railway axle boxes across India rely on vacuum-degassed steel cleanliness ratings per ISO 683-17.
- Ceramic:Silicon nitride rolling elements reduce density forty percent versus steel with superior thermal stability. Semiconductor vacuum pumps in Hsinchu and medical CT scanner gantries in Munich specify hybrid ceramic-steel configurations for speed and corrosion resistance.
- Plastic:Polyether ether ketone and polytetrafluoroethylene cages reduce weight and eliminate galvanic corrosion in marine environments. Fishing vessel winches and desalination plant pumps in Jeddah deploy polymer-lined bearings for seawater immersion.
- Composite:Fiber-reinforced polymer races enable magnetic transparency and electrical insulation. MRI machine gradient coils and particle accelerator beam lines in Geneva use composite structures to avoid eddy current heating.
Steel retains volume dominance; Ceramic is climbing the fastest on regulatory chemistry bans and electrification thermal loads.
Application:
Equipment duty cycles determine whether bearings fail through fatigue, contamination, or lubricant degradation.
- Motors:Electric motor bearings face electrical pitting from variable frequency drive switching frequencies. Industrial motor repair shops in Chicago and Milan report ceramic insulation coatings as standard above two hundred kilowatt ratings.
- Gearboxes:Combined radial and thrust loads from helical and bevel gear meshes demand paired bearing arrangements. Mining grinding mills in Chile and cement kilns in Vietnam use spherical roller configurations with split housings for maintenance access.
- Pumps:Cavitation and dry-running protection drive material selection in process industries. Chemical transfer pumps in Ludwigshafen and wastewater facilities in Sydney specify silicon carbide or ceramic variants for abrasive slurry duty.
- Compressors:Oil-free operation mandates magnetic or air-foil bearings in food and pharmaceutical gas systems. Air separation plants in Louisiana and hydrogen refueling stations in California deploy active magnetic bearings to eliminate hydrocarbon contamination risk.
Gearbox applications anchor current volume; Compressor configurations are gaining share fastest on hydrogen infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of seamless steel rings while Germany and the United States absorb premium precision output. This production-consumption split concentrates forging capacity in East Asia and finishing expertise in Western Europe and North America.
China
MIIT energy efficiency mandates accelerate magnetic bearing adoption in steel and cement plants. Dual carbon goals force compressed air system upgrades across industrial clusters. The Yangtze River Delta hosts precision grinding facilities serving semiconductor and automotive export demand.
Germany
Machine tool builders specify angular-contact ball bearings for sub-five-micron positioning accuracy. REACH Annex XVII PFAS restrictions drive lubricant reformulation toward ionic liquid alternatives. Stuttgart and Munich industrial corridors concentrate sensor-integrated bearing R&D for predictive maintenance platforms.
United States
Power generation turbines along the Texas Gulf Coast deploy hydrodynamic fluid bearings for vibration damping above ten thousand RPM. EPA emissions frameworks shape material selection for heavy-industry applications. Chicago motor repair shops standardize ceramic insulation coatings above two hundred kilowatt ratings.
India
PLI scheme production-linked incentives attract precision component capacity to Tamil Nadu and Gujarat corridors. Railway axle box demand across the subcontinent relies on vacuum-degassed steel cleanliness ratings. Mining haul trucks in Rajasthan and cement mills nationwide consume spherical roller variants for shock load tolerance.
Japan
Semiconductor manufacturing equipment builders specify hybrid ceramic-steel configurations for forty percent speed advantages. METI industrial standards govern bearing qualification for robotics and medical imaging exports. Nagoya and Osaka precision clusters supply high-frequency inverter motor drive integrations.
Global Bearings Market Vendor Landscape
Top-tier vendors anchor premium precision and digital diagnostics, while mid-scale specialists occupy regional fabrication and aftermarket service tiers. The structure consolidates around technology leaders with sensor-integrated platforms and fragments across commodity steel ring producers. Two strategic archetypes dominate: integrated manufacturers controlling seamless forging through finishing, and digital-native suppliers monetizing predictive maintenance subscriptions. Competitive moves center on capacity expansion in Indian industrial corridors and strategic partnerships for PFAS-free lubricant certification pathways.
Within the premium-tier vector, SKF exemplifies the predictive maintenance subscription model, while Schaeffler Group occupies a position in sensor-integrated system development. Timken Company represents high-performance tapered roller specialization for heavy-industry applications. These three anchors demonstrate how geographic origin—Swedish, German, and American respectively—maps to distinct competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| SKF |
| Schaeffler Group |
| NSK Ltd. |
| NTN Corporation |
| Timken Company |
| JTEKT Corporation |
| MinebeaMitsumi Inc. |
| Nachi-Fujikoshi Corp. |
| RBC Bearings |
| Others |
Supply Flow & Price Mechanics
German automotive tier-one procurement teams dominate premium bearing negotiations through long-term total cost of ownership contracts that displace unit-price benchmarking. This buyer concentration forces suppliers toward subscription-based uptime guarantees rather than transactional component sales.
Pricing Analysis
Margin tightening in standard-grade steel bearings reflects vacuum-degassed alloy cost volatility and energy-intensive processing tariffs. Three-tier pricing structure across premium ceramic hybrids, certified aerospace grades, and commodity roller configurations separates AS9100-qualified suppliers from regional forging operations. Cost compression accelerates in automotive motor bearings as inverter-induced electrical pitting demands ceramic insulation coatings above two hundred kilowatt ratings. Construction equipment buyers exhibit highest price sensitivity due to contaminated operating environments driving sealed-unit specifications with shortened relubrication intervals.
Supply Chain Analysis
Freight cost differentials between East Asian forging hubs and European precision grinding centers favor localized finishing investments in Tamil Nadu and Gujarat industrial corridors. Seamless steel ring production concentrates in China, Germany, and India, while raceway superfinishing expertise clusters in Sweden, Germany, and Japan. Raw material dependencies span vacuum-degassed bearing steel, silicon nitride ceramic feedstock, and rare-earth magnetic alloys for active bearing systems. Single-source vulnerability in Chinese seamless ring forging exposes European and North American grinders to tariff exposure and logistics chokepoints at Rotterdam and Hamburg port clusters. Distribution runs through authorized industrial distributors with certified relubrication service capabilities, though direct manufacturer contracting now captures twenty-five-year service interval agreements in wind turbine offshore maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic bearing systems are displacing conventional hydrodynamic and rolling-element configurations in compressed air and turbomachinery applications, compressing legacy product lifecycles and rewiring supplier qualification protocols.
For Market Incumbents: Hedge ceramic hybrid margin pools against steel commodity volatility by deepening backward integration into silicon nitride powder synthesis and vacuum-degassed steel cleanliness protocols. Anchor recurring revenue through predictive maintenance subscriptions that bundle sensor-integrated bearing hardware with vibration analytics platforms, defending against distributor disintermediation in German automotive supply chains. For New Entrants and Emerging Players: REACH Annex XVII PFAS restrictions in Europe open a window for ionic liquid and graphene-based lubricant formulations that bypass long-chain fluoropolymer chemistry bans. Target semiconductor vacuum pump retrofits in Hsinchu and Munich precision clusters where thermal stability commands premium positioning. Pursue Swiss and Dutch certification body partnerships for accelerated PFAS-free bearing system approvals. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision grinding specialists with captive raceway superfinishing capabilities in Indian PLI scheme corridors. Long-term viability hinges on sensor-integrated platform monetization rather than unit sales exposure. Monitor MIIT energy efficiency mandate enforcement in Chinese steel and cement plants as magnetic bearing adoption inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | SKF and Schaeffler anchor recurring revenue through digital diagnostics subscriptions that guarantee uptime. |
| PFAS-Free Lubricant Certification Pathway | ECHA enforcement timelines force reformulation partnerships with Swiss and Dutch certification bodies by 2026. |
| Indian Precision Grinding Capacity Expansion | PLI scheme incentives attract seamless ring forging and raceway finishing investment to Tamil Nadu corridors. |
| Hybrid Ceramic-Steel R&D Intensification | Silicon nitride rolling elements capture forty percent speed advantages in Japanese semiconductor equipment. |
| Magnetic Bearing System Integration | MIIT mandates favor electromagnetic levitation adoption in Chinese steel plant compressed air systems. |
Methodological Framework
Multi-period observation of bearing replacement cycle compression, ceramic material substitution rates, and predictive maintenance subscription penetration anchored the trend analysis, supplemented by interviews with maintenance directors at mining and cement operations, OEM procurement teams in automotive powertrain divisions, aftermarket service heads at industrial distributors, and precision grinding facility managers. Secondary validation drew from customs trade data on vacuum-degassed steel imports, SEC filings of publicly traded bearing manufacturers, MIIT energy efficiency mandate documentation, and ECHA PFAS restriction enforcement timelines. Bottom-up segment sizing triangulated against top-down industrial machinery production forecasts.
The input-output matrix mapped roller bearing demand to mining haul truck fleet expansion, ball bearing specifications to machine tool spindle production, and magnetic bearing adoption to MIIT-mandated compressed air system upgrades. Segmentation dimensions spanned product type, material grade tier, end-use industry vertical, application duty cycle, and regional regulatory cluster. CAGRs derived from installed base turnover analysis and electrification-driven specification shifts across the projection horizon. Forecast inputs included inverter motor drive penetration in automotive powertrains and floating offshore wind turbine installation schedules in North Sea clusters.
The model assumes a particular technology adoption path for magnetic bearing systems in heavy industry; alternative pathways for active magnetic bearing cost reduction would alter the outlook for ceramic hybrid configurations. Forecasts reflect assumptions on PLI scheme execution in India, REACH enforcement consistency, and semiconductor capital expenditure cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Car Modification Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Bicycle Components Aftermarket Market