
 Bus and Coach Suspension Bearing Components Market | 2026-2036
Bus and Coach Suspension Bearing Components Market Size, Share, and Industry Trends Forecast 2026-2036
Bus and Coach Suspension Bearing Components Market Insights
EU Green Deal emission benchmarks is realigning the cost-of-entry calculus for suspension bearing suppliers serving European OEMs. Continental AG leverages its integrated chassis electronics portfolio to anchor premium bearing system contracts with German bus manufacturers. ZF Friedrichshafen sustains competitive positioning through in-house forging capacity for tapered roller bearing races. ThyssenKrupp specializes in ceramic-coated plain bearings that withstand corrosive road-salt environments across Nordic fleet operations.
Bus and coach suspension bearing components are precision-engineered rotational and sliding elements—typically fabricated from through-hardened alloy steel or sintered bronze composites with dimensional tolerances within ISO 492 Class 4—that transmit loads between axle assemblies and chassis frames while isolating road-induced vibration from passenger compartments. Roller bearings dominate OEM fitments for drive-axle and tag-axle positions due to their radial load capacity, while polymer-composite plain bearings are displacing bronze in air-suspension linkages where weight reduction and maintenance-free operation matter most. Ceramic hybrid configurations command margin premiums in high-frequency stop-start city transit duty cycles where thermal management and grease retention determine service intervals.
F-Gas Regulation refrigerant phase-downs indirectly pressure bus HVAC mass budgets, which in turn tightens suspension component weight allowances that bearing designers must satisfy. ECHA REACH substance restrictions on hexavalent chromium plating compel suppliers to validate alternative surface treatments for corrosion protection. NHTSA brake stability mandates in the US and China's GB standards for commercial vehicle ride quality both specify minimum damping coefficients that suspension bearing assemblies must preserve across their design life. Stakeholders should monitor how dual carbon goals in Beijing and Brussels converge on material carbon-intensity disclosure requirements that will reshape supplier qualification protocols.
Market Dynamics
EU Green Deal vehicle-weight reduction mandates are compressing design cycles for suspension bearing suppliers, forcing simultaneous material substitution toward polymer-composite architectures and precision-matched assembly tolerances that legacy steel-forging workflows cannot accommodate.
Growth Catalysts
- F-Gas Regulation refrigerant phase-downs:HVAC mass budgets on intercity coaches are tightening, redirecting engineering resources toward lighter suspension linkages that polymer-composite bearings enable without structural compromise.
- China's dual carbon goals:Municipal transit authorities in Beijing and Shanghai are specifying ceramic hybrid bearings for high-frequency stop-start duty cycles where thermal management extends service intervals.
- Air-suspension linkage upgrades:Fleet operators across Germany's commercial vehicle corridor are procuring maintenance-free polymer plain bearings that eliminate grease points and reduce curb weight.
Market Restraints
- Alloy steel input volatility:Through-hardened bearing race production remains exposed to nickel and molybdenum price swings that compress margin buffers for forged-component suppliers.
- ECHA REACH hexavalent chromium restrictions:Corrosion protection protocols must validate alternative surface treatments, extending qualification timelines for Nordic road-salt duty ratings.
- Ceramic ball supply concentration:Silicon nitride powder synthesis capacity clusters in Japanese and German specialty chemical corridors, creating single-source vulnerability for hybrid bearing assemblers.
Strategic Opportunities
- Indian intercity coach electrification:State transport undertakings are tendering for lightweight suspension modules where polymer-composite bearings reduce unsprung mass on battery-electric chassis.
- ISO 492 Class 4 precision convergence:Metrology investments are opening tier-one supply positions for bearing houses that can match tapered roller geometries to axle housing bores within four-micron tolerances.
- Aftermarket service unbundling:Independent fleet maintenance providers are sourcing direct-fit bearing cartridges bypassing OEM captive distribution, creating channel arbitrage for qualified component brands.
Industry Challenges
- Tribology specialist scarcity:Grease formulation chemists capable of optimizing ceramic-steel interface lubrication for variable temperature envelopes command premium compensation that mid-tier suppliers struggle to fund.
- Legacy chassis integration friction:Retrofit polymer bearings into air-suspension linkages originally designed for sintered bronze clearances demands custom shim packages that erode unit economics.
- GB standard ride-quality certification:China's commercial vehicle damping coefficient validation protocols require extended track testing that extends new product introduction calendars by two to three quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus and Coach Suspension Bearing Components Market |
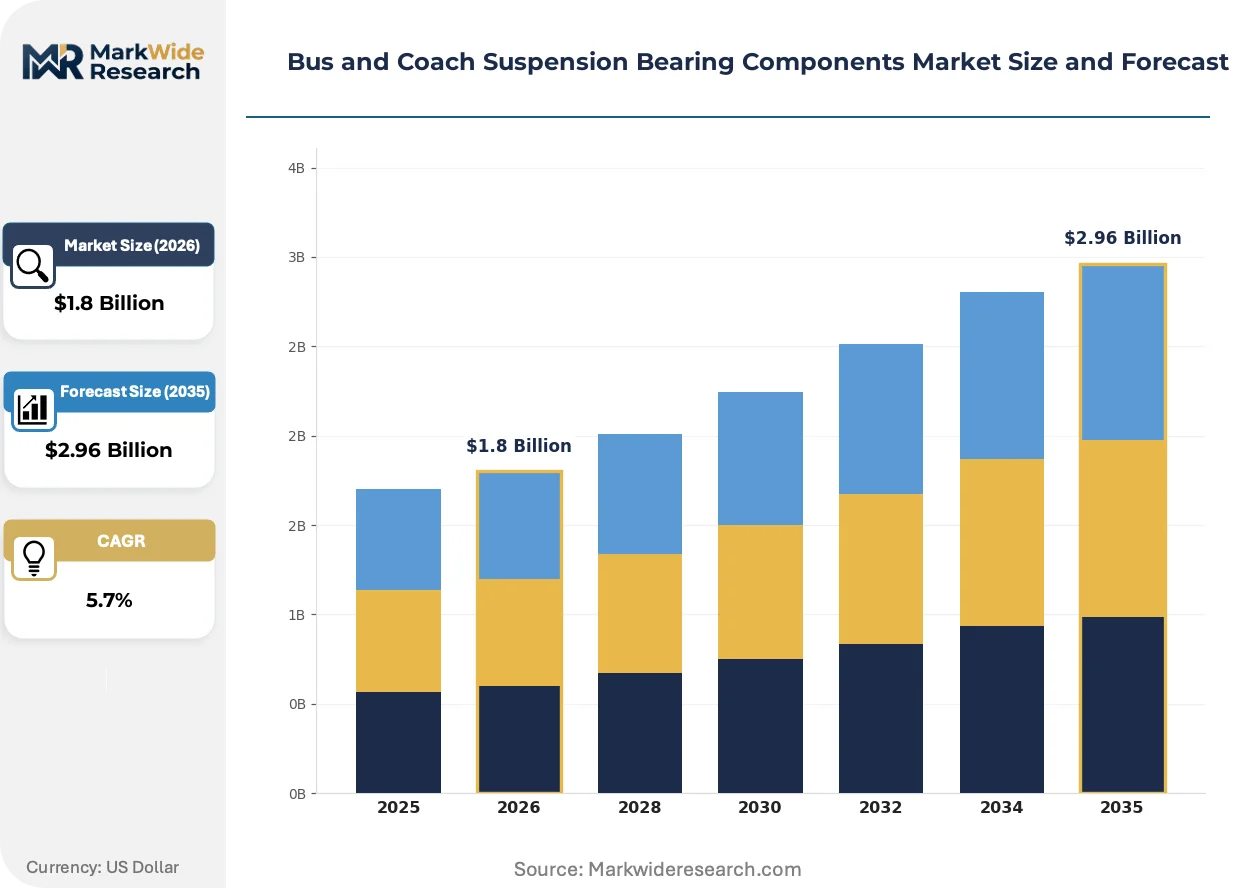
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Ball Bearings, Roller Bearings, Needle Bearings, Tapered Bearings, Plain Bearings Material: Steel, Bronze, Ceramic, Polymer, Composite Application: City Transit Vehicles, Intercity Coaches, Tourist Buses, School Buses, Shuttle Services End User: OEM Manufacturers, Fleet Operators, Aftermarket Suppliers, Maintenance Providers |
| Companies Covered | Continental AG, ZF Friedrichshafen, ThyssenKrupp, KYB Corporation, Hendrickson, Wabco Holdings, Hitachi Astemo, Tenneco, Firestone Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus and Coach Suspension Bearing Components Market Trends and Innovations
Active material substitution and regulatory compliance automation are compressing traditional bearing design paradigms, while procurement behavior shifts reward suppliers capable of delivering weight-optimized assemblies with embedded carbon-intensity documentation.
Polymer-composite plain bearings with PTFE-impregnated fiber matrices are integrating into air-suspension linkages as OEM chassis engineers prioritize unsprung mass reduction. German bus manufacturers are specifying these architectures for next-generation intercity platforms where every kilogram of bearing weight eliminated translates to payload or battery capacity recovery. The technology is integrating formerly separate functions—vibration isolation, corrosion immunity, and maintenance elimination—into unitized components that simplify assembly line logistics.
EU F-Gas Regulation phase-down schedules are forcing HVAC system redesigns that indirectly constrain suspension component mass budgets, compelling bearing designers to document polymer substitution pathways through ECHA REACH substance portfolios. The industrial consequence is accelerated validation of ceramic-coated plain bearings that withstand corrosive environments without hexavalent chromium plating. Nordic fleet operators are most affected, as road-salt exposure severity demands surface treatments that comply with substance restrictions while maintaining 800,000-kilometer design life.
Specification authority is migrating from OEM chassis divisions to fleet procurement departments that negotiate total-cost-of-ownership contracts including predictive maintenance telemetry. Tier-one bearing suppliers are responding by embedding RFID-enabled wear sensors in polymer-composite housings, displacing traditional calendar-based replacement schedules with condition-triggered service events. This behavioral shift is most visible across Germany's long-distance coach networks where on-road availability guarantees dominate supplier selection criteria.
Bus and Coach Suspension Bearing Components Market Segmentation
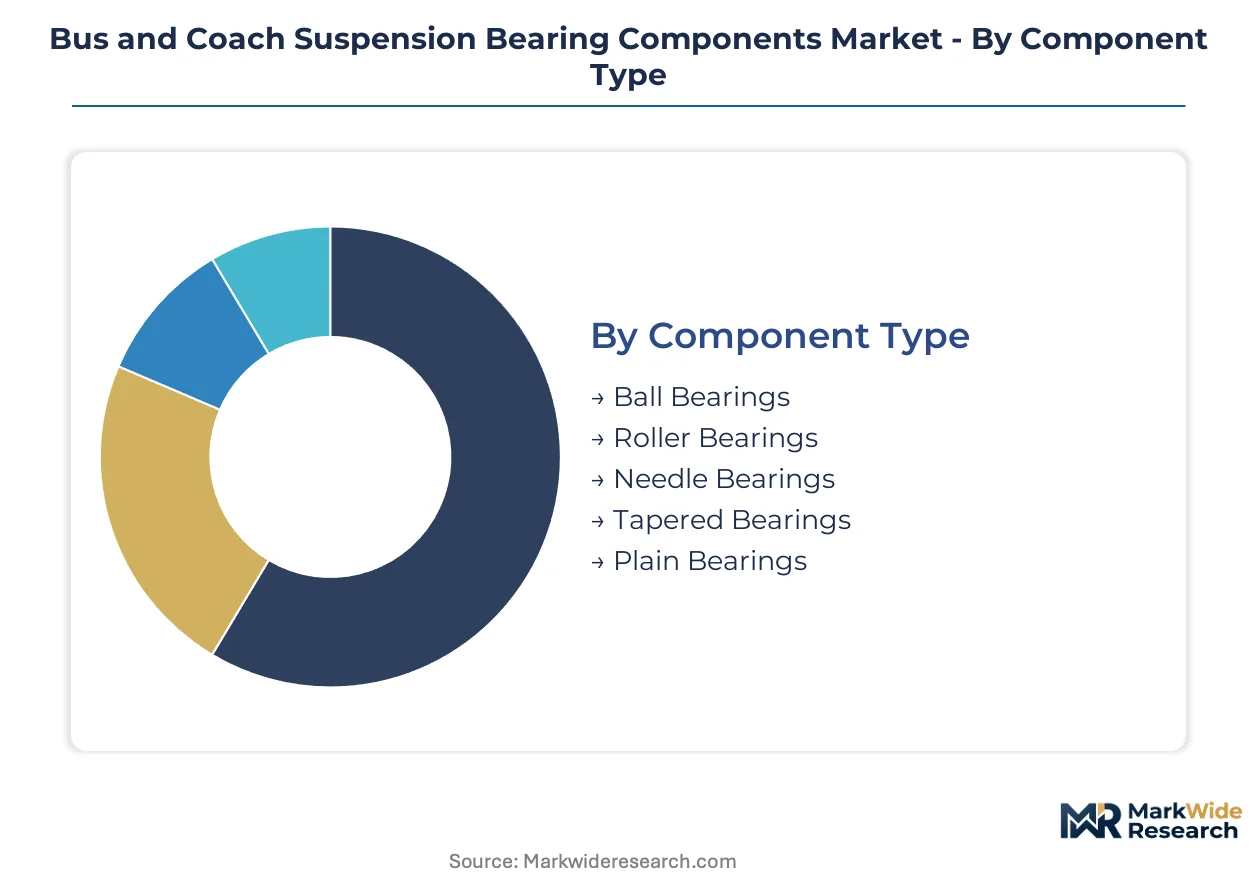
Bus and coach suspension bearing components fragment across multiple technical and commercial axes that determine procurement logic. Material chemistry, geometric configuration, and duty-cycle severity each create distinct value pools with incompatible supplier capabilities.
Component Type:
Roller geometries dominate OEM specifications where radial load capacity and ISO 492 precision tolerances determine axle assembly performance.
- Roller Bearings:Cylindrical and spherical variants handle radial loads exceeding 50 kN in drive-axle positions. German commercial vehicle manufacturers specify these for intercity coach tag-axle assemblies where 800,000-kilometer design life is mandatory.
- Tapered Bearings:Conical raceway geometries manage combined radial and thrust loads in steering knuckle applications. Fleet operators in Nordic road-salt environments prioritize ceramic-coated variants that withstand corrosive exposure without hexavalent chromium plating.
- Ball Bearings:Deep-groove configurations occupy lighter-duty linkage positions with moderate speed requirements.
- Needle Bearings:Compact radial envelopes suit space-constrained suspension arm pivots on low-floor city transit chassis.
- Plain Bearings:PTFE-impregnated polymer and sintered bronze variants eliminate grease points in maintenance-free air-suspension linkages.
Roller bearings lead on scale across OEM fitments; polymer-composite plain bearings lead on momentum as weight-reduction mandates intensify.
Material:
Cost-to-performance positioning separates commodity metallurgy from engineered ceramics and polymer matrices.
- Steel:Through-hardened alloy grades with nickel and molybdenum additions remain the baseline for forged bearing races. Input price volatility compresses margin buffers for suppliers without captive forging capacity.
- Polymer:PTFE-impregnated fiber matrices and PEEK composites reduce unsprung mass by 60-70% versus bronze equivalents. EU Green Deal vehicle-weight targets accelerate substitution in German bus manufacturer procurement specifications.
- Ceramic:Silicon nitride hybrid configurations command premium positioning in high-frequency stop-start duty cycles where thermal management extends service intervals. Powder synthesis capacity concentrates in Japanese and German specialty chemical corridors.
- Bronze:Sintered oil-impregnated grades retain share in legacy fleet maintenance where original equipment clearances must be preserved.
- Composite:Glass-fiber reinforced polymer housings integrate vibration isolation and corrosion immunity for next-generation chassis platforms.
Steel maintains volume dominance; polymer composites are climbing the fastest as electrification tightens mass budgets.
Application:
Duty-cycle severity and regulatory exposure create divergent specification requirements across vehicle categories.
- Intercity Coaches:Air-suspension systems with multi-axle tag configurations demand precision-matched tapered roller assemblies. China's GB standards for commercial vehicle ride quality specify minimum damping coefficients that bearing assemblies must preserve.
- City Transit Vehicles:High-frequency stop-start operation generates thermal loads that favor ceramic hybrid bearings with optimized grease retention. Beijing and Shanghai municipal authorities specify these for extended service interval targets.
- Tourist Buses:Premium ride-comfort mandates drive specification of low-noise spherical roller variants with enhanced sealing packages.
- School Buses:Cost-constrained procurement favors standard steel ball bearing configurations with calendar-based replacement schedules.
- Shuttle Services:High-utilization airport and corporate fleets prioritize predictive maintenance telemetry integration in bearing housings.
Intercity coaches anchor revenue concentration; city transit vehicles show steepest expansion trajectory as electrification accelerates.
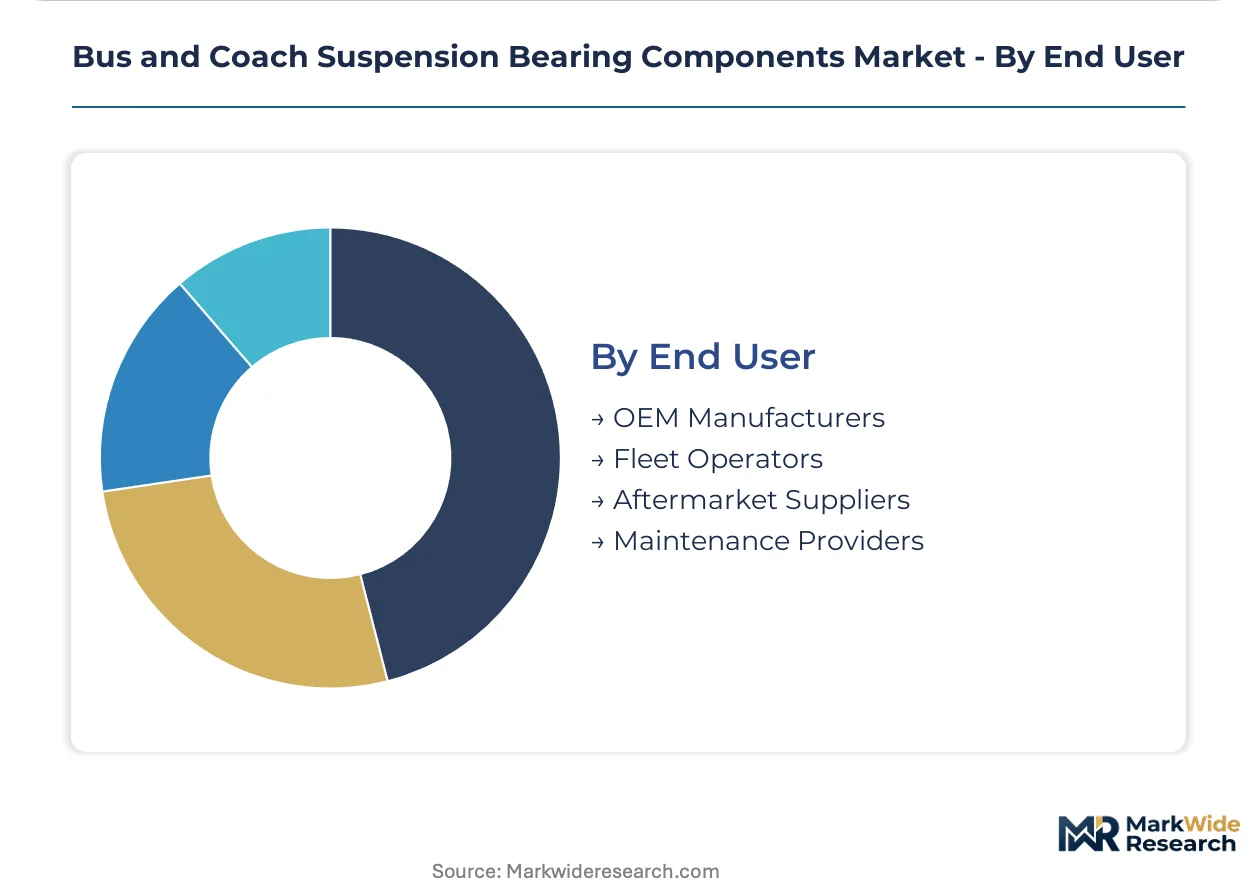
End User:
Specification authority migration from chassis engineers to fleet procurement departments reconfigures channel economics.
- OEM Manufacturers:German commercial vehicle manufacturers source ISO 492 Class 4 precision-matched assemblies through long-term framework agreements. Metrology investments determine tier-one supply position eligibility.
- Fleet Operators:Total-cost-of-ownership contracts now incorporate predictive maintenance telemetry and on-road availability guarantees. Germany's long-distance coach networks negotiate these terms directly with bearing suppliers.
- Aftermarket Suppliers:Independent distributors exploit channel arbitrage by sourcing direct-fit bearing cartridges that bypass OEM captive distribution networks.
- Maintenance Providers:Service unbundling creates demand for retrofit polymer bearing kits with custom shim packages for legacy bronze-linkage conversions.
OEMs retain specification control for new platforms; fleet operators are gaining share fastest as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tribology specialists and precision-forging workforces cluster in Germany's commercial vehicle corridor, China's Yangtze River Delta, and Japan's specialty chemical belt, anchoring regional supply capabilities.
Germany
Intercity coach OEMs in Bavaria and Baden-Württemberg procure ISO 492 Class 4 precision-matched bearing assemblies for next-generation chassis platforms. EU Green Deal vehicle-weight reduction targets accelerate polymer-composite substitution in air-suspension linkages. Stuttgart and Munich host integrated chassis electronics portfolios that anchor premium bearing system contracts.
China
Beijing and Shanghai municipal transit authorities specify ceramic hybrid bearings for high-frequency stop-start duty cycles where thermal management extends service intervals. GB standards for commercial vehicle ride quality mandate minimum damping coefficients across design life. Yangtze River Delta manufacturing clusters supply silicon nitride powder synthesis for hybrid bearing assemblers.
United States
NHTSA brake stability mandates drive specification of precision-tapered roller assemblies in heavy-duty transit applications. Fleet operators in the Midwest corridor negotiate total-cost-of-ownership contracts with predictive maintenance telemetry. Michigan and Ohio manufacturing bases source forged bearing races for domestic chassis platforms.
Japan
Specialty chemical corridors concentrate silicon nitride powder synthesis capacity for ceramic ball production. METI industrial standards govern precision tolerance protocols for export-oriented bearing manufacturers. Nagoya and Osaka industrial zones supply hybrid bearing components to Asian transit OEMs.
India
State transport undertakings tender for lightweight suspension modules where polymer-composite bearings reduce unsprung mass on battery-electric chassis. BIS certification requirements align with international ISO standards for commercial vehicle components. Maharashtra and Gujarat manufacturing clusters develop domestic forging capacity for tapered roller bearing races.
Bus and Coach Suspension Bearing Components Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated chassis system suppliers with captive bearing production, independent precision-forging houses serving multiple OEMs, and polymer-composite material specialists displacing legacy metallurgy. Dominant competitive moves include backward integration into ceramic powder synthesis and strategic partnerships for RFID-enabled predictive maintenance telemetry.
Within the integrated chassis systems tier, Continental AG and ZF Friedrichshafen exemplify diversified conglomerates leveraging electronics portfolios to anchor premium contracts. ThyssenKrupp occupies a position among specialty surface treatment providers serving corrosive-environment duty cycles. KYB Corporation represents the Asia-based precision component archetype with manufacturing footprints across multiple transit markets.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen |
| ThyssenKrupp |
| KYB Corporation |
| Hendrickson |
| Wabco Holdings |
| Hitachi Astemo |
| Tenneco |
| Firestone Industrial Products |
| Others |
Pricing and Supply Chain Analysis
Tribology specialists in Germany's precision-forging corridor command premium compensation that widens spreads between ISO 492 Class 4 certified assemblies and commodity-grade alternatives. Labor-cost differentials between German metrology houses and emerging forging clusters in India compress margin buffers for mid-tier suppliers unable to automate quality validation.
Pricing Analysis
Bundled predictive-maintenance telemetry contracts versus unbundled component-only procurement splits the market into divergent value-capture models. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-hybrid bearing systems with embedded RFID sensors from standard steel roller configurations and basic bronze plain bearings. Price differentiation hinges on ISO 492 precision certification and after-sales service bundling. Cost compression in the standard tier is intensifying because alloy steel input volatility erodes forging-house margins. Fleet procurement departments exhibit lowest price sensitivity for premium tier assemblies with availability guarantees, while aftermarket distributors show highest sensitivity for direct-fit cartridges.
Supply Chain Analysis
Silicon nitride powder synthesis rests on Japanese and German specialty chemical producers, creating single-source vulnerability for ceramic ball production. Raw material flows draw from nickel and molybdenum mining corridors in Indonesia and Chile for alloy steel races, PTFE resin from Belgian fluoropolymer specialists, and silicon nitride precursor chemicals from Nagoya industrial zones. Supply chain risk centers on ceramic ball supply concentration that exposes hybrid bearing assemblers to allocation constraints. Distribution runs through OEM captive networks for new platform fitments and independent aftermarket channels for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal vehicle-weight mandates and ECHA REACH substance restrictions continuously reshape procurement specifications and supplier qualification thresholds.
For Market Incumbents: Cement tier-one supply positions by deepening backward integration into ceramic powder synthesis and securing captive silicon nitride sourcing from Japanese specialty chemical corridors. Defend against polymer-composite displacement threats by accelerating validation of maintenance-free bearing architectures that eliminate grease points. Priority lever: metrology investments that achieve four-micron taper tolerance matching for German OEM framework agreements.
For New Entrants and Emerging Players: ECHA REACH hexavalent chromium restrictions in Europe open a window for ceramic-coated plain bearing specialists to capture Nordic road-salt duty ratings previously served by legacy plating technologies. Target Indian intercity coach electrification tenders where state transport undertakings specify lightweight suspension modules with polymer-composite bearings. Go-to-market angle: direct-fit retrofit kits with custom shim packages for bronze-linkage conversions.
For Investors and Strategic Acquirers: Integrated chassis system suppliers are the most active acquirer in this space, seeking precision-forging capabilities and polymer-composite material expertise to complete portfolio coverage. Long-term viability favors targets with dual metallurgy-polymer competency and established OEM qualification pathways. Signal to watch: fleet procurement centralization accelerating total-cost-of-ownership contract migration from OEM chassis divisions to operator procurement departments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | Secures silicon nitride supply from Japanese specialty chemical corridors against allocation risk. |
| RFID-Enabled Predictive Maintenance Telemetry | Enables condition-triggered service events for Germany's long-distance coach networks. |
| Polymer-Composite Material Validation | Addresses EU Green Deal weight targets for German bus manufacturer air-suspension linkages. |
| ISO 492 Class 4 Metrology Investment | Opens tier-one supply positions with Bavaria and Baden-Württemberg commercial vehicle OEMs. |
| Alternative Surface Treatment Certification | Validates corrosion protection for Nordic road-salt duty ratings under ECHA REACH restrictions. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, fleet maintenance directors, and aftermarket distribution channel heads grounded qualitative assessment in operational reality. Secondary validation drew from vehicle production databases, customs and trade flow records for bearing component imports, SEC 10-K filings of diversified chassis suppliers, and EU regulatory filings documenting ECHA REACH substance restrictions. Bottom-up and top-down triangulation reconciled unit-level procurement patterns with aggregate market sizing across component type, material chemistry, and application segments.
Bottom-up modeling anchored volume estimates in OEM platform production schedules and fleet replacement cycle analysis, while top-down cross-checks validated against aggregate commercial vehicle manufacturing data across the analysis window. Segmentation dimensions included roller geometry configuration, material chemistry tier, duty-cycle severity classification, and end-user procurement authority. CAGRs were derived from regression analysis of historical procurement trends and regulatory mandate implementation timelines. Industry-specific inputs incorporated F-Gas Regulation HVAC mass budget constraints and GB standard ride-quality damping coefficient requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alloy steel price volatility spikes or ceramic powder supply disruptions. Forecasts reflect assumptions regarding regulatory implementation schedules, OEM platform launch cadences, and fleet electrification adoption curves. A small set of triggers warrants ongoing watch: ECHA substance restriction expansion, Chinese dual carbon goal acceleration, and Nordic fleet procurement centralization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Bicycle Frames Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Engine Components Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Sideloaders Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Latin America Automotive Connectors Market