
 Italy Automotive Glass Fiber Composites Market | 2026-2036
Italy Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Glass Fiber Composites Market Foresight
Buyer concentration among Italian OEMs and Tier 1 suppliers is pivoting toward integrated composite module sourcing rather than discrete component procurement. Owens Corning leverages its European glass fiber supply network to anchor thermoplastic composite deliveries to Stellantis-related manufacturing sites. SGL Carbon specializes in carbon-glass hybrid solutions that compete for structural battery enclosure contracts with domestic EV startups. SAERTEX GmbH & Co.KG sustains technical leadership through multiaxial fabric architectures optimized for Italian automotive RTM lines.
Automotive glass fiber composites combine woven or chopped E-glass reinforcement with thermoset or thermoplastic matrices to achieve specific strength-to-density ratios exceeding steel by mass. Typical formulations employ epoxy, polyester, or polypropylene matrices with fiber volume fractions of 30-60 percent, processed through vacuum infusion or resin transfer molding to produce Class A exterior panels and load-bearing structural members. Molded Parts command the largest value share among product categories due to integration complexity in bumper beams and underbody shields. Exterior Components represent the fastest-growing application dimension as Italian OEMs pursue aerodynamic efficiency targets through integrated spoiler and diffuser designs. Prepreg technology occupies premium positioning among process segments where batch consistency and void-free laminates justify higher unit economics.
Italy's Ministry of Enterprise applies EU Green Deal automotive CO2 benchmarks through national vehicle registration incentives that directly reward lightweight material content. The country's adoption of REACH chemical compliance and CE marking protocols for structural automotive components shapes material qualification timelines and supplier certification requirements. EMA-aligned safety standards for passenger compartment integrity influence glass fiber composite specification in A-pillar and roof reinforcement applications. Stakeholders must monitor evolving EU End-of-Life Vehicle Directive recyclability mandates that will determine acceptable resin systems and fiber recovery pathways for next-generation Italian automotive platforms.
Market Dynamics
Italy's National Recovery and Resilience Plan is redirecting procurement flows toward low-carbon composite systems, forcing Tier 1 suppliers to requalify their glass fiber supply chains around Piedmont and Lombardy EV platforms.
Growth Catalysts
- EU Green Deal automotive CO2 benchmarks:Italy's Ministry of Enterprise applies these through national vehicle registration incentives that directly reward lightweight material content in new EV platforms.
- Structural battery enclosures:Domestic EV startups in Turin and Milan are specifying glass fiber composites for load-bearing battery protection modules, creating dedicated demand pull.
- Thermoplastic RTM processing:Northern Italian OEM supply clusters are upgrading resin transfer molding lines to handle faster-cycle thermoplastic composites, reducing per-part manufacturing time.
Market Restraints
- Petrochemical input volatility:Epoxy and polyester matrix resins face price instability tied to propylene and benzene feedstock fluctuations, compressing formulation margins for Italian compounders.
- Single-source glass fiber dependency:Owens Corning's European network anchors a disproportionate share of E-glass supply to Stellantis-related sites, creating concentration risk for alternative OEM programs.
- REACH chemical compliance timelines:ECHA substance authorization protocols extend material qualification cycles by 12-18 months, delaying new resin system adoption for structural automotive components.
Strategic Opportunities
- Carbon-glass hybrid architectures:SGL Carbon's specialty solutions are competing for structural battery enclosure contracts, opening premium positioning above commodity glass fiber formulations.
- Southern Italian supplier development:Campania and Apulia manufacturing zones remain underpenetrated for automotive composite conversion, offering greenfield site advantages for new RTM capacity.
- EU End-of-Life Vehicle Directive recyclability mandates:Evolving fiber recovery pathway requirements will favor Italian compounders with established pyrolysis or solvolysis capabilities for next-generation resin systems.
Industry Challenges
- Multiaxial fabric processing expertise:SAERTEX-optimized architectures require specialized technician training that Italian technical institutes have not scaled to match RTM line expansion rates.
- EMA-aligned passenger compartment safety certification:A-pillar and roof reinforcement applications demand extended crash-test validation cycles that compress program launch windows.
- Legacy steel-to-composite design integration:Italian OEM engineering teams face workflow friction when adapting existing CAD-CAM pipelines for anisotropic glass fiber laminate specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Glass Fiber Composites Market |
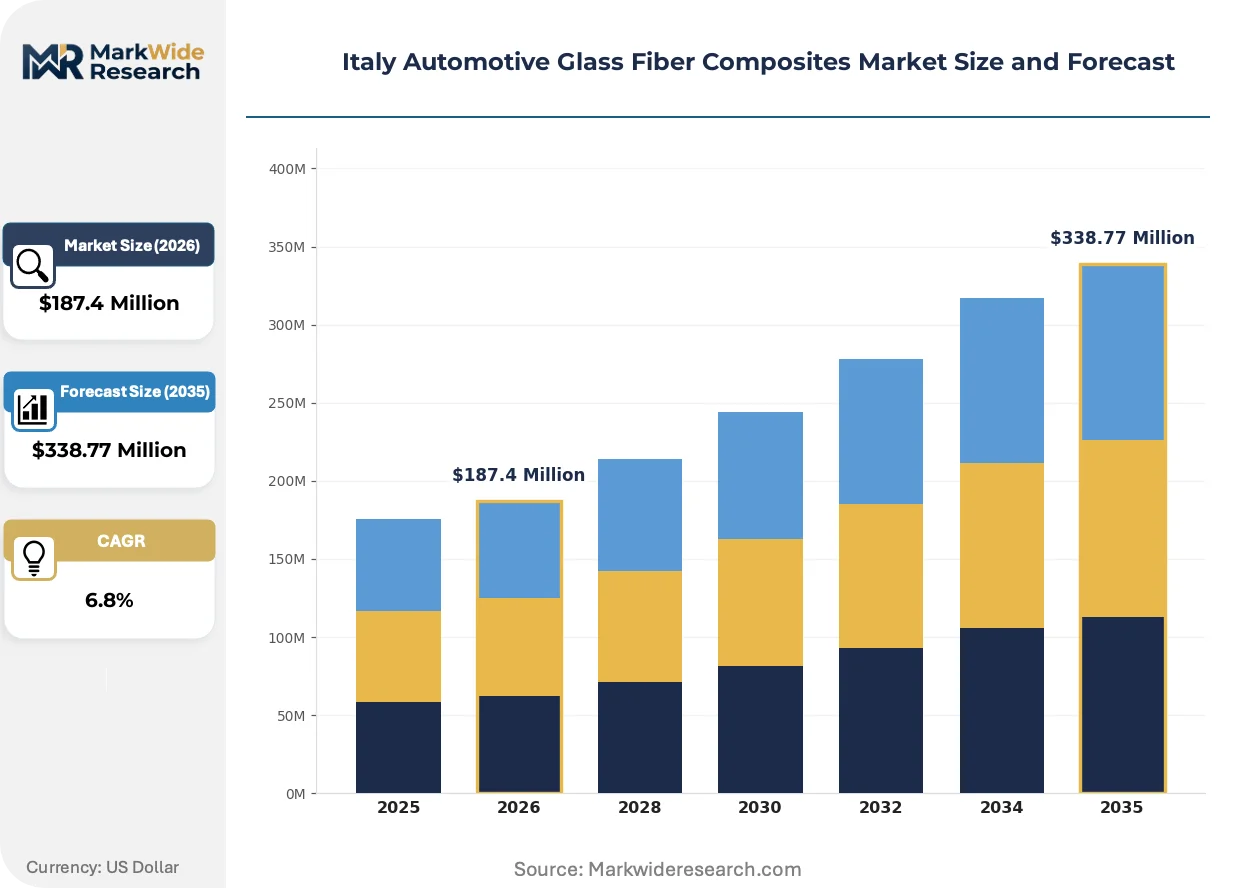
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Sheets, Molded Parts, Fabricated Components, Laminates Application: Interior Panels, Exterior Components, Structural Parts, Performance Enhancements End User: Automobile Manufacturers, Tier 1 Suppliers, Aftermarket Providers, OEMs Technology: Vacuum Infusion, RTM, Hand Lay-Up, Prepreg |
| Companies Covered | 3B (Braj Binani Group), Owens Corning, Solvay Group, Veplas Group, SAERTEX GmbH & Co.KG, SGL Carbon, LANXESS, Saint-Gobain, PPG Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Glass Fiber Composites Market Shifts & Advancements
Material-process convergence is compressing development cycles for Italian automotive platforms. Three distinct vectors are restructuring how glass fiber composites penetrate vehicle architectures.
Thermoplastic polypropylene matrices with 40-50 percent fiber volume fractions are rewriting the cost-performance calculus for underbody shields and bumper beams. Stellantis-related manufacturing sites in Turin are adopting these formulations at accelerated rates, displacing thermoset epoxies in non-Class A structural applications where cycle time trumps surface finish requirements.
REACH chemical compliance protocols from ECHA are forcing reformulation of legacy polyester systems ahead of substance restriction deadlines. Italian compounders serving the automotive sector are pivoting toward bio-based epoxy alternatives, with Piedmont-based suppliers investing in qualification labs to maintain CE marking continuity for structural components.
Integrated module sourcing contracts are consolidating procurement decisions at the Tier 1 level rather than the discrete component tier. Italian OEM engineering departments are ceding specification authority to Magna and Bosch automotive divisions, which now dictate fiber architecture and resin selection for complete bumper-to-rail assemblies rather than individual laminate sheets.
Italy Automotive Glass Fiber Composites Market Segmentation
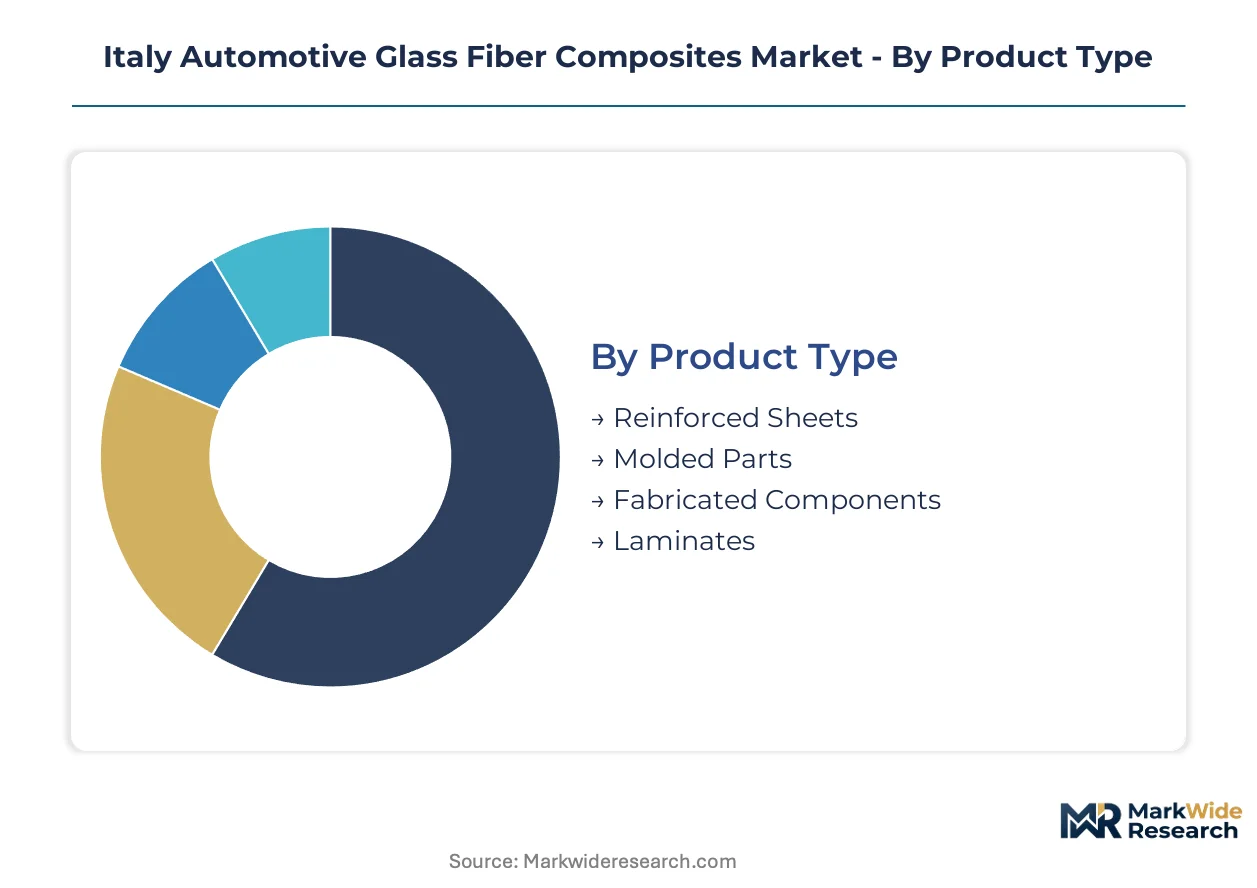
Glass fiber composite specifications diverge sharply across Italian automotive platforms based on load-bearing requirements and surface finish demands. Procurement patterns in Piedmont and Lombardy clusters reveal distinct purchasing logic for structural versus aesthetic applications.
Product Type:
Volume production concentrates in commodity-grade formats serving high-throughput RTM lines, while premium positioning attaches to specialized laminates qualifying for Class A surfaces.
- Reinforced Sheets:Continuous fiber mats impregnated with thermoset or thermoplastic binders serve as feedstock for compression-molded interior panels. Demand clusters around Tier 1 suppliers serving Stellantis-related manufacturing sites in Turin where batch-to-batch consistency governs supplier selection.
- Molded Parts:Complex geometries integrating ribs, bosses, and attachment features dominate bumper beam and underbody shield production. Integration complexity commands premium positioning as Italian OEMs outsource complete module assembly rather than discrete laminate procurement.
- Fabricated Components:Post-molded assemblies combining metallic inserts with composite substrates address hybrid joining requirements.
- Laminates:Multi-ply consolidated sheets target structural battery enclosures and load-bearing floor pans.
Mature deployment sits with Molded Parts. Newer deployment is concentrated in Laminates.
Application:
Functional requirements separate visible surfaces demanding paintability from hidden structural members prioritizing specific stiffness.
- Interior Panels:Door trim, headliners, and dashboard carriers employ low-density glass mat thermoplastic formulations. Piedmont-based compounders supply these to Magna and Bosch automotive divisions for complete cockpit module integration.
- Exterior Components:Spoilers, diffusers, and fenders require UV-stable gel coats and Class A surface quality. Aerodynamic efficiency targets from EU CO2 benchmarks are accelerating specification of integrated composite exterior modules across Milan-area EV platforms.
- Structural Parts:A-pillars, roof reinforcements, and frame rails demand crash-certified laminate architectures.
- Performance Enhancements:Lightweighting inserts for unsprung mass reduction target niche motorsport derivatives.
Established penetration characterizes Interior Panels. Steepest expansion trajectory belongs to Exterior Components.
End User:
Procurement authority is migrating upstream as integrated module contracts consolidate specification decisions.
- Automobile Manufacturers:Stellantis, Ferrari, and Lamborghini retain direct sourcing for visible carbon-glass hybrid body panels where brand differentiation justifies premium resin systems.
- Tier 1 Suppliers:Magna, Bosch, and Marelli now dictate fiber architecture and resin selection for complete bumper-to-rail assemblies. Northern Italian OEM supply clusters are redirecting procurement flows toward these consolidated supplier relationships under National Recovery and Resilience Plan incentives.
- Aftermarket Providers:Collision repair and performance upgrade channels serve aging vehicle parc.
- OEMs:Domestic EV startups in Turin and Milan specify glass fiber composites for load-bearing battery protection modules, creating dedicated demand pull outside traditional supply hierarchies.
Concentrated purchasing power rests with Tier 1 Suppliers. Emerging demand generation is shifting toward OEMs.
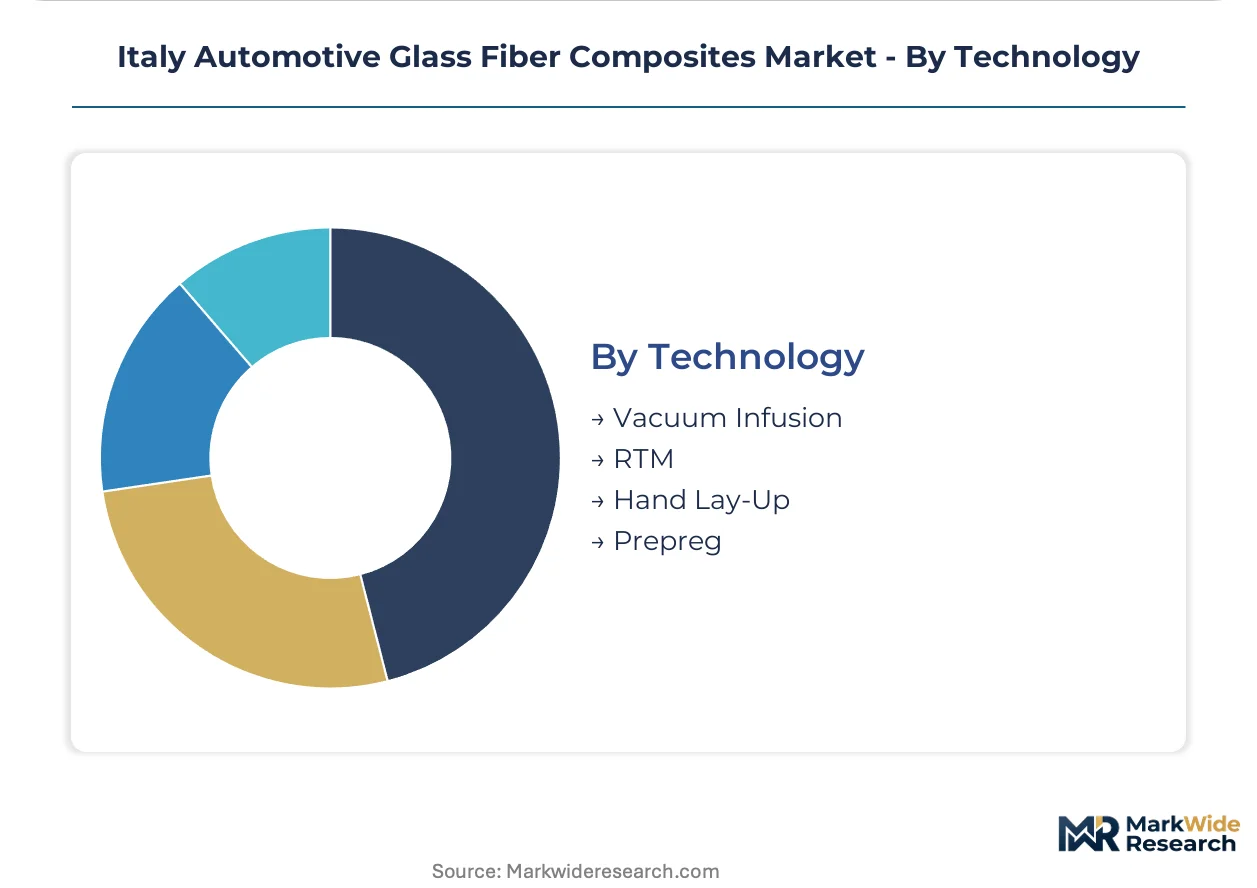
Technology:
Cycle time economics and void-free quality requirements partition process selection between high-volume structural and premium surface applications.
- Vacuum Infusion:Large-area laminates for wind deflectors and roof modules benefit from consistent fiber wet-out without press capital investment. Campania and Apulia manufacturing zones are evaluating this lower-barrier entry point for greenfield composite conversion capacity.
- RTM:Closed-mold resin transfer molding dominates bumper beam and underbody shield production across northern Italian OEM supply clusters. Thermoplastic-compatible RTM variants are compressing cycle times to match metal stamping economics.
- Hand Lay-Up:Low-volume prototyping and motorsport applications retain manual placement for complex curvature realization.
- Prepreg:Refrigerated B-stage resins with controlled tack enable void-free laminates for structural battery enclosures. Batch consistency and aerospace-derived quality protocols justify higher unit economics in premium positioning segments.
Process maturity anchors RTM deployment. Technology transition is accelerating toward Vacuum Infusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive glass fiber composites concentrates in northern Italian industrial clusters, with procurement authority migrating toward integrated module suppliers serving EV platforms in Turin and Milan.
Piedmont
Stellantis-related manufacturing sites in Turin specify thermoplastic composite formulations for bumper beams and underbody shields. Italy's National Recovery and Resilience Plan channels incentives toward low-carbon material systems in this region. The Turin automotive cluster is upgrading RTM lines to handle faster-cycle thermoplastic processing, compressing per-part manufacturing time for structural modules.
Lombardy
Domestic EV startups in Milan are creating dedicated demand pull for glass fiber composites in load-bearing battery protection modules. REACH chemical compliance protocols from ECHA extend material qualification cycles for compounders serving this market. The Milan-area EV platform ecosystem is accelerating specification of integrated composite exterior modules to meet aerodynamic efficiency targets under EU CO2 benchmarks.
Veneto
Tier 1 suppliers serving interior panel applications cluster around Magna and Bosch automotive divisions in this region. CE marking protocols for structural automotive components shape supplier certification requirements for Venetian compounders. Technical institutes in Veneto are scaling technician training programs to match RTM line expansion rates for multiaxial fabric processing.
Emilia-Romagna
Motorsport derivatives and performance enhancement applications sustain niche demand for hand lay-up composite processing in this region. EMA-aligned safety standards for passenger compartment integrity influence glass fiber composite specification for A-pillar applications. The Modena-Maranello corridor retains specialized demand for carbon-glass hybrid solutions in visible body panel applications.
Campania and Apulia
These southern zones remain underpenetrated for automotive composite conversion, offering greenfield site advantages for new vacuum infusion capacity. EU End-of-Life Vehicle Directive recyclability mandates will favor compounders with established fiber recovery capabilities in these regions. Manufacturing zones in Campania and Apulia are evaluating lower-barrier entry points for composite conversion to diversify beyond traditional supply hierarchies.
Italy Automotive Glass Fiber Composites Market Competitive Landscape
European producers anchor one tier; North American material specialists hold supply network positions across northern Italian OEM clusters. The vendor base organizes around three strategic archetypes: integrated fiber-to-composite suppliers, specialized fabric architecture developers, and resin system compounders. Consolidation pressure is concentrating procurement decisions at the Tier 1 level. Dominant competitive moves include backward integration into fiber supply and geographic co-location with Stellantis-related manufacturing sites.
Among European-based suppliers, Owens Corning, SAERTEX GmbH & Co.KG, and SGL Carbon occupy distinct positioning vectors. Owens Corning exemplifies the integrated fiber-to-composite archetype through its European supply network anchoring thermoplastic deliveries. SAERTEX GmbH & Co.KG represents specialized fabric architecture development, with multiaxial constructions optimized for Italian automotive RTM lines. SGL Carbon sits within the hybrid materials tier, competing for structural battery enclosure contracts with carbon-glass formulations that command premium positioning above commodity glass fiber systems.
| Leading Market Players |
|---|
| 3B (Braj Binani Group) |
| Owens Corning |
| Solvay Group |
| Veplas Group |
| SAERTEX GmbH & Co.KG |
| SGL Carbon |
| LANXESS |
| Saint-Gobain |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Tier 1 supplier consolidation around Stellantis-related manufacturing sites in Turin anchors contract-based long-term offtake pricing for thermoplastic composite modules, compressing margin buffers for compounders serving smaller domestic EV programs.
Pricing Analysis
High-volume bumper beam and underbody shield contracts run on fixed-price multi-year agreements, while low-volume Class A exterior modules retain project-based quoting with customization premiums. Price differentiation hinges on CE marking tier and fiber volume fraction certification, with REACH-compliant bio-based epoxy formulations commanding 15-20 percent premiums over legacy polyester systems. Cost compression in commodity thermoplastic grades is intensifying because of propylene feedstock volatility, squeezing compounder margins most acutely in standard-grade reinforced sheet supply to interior panel producers. Aftermarket collision repair channels exhibit highest price sensitivity, whereas Ferrari and Lamborghini direct procurement shows lowest elasticity for carbon-glass hybrid body panels.
Supply Chain Analysis
Freight costs from Owens Corning's European network to Piedmont RTM lines add 8-12 percent landed cost premiums versus domestic Italian compounder supply, incentivizing geographic co-location with Stellantis manufacturing sites. E-glass fiber supply draws from Belgium, Germany, and the Netherlands, while epoxy and polyester matrix resins rest on petrochemical feedstocks from Rotterdam and Antwerp refining clusters. Single-source vulnerability concentrates in Owens Corning's disproportionate share of thermoplastic-compatible glass fiber supply to northern Italian OEM clusters. Distribution runs through Magna and Bosch automotive divisions, which now consolidate procurement decisions for complete bumper-to-rail assemblies rather than discrete laminate sheets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
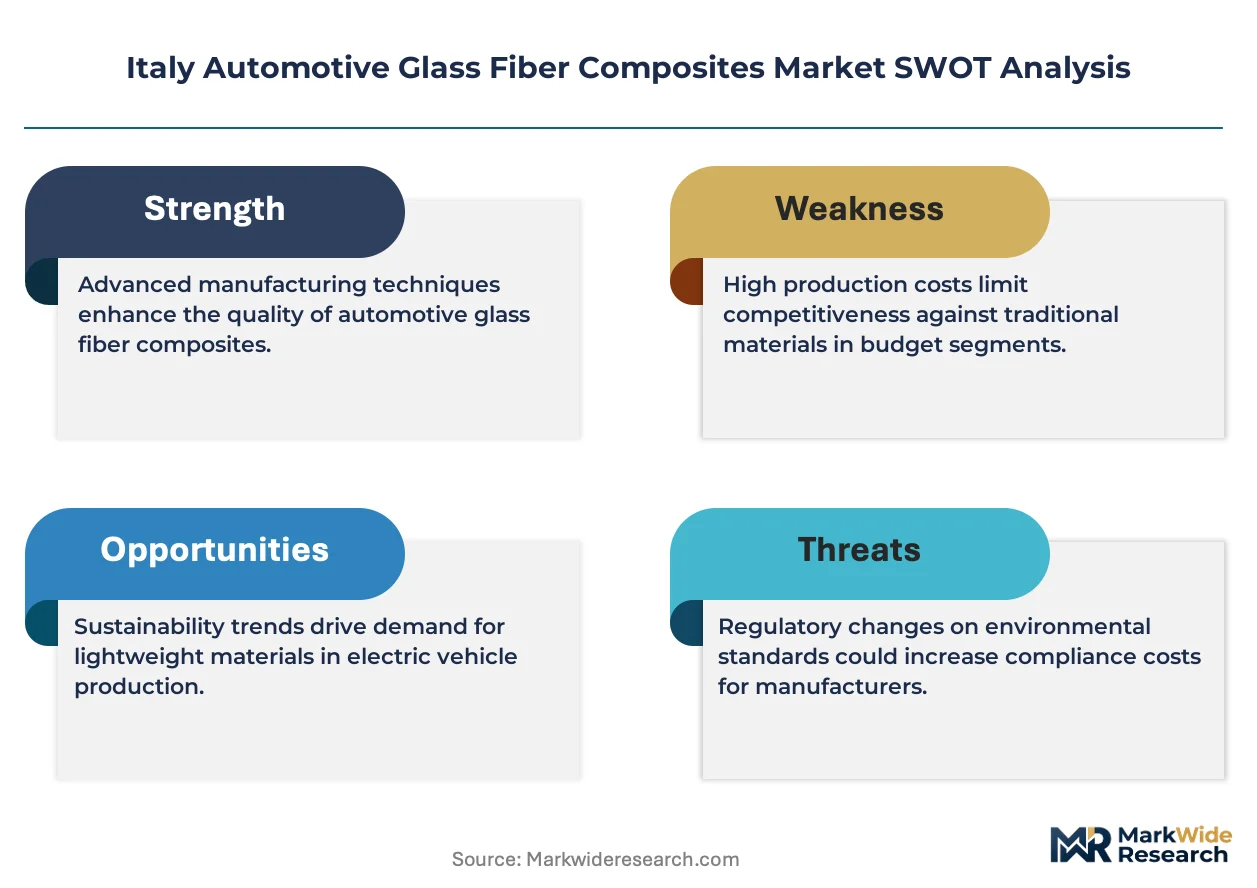
The Italy automotive glass fiber composites market is becoming a vertical-integration race, with backward integration into fiber supply and captive pyrolysis recovery capabilities emerging as decisive levers for next-generation contract qualification.
For Market Incumbents: To counter single-source supply concentration risk, Owens Corning should deepen upstream control over thermoplastic resin compounding in Piedmont, while SAERTEX must invest in multiaxial fabric technician training partnerships with Veneto technical institutes to match RTM line expansion rates and defend qualification timelines against emerging fabric architecture competitors. For New Entrants and Emerging Players: Thermoplastic polypropylene matrix formulations with 40-50 percent fiber volume fractions offer the most penetrable wedge, targeting Campania and Apulia greenfield vacuum infusion capacity for underbody shield applications outside established Stellantis supply hierarchies, with go-to-market positioning anchored to EU End-of-Life Vehicle Directive recyclability pre-certification. For Investors and Strategic Acquirers: The window for entry favors compounders with established pyrolysis or solvolysis fiber recovery capabilities, as evolving EU recyclability mandates will disqualify resin systems lacking certified recovery pathways within the medium-term planning horizon; watch for ECHA substance authorization protocol acceleration as the inflection signal for bio-based epoxy formulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Owens Corning's European network anchoring thermoplastic deliveries to Stellantis-related sites secures volume commitment pricing. |
| Green Manufacturing Transition | Piedmont-based suppliers investing in bio-based epoxy qualification labs maintain CE marking continuity under REACH protocols. |
| Long-term Supply Agreement | Magna and Bosch automotive divisions consolidating procurement for complete bumper-to-rail assemblies redirect Tier 1 supplier selection criteria. |
| Joint Venture | Campania and Apulia manufacturing zones partnering with northern Italian OEM clusters transfer RTM expertise to underpenetrated southern regions. |
| Technology Licensing | SAERTEX multiaxial fabric architectures licensed to Veneto technical institutes scale technician training to match production expansion rates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, RTM line technicians, composite compounder R&D directors, and aftermarket distribution heads. Bottom-up volume modeling triangulated against top-down value estimates derived from ECHA substance authorization databases, EU vehicle registration incentive program disclosures, and Italian National Recovery and Resilience Plan procurement flow documentation.
Reconciliation of production volume streams from IHS Markit vehicle registration data with composite content-per-vehicle assumptions across propulsion architecture, vehicle class, and regional production cluster dimensions generated segment-level forecasts. CAGRs were derived from slope analysis of year-over-year progression rates, with thermoplastic RTM cycle time compression and REACH chemical compliance timeline extensions incorporated as industry-specific demand elasticity and supply constraint inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance authorization acceleration or EU End-of-Life Vehicle Directive mandate tightening. Stakeholders should weight assumptions against their own operating context, particularly resin system qualification timelines and fiber recovery capability investment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
EGR Valve Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Latin America Automotive Connectors Market