
 Refrigerated Trailer Hinges Market | 2026-2036
Refrigerated Trailer Hinges Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Trailer Hinges Market Analytics
Corrosion-resistant alloy formulations is rewriting how hinge assemblies survive salt-road exposure and chemical washdown cycles in refrigerated transport. Wabash National Corporation leverages captive metallurgy labs to validate stainless-steel hinge grades before fleet deployment. Schmitz Cargobull AG anchors its European aftermarket position through standardized bolt-on hinge geometries that reduce dealer inventory complexity. Hyundai Translead competes on price-adjustable hinge lines that accommodate mixed trailer fleets across Asian logistics corridors.
Refrigerated trailer hinges are mechanical articulation devices, typically fabricated from 304 or 316 stainless steel or extruded aluminum alloys, that maintain sealed door alignment across temperature cycles from ambient to minus twenty degrees Celsius while sustaining repetitive loading from forklift impact and road vibration. Their primary purpose is preserving thermal envelope integrity and cargo security in temperature-controlled over-the-road transport. Heavy-duty stainless steel variants dominate installed base volumes due to regulatory washdown mandates in food-grade logistics, while aluminum bolt-on configurations represent the fastest-expanding material-installation pairing as fleets chase tare weight reductions to comply with axle load limits. Spring-loaded adjustable hinges concentrate margin pools because they command replacement premiums from cold storage providers running multi-shift operations with minimal downtime tolerance.
The US EPA, the EU F-Gas Regulation, and the FDA Food Safety Modernization Act collectively shape hinge specifications through emissions-linked weight targets, refrigerant containment protocols, and sanitary design requirements for food contact zones. Trailer OEMs must certify hardware assemblies against these overlapping standards to maintain market access across transatlantic trade lanes. Stakeholders should monitor how impending revisions to EPA trailer greenhouse gas rules and EU Green Deal logistics decarbonization timelines recalibrate material substitution thresholds between stainless and aluminum hinge platforms.
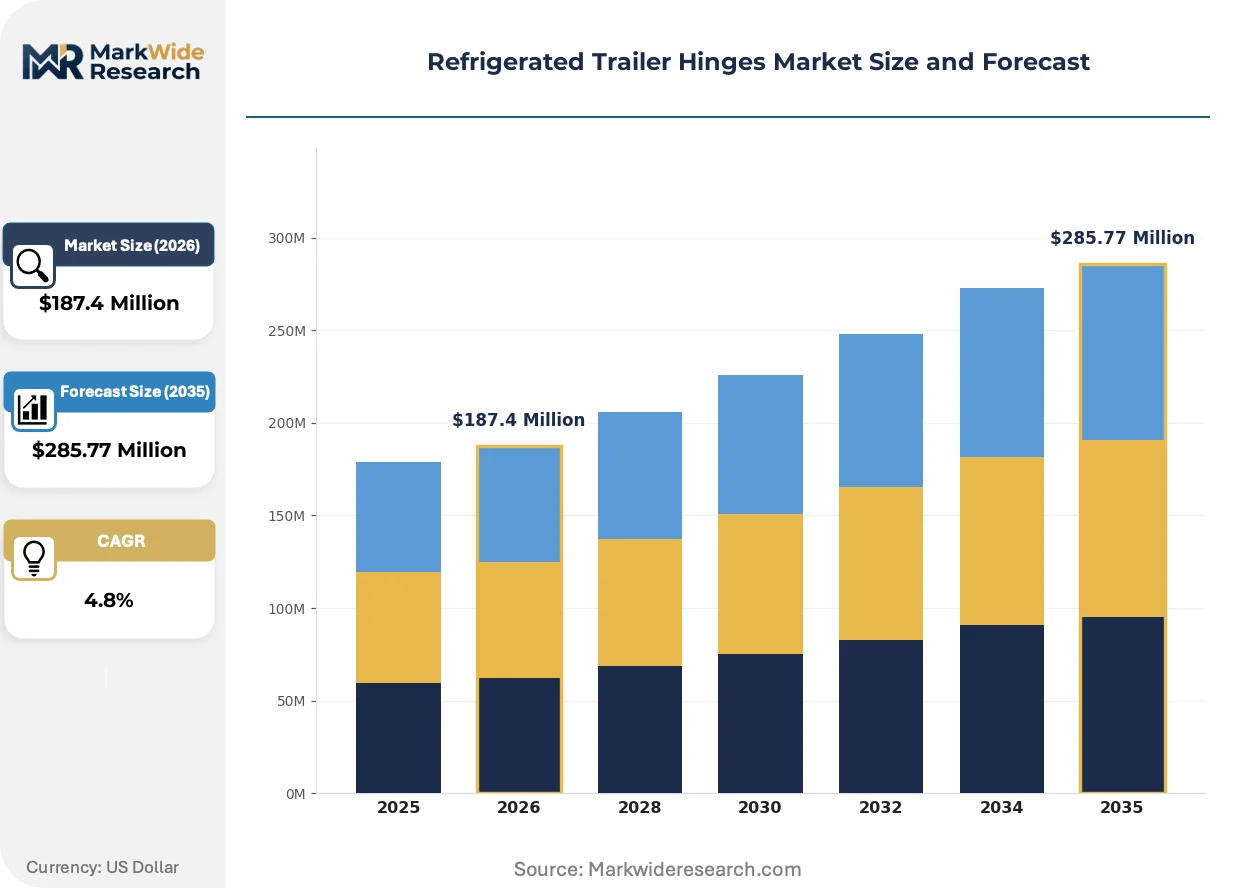
Market Dynamics
Fleet operators face mounting pressure to reduce tare weight while maintaining washdown-compliant hardware integrity, forcing hinge manufacturers to recalibrate material portfolios between stainless steel and aluminum alloys.
Growth Catalysts
- EPA Phase 2 greenhouse gas standards:US trailer emissions rules mandate lighter hardware assemblies, accelerating aluminum hinge adoption in food-grade logistics fleets.
- E-commerce grocery fulfillment:Cold chain operators in the US Midwest are expanding refrigerated trailer capacity, driving replacement hinge demand from multi-shift distribution hubs.
- FDA Food Safety Modernization Act:Sanitary design requirements for food contact zones mandate corrosion-resistant hinge formulations that withstand chemical washdown cycles.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin stability for heavy-duty hinge producers serving washdown-mandated fleets.
- Midwest supplier concentration:OEM cluster density in Indiana and Ohio creates geographic supply risk for aftermarket distributors serving dispersed national fleets.
- Aluminum fatigue limitations:Lower load-bearing capacity versus stainless steel restricts aluminum hinge deployment in high-impact forklift loading zones.
Strategic Opportunities
- EU Green Deal logistics decarbonization:European axle load incentives create white space for lightweight aluminum bolt-on hinge platforms in transatlantic trade lanes.
- Spring-loaded adjustable hinges:Cold storage providers with minimal downtime tolerance represent an underserved premium segment for maintenance-reducing hardware designs.
- Standardized bolt-on geometries:Dealer inventory simplification through modular hinge architectures unlocks aftermarket penetration in fragmented European service networks.
Industry Challenges
- Metallurgical validation timelines:Captive lab testing for salt-road corrosion resistance extends new alloy certification cycles beyond fleet procurement windows.
- Multi-standard compliance complexity:Overlapping EPA, FDA, and EU F-Gas protocols force hinge assemblers to maintain parallel certification tracks for cross-border market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Trailer Hinges Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Light-Duty, Adjustable, Spring-Loaded Material: Stainless Steel, Aluminum, Plastic, Composite Installation Type: Weld-On, Bolt-On, Pin, Clip-On End User: Logistics Companies, Grocery Chains, Food Distributors, Cold Storage Providers |
| Companies Covered | Wabash National Corporation, Utility Trailer Manufacturing Company, Great Dane Trailers, Schmitz Cargobull AG, Stoughton Trailers, LLC, Heil Trailer International, Hyundai Translead, Fahrzeugwerk Bernard Krone GmbH, CIMC Vehicles Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Trailer Hinges Market Evolving Landscape
Material science advances and regulatory tightening are compressing traditional hardware lifecycles, forcing hinge architectures to evolve from passive mechanical components to weight-optimized, compliance-integrated systems.
Extruded aluminum alloy hinge bodies with integrated thermal break geometries are rendering obsolete solid stainless steel castings in temperature-cycling applications. Fleet operators chasing axle load compliance are specifying these platforms for dry freight and light refrigerated duty cycles. The shift is compressing stainless steel hinge margins to washdown-only food-grade niches.
EU F-Gas Regulation refrigerant containment protocols are mandating sealed-door hardware tolerances that exceed legacy hinge alignment specifications. Trailer OEMs serving European lanes must certify assemblies against leak-tightness standards that propagate back to hinge pivot precision requirements. This regulatory stringency is favoring European suppliers with captive metrology capabilities.
Direct procurement relationships between national grocery chains and hinge manufacturers are displacing traditional trailer OEM captive supply arrangements. Large cold storage operators with standardized fleet specifications are unbundling hardware sourcing from complete trailer purchases. This pattern concentrates most visibly in US Midwest distribution corridors where e-commerce fulfillment density justifies volume-direct negotiations.
Refrigerated Trailer Hinges Market Segmentation
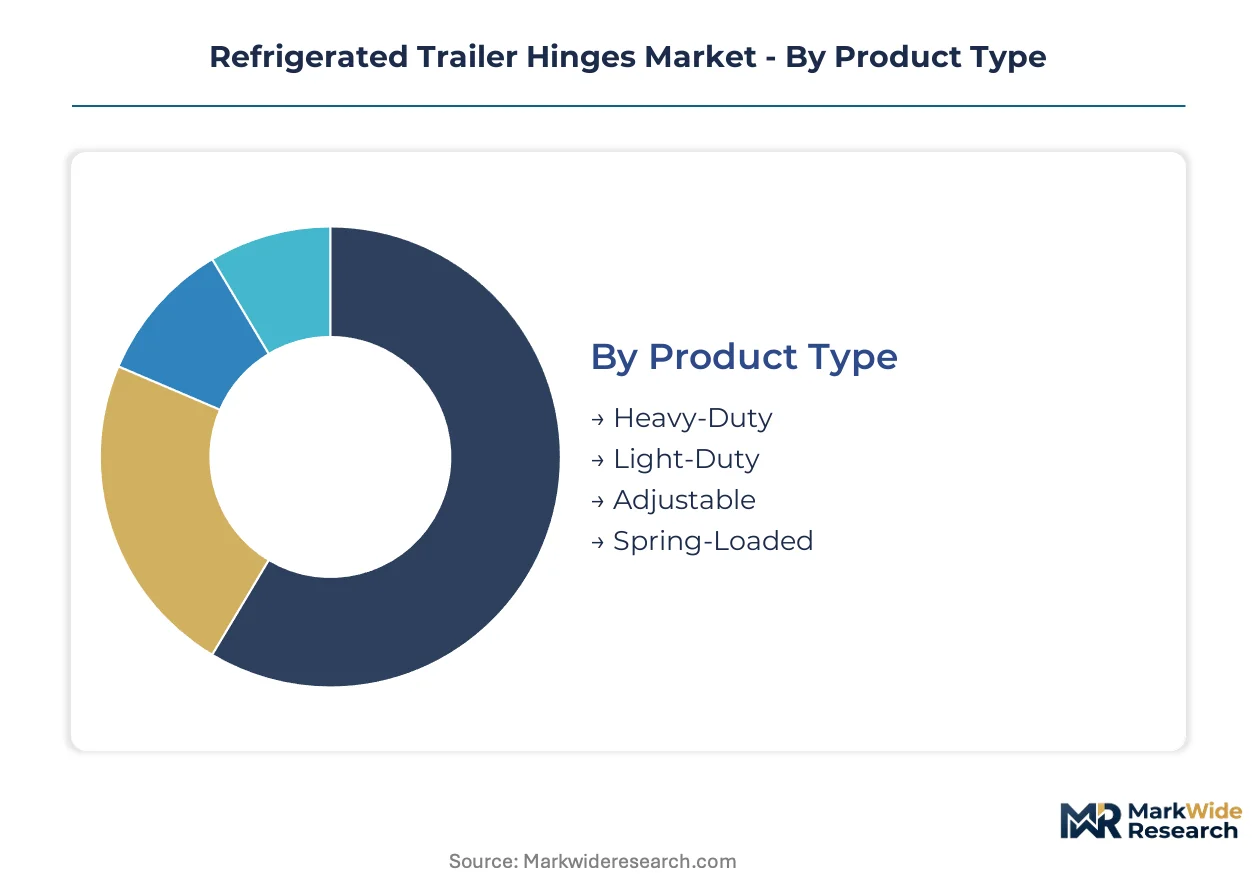
Refrigerated trailer hinges fragment across four structural dimensions that determine procurement priorities. Fleet operators weight material selection against axle load compliance, while end-user scale dictates whether standardized or custom hinge architectures prevail.
Product Type:
Mature mechanical designs dominate installed base volumes, yet emerging adjustable configurations are capturing replacement premiums from uptime-sensitive operators.
- Heavy-Duty:Fabricated from 304 or 316 stainless steel with reinforced pivot bushings rated for repetitive forklift impact cycles. Demand concentrates in multi-shift food distribution hubs across Indiana and Ohio where washdown mandates eliminate corrosion-tolerant alternatives.
- Spring-Loaded:Self-adjusting tension mechanisms maintain door alignment across temperature cycles from ambient to minus twenty degrees Celsius. Cold storage providers with minimal downtime tolerance drive specification for these maintenance-reducing designs in US Midwest e-commerce fulfillment corridors.
- Light-Duty:Extruded aluminum constructions suit dry freight and light refrigerated duty cycles where axle load compliance outweighs impact resistance requirements.
- Adjustable:Modular geometries accommodate mixed fleet standardization, reducing dealer inventory complexity for aftermarket distributors.
Heavy-Duty retains volume leadership; Spring-Loaded holds the steepest expansion curve.
Material:
Cost tier stratification separates premium corrosion-resistant grades from lightweight alternatives chasing regulatory weight targets.
- Stainless Steel:304 and 316 grades withstand chemical washdown cycles mandated by FDA Food Safety Modernization Act protocols. Nickel and chromium price volatility compress margin stability for producers serving washdown-mandated fleets.
- Aluminum:Extruded alloy hinge bodies with integrated thermal break geometries reduce tare weight for EPA Phase 2 greenhouse gas compliance. US fleets specifying these platforms sacrifice some forklift impact tolerance for axle load advantages.
- Plastic:Glass-reinforced polymer formulations serve niche applications in non-food-grade logistics where corrosion resistance is secondary to cost minimization.
- Composite:Hybrid material constructions blending metal inserts with polymer housings target emerging electric trailer platforms seeking maximum weight reduction.
Stainless Steel commands the premium tier; Aluminum is climbing the fastest on regulatory weight pressure.
Installation Type:
Volume concentration favors permanent attachment methods, while serviceability demands are elevating modular alternatives.
- Weld-On:Permanent fusion to trailer frame structures delivers maximum load-bearing capacity for heavy-duty food-grade applications. OEM production lines in Indiana and Ohio specify these for new trailer builds where field service access is limited.
- Bolt-On:Standardized geometries enable rapid replacement without cutting or grinding, reducing dealer inventory complexity across fragmented European service networks.
- Pin:Quick-detach pivot mechanisms suit rental fleet operators requiring rapid hardware swaps between duty cycles.
- Clip-On:Tool-free attachment systems target aftermarket emergency replacement scenarios where downtime costs exceed hardware premiums.
Weld-On anchors OEM volume; Bolt-On is gaining share fastest on aftermarket serviceability demands.
End User:
Customer type determines whether procurement flows through trailer OEMs or shifts to direct manufacturer negotiation.
- Logistics Companies:National operators with standardized fleet specifications unbundle hardware sourcing from complete trailer purchases, concentrating direct procurement relationships in US Midwest distribution corridors.
- Cold Storage Providers:Multi-shift operations with minimal downtime tolerance specify spring-loaded adjustable hinges and premium service contracts, creating margin pools for maintenance-reducing designs.
- Grocery Chains:E-commerce fulfillment density justifies volume-direct negotiations with hinge manufacturers rather than accepting OEM captive supply arrangements.
- Food Distributors:Regional operators balance washdown compliance requirements against capital constraints, typically accepting standard heavy-duty stainless configurations through dealer networks.
Logistics Companies concentrate procurement leverage; Cold Storage Providers deliver the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold storage providers and grocery chains concentrate procurement leverage in specific industrial corridors where trailer OEM clusters overlap with food distribution infrastructure. Fleet standardization programs and regulatory compliance timelines vary sharply across national boundaries.
United States
E-commerce grocery fulfillment density in the Midwest drives refrigerated trailer fleet expansion among national logistics operators. EPA Phase 2 greenhouse gas standards mandate lighter hardware assemblies, pushing hinge specifications toward aluminum alloys in non-washdown applications. Indiana and Ohio host overlapping trailer OEM production clusters and multi-shift food distribution hubs that concentrate replacement hinge demand.
Germany
EU Green Deal logistics decarbonization timelines accelerate axle load compliance investments across transcontinental freight operators. The EU F-Gas Regulation mandates sealed-door hardware tolerances that exceed legacy hinge alignment specifications. Baden-Württemberg and North Rhine-Westphalia anchor European trailer component manufacturing with captive metrology capabilities serving leak-tightness certification requirements.
China
Domestic cold chain infrastructure expansion supports hinge demand from regional food distributors upgrading fleet capacity. National dual carbon goals pressure logistics operators toward weight-optimized hardware platforms. Yangtze River Delta manufacturing bases produce extruded aluminum hinge bodies for both domestic deployment and export to Southeast Asian logistics corridors.
Japan
Precision logistics requirements from pharmaceutical and high-value food cold chains sustain premium hinge specifications. METI energy efficiency guidelines influence trailer hardware weight targets in domestic fleet procurement. Kanto region distribution networks specify maintenance-reducing spring-loaded configurations to minimize downtime in multi-shift operations.
Canada
Cross-border trade lanes with the United States require hardware compliance with both EPA emissions-linked weight targets and domestic transport regulations. Salt-road exposure from winter highway maintenance drives corrosion-resistant alloy specifications in Prairie Provinces fleet operations. Ontario-based cold storage providers mirror US Midwest procurement patterns through direct manufacturer negotiations.
Refrigerated Trailer Hinges Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price-performance segments. Trailer OEMs with captive hardware supply arrangements dominate new-build volumes, while independent component fabricators capture aftermarket replacement cycles. Three archetypes prevail: vertically integrated trailer manufacturers with in-house metallurgy capabilities, regional alloy specialists serving washdown-mandated food-grade niches, and lightweight hardware innovators targeting regulatory weight compliance. Consolidation pressure manifests through strategic partnerships between OEMs and alloy suppliers, plus geographic expansion by European suppliers into North American aftermarket networks.
Among North American trailer OEMs with integrated hardware operations, Wabash National Corporation and Utility Trailer Manufacturing Company exemplify the channel-control archetype through captive supply relationships with fleet operators. Schmitz Cargobull AG represents the European aftermarket standardization approach with modular bolt-on geometries. Hyundai Translead occupies a position in the Asia-Pacific price-adjustable segment serving mixed fleet logistics corridors. These three anchors illustrate how competitive positioning splits between regulatory compliance integration and serviceability optimization.
| Leading Market Players |
|---|
| Wabash National Corporation |
| Utility Trailer Manufacturing Company |
| Great Dane Trailers |
| Schmitz Cargobull AG |
| Stoughton Trailers, LLC |
| Heil Trailer International |
| Hyundai Translead |
| Fahrzeugwerk Bernard Krone GmbH |
| CIMC Vehicles Group Co., Ltd. |
| Others |
Value Network & Pricing Analysis
US Midwest e-commerce fulfillment corridors concentrate hinge procurement leverage among national grocery chains and cold storage operators, compressing margins for standardized stainless steel grades while elevating premiums for spring-loaded adjustable configurations with attached service contracts. This geographic demand density enables direct manufacturer negotiations that bypass traditional trailer OEM markups, fragmenting pricing power across captive supply and independent aftermarket channels.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and chromium benchmarks dominate stainless steel hinge procurement, insulating producers from raw material volatility while exposing buyers to alloy price swings. Price differentiation centers on FDA Food Safety Modernization Act certification tier and bundled after-sales maintenance agreements. Cost compression in heavy-duty stainless segments is intensifying as aluminum alternatives capture EPA Phase 2 compliance-driven volume. Fleet operators with standardized multi-shift specifications exhibit lowest price sensitivity; regional food distributors dependent on dealer networks face highest procurement cost exposure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from tier-one trailer OEMs in Indiana and Ohio anchor working capital flows for captive hinge suppliers, squeezing independent fabricators on cash conversion cycles. Manufacturing concentrates in the United States, Germany, and China, with extruded aluminum hinge bodies sourcing from Yangtze River Delta mills. The supply chain rests on nickel and chromium feedstock dependencies from South African and Indonesian mining operations. Tariff exposure on Chinese aluminum extrusions creates margin vulnerability for lightweight hinge platforms. Distribution runs through OEM captive supply for new trailer builds and fragmented dealer networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerated trailer hinges represent a service-attach opportunity where predictive maintenance contracts and rapid-replacement service level agreements expand faster than hardware unit sales. Recurring revenue from uptime-guarantee programs now commands higher enterprise value multiples than transactional component sales.
For Market Incumbents: Insulate margin pools by deepening backward integration into stainless steel alloy formulation and captive metrology certification against FDA washdown protocols. Expand spring-loaded adjustable hinge production capacity in Ohio to capture cold storage provider premiums. Aluminum hinge commoditization from Chinese imports and nickel price volatility threaten legacy stainless steel margins. For New Entrants and Emerging Players: Establish a beachhead in European aftermarket bolt-on hinge platforms where standardized geometries reduce dealer inventory complexity and Schmitz Cargobull's modular architecture has not fully penetrated fragmented service networks. Target German Baden-Württemberg distribution corridors with EU F-Gas Regulation-certified leak-tightness specifications. Go-to-market through direct procurement relationships with national grocery chains unbundling hardware from complete trailer purchases. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metallurgy-specialist fabricators with captive corrosion validation labs over pure-play assemblers dependent on outsourced alloy certification. Long-term viability across the analysis window rests on regulatory compliance integration capabilities rather than scale economies. Acquisition target archetype: regional alloy specialists serving FDA-mandated food-grade niches with validated 316 stainless grades. Monitor EPA Phase 2 trailer greenhouse gas rule revisions as inflection indicator for aluminum hinge substitution thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Metallurgy Lab Investment | Wabash National validates stainless grades before fleet deployment, compressing certification cycles. |
| Standardized Bolt-On Geometry Expansion | Schmitz Cargobull reduces European dealer inventory complexity through modular hinge architectures. |
| Spring-Loaded Adjustable Product Line Launch | Cold storage providers with minimal downtime tolerance pay replacement premiums for maintenance-reducing designs. |
| Direct Procurement Channel Development | National grocery chains in US Midwest unbundle hardware sourcing from complete trailer OEM purchases. |
| Aluminum Thermal Break Geometry Patent Filing | Extruded alloy hinge bodies with integrated thermal breaks chase EPA Phase 2 axle load compliance. |
Research Methodology
A spread of perspectives from trailer OEM procurement directors, cold storage fleet maintenance managers, metallurgy lab certification leads, and aftermarket distributor inventory planners converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings from Wabash National and Utility Trailer, EPA Phase 2 greenhouse gas rulemaking dockets, FDA Food Safety Modernization Act guidance documents, and EU F-Gas Regulation implementation reports. Bottom-up hinge unit demand estimates triangulated against top-down refrigerated trailer production forecasts from IHS Markit vehicle registration databases.
Demand-supply balance framing anchored the forecast framework across the projection horizon, modeling refrigerated trailer hinge consumption by product type, material grade, installation method, and end-user procurement channel. Segmentation dimensions included heavy-duty versus spring-loaded mechanical designs, 304/316 stainless versus extruded aluminum alloy formulations, weld-on versus bolt-on attachment geometries, and logistics company direct procurement versus OEM captive supply arrangements. CAGRs derived from regression analysis of historical fleet expansion rates against e-commerce grocery fulfillment penetration curves and regulatory compliance timeline acceleration.
Sensitivities concentrate around nickel and chromium price volatility, EPA trailer greenhouse gas rule revision timing, and EU Green Deal logistics decarbonization implementation pace. Forecasts reflect documented assumptions on fleet standardization trends and aftermarket service contract attach rates. Macroeconomic freight volume contraction, unanticipated alloy substitution breakthroughs, or regulatory harmonization failures between EPA and EU protocols would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Rear Axle Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Steering Gear Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Injector Deposit-Resistant Fuel Injection Component Platforms Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Locomotive Lighting Batteries Market