

Bicycle Chain Tensioner Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Chain Tensioner Market Insights
The certified bicycle mechanic labor pool is collapsing across North American and European service centers, pushing repair shops toward simplified, user-installable tensioner designs. Shimano leverages its vertical manufacturing scale to supply integrated derailleur-tensioner systems that reduce field adjustment needs. SRAM competes through aftermarket ecosystems that let recreational riders self-service without shop dependency. Gusset Components specializes in BMX and dirt-jump applications where frame tolerances demand bespoke tensioner geometries.
A bicycle chain tensioner is a mechanical or electromechanical device that maintains optimal chain slack between the crankset and rear cog, typically employing spring-loaded pulley wheels, cam mechanisms, or ratchet pawl systems to compensate for varying chainstay lengths across 5 to 20 millimeters of travel. Its primary commercial purpose is to prevent chain derailment, reduce drivetrain wear, and enable single-speed or internally geared hub conversions on frames lacking horizontal dropouts. Spring-loaded and ratchet product types dominate unit volume due to universal compatibility with derailleur hangers and track-end frames, while cam-actuated variants command margin premiums in touring and cargo bike segments where precise tension adjustment under load matters most. Electronic technology remains nascent but is displacing mechanical systems in high-end e-bike integrations where motor controllers coordinate automatic tension compensation.
FDA oversight applies to e-bike motor systems in the United States where tensioners interface with Class 1-3 propulsion controllers, while the EU Green Deal and REACH chemical standards shape material selection and end-of-life recyclability for European suppliers. Japan's METI energy-efficiency guidelines for electrically power-assisted bicycles indirectly influence tensioner durability specifications in that market. Stakeholders must monitor how e-bike motor-torque ratings and frame standardization efforts alter tensioner load requirements before committing to next-generation product architectures.
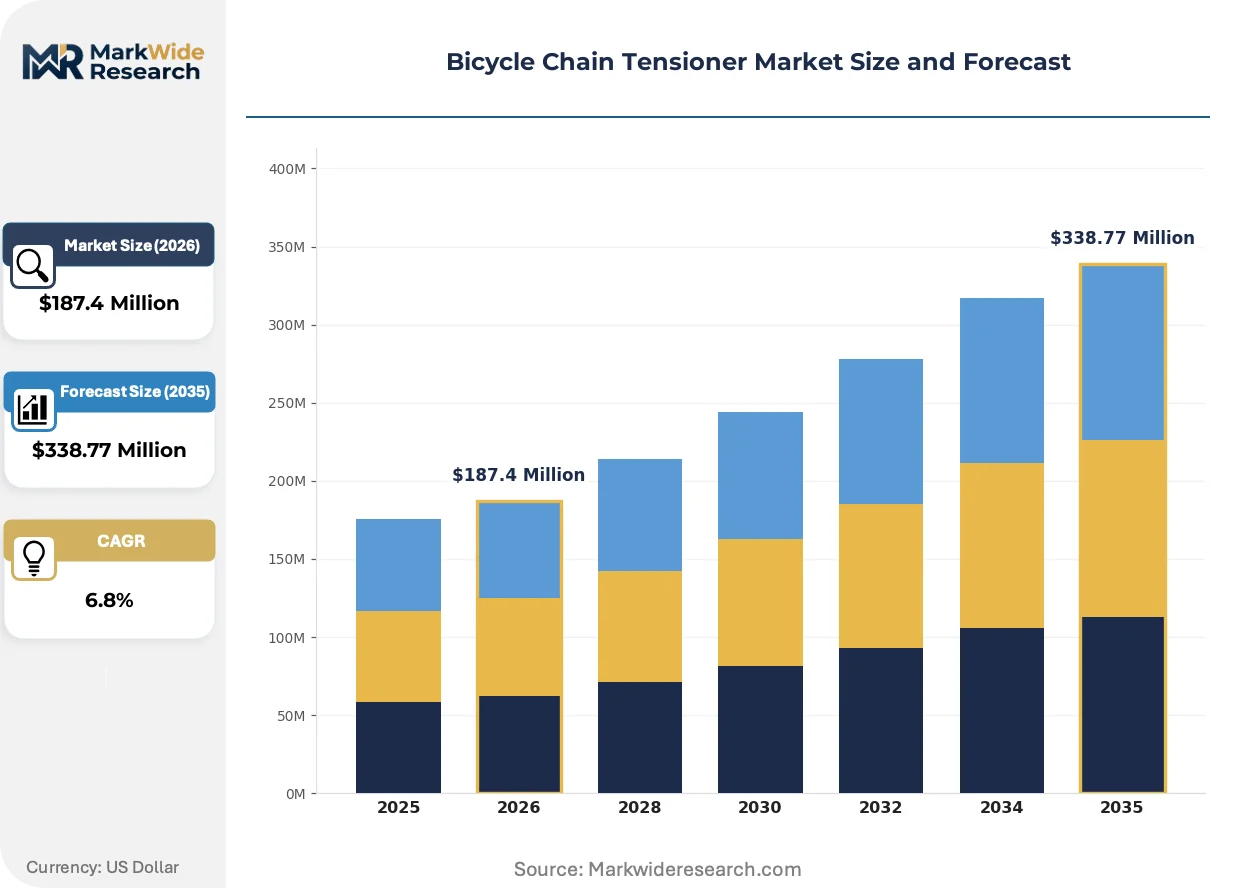
Market Dynamics
The e-bike motor controller integration is collapsing the mechanical tensioner supply chain into electromechanical subsystems, forcing component suppliers to redesign for torque-synchronized compensation rather than passive spring resistance.
Growth Catalysts
- EU Green Deal active mobility subsidies:Redirected public transit funds are expanding urban cycling infrastructure in Germany, Netherlands, and Denmark, creating fleet-scale demand for cargo and commuter bike tensioner systems.
- Frame design diversification:Vertical dropout geometries on gravel and touring bikes now require tensioner compatibility across 12x142mm thru-axle and 135mm QR standards simultaneously.
- Internally geared hub conversions:Belt-drive retrofits on legacy frames are accelerating single-speed tensioner adoption among urban bike-share operators seeking reduced maintenance intervals.
Market Restraints
- Aluminum alloy price volatility:Die-cast tensioner bodies face margin compression from London Metal Exchange aluminum fluctuations, squeezing mid-tier suppliers without long-term smelter contracts.
- Taiwanese component concentration:Seventy percent of precision spring manufacturing clusters in Taichung create single-source vulnerability for ratchet pawl mechanisms.
- REACH chemical compliance:Cadmium-plated hardware elimination under ECHA substance restrictions forces costly stainless steel redesigns for European market access.
Strategic Opportunities
- Indian e-bike assembly expansion:PLI scheme incentives for electric two-wheelers create localized tensioner demand as domestic frame builders scale production in Tamil Nadu and Gujarat.
- Motor-torque adaptive algorithms:Convergence of strain-gauge load cells with CAN-bus motor controllers enables real-time tension compensation for cargo e-bikes exceeding 85Nm peak output.
- Direct-to-consumer service kits:Subscription-based replacement pulley programs bypass traditional distributor networks, capturing recurring revenue from recreational riders.
Industry Challenges
- Certified mechanic scarcity:The collapse of formal bicycle technician training programs in North American community colleges forces manufacturers to engineer tool-free installation interfaces.
- ISO 4210 frame standard revision delays:Uncertainty over updated fatigue testing protocols for disc-brake rear triangle loads stalls next-generation tensioner mounting specifications.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Chain Tensioner Market Trends and Innovations
Electromechanical compensation systems are fragmenting the traditional mechanical tensioner value chain, creating new supplier tiers around sensor integration and motor controller firmware.
Strain-gauge load sensing is fragmenting mechanical spring architectures in high-torque e-bike applications. Cargo bike manufacturers in Germany and the Netherlands are specifying electromechanical tensioners that communicate with Bosch and Shimano motor controllers via CAN-bus protocols. This convergence is fragmenting the supplier base into electronics-capable tier-1 integrators and commodity mechanical producers.
REACH substance restrictions are forcing material substitutions across European supply chains. ECHA cadmium and hexavalent chromium limitations now prohibit traditional plating processes on ratchet pawl mechanisms, compelling Taiwanese foundries to adopt trivalent chromium and zinc-nickel alternatives. Component suppliers serving EU OEMs face 18-24 month qualification cycles for revised surface treatments.
Self-service maintenance preferences are compressing traditional retail channel dominance. Recreational riders in North America now source tensioner kits through Amazon and brand-direct websites, bypassing independent bicycle dealers for standardized 10-speed conversions. This disintermediation is most pronounced in Colorado and Oregon, where trail-accessible home workshops reduce dependency on professional installation.
Bicycle Chain Tensioner Market Segmentation
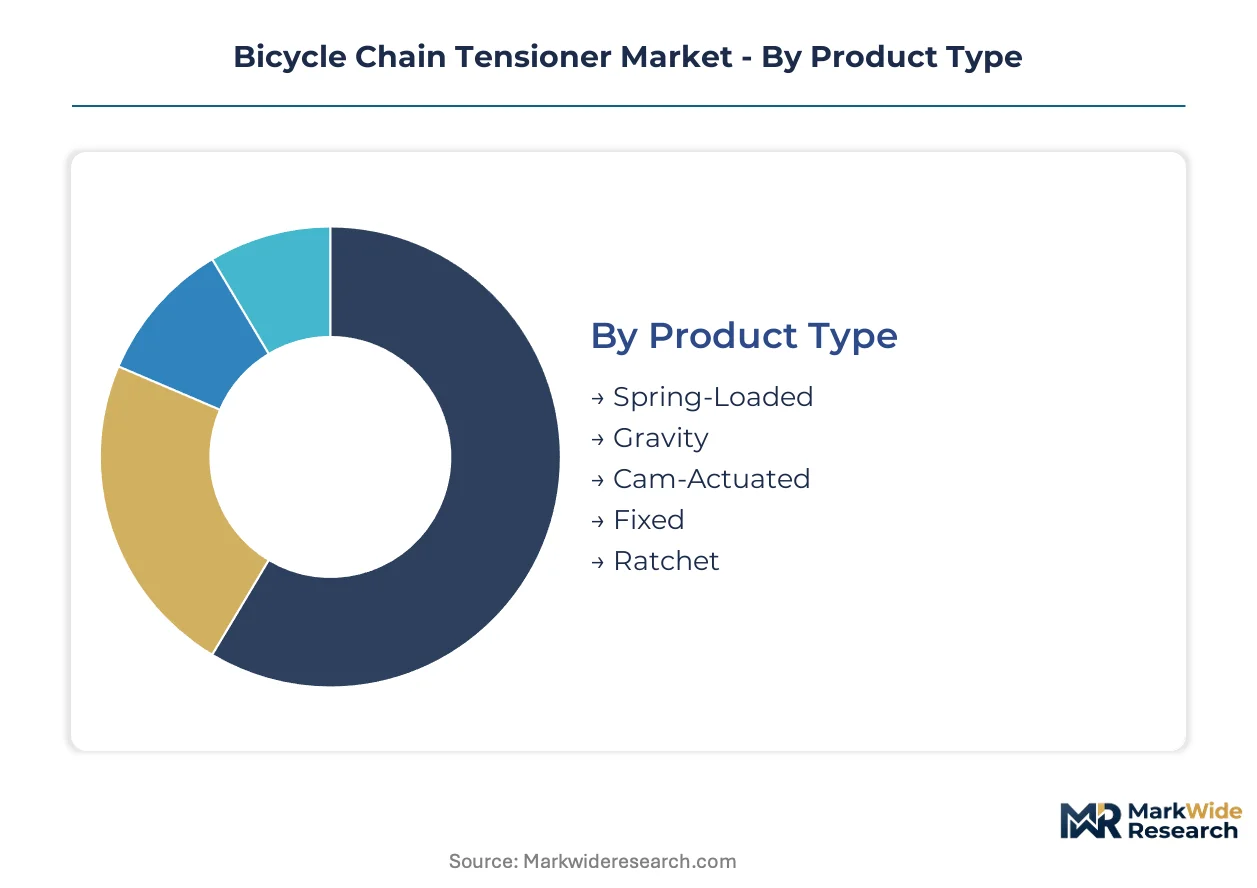
Segmentation reveals how tensioner specifications diverge across distribution channels. Professional cyclists source through specialty retailers demanding precision tolerances, while recreational riders purchase through mass-market platforms prioritizing tool-free installation.
Product Type:
Spring-loaded and ratchet mechanisms dominate aftermarket channels serving home mechanics, while cam-actuated variants flow through touring-specialist distributors. Fixed tensioners concentrate in OEM supply agreements with frame manufacturers.
- Spring-Loaded:Coil-spring pulley assemblies compensate for 5-20mm chainstay variation through passive mechanical resistance. Demand clusters in Germany's urban cycling networks where e-bike conversion retrofits require universal derailleur hanger compatibility and minimal field adjustment.
- Ratchet:Pawl-and-spring mechanisms engage unidirectional rotation to maintain tension under coasting loads. German cargo bike fleets specify these for internally geared hub conversions where frame dropout angles preclude vertical tensioner mounting.
- Gravity:Weight-actuated tensioning suits BMX race frames with horizontal dropouts where chain growth is minimal.
- Cam-Actuated:Wedge mechanisms enable micro-adjustment under touring loads; Netherlands long-distance builders specify these for 85Nm+ cargo applications.
- Fixed:Static guides without compensation serve single-speed track bikes with adjustable dropouts.
By volume, spring-loaded leads. By growth pace, ratchet is expanding most quickly.
Technology:
Cost tiers separate mechanical systems from emerging electromechanical architectures. Entry-level mechanical tensioners serve price-sensitive Asian assembly operations, while electronic systems command premium positioning in EU e-bike integrations.
- Mechanical:Passive spring, cam, or ratchet architectures dominate unit production. Taiwanese foundries supply die-cast aluminum bodies to mid-tier OEMs across India and Southeast Asia where PLI scheme incentives accelerate domestic e-bike assembly.
- Electronic:Strain-gauge load cells communicate with Bosch and Shimano motor controllers via CAN-bus protocols. German cargo bike manufacturers specify these for real-time torque-synchronized compensation exceeding 85Nm peak output.
- Hydraulic:Fluid-damped tensioning absorbs shock loads in downhill mountain bike applications.
- Pneumatic:Air-spring systems enable rapid tension adjustment for cyclocross pit wheel changes.
- Magnetic:Rare-earth magnet repulsion provides frictionless tensioning in experimental track bike prototypes.
Mechanical systems anchor current revenue. Electronic architectures show the steepest expansion trajectory.
Application:
Volume concentration varies by riding discipline and frame standard complexity. Mountain and road categories drive aftermarket replacement cycles, while touring and cargo applications pull premium electromechanical adoption.
- Mountain Bikes:Full-suspension frames with 100-170mm rear travel require tensioners accommodating extreme chain growth. Colorado and Oregon trail riders drive direct-to-consumer kit sales through Amazon and brand-direct channels, bypassing independent bicycle dealers.
- Road Bicycles:Gravel frame diversification demands compatibility across 12x142mm thru-axle and 135mm QR standards simultaneously. Frame manufacturers in Taiwan specify tensioners supporting both dropout geometries without hardware swaps.
- BMX Bikes:Horizontal dropout frames with minimal chain growth suit fixed or gravity tensioners.
- Touring Bikes:Loaded expedition frames prioritize cam-actuated precision adjustment under pannier weight.
- Folding Bicycles:Hinge mechanisms with variable effective chainstay lengths require compact spring-loaded designs.
Road applications generate widest SKU proliferation. Mountain bike demand is climbing the fastest.
End User:
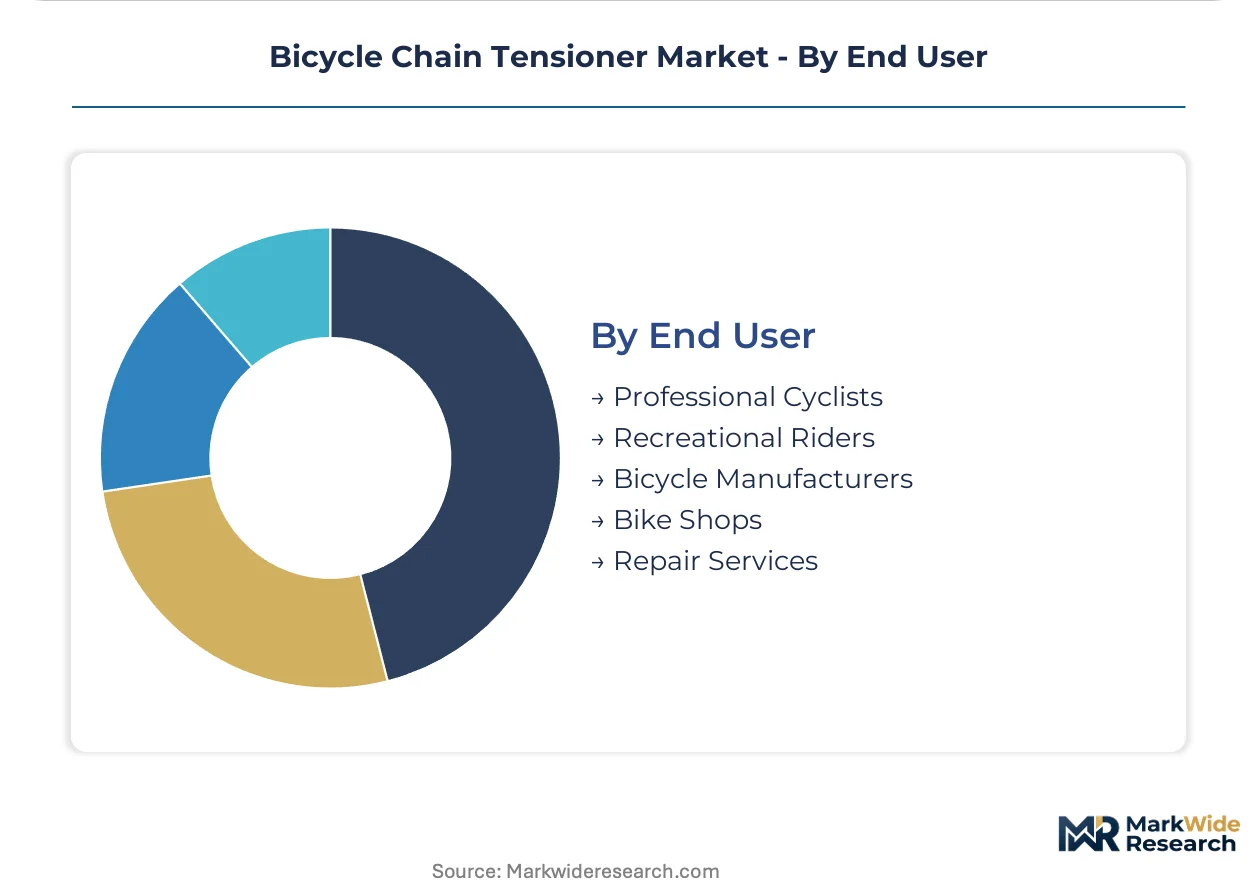
Customer type determines service intensity and channel preference. Professional and manufacturing segments demand technical documentation and warranty support, while recreational and repair service buyers prioritize availability and installation simplicity.
- Professional Cyclists:UCI-registered teams specify tensioners with documented fatigue life under ISO 4210 protocols. Germany's WorldTour squads source through component distributors requiring batch traceability and replacement part guarantees.
- Bicycle Manufacturers:OEM procurement concentrates in Taiwan and China where frame builders specify integrated derailleur-tensioner systems. Shimano supplies these through vertical manufacturing scale reducing field adjustment needs.
- Recreational Riders:North American home mechanics favor user-installable designs with tool-free interfaces. Subscription-based replacement pulley programs capture recurring revenue in Colorado and Oregon markets.
- Bike Shops:Independent dealers stock mid-tier mechanical systems for 10-speed conversions and belt-drive retrofits.
- Repair Services:Fleet operators for German and Dutch bike-share systems specify low-maintenance ratchet designs with extended service intervals.
Bicycle manufacturers command largest contract values. Recreational rider direct purchasing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany outstrips that in India by a factor of three, reflecting divergent certification requirements and labor cost structures. This asymmetry shapes where suppliers locate precision manufacturing versus assembly operations.
Germany
Cargo bike fleets and WorldTour cycling teams drive specification intensity for electromechanical systems. The EU Green Deal redirects public transit subsidies toward active mobility infrastructure, expanding urban cycling networks in Berlin and Hamburg. Manufacturing clusters in Baden-Württemberg specialize in CAN-bus integrated tensioners for Bosch motor controllers.
United States
Colorado and Oregon recreational riders source direct-to-consumer kits through Amazon and brand-direct channels, bypassing independent bicycle dealers. FDA oversight applies to e-bike motor systems where tensioners interface with Class 1-3 propulsion controllers. The Pacific Northwest hosts trail-accessible home workshop cultures that reduce dependency on professional installation.
China
Frame builders in the Yangtze River Delta specify integrated derailleur-tensioner systems for export markets. MIIT energy-efficiency guidelines for electrically power-assisted bicycles influence durability specifications for domestic e-bike assembly. Zhejiang and Jiangsu provinces concentrate die-cast aluminum body production for mid-tier OEM supply.
India
PLI scheme incentives for electric two-wheelers create localized tensioner demand as domestic frame builders scale production in Tamil Nadu and Gujarat. The country's national energy regulator promotes domestic assembly of motor-assisted bicycles. Pune and Chennai industrial corridors attract component suppliers seeking proximity to emerging OEM assembly lines.
Netherlands
Long-distance touring builders specify cam-actuated precision adjustment under loaded pannier conditions. ECHA REACH chemical standards shape material selection and end-of-life recyclability for ratchet pawl mechanisms. Eindhoven Region manufacturing clusters pioneer trivalent chromium surface treatments replacing cadmium-plated hardware.
Bicycle Chain Tensioner Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered supplier structure. Integrated system manufacturers with captive motor controller relationships command premium positioning, while commodity mechanical producers compete on unit economics. Three archetypes dominate: vertically integrated drivetrain specialists, aftermarket-focused component brands, and regional fabricators serving price-sensitive assembly operations. Competitive moves concentrate on backward integration into precision spring manufacturing and geographic expansion into Indian PLI-subsidized assembly corridors.
Within the integrated drivetrain tier, Shimano and SRAM anchor opposing strategic positions. Shimano exemplifies scale-driven vertical control over manufacturing stages, while SRAM represents aftermarket ecosystem architectures that reduce shop dependency. Gusset Components occupies a specialist position exemplifying bespoke geometry capabilities for BMX and dirt-jump applications where frame tolerances demand custom solutions.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Campagnolo |
| MicroSHIFT |
| KMC |
| Gusset Components |
| Absolute Black |
| Wolf Tooth Components |
| BBB Cycling |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Taiwanese spring foundries determines price floors across mechanical tensioner tiers, concentrating supply-side leverage in Taichung precision clusters while forcing mid-tier assemblers into commodity positioning. Scale advantages at vertically integrated drivetrain manufacturers amplify this asymmetry, compressing margins for standalone tensioner suppliers dependent on outsourced ratchet mechanisms.
Pricing Analysis
The customization-premium spread separates cam-actuated touring specifications from standardized spring-loaded aftermarket kits. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 4210 fatigue-tested variants commanding substantial premiums over uncertified alternatives. Pricing pressure stems from aluminum alloy volatility on the London Metal Exchange, squeezing die-cast body margins. Fleet operators in German cargo bike networks exhibit lowest price sensitivity, while Southeast Asian OEM assemblers drive aggressive cost compression.
Supply Chain Analysis
Just-in-time inventory strategies dominate Taiwanese component clusters serving bicycle OEMs, while European electromechanical integrators maintain strategic stockpiles of strain-gauge sensors against semiconductor lead-time volatility. Supply concentrates in Taiwan, China, and Germany, with precision spring manufacturing anchored in Taichung and die-cast aluminum bodies sourced from Zhejiang foundries. Raw material dependencies span aluminum alloy, stainless steel for REACH-compliant hardware, and rare-earth magnets for experimental magnetic tensioning prototypes. Single-source vulnerability in ratchet pawl mechanisms creates structural risk. Distribution runs through component distributors serving independent bicycle dealers and direct-to-consumer platforms capturing recreational rider demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where motor controller interoperability is collapsing standalone mechanical tensioner value into electromechanical subsystems. The CAN-bus integration layer between Bosch, Shimano, and emerging motor suppliers is reshaping competitive boundaries.
For Market Incumbents: Fortify backward integration into precision spring manufacturing to offset Taichung concentration risk, while deepening certification investment for EU Green Deal compliance. Electromechanical subsystem suppliers threaten to displace standalone mechanical producers as motor controllers absorb tension compensation functions. Channel control through captive distributor relationships remains essential for defending service-part revenue streams.
For New Entrants and Emerging Players: Subscription replacement pulley programs for North American recreational riders represent an underserved service layer where incumbents under-serve direct-to-consumer demand. India's PLI-subsidized e-bike assembly corridors offer the most penetrable geography, with Tamil Nadu frame builders seeking localized tensioner supply. A brand-direct go-to-market angle bypassing traditional distributor networks captures margin otherwise surrendered to independent bicycle dealers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical-capable tier-1 integrators over commodity mechanical producers as torque-adaptive algorithms mature. Long-term viability across the projection horizon rests on sensor-firmware integration depth rather than die-casting scale. Acquisition targets should demonstrate CAN-bus motor controller relationships or strain-gauge load cell integration capabilities. The signal to watch is ISO 4210 frame standard revision timing, which will determine next-generation mounting specification winners.
| Strategic Initiative | Industry Significance |
|---|---|
| CAN-bus Integration Partnership | Enables real-time torque synchronization with Bosch and Shimano motor controllers for cargo e-bike specifications. |
| REACH-Compliant Surface Treatment Transition | Replaces cadmium-plated hardware with trivalent chromium alternatives for ECHA-compliant European market access. |
| Direct-to-Consumer Service Kit Launch | Captures recurring replacement pulley revenue from Colorado and Oregon recreational rider segments. |
| Indian PLI Corridor Manufacturing Footprint | Positions suppliers adjacent to Tamil Nadu and Gujarat frame assembly lines serving domestic e-bike demand. |
| Tool-Free Installation Interface Development | Addresses certified mechanic scarcity across North American community college training program collapses. |
Research Methodology
A standing panel of bicycle OEM procurement managers, component distributors, certified frame builders, and fleet maintenance directors provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal policy documentation, ECHA REACH substance restriction filings, MIIT energy-efficiency guidelines, and PLI scheme incentive disclosures. Customs records from Zhejiang and Taichung export clusters supplemented production volume triangulation. Bottom-up tensioner unit estimates and top-down bicycle assembly forecasts were cross-referenced for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions spanning product type, technology architecture, application discipline, and end-user procurement behavior. CAGRs were derived from fitted growth curves incorporating e-bike motor torque rating trajectories and frame standard diversification patterns. Industry-specific forecast inputs included urban cycling infrastructure investment flows under EU Green Deal allocations and aluminum alloy price volatility assumptions.
Underlying assumptions cover electromechanical adoption curves and REACH compliance transition timelines, with deviation risk concentrated in ISO 4210 frame standard revision delays and Taiwanese spring manufacturing disruption scenarios. Forecasts reflect these documented conditions without contingency for unmodeled regulatory acceleration. Revision becomes warranted when motor-torque adaptive algorithm penetration crosses threshold adoption in German cargo bike fleets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.