
 Industrial Truck Market | 2026-2036
Industrial Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Truck Market Intelligence
The substitution of lithium-ion batteries for traditional lead-acid power sources is decoupling industrial truck operational uptime from lengthy charging cycles. Toyota Industries Corporation leverages its automotive battery expertise to lead this transition. KION Group AG competes through its diverse portfolio of electric and autonomous solutions. Hyster-Yale Materials Handling Inc. differentiates by offering multiple power options, including hydrogen fuel cells, across its product lines.
An industrial truck is a powered vehicle designed for lifting, moving, and placing materials over short distances. These vehicles, including forklifts and pallet jacks, are engineered with specific load capacities, often ranging from 1 to over 50 tons, for use in constrained environments. Electric models now dominate new equipment sales, supplanting diesel and LPG technologies in indoor applications. Within product types, counterbalance forklifts remain the core segment, while demand for order pickers grows swiftly due to e-commerce fulfillment needs.
Operator safety and emissions standards heavily influence design, governed by bodies like the US Occupational Safety and Health Administration (OSHA). In Europe, compliance with CE marking and machinery directives is mandatory for market access, while China's MEE enforces stringent emissions controls for internal combustion engines. Decisions on powertrain electrification versus internal combustion will define fleet total cost of ownership and operational viability for end users.
Market Dynamics
The bifurcation of fleet strategies between internal combustion and electric powertrains defines the market's structure. This division is driven by advancements in battery technology and tightening emissions standards, forcing end-users to make long-term total cost of ownership decisions.
Growth Catalysts
- E-commerce Expansion:The rapid growth of e-commerce fulfillment centers, particularly in the United States, necessitates a higher density of order pickers and narrow-aisle trucks to manage inventory velocity and small-item handling.
- Emissions Mandates:Stringent emissions controls for non-road mobile machinery, such as those enforced by China's Ministry of Ecology and Environment (MEE), accelerate the replacement cycle for older internal combustion engine forklifts.
- Battery System Innovation:Advances in lithium-ion battery energy density and charging speeds enable electric trucks to perform in continuous-use applications previously dominated by internal combustion, expanding their addressable market within manufacturing.
Market Restraints
- Capital Investment:The high initial acquisition cost of electric trucks, particularly those powered by lithium-ion batteries, presents a significant capital barrier for small and medium-sized enterprises compared to legacy internal combustion models.
- Infrastructure Deficits:Existing warehouses, especially older facilities, often lack the electrical infrastructure required to support large-scale fleet charging, limiting the pace of electric truck adoption without significant facility upgrades.
- Component Supply Concentration:The global supply of high-capacity lithium-ion battery cells is heavily concentrated in a few key Asian producers, exposing truck manufacturers to price volatility and geopolitical supply chain risks.
Strategic Opportunities
- Automation as a Service:The convergence of advanced telematics and AI-driven software creates an opportunity for offering autonomous navigation as a subscription service, lowering the adoption barrier for automated guided vehicles in logistics.
- Emerging Market Modernization:Logistics modernization in markets like Brazil and Mexico presents a significant opportunity for replacing aging material handling equipment with modern electric and safer forklift models in manufacturing plants.
- Hydrogen Fuel Cell Niche:For high-throughput, 24/7 operations where battery charging is impractical, hydrogen fuel cells offer a zero-emission alternative, creating a specialized market segment in large distribution centers and port logistics.
Industry Challenges
- Technician Skill Gaps:A shortage of technicians skilled in servicing advanced electronics, lithium-ion battery systems, and the software that governs modern industrial trucks creates maintenance bottlenecks and increases operational downtime for end-users.
- Legacy System Integration:Integrating new autonomous and connected industrial trucks with existing, often proprietary, Warehouse Management Systems (WMS) is a complex and costly challenge, hindering the deployment of fully automated intralogistics solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Truck Market |
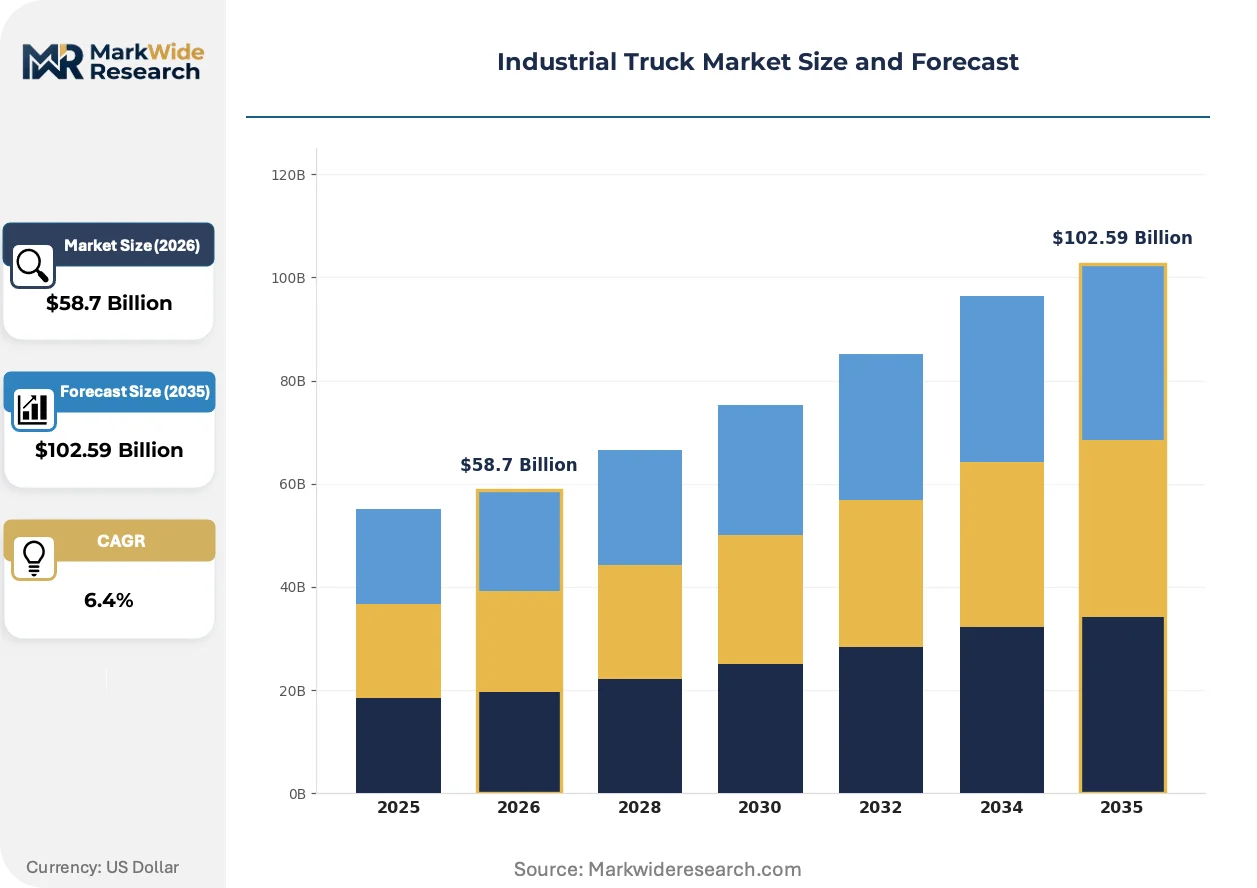
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counterbalance Forklifts, Reach Trucks, Pallet Jacks, Order Pickers, Tow Tractors Technology: Electric, Diesel, LPG, Hydrogen Fuel Cell, Hybrid Application: Warehousing, Distribution Centers, Manufacturing Plants, Ports & Terminals, Construction Sites End User: Logistics Providers, Retail Warehousing, Food & Beverage Facilities, Chemical Plants, Textile Manufacturers |
| Companies Covered | Mitsubishi Logisnext Co., Ltd., Crown Equipment Corporation, Toyota Industries Corporation, Clark Material Handling Company, Komatsu Ltd., KION Group AG, Hyster-Yale Materials Handling Inc., Anhui Heli Co., Ltd., Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Truck Market Strategic Shifts & Innovations
The industrial truck industry is transitioning from a focus on mechanical lifting capacity to one defined by software-enabled operational intelligence. This shift prioritizes uptime, fleet efficiency, and integration with broader logistics information systems over standalone vehicle performance.
Autonomous navigation technology, utilizing LiDAR and vision-based sensors, allows industrial trucks to perform repetitive transport tasks without a human operator. Large-scale distribution centers and manufacturing facilities are steadily adopting these systems for pallet movement. This technology is absorbing the operational variability and labor costs associated with manual vehicle operation into a predictable, software-defined workflow.
European Union regulations, specifically the Machinery Directive, mandate CE marking and impose strict safety design standards on industrial trucks. This forces manufacturers to embed features like stability controls and operator presence sensors across their product lines. Counterbalance forklift and warehouse equipment segments feel the greatest impact, which elevates baseline design complexity and unit cost.
A preference for shorter-term rental and full-service leasing contracts is replacing outright capital purchases for many fleet operators. This model shifts the responsibility for maintenance, compliance, and technology upgrades from the end-user to the dealer or manufacturer. The trend is most pronounced in the United States and Europe, particularly among third-party logistics providers seeking operational flexibility.
Industrial Truck Market Segmentation
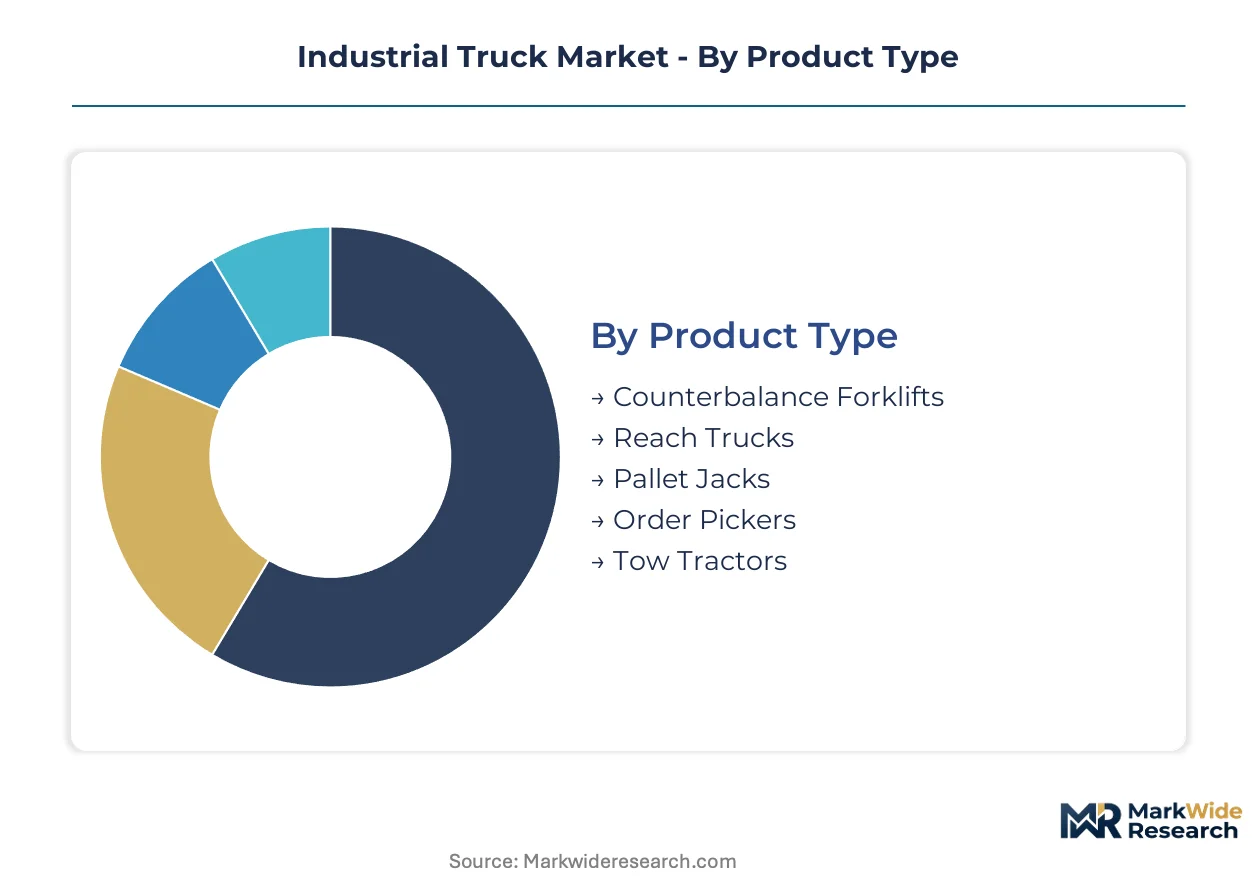
The industrial truck market divides into distinct segments, reflecting diverse operational needs and regulatory compliance requirements across various industries. Understanding these segmentations helps manufacturers tailor product development and end-users optimize fleet acquisition strategies. This detailed breakdown highlights the specific characteristics and demand drivers shaping each market component.
Product Type:
Product type segmentation often dictates the primary safety and operational certifications required, with complex machinery like counterbalance forklifts facing stringent stability standards from bodies like the US Occupational Safety and Health Administration (OSHA).
- Counterbalance Forklifts:These powered industrial trucks feature a counterweight at the rear to offset the load, offering versatility in lifting and transporting heavy loads. Demand remains concentrated in general warehousing.
- Order Pickers:Designed for lifting operators to rack levels for individual item retrieval, these specialized trucks optimize speed and accuracy in high-density storage. E-commerce fulfillment centers drive significant demand in the United States.
- Reach Trucks:These trucks extend forks beyond outriggers, allowing deep stacking in narrow aisles.
- Pallet Jacks:Manual or powered, these vehicles transport palletized loads over short distances.
- Tow Tractors:Used for pulling multiple unpowered trailers or carts in manufacturing lines.
Counterbalance Forklifts sit at the top of the volume ranking, with Order Pickers climbing the fastest.
Technology:
The choice of industrial truck technology is increasingly defined by operational suitability for specific environments, balancing power requirements with emissions controls and infrastructure availability.
- Electric:These trucks are powered by rechargeable batteries, offering zero emissions and quiet operation, ideal for indoor applications. Advances in lithium-ion battery energy density expand their utility.
- Hydrogen Fuel Cell:Utilizing a chemical reaction to produce electricity, these systems offer rapid refueling and consistent power without emissions, suitable for 24/7 high-throughput distribution centers.
- Diesel:Internal combustion engines provide high torque and long run times, typically used in heavy-duty outdoor applications.
- LPG:LPG-powered trucks balance indoor and outdoor use with lower emissions than diesel.
- Hybrid:These systems combine internal combustion with an electric motor, optimizing fuel efficiency.
Demand for Electric technology is driven by tightening emissions mandates, while Hydrogen Fuel Cell addresses continuous-use operational requirements.
Application:
Industrial truck application segments are often distinguished by the primary customer types they serve, each with unique material flow patterns and storage density requirements.
- Warehousing:This segment includes general storage and large-scale inventory holding operations, requiring a mix of counterbalance, reach, and pallet trucks. Logistics modernization drives new equipment demand.
- Distribution Centers:Focused on rapid throughput and order fulfillment, these facilities demand high volumes of order pickers and narrow-aisle trucks for inventory velocity. E-commerce expansion fuels this growth.
- Manufacturing Plants:Industrial trucks support production lines, moving raw materials and finished goods.
- Ports & Terminals:These heavy-duty environments utilize large capacity forklifts for container handling.
- Construction Sites:Rough terrain forklifts and specialized telehandlers are employed for lifting materials over uneven outdoor surfaces.
The Warehousing application requires robust, versatile equipment, contrasting with the Distribution Centers' need for speed and automation.
End User:
The end-user segmentation for industrial trucks is influenced by the margin pressures and operational efficiencies sought by different industry verticals.
- Logistics Providers:Third-party logistics (3PL) companies operate vast networks of warehouses, requiring flexible fleets for diverse client needs. They prioritize operational uptime and total cost of ownership.
- Retail Warehousing:This segment encompasses storage and distribution operations supporting retail chains, characterized by high SKU counts and rapid inventory turnover. E-commerce expansion necessitates efficient order picking.
- Food & Beverage Facilities:These environments demand strict hygiene and temperature control, influencing the selection of electric trucks.
- Chemical Plants:Specialized industrial trucks with explosion-proof features handle hazardous materials.
- Textile Manufacturers:Material handling involves moving large rolls of fabric and finished goods.
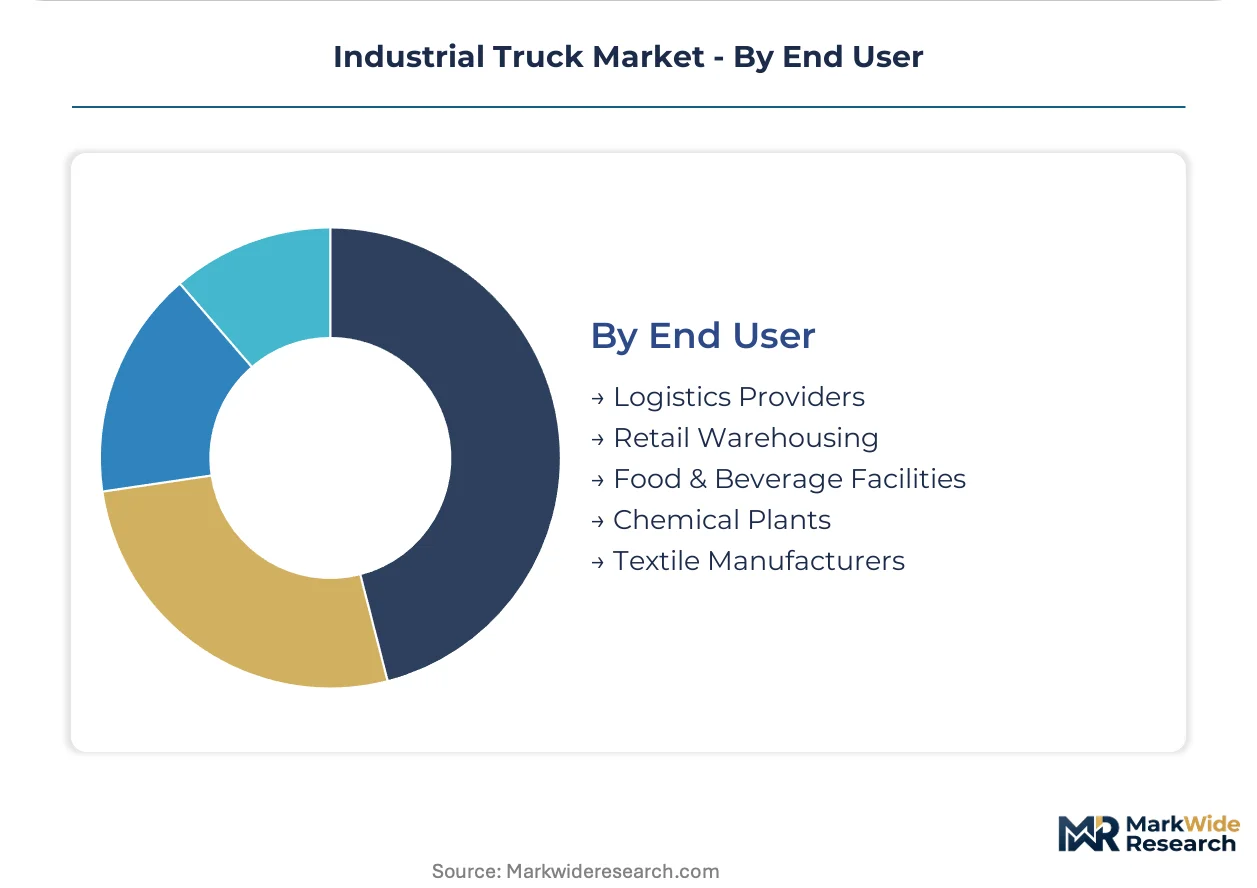
Logistics Providers prioritize fleet flexibility and low total cost of ownership, whereas Retail Warehousing focuses on inventory velocity and order fulfillment efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Distribution centers across the United States drive significant demand for industrial trucks, especially order pickers in e-commerce fulfillment. European manufacturing zones, particularly in Germany, also necessitate advanced material handling solutions. Developing economies in Latin America are simultaneously modernizing their logistics infrastructure.
United States
E-commerce expansion in the United States fuels substantial demand for order pickers and narrow-aisle trucks. US Occupational Safety and Health Administration (OSHA) regulations mandate stringent safety features across all powered industrial trucks. Major logistics hubs like the Dallas-Fort Worth region and California's Inland Empire see intensive adoption of automated guided vehicles.
Germany
Manufacturing zones in Germany require sophisticated industrial trucks for production line support and efficient material flow. European Union regulations, including CE marking and the Machinery Directive, enforce high safety and design standards. Automotive and machinery production centers in Bavaria and North Rhine-Westphalia integrate electric models for indoor applications.
China
China's industrial modernization and vast e-commerce sector generate strong demand for electric and automated material handling equipment. The Ministry of Ecology and Environment (MEE) enforces stringent emissions controls, accelerating the shift from internal combustion engines. Manufacturing and logistics hubs in the Yangtze River Delta and Pearl River Delta lead electric truck adoption.
Brazil
Logistics modernization in Brazil presents significant opportunities for replacing aging material handling equipment. National environmental standards increasingly favor electric models over diesel, impacting fleet acquisition decisions. Industrial and port logistics centers around São Paulo and Rio de Janeiro are upgrading to modern electric and safer forklift models.
Japan
Japan's focus on high-efficiency warehousing and precision manufacturing drives demand for advanced narrow-aisle and automated trucks. Japanese Industrial Standards (JIS) guide the design and safety of material handling equipment, ensuring operational reliability. Major distribution centers in the Kanto region and manufacturing facilities in Aichi Prefecture prioritize electric and autonomous solutions.
Industrial Truck Market Key Industry Players
Technology innovation dominates the current landscape, driving shifts in industrial truck design and operational functionality. The market exhibits a tiered structure, with established global players and specialized regional manufacturers competing for market share. Strategic archetypes include full-line solution providers offering comprehensive material handling solutions, niche technology developers focusing on specific power sources or automation, and regional service-focused entities. Portfolio diversification into electric and autonomous solutions, alongside strategic partnerships for advanced telematics, represents key competitive moves.
Within the global full-line solution provider archetype, Toyota Industries Corporation and KION Group AG represent established entities leveraging extensive R&D capabilities and broad product lines. Toyota Industries Corporation, a Japanese-based manufacturer, anchors a strong position through its automotive battery expertise and integration of advanced power systems. German-headquartered KION Group AG exemplifies a diverse portfolio of electric and autonomous solutions, catering to varied industrial applications. Anhui Heli Co., Ltd., a Chinese-based manufacturer, sits within the expanding segment of regional specialists, addressing localized demand and competitive pricing needs across Asian markets.
| Leading Market Players |
|---|
| Mitsubishi Logisnext Co., Ltd. |
| Crown Equipment Corporation |
| Toyota Industries Corporation |
| Clark Material Handling Company |
| Komatsu Ltd. |
| KION Group AG |
| Hyster-Yale Materials Handling Inc. |
| Anhui Heli Co., Ltd. |
| Jungheinrich AG |
Cost & Logistics Intelligence
Logistics providers' increasing reliance on flexible fleet solutions shapes a hybrid pricing model combining outright purchases with full-service leasing arrangements. This model shifts capital expenditure to operational expenditure for many end-users.
Pricing Analysis
Input cost pass-through from advanced battery systems and electronic components directly influences industrial truck pricing. The market features a hybrid pricing model, blending per-unit transactional sales for outright purchases with subscription-based full-service leasing options. Price differentiation stems from technology integration, such as advanced automation, and comprehensive after-sales support. Pricing softness reflects intense competition and the high initial acquisition cost of electric models. Small and medium-sized enterprises exhibit higher price sensitivity compared to large distribution centers prioritizing operational uptime.
Supply Chain Analysis
Lithium-ion battery cell supply rests heavily on key Asian producers, particularly in China, South Korea, and Japan. This creates material dependencies on critical inputs like lithium, cobalt, and nickel, alongside semiconductors for advanced control systems. A structural risk involves geopolitical supply chain disruptions and raw material price volatility. Distribution runs through established global OEM networks and regional dealer partnerships, providing sales and aftermarket support to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial truck market functions as a stable compounder, driven by the persistent global expansion of e-commerce and subsequent logistics modernization. This foundational demand ensures consistent, long-term growth across all segments.
For Market Incumbents: Acquire specialized software firms focusing on AI-driven fleet management and autonomous navigation to counter disruptive automation startups. Deepen vertical integration into advanced battery manufacturing or secure long-term supply agreements to mitigate supply chain volatility for critical components. Prioritize R&D in next-generation battery chemistries and AI algorithms to maintain technological leadership against emerging entrants.
For New Entrants and Emerging Players: Enter via niche automation solutions or specialized hydrogen fuel cell systems for high-throughput operations. The most penetrable segment remains small and medium-sized enterprises seeking cost-effective automation. A subscription-based "Automation as a Service" model can lower adoption barriers and provide a predictable revenue stream. Focus on regional service capabilities to differentiate from established global players.
For Investors and Strategic Acquirers: Industrial equipment specialists and logistics infrastructure funds are the most active acquirers in this space, seeking long-term value from electrification and automation. Focus on acquisition targets that offer advanced telematics, autonomous navigation software, or hydrogen fuel cell integration capabilities. A critical signal to watch is the acceleration of regulatory incentives for zero-emission industrial vehicles, which will further de-risk investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Battery R&D Investment | Developing next-generation lithium-ion systems enhances electric truck performance and extends operational uptime. |
| Autonomous Navigation Software Integration | Integrating AI-driven software enables predictable, labor-saving workflows in large distribution centers. |
| Full-Service Leasing Expansion | Offering comprehensive leasing models shifts capital expenditure burdens for third-party logistics providers. |
| Hydrogen Fuel Cell Portfolio Development | Expanding hydrogen options addresses niche demand for continuous, high-throughput 24/7 operations. |
| Technician Training Programs | Addressing the skill gap in advanced electronics servicing ensures operational reliability for end-users. |
Research Approach
Multiple input streams — industry association reports, OEM financial disclosures, and government regulatory updates — were reconciled to build a comprehensive market view. Primary interviews with plant engineers, logistics managers, and OEM procurement teams provided qualitative insights into operational challenges and technology adoption. This approach combined bottom-up market sizing with top-down validation, ensuring robust data integrity.
Data stream reconciliation informed the analytical framework, projecting market trajectories across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and regional adoption patterns. Compound Annual Growth Rates were derived from historical trends and projected future demand, influenced by e-commerce expansion and lithium-ion battery cost curves.
Inputs from major industrial truck OEMs and battery suppliers were available through the study window; gaps in emerging market adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Truck Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Refrigerated Truck Market