
 Seating and Positioning Belts Market | 2026-2036
Seating and Positioning Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Seating and Positioning Belts Market Analytics
Sensor-integrated smart restraint systems is narrowing the performance gap between passive belts and active monitoring solutions. Ottobock SE & Co. KGaA leverages its prosthetics biomechanics expertise to anchor positioning belt design in anthropometric data. Permobil AB competes through vertical control over powered seating actuators that interface with its restraint lines. Sunrise Medical LLC sustains geographic dominance across European rehabilitation channels through specialized distribution partnerships.
Seating and positioning belts comprise woven textile restraints with tensile strengths typically exceeding 5000 N, incorporating foam-padded contact surfaces and metal cam-lock or push-button buckles engineered to secure occupants in wheelchairs, vehicle seats, and clinical furniture. Their primary purpose is preventing falls, postural collapse, and shear injuries during transit or stationary use. Lap belts and adjustable belts capture the dominant share of medical rehabilitation procurement due to universal compatibility with sling-seat wheelchairs, while shoulder belts command premium positioning in aviation and commercial transport applications where multi-point restraint is mandatory. Booster seats represent the fastest-growing product category as pediatric mobility clinics expand postural support programs.
The EU Medical Device Regulation and FDA 510(k) pathway govern biocompatibility and mechanical testing requirements for clinical positioning belts, while ISO 16840 establishes wheelchair seating integrity standards that directly influence belt attachment point specifications. Japan's Ministry of Economy, Trade and Industry enforces JIS standards for elderly-care equipment that elevate minimum dynamic load thresholds. Stakeholders must monitor divergence between regional testing protocols and decide whether to pursue unified certification or maintain separate product variants.
Market Dynamics
The EU Medical Device Regulation's biocompatibility testing requirements are compressing supplier margins while simultaneously elevating entry barriers for textile restraint manufacturers serving European rehabilitation channels.
Growth Catalysts
- Japan's aged-care facility procurement standards:METI enforcement of elevated JIS dynamic load thresholds is institutionalizing belt replacement cycles across municipal eldercare networks.
- ISO 16840 wheelchair seating integrity standards:Attachment point specifications are harmonizing belt interface designs, reducing SKU complexity for manufacturers serving multiple clinical markets.
- Powered wheelchair actuator integration:Synchronized restraint positioning is creating technical stickiness between seating systems and belt suppliers in German rehabilitation procurement.
Market Restraints
- Medical-grade polymer fiber cost volatility:Specialized high-tenacity polyester and aramid inputs face petrochemical feedstock price swings that compress textile converter margins.
- Cam-lock buckle supplier concentration:Precision metal forming capacity clusters in Southern Germany and Northern Italy, creating single-source vulnerability for mid-tier belt assemblers.
- Shear injury liability exposure:Postural collapse litigation risk elevates product liability premiums beyond reach of emerging market entrants lacking clinical validation history.
Strategic Opportunities
- India's nascent pediatric mobility clinic network:Postural support program expansion in tier-2 cities offers first-mover positioning before regulatory harmonization with ISO standards.
- Aviation multi-point shoulder belt mandates:FAA cabin safety directives are opening premium positioning segments distinct from medical rehabilitation's price-sensitive procurement.
- Sensor-telemetry convergence:Pressure-mapping textiles and restraint-mounted accelerometers are enabling outcome-based service models in Japanese institutional purchasing.
Industry Challenges
- Biomechanical engineer talent scarcity:Anthropometric data interpretation and finite element modeling for occupant restraint design require specialized expertise concentrated in prosthetics and automotive safety programs.
- FDA 510(k) submission timeline compression:Predicate device identification and substantial equivalence documentation demands extend product launch cycles for novel foam-padded contact surface configurations.
- Legacy sling-seat wheelchair interface fragmentation:Non-standardized attachment point geometries across installed base equipment complicate universal belt compatibility claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seating and Positioning Belts Market |
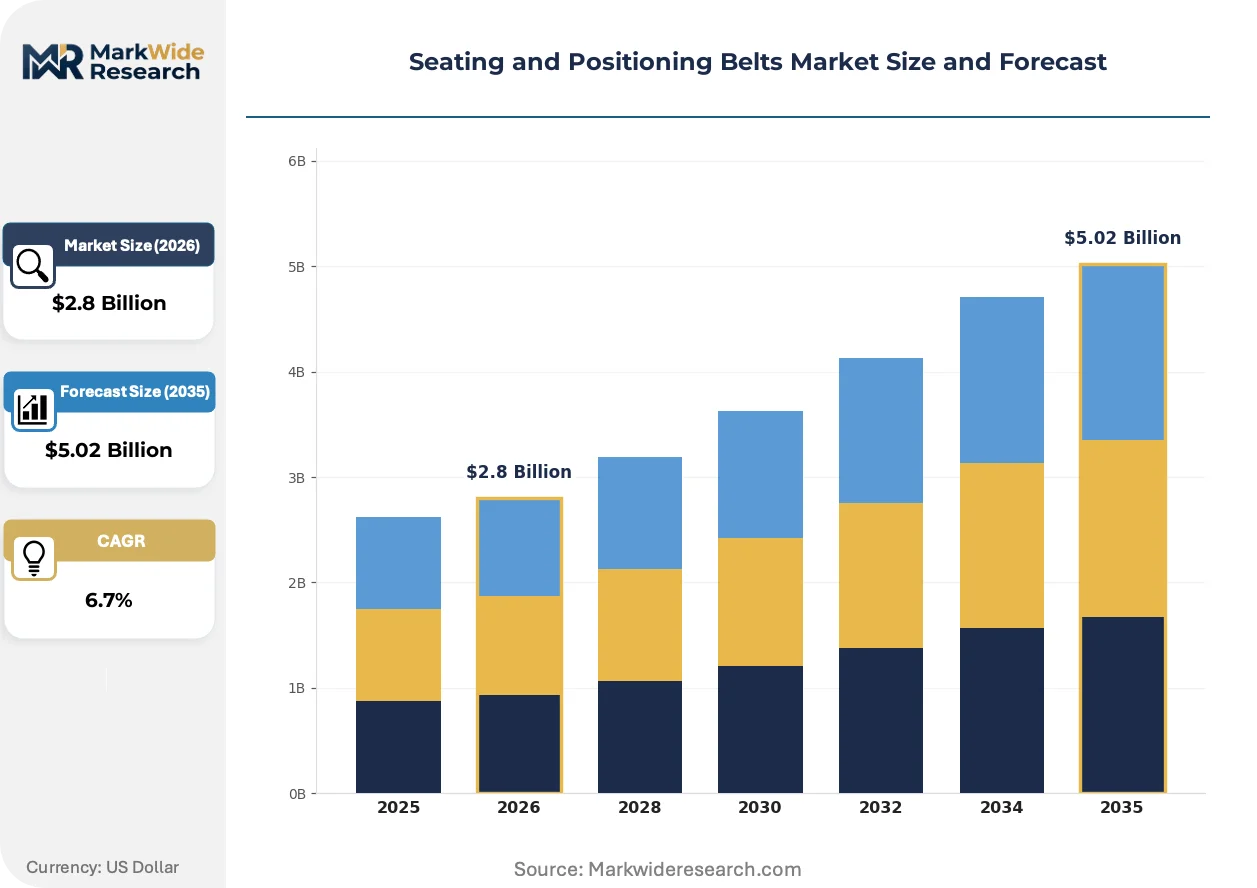
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lap Belts, Shoulder Belts, Adjustable Belts, Booster Seats End User: Child Safety, Elderly Care, Medical Rehabilitation, Commercial Transport Material: Nylon, Polyester, Foam Padding, Metal Application: Residential Use, Automotive, Aviation, Public Transport |
| Companies Covered | Sunrise Medical LLC, Ottobock SE & Co. KGaA, Invacare Corporation, Permobil AB, Drive DeVilbiss Healthcare, Numotion Inc., GF Health Products, Inc., Autoliv Inc., Joyson Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seating and Positioning Belts Market Evolving Landscape
Smart textile integration and regulatory harmonization pressures are bifurcating the supplier base between sensor-capable system integrators and commodity restraint fabricators.
Woven conductive fiber matrices embedded within restraint webbing are enabling real-time pressure distribution monitoring without compromising tensile integrity. German rehabilitation clinics are piloting these systems for pressure ulcer prevention protocols. The technology is hybridizing passive mechanical restraint with active clinical telemetry, compressing the historical separation between seating hardware and patient monitoring equipment.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports for all Class I medical device restraints, including legacy lap belt configurations previously exempt under the Medical Devices Directive. This regulatory burden is favoring incumbent manufacturers with established quality management systems. Smaller textile converters are responding by exiting direct EU market access and licensing designs to notified body-certified partners.
Institutional procurement in Japan's municipal eldercare sector is consolidating purchasing authority from facility-level decision-making to prefectural cooperative purchasing organizations. Group purchasing organizations are replacing distributor relationships as the primary commercial interface. This concentration is most visible in Hokkaido and Kyushu regional networks, where standardized tender specifications now favor suppliers offering multi-year maintenance and replacement scheduling.
Seating and Positioning Belts Market Segmentation
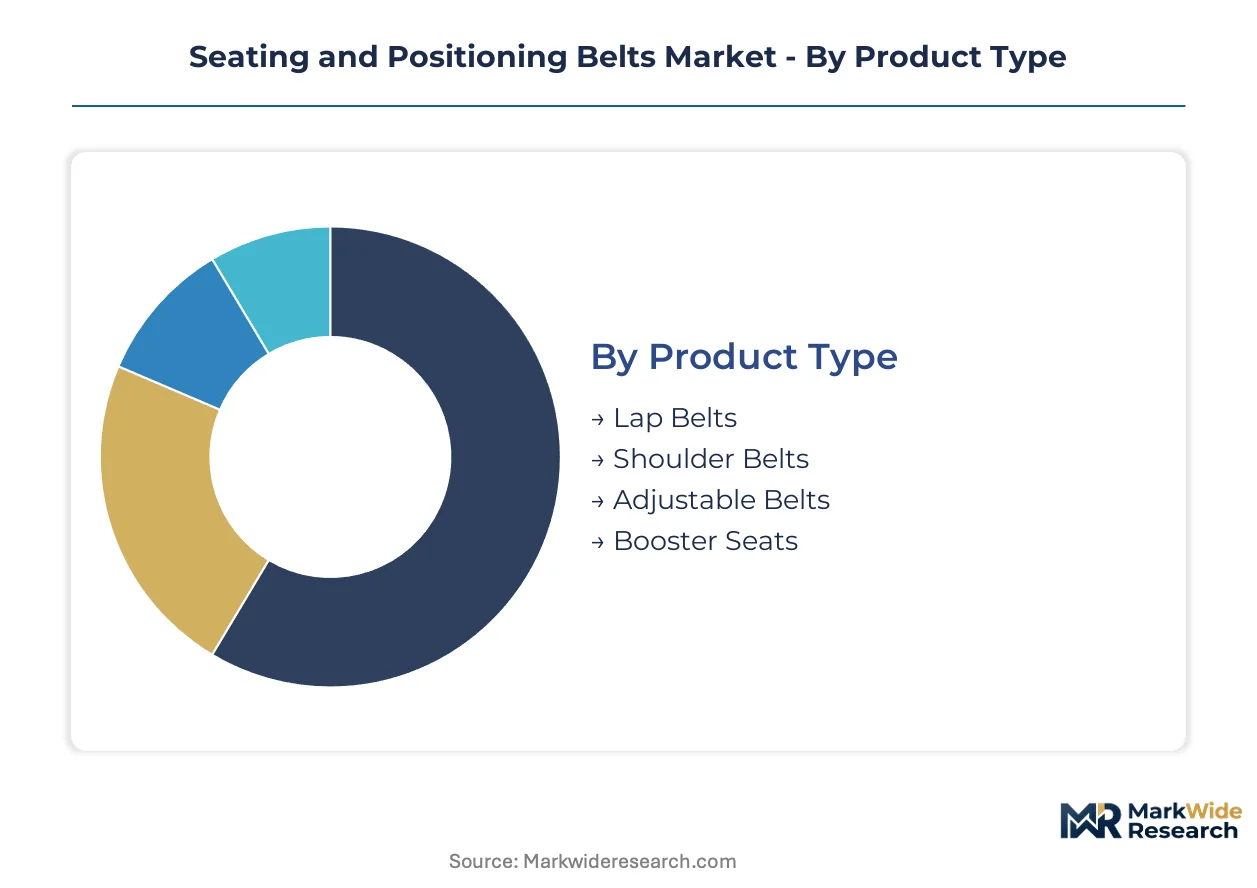
Segmentation in seating and positioning belts reveals how procurement patterns diverge across clinical, transport, and residential settings. Material specifications and attachment geometries vary sharply between powered wheelchair integrations and aviation multi-point systems, creating distinct supplier specialization zones.
Product Type:
Use-case spectrum spans passive mechanical restraint through active postural correction, with buckle mechanisms and webbing configurations calibrated to occupant mobility levels.
- Lap Belts:Woven high-tenacity polyester webbing with metal cam-lock buckles secures the pelvic region against forward excursion. Demand concentrates in German medical rehabilitation facilities procuring for sling-seat wheelchairs, driven by ISO 16840 attachment point harmonization reducing interface compatibility costs.
- Adjustable Belts:Multi-position strap systems with quick-release mechanisms accommodate varying anthropometric dimensions and seating geometries. Japan's municipal eldercare networks are standardizing these across institutional procurement, compelled by METI-enforced JIS dynamic load thresholds mandating replacement cycles.
- Shoulder Belts:Three-point and four-point configurations with torso-level anchoring prevent upper-body flexion during sudden deceleration. Aviation applications under FAA cabin safety directives dominate premium positioning.
- Booster Seats:Elevated seating platforms with integrated restraint systems position pediatric occupants for optimal belt fit. Pediatric mobility clinics in tier-2 Indian cities are expanding postural support programs.
The dominant share belongs to lap belts, while booster seats are closing the gap fastest.
End User:
Customer archetypes range from institutional procurement offices with multi-year maintenance contracts to individual caregivers prioritizing ease of installation.
- Medical Rehabilitation:Powered wheelchair users and post-surgical patients require dynamic positioning during seated activities. German rehabilitation channels exhibit synchronized restraint-actuator integration creating supplier technical stickiness.
- Elderly Care:Municipal eldercare facilities in Japan's Hokkaido and Kyushu networks are consolidating purchasing authority through prefectural cooperative organizations with standardized tender specifications.
- Child Safety:Pediatric mobility clinics and automotive child restraint systems demand compliance with evolving biomechanical safety standards.
- Commercial Transport:Aviation and motor coach operators face mandatory multi-point restraint regulations distinct from medical price-sensitive procurement.
Medical rehabilitation commands the largest procurement volume, though elderly care is expanding most quickly through institutional purchasing consolidation.
Material:
Raw material selection trades off tensile performance against biocompatibility certification burdens under tightening regulatory frameworks.
- Polyester:High-tenacity filament yarns deliver tensile strengths exceeding 5000 N with controlled elongation characteristics. Petrochemical feedstock price volatility compresses converter margins.
- Nylon:Polyamide fibers offer superior abrasion resistance and moisture management for high-cycle institutional applications.
- Foam Padding:Viscoelastic and polyurethane contact surfaces distribute pressure to prevent shear injuries and pressure ulcers. EU MDR clinical evaluation report requirements now extend to legacy configurations.
- Metal:Precision-formed cam-lock and push-button buckles from Southern German and Northern Italian suppliers create single-source vulnerability for mid-tier assemblers.
Polyester retains the dominant material position, with foam padding gaining share fastest under pressure-mapping textile convergence.
Application:
Installation environments dictate attachment geometry, dynamic load testing protocols, and regulatory compliance pathways.
- Automotive:Vehicle-integrated anchorage points and child restraint systems must satisfy NHTSA and equivalent national motor vehicle safety standards.
- Aviation:FAA cabin safety directives mandate multi-point shoulder restraint for commercial aircraft seating, opening premium segments.
- Residential Use:Home-based wheelchair and clinical furniture applications prioritize caregiver-operated quick-release mechanisms.
- Public Transport:Motor coach and rail seating systems face evolving accessibility mandates with high-occupancy cycle requirements.
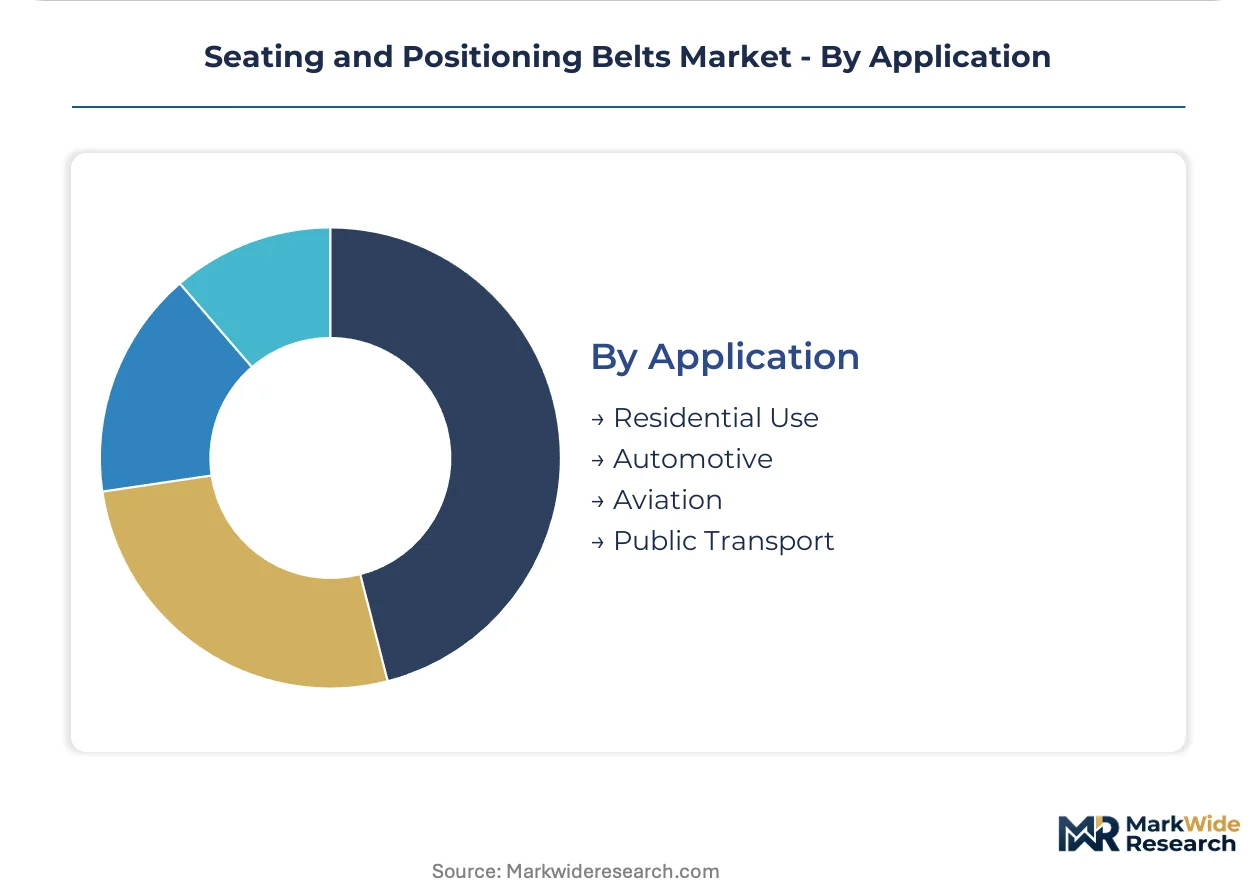
Automotive represents the most mature application base, while aviation is climbing the fastest on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rehabilitation procurement offices and Japanese municipal eldercare networks concentrate institutional purchasing power for positioning belts. These buyer archetypes drive standardization across supplier bases. Regional regulatory divergence shapes competitive access patterns.
Germany
Medical rehabilitation facilities in Bavaria and North Rhine-Westphalia expand powered wheelchair procurement with synchronized restraint-actuator integration. The EU Medical Device Regulation tightens biocompatibility testing requirements for restraint fabrics entering clinical channels. Precision metal forming capacity clusters in Southern Germany supply cam-lock buckle components to mid-tier belt assemblers.
Japan
Municipal eldercare networks in Hokkaido and Kyushu consolidate purchasing authority through prefectural cooperative organizations. METI enforces elevated JIS dynamic load thresholds that institutionalize belt replacement cycles across institutional networks. Tokyo-based rehabilitation equipment distributors pivot toward outcome-based service models incorporating sensor-telemetry convergence.
United States
Pediatric mobility clinics and FAA-regulated aviation operators represent distinct premium demand channels. The FDA 510(k) pathway governs mechanical testing requirements for clinical positioning belts. Greater Boston and Pacific Northwest rehabilitation hubs pilot pressure-mapping textile protocols for pressure ulcer prevention.
India
Tier-2 cities expand pediatric mobility clinic networks before regulatory harmonization with ISO standards. The country's national medical device regulator maintains divergent testing protocols from EU and US pathways. Maharashtra and Gujarat host emerging textile converter capacity targeting postural support program expansion.
Seating and Positioning Belts Market Competitive Landscape
Channel-controlling players compete with product-specialist players across rehabilitation and transport verticals. The supplier base exhibits moderate concentration with tiered specialization between medical device integrators and automotive safety fabricators. Three archetypes dominate: prosthetics-biomechanics specialists leveraging anthropometric data, powered seating system integrators with actuator control, and automotive safety suppliers diversifying into medical adjacent markets. Competitive moves center on vertical control over seating actuators and geographic distribution partnerships.
Among European rehabilitation equipment specialists, Ottobock SE & Co. KGaA and Permobil AB occupy positions anchored in clinical channel relationships. Sunrise Medical LLC exemplifies geographic dominance through specialized distribution structures. These three represent distinct strategic postures: prosthetics-derived biomechanics expertise, vertical control over powered seating systems, and European rehabilitation channel penetration.
| Leading Market Players |
|---|
| Sunrise Medical LLC |
| Ottobock SE & Co. KGaA |
| Invacare Corporation |
| Permobil AB |
| Drive DeVilbiss Healthcare |
| Numotion Inc. |
| GF Health Products, Inc. |
| Autoliv Inc. |
| Joyson Safety Systems |
| Others |
Value Network & Pricing Analysis
Precision metal forming capacity clustering in Southern Germany and Northern Italy feeds cam-lock buckle components to mid-tier belt assemblers, concentrating margin capture upstream while downstream pricing power fragments across distributor and GPO channels. Medical-grade polymer fiber cost volatility from petrochemical feedstock swings compresses textile converter margins, forcing pricing discipline onto raw material indexation clauses.
Pricing Analysis
Cost-plus contracts with quarterly polyester and aramid fiber indexation dominate procurement between German rehabilitation channels and belt manufacturers. Pricing stratifies across premium sensor-integrated systems, standard ISO 16840-certified configurations, and economy-grade lap belts without biocompatibility documentation. Cost compression in standard-tier products is intensifying because EU MDR clinical evaluation report requirements extend to legacy foam-padded configurations previously exempt. Medical rehabilitation facilities exhibit highest price sensitivity due to municipal budget constraints, while aviation operators under FAA mandates show lowest sensitivity for multi-point shoulder systems.
Supply Chain Analysis
Tariff exposure between Germany and Northern Italy dominates supply chain risk planning for precision buckle components. High-tenacity polyester filament production concentrates in China, Germany, and the United States, while medical-grade foam padding sources from specialized converters in Japan and Switzerland. Single-source vulnerability in Southern German cam-lock forming capacity threatens mid-tier assemblers lacking dual-qualified suppliers. Distribution runs through regional rehabilitation equipment distributors in Europe, prefectural cooperative purchasing organizations in Japan, and specialized GPOs in North American hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from multi-year maintenance and replacement scheduling expands faster than hardware sales, particularly in Japan's municipal eldercare networks where prefectural GPOs bundle outcome-based telemetry services with belt procurement.
For Market Incumbents: Entrench technical stickiness through powered wheelchair actuator synchronization that locks rehabilitation clinics into integrated seating-restraint systems. Deepen backward integration into precision metal forming capacity to neutralize Southern German supplier concentration risk. Prioritize EU MDR notified body certification maintenance as smaller textile converters exit direct market access, consolidating channel control for compliant incumbents. For New Entrants and Emerging Players: Pursue India's tier-2 pediatric mobility clinic expansion before ISO standard harmonization raises compliance barriers. Target aviation multi-point shoulder belt segments where FAA mandates create premium positioning insulated from medical rehabilitation price sensitivity. Lead with pressure-mapping textile pilots in Greater Boston rehabilitation hubs to establish clinical validation credentials before scaling manufacturing footprint. For Investors and Strategic Acquirers: Capital is best deployed toward sensor-telemetry system integrators with established Japanese institutional purchasing relationships and proprietary pressure-mapping IP. Five-to-ten year viability hinges on outcome-based service model transition rather than commodity restraint fabrication. Watch for inflection when METI extends JIS dynamic load threshold enforcement beyond Hokkaido and Kyushu to national municipal networks, accelerating replacement cycle revenue predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Telemetry Integration | Pressure-mapping textiles enable outcome-based service contracts in Japanese eldercare procurement. |
| EU MDR Notified Body Certification | Clinical evaluation report requirements favor incumbents with established quality management systems. |
| Prefectural GPO Partnership | Consolidated purchasing authority in Hokkaido and Kyushu rewards multi-year maintenance bundling. |
| Aviation Multi-Point Certification | FAA cabin safety directives open premium segments distinct from medical price competition. |
| Backward Integration into Metal Forming | Captive cam-lock buckle production neutralizes Southern German supplier concentration vulnerability. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rehabilitation equipment procurement managers, biomedical engineers, GPO contracts specialists, and prefectural eldercare purchasing officers; and secondary validation against FDA 510(k) filings, EU MDR notified body certificates, JIS standard enforcement bulletins, and hospital procurement database extracts. Bottom-up demand modeling across product type, end user, material, and application segments triangulated against top-down macroeconomic indicators and healthcare expenditure trends.
Forecast inputs considered powered wheelchair actuator integration rates, METI enforcement timeline expansion for JIS thresholds, and FAA mandate adoption curves across commercial aviation fleets. Segmentation dimensions modeled include product configuration, institutional versus individual procurement channel, certification tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and elasticity-adjusted price trajectory assumptions.
Sensitivities concentrate around EU MDR implementation timeline delays, polyester feedstock price volatility, and Japanese municipal budget cycle fluctuations. Forecasts reflect documented assumptions regarding regulatory harmonization progress and institutional purchasing consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Car Modification Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Rolling Stock LED Lights Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Engine Components Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Europe Automotive Connectors Market