
 Electric Vehicle Battery Enclosure Market | 2026-2036
Electric Vehicle Battery Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Enclosure Market Insights
The EU Battery Regulation is repositioning enclosure material selection across European supply chains. Novelis Inc. leverages its closed-loop aluminum recycling infrastructure to meet circularity mandates. ThyssenKrupp AG anchors its position through integrated steel-aluminum hybrid solutions for structural battery protection. Nemak S.A.B. de C.V. specializes in high-pressure die-casting expertise for complex enclosure geometries.
An electric vehicle battery enclosure is a structural housing that contains and protects battery cells, modules, or packs from mechanical impact, thermal events, and environmental ingress, typically fabricated from aluminum extrusions, steel stampings, or fiber-reinforced composites with specified crash-load and fire-resistance ratings. Its primary purpose is to maintain cell positional integrity during collisions while managing heat dissipation pathways and sealing against water and dust intrusion. Aluminum dominates product type selection due to its strength-to-weight ratio and compatibility with gigacasting integration, while composite segments attract R&D investment for next-generation thermal barrier performance. Die casting leads manufacturing stage adoption as OEMs consolidate enclosure production with larger structural castings, whereas stamping retains share in cost-optimized steel platforms.
FDA guidelines on workplace safety during battery assembly, EPA emissions frameworks for manufacturing facilities, and NHTSA crashworthiness standards collectively shape enclosure design loads and material certification requirements in the United States. ECHA REACH compliance and CE marking obligations in Europe restrict certain flame-retardant chemistries and mandate supply chain disclosure for imported aluminum and steel. Stakeholders must monitor evolving cell-to-pack architectures that eliminate module-level enclosures entirely, forcing suppliers to recalibrate whether their value resides in material supply, structural design, or integrated thermal management.
Market Dynamics
Cell-to-pack architectures are compressing enclosure volumes by eliminating module-level housings, forcing suppliers to pivot from selling stamped metal boxes toward integrated thermal-structural systems that manage crash loads and fire containment simultaneously.
Growth Catalysts
- China's NEV mandate:Binding production quotas for new energy vehicles compel domestic OEMs to source lightweight aluminum enclosures at scale, tightening supply-demand balances for extrusion-grade alloys.
- Aluminum gigacasting integration:Single-piece casting processes consolidate floor pan and enclosure sidewalls, reducing part count and assembly labor for high-volume EV platforms.
- Thermal runaway standards:UN ECE R100 and China's GB 38031 mandate barrier performance between cells, driving specification upgrades for fire-resistant enclosure materials.
Market Restraints
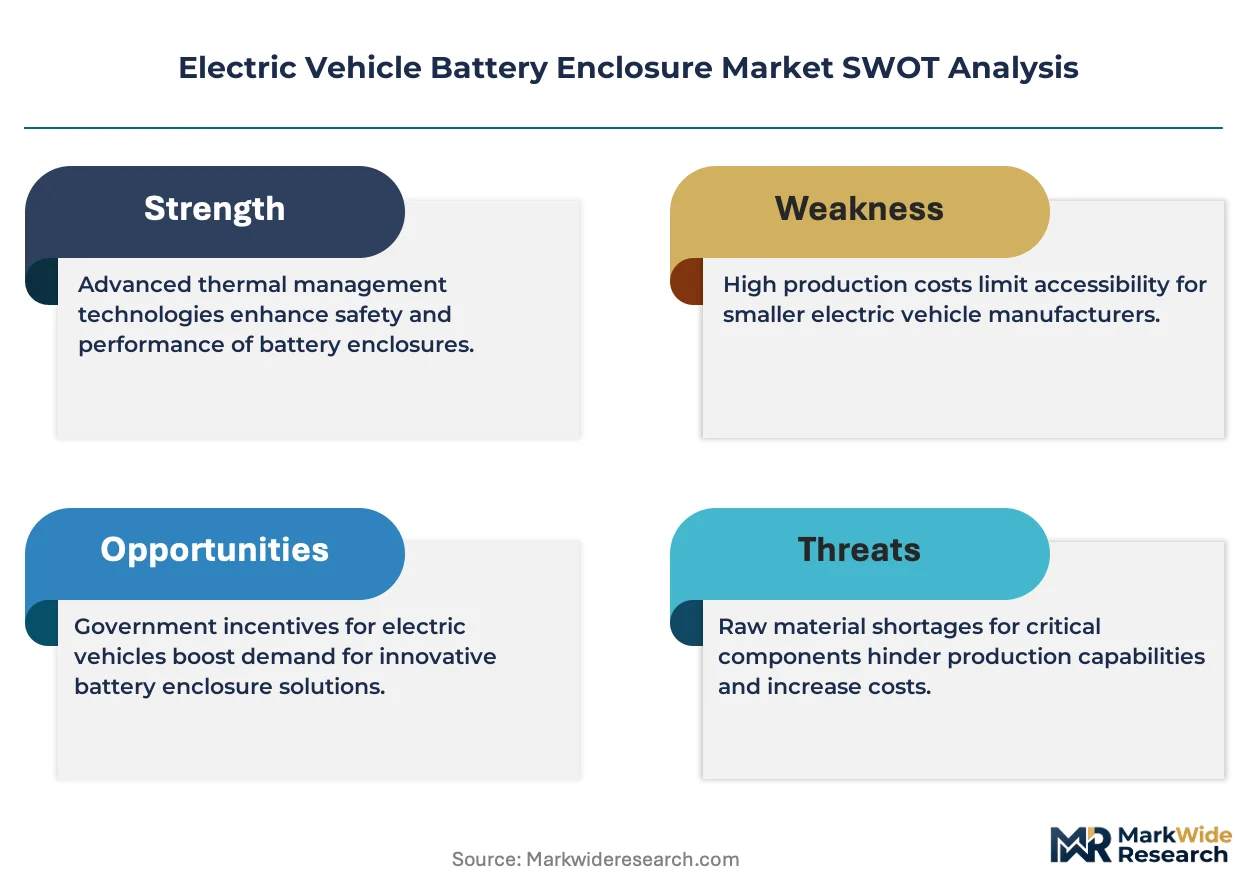
- Primary aluminum price volatility:Smelter energy costs and LME trading spreads compress margin predictability for enclosure fabricators locked into annual supply contracts.
- Scrap segregation requirements:EU Battery Regulation traceability rules force closed-loop recycling investments that smaller stampers cannot finance, concentrating supply among integrated metal producers.
- Steel cost advantage in mass-market segments:High-strength steel stampings retain share in entry-range EVs where aluminum's weight savings fail to justify material cost premiums.
Strategic Opportunities
- India's PLI scheme for ACC battery manufacturing:Subsidized gigafactory construction creates captive demand for localized enclosure production serving two-wheeler and four-wheeler OEMs.
- Fiber-reinforced composite barriers:Glass- and carbon-fiber sandwich panels integrated between cell rows offer thermal isolation without metallic conductivity, opening specialty tier-2 supply positions.
- Second-life battery housing refurbishment:Remanufacturing standards for stationary energy storage extend enclosure service cycles, creating aftermarket revenue streams distinct from virgin production.
Industry Challenges
- Multi-material welding expertise:Joining aluminum extrusions to steel reinforcements or composite inserts demands process engineers scarce in traditional automotive body-in-white operations.
- Fire-resistance certification timelines:UL 9540A and UN 38.3 test protocols require months of cell-level abuse testing before enclosure designs gain platform approval, compressing development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Enclosure Market |
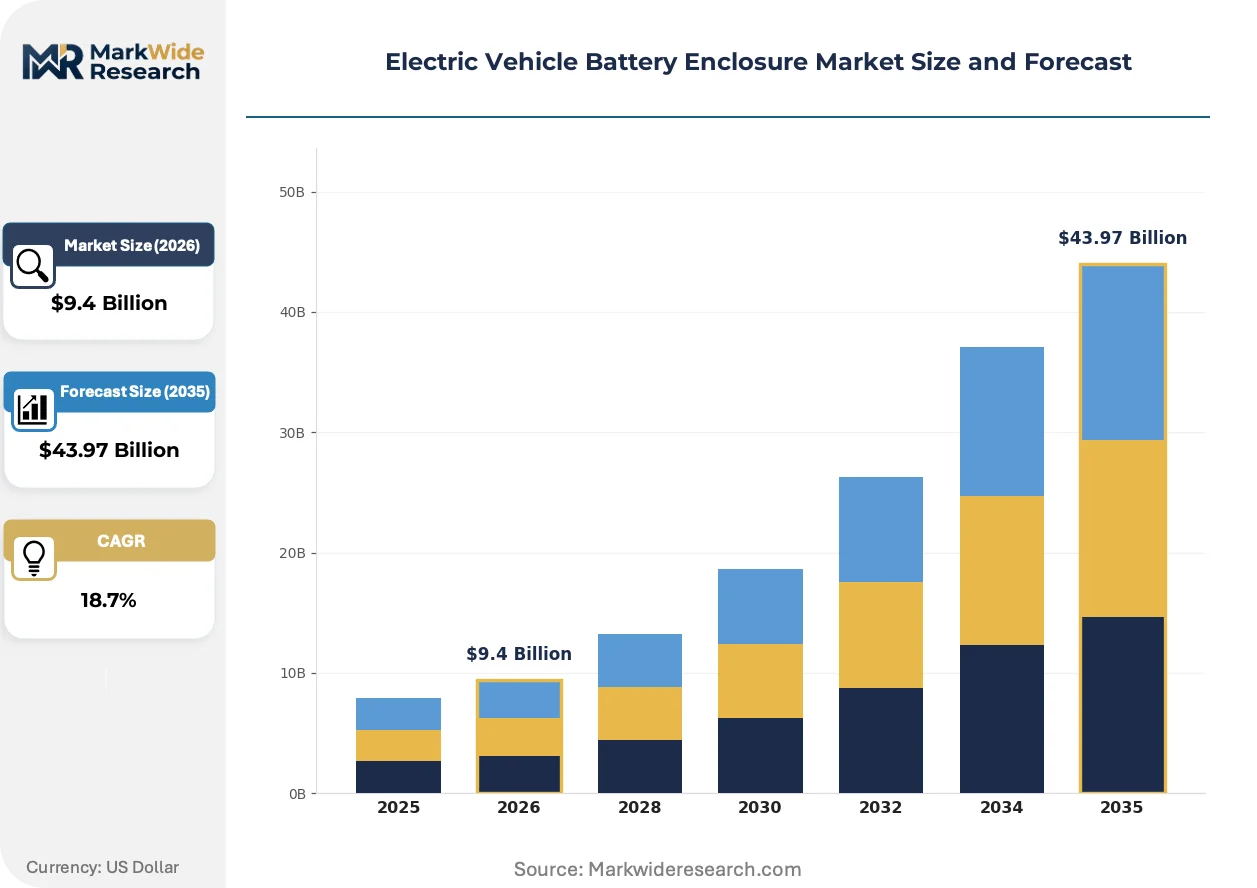
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $43.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Steel, Composite Manufacturing Stage: Injection Molding, Extrusion, Die Casting, Stamping End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, OEMs Connectivity: Wired, Wireless, Bluetooth, CAN Bus |
| Companies Covered | Novelis Inc., ThyssenKrupp AG, Nemak S.A.B. de C.V., Magna International Inc., Gestamp Automocion S.A., SGL Carbon, Constellium SE, UACJ Corporation, Hitachi Metals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Enclosure Market Trends and Innovations
Enclosure engineering is pivoting from passive structural shells toward active thermal management substrates, with material selection now governed by heat dissipation coefficients and dielectric properties alongside crashworthiness metrics.
Cell-to-pack structural battery trays are electrifying enclosure design by embedding cooling channels directly into aluminum extrusion profiles. Premium OEMs in Germany and South Korea have adopted these integrated designs for 800-volt architectures. The technology is electrifying supplier hierarchies as thermal management specialists capture value previously held by metal stampers.
REACH authorization restrictions on halogenated flame retardants are compelling European enclosure fabricators to validate phosphorus-based and mineral-fill alternatives. ECHA substance-of-very-high-concern listings now cover legacy brominated chemistries common in battery barrier foams. German and French OEMs are responding by qualifying magnesium hydroxide-loaded polypropylene sheets for inter-cell insulation layers.
Fleet operators and battery leasing companies are consolidating procurement decisions at the pack-system level rather than sourcing enclosures as discrete commodities. This channel compression bypasses traditional tier-1 metal suppliers, favoring integrated battery manufacturers with in-house structural engineering capabilities. The shift is most pronounced in North American commercial vehicle electrification programs where total-cost-of-ownership contracts bundle hardware and thermal management responsibility.
Electric Vehicle Battery Enclosure Market Segmentation
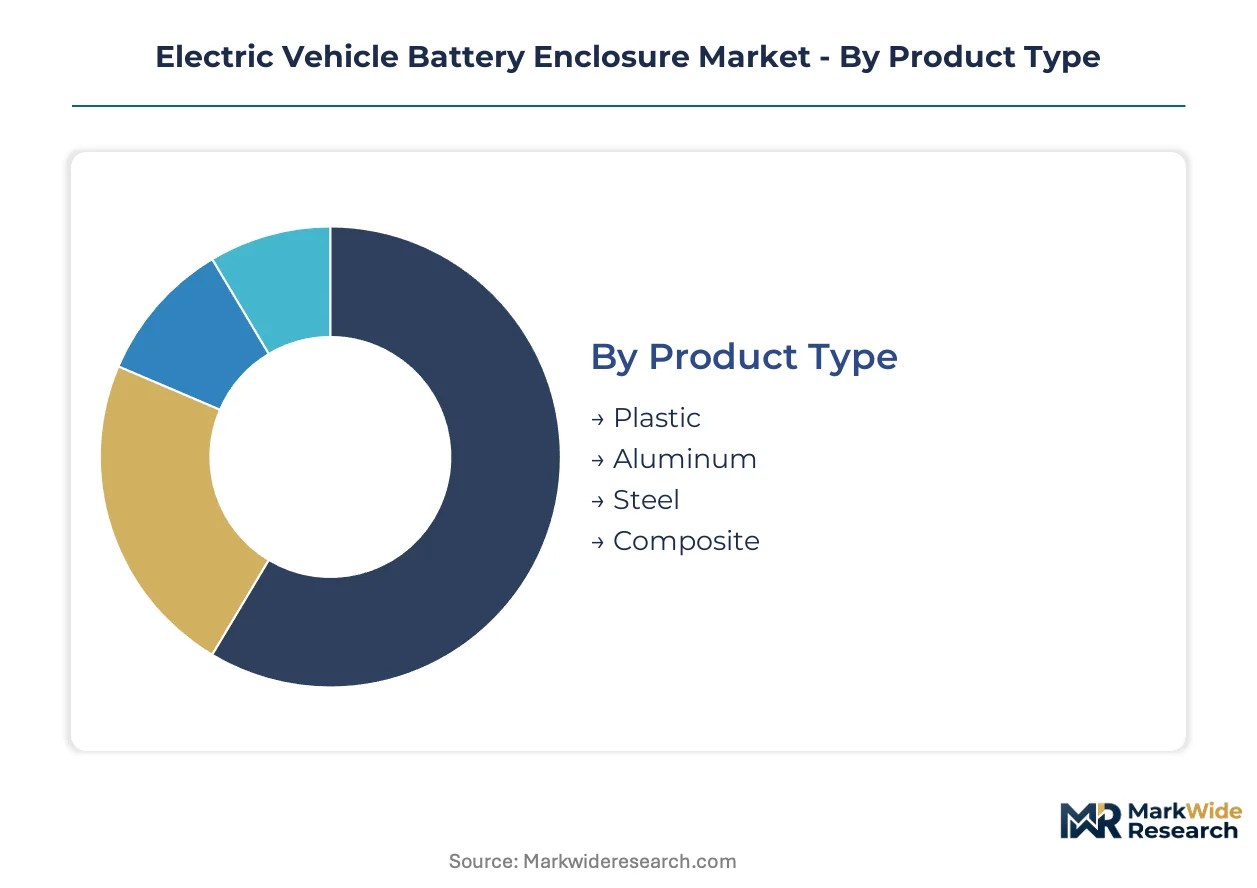
Electric vehicle battery enclosure segmentation reveals how material selection and manufacturing method determine regulatory compliance pathways. Certification requirements from NHTSA, ECHA REACH, and China's GB standards vary sharply across product categories, forcing suppliers to align technical capabilities with specific approval burdens.
Product Type:
Aluminum and steel enclosures carry distinct certification obligations under UN ECE R100 and EPA emissions frameworks, while composite and plastic variants face separate flame-retardant testing protocols.
- Aluminum:Extrusion-grade alloys with strength-to-weight ratios of 150-200 MPa tensile strength dominate premium passenger EV platforms. German and South Korean automakers specify these for 800-volt architectures where crash-load management and thermal conductivity must coexist. GB 38031 barrier performance mandates in China tighten alloy purity requirements for fire-resistant grades.
- Steel:High-strength stampings from dual-phase and press-hardened grades retain cost advantage in entry-range EVs. US mass-market OEMs source these where aluminum's weight savings fail to justify material premiums under IRA domestic content rules. NHTSA crashworthiness standards drive thickness specifications for side-impact protection.
- Composite:Glass- and carbon-fiber sandwich panels with mineral-fill cores offer dielectric thermal isolation between cell rows. Specialty tier-2 suppliers in France and Japan qualify these for inter-cell barriers under ECHA REACH phosphorus-based flame-retardant approvals.
- Plastic:Injection-molded structural polymers with magnesium hydroxide loading serve secondary enclosure components and cable routing channels. Chinese two-wheeler OEMs specify these for cost-optimized NEV platforms with reduced thermal management demands.
Aluminum sits at the top of the volume ranking, with composite climbing the fastest as 800-volt architectures proliferate.
Manufacturing Stage:
Process selection determines capital intensity and labor content, with die casting and extrusion requiring fundamentally different facility investments than stamping or molding.
- Die Casting:Single-piece gigacasting consolidates floor pan and enclosure sidewalls, eliminating 40-70 joints per vehicle. Tesla's Austin and Berlin facilities anchor this process for high-volume platforms. The method demands 6,000-9,000 ton press investments that concentrate supply among integrated metal producers.
- Extrusion:Hollow aluminum profiles with embedded cooling channels enable cell-to-pack thermal-structural integration. German premium OEMs specify these for structural battery trays where heat dissipation coefficients govern material selection. Process expertise concentrates in Austrian and Chinese supply bases.
- Stamping:Progressive die forming of steel grades retains share where annual volumes fall below gigacasting break-even thresholds. Indian and Southeast Asian suppliers serve regional OEMs with cost-optimized tool-and-die investments.
- Injection Molding:High-pressure polymer forming produces complex geometries for cable glands, venting components, and secondary housings. Tooling amortization favors this method for platforms below 50,000 annual units.
Die casting commands the highest capital allocation, while extrusion gains share fastest through thermal management integration.
End User:
Procurement authority is shifting from discrete component sourcing toward pack-system integration, altering which stakeholders specify enclosure designs.
- Automakers:Volkswagen, BYD, and Hyundai retain direct enclosure specification for proprietary cell-to-pack architectures. These OEMs integrate thermal management responsibility in-house, bypassing traditional tier-1 metal suppliers for structural battery tray design.
- Tier-1 Suppliers:Contemporary Amperex Technology and LG Energy Solution bundle enclosure engineering with cell manufacturing for leased battery programs. North American commercial vehicle electrification contracts consolidate procurement decisions at this level.
- OEMs:Battery leasing companies and fleet operators in European and North American markets specify refurbishment standards for second-life stationary storage. Remanufacturing protocols extend enclosure service cycles beyond automotive retirement.
- Aftermarket Providers:Independent repair networks and collision shops source replacement enclosures for crash-damaged vehicles. Fragmented demand characterizes this channel with limited standardization across vehicle platforms.
Automakers hold the largest specification authority, with tier-1 suppliers expanding fastest through battery leasing integration.
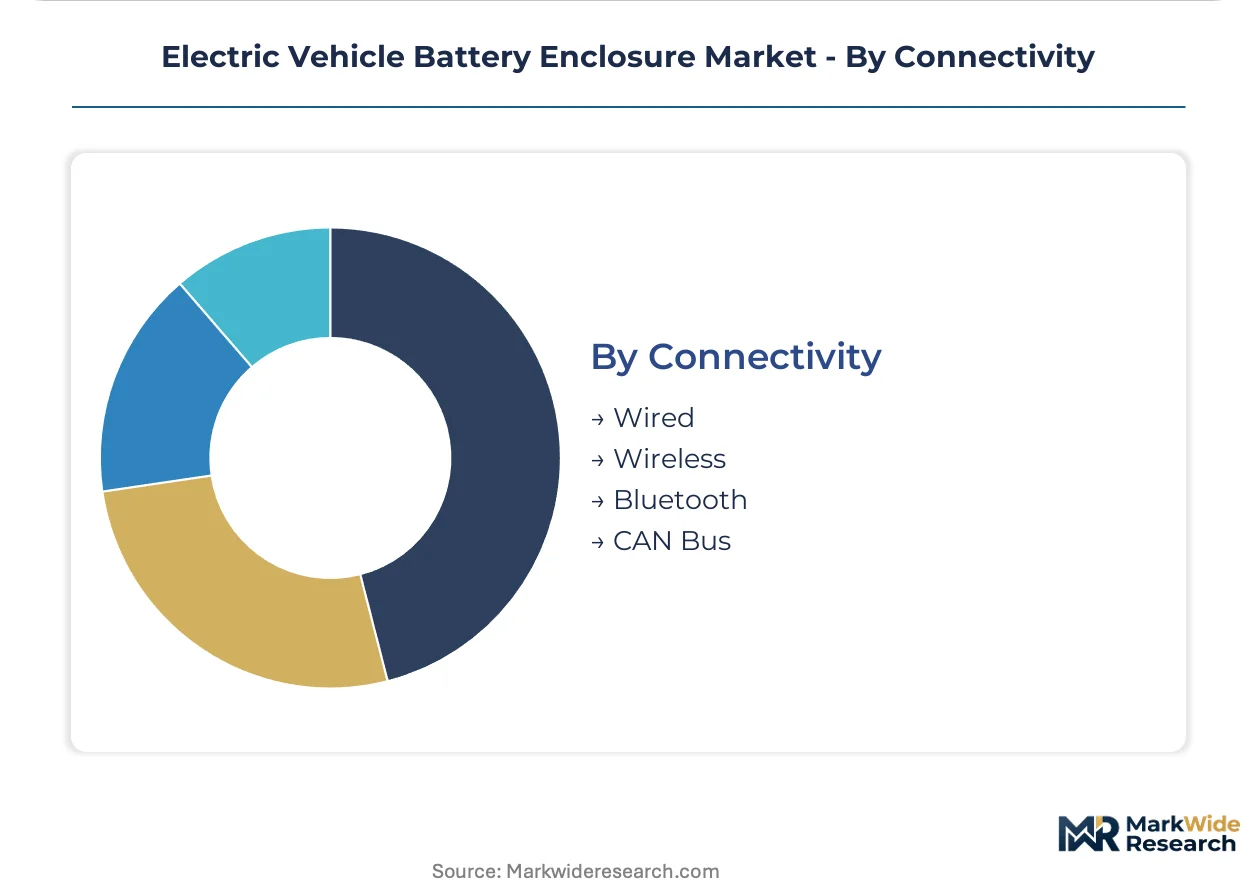
Connectivity:
Data transmission architecture within enclosures determines sensor placement and wiring complexity, with implications for electromagnetic compatibility certification.
- CAN Bus:Controller Area Network protocols dominate real-time thermal and voltage monitoring within battery management systems. Automotive-grade shielding requirements under ISO 11898 govern cable routing through enclosure penetrations.
- Wired:Dedicated high-voltage interlock loops and temperature sensor harnesses provide deterministic signal paths for safety-critical functions. German and Japanese OEMs specify these for fault-tolerant architectures.
- Wireless:Low-power radio frequency modules enable predictive maintenance data extraction without physical service access. Emerging qualification for sealed enclosure environments where connector corrosion risks dominate.
- Bluetooth:Diagnostic and configuration interfaces for service technicians operate in unlicensed spectrum with range limitations. Secondary status applications rather than primary battery management functions.
CAN Bus maintains the highest installation base, with wireless expanding most quickly through predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum-intensive battery enclosures first achieved industrial scale in Germany's automotive corridor during the early 2010s, establishing the technical foundations that Chinese and South Korean producers later adapted for mass-market EV platforms.
China
Domestic OEMs source extrusion-grade aluminum enclosures at volume under binding NEV production quotas. GB 38031 thermal barrier standards tighten alloy purity specifications for fire-resistant grades. Shanghai and Shenzhen clusters concentrate gigacasting investments that consolidate floor pan and enclosure sidewall production.
Germany
Premium automakers specify 800-volt structural battery trays with embedded cooling channels. ECHA REACH authorization restrictions on halogenated flame retardants compel validation of phosphorus-based alternatives. Bavaria's aluminum extrusion specialists supply integrated thermal-structural systems to Stuttgart and Munich engineering centers.
United States
Mass-market OEMs balance aluminum weight savings against IRA domestic content requirements for high-strength steel alternatives. NHTSA crashworthiness standards drive thickness specifications for side-impact protection. Michigan and Ohio stamping operations serve regional EV assembly plants with cost-optimized tool-and-die investments.
South Korea
Battery manufacturers bundle enclosure engineering with cell production for leased vehicle programs. MFDS workplace safety guidelines intersect with UN ECE R100 certification timelines for platform approval. Gyeonggi-do and Chungnam provinces host integrated pack-system facilities that bypass traditional tier-1 metal suppliers.
India
PLI scheme subsidies for ACC battery manufacturing create captive demand for localized enclosure production. BIS certification requirements for automotive-grade aluminum extrusions concentrate supply among integrated metal producers. Tamil Nadu and Gujarat gigafactory construction attracts tier-2 suppliers serving two-wheeler and four-wheeler OEMs.
Electric Vehicle Battery Enclosure Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across enclosure fabrication, creating a tiered structure where integrated metal companies with smelter and recycling assets face specialized die-casting and extrusion houses. The vendor base spans aluminum rolling specialists, steel-aluminum hybrid solution providers, and high-pressure die-casting experts. Three archetypes dominate: closed-loop recyclers leveraging circularity mandates, thermal-structural integrators capturing cell-to-pack value, and composite barrier specialists qualifying dielectric alternatives. Competitive moves concentrate on M&A for recycling infrastructure and strategic partnerships for gigacasting capacity.
Among North American aluminum specialists, Novelis Inc. and Magna International Inc. occupy positions within the closed-loop recycling and integrated manufacturing tiers respectively. ThyssenKrupp AG anchors the European steel-aluminum hybrid segment. Japanese fabricators UACJ Corporation and Hitachi Metals Ltd. represent the precision extrusion archetype serving 800-volt thermal management requirements. Mexican die-casting expertise through Nemak S.A.B. de C.V. exemplifies the high-pressure forming specialization for complex enclosure geometries.
| Leading Market Players |
|---|
| Novelis Inc. |
| ThyssenKrupp AG |
| Nemak S.A.B. de C.V. |
| Magna International Inc. |
| Gestamp Automocion S.A. |
| SGL Carbon |
| Constellium SE |
| UACJ Corporation |
| Hitachi Metals Ltd. |
| Others |
Pricing and Supply Chain Analysis
Cell-to-pack architecture mandates from German and South Korean OEMs are compressing enclosure specifications toward integrated thermal-structural systems, forcing aluminum extruders and die-casters to absorb R&D costs for cooling-channel embedding while steel stampers capture residual demand in cost-optimized platforms. This specification shift concentrates pricing power among integrated metal producers with captive recycling infrastructure, squeezing margin buffers for standalone fabricators locked into annual supply contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates 800-volt aluminum extrusion systems from gigacast structural trays and high-strength steel stampings. Price differentiation rests on certification grade for UN ECE R100 thermal barrier performance and volume scale for gigacasting break-even thresholds. Cost compression in entry-range steel platforms is intensifying because IRA domestic content rules constrain aluminum sourcing flexibility. Fleet operators and battery leasing companies exhibit the highest price sensitivity through total-cost-of-ownership contracting, while premium German automakers show the least sensitivity for crash-load-rated aluminum grades.
Supply Chain Analysis
Process engineering talent shortages in Shanghai, Shenzhen, and Bavaria are constraining expansion timelines for gigacasting and precision extrusion facilities. Supply concentrates in China, Germany, and the United States, with raw material dependencies on extrusion-grade aluminum alloys, high-strength steel coils, and phosphorus-based flame-retardant chemistries. Single-source vulnerability runs through Austrian and Chinese aluminum extrusion specialists serving 800-volt thermal management requirements. Distribution runs through pack-system integrators at tier-1 battery manufacturers, bypassing traditional discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle battery enclosure market functions as a stable compounder anchored by binding regulatory mandates for thermal runaway protection that perpetually refresh specification cycles across successive EV platform generations.
For Market Incumbents: Extend closed-loop recycling capabilities into European supply chains to capture circularity premiums under EU Battery Regulation traceability rules. Deepen captive supply of extrusion-grade alloys to offset primary aluminum price volatility that threatens margin predictability. Defend against integrated battery manufacturers by embedding thermal management expertise directly into structural tray designs. For New Entrants and Emerging Players: Enter via fiber-reinforced composite barrier specialization for inter-cell thermal isolation in 800-volt architectures, where dielectric performance requirements outpace incumbent metal-forming capabilities. Target India's PLI-subsidized ACC gigafactory clusters for localized enclosure production serving two-wheeler and four-wheeler OEMs. Qualify phosphorus-based flame-retardant alternatives ahead of ECHA REACH authorization restrictions to secure European OEM qualification pipelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap die-casting specialists possessing 6,000-ton press capacity and existing relationships with South Korean battery manufacturers. Long-term viability hinges on positioning for cell-to-pack architecture proliferation rather than module-level enclosure replacement. Watch for MFDS and NHTSA thermal barrier test protocol harmonization as the signal indicating accelerated platform approval timelines and consolidation pressure on sub-scale stampers.| Strategic Initiative | Industry Significance |
|---|---|
| Gigacasting Capacity Expansion | Consolidates floor pan and enclosure production, eliminating 40-70 joints per Tesla and Volkswagen platforms. |
| Closed-Loop Recycling Infrastructure | Novelis leverages smelter assets to meet EU Battery Regulation aluminum traceability mandates. |
| Cell-to-Pack Thermal Integration | Embeds cooling channels directly into aluminum extrusions for Hyundai and BMW 800-volt architectures. |
| Phosphorus-Based Flame Retardant Qualification | Replaces halogenated chemistries under ECHA REACH restrictions for German and French OEM barrier foams. |
| Second-Life Refurbishment Standards | Extends enclosure service cycles for stationary storage applications in European battery leasing programs. |
Research Methodology
Direct dialogue with OEM platform engineers, tier-1 battery manufacturer procurement leads, aluminum extrusion plant managers, and thermal management system architects grounded the qualitative foundation of this study. Secondary validation drew from NHTSA crashworthiness filings, ECHA REACH substance registrations, GB 38031 certification databases, and vehicle production data from IHS Markit. Bottom-up enclosure demand modeling triangulated against top-down EV production forecasts across the analysis window.
Segmentation outputs by material type, manufacturing process, and end-user procurement authority reflect granular assumptions for aluminum gigacasting penetration, steel stamping retention in IRA-constrained platforms, and composite barrier adoption in 800-volt architectures. CAGRs were derived from regression analysis of historical enclosure content per vehicle against projected EV platform launches. Key inputs included cell-to-pack architecture transition timelines, NEV mandate quota trajectories, and thermal runaway standard implementation schedules.
Inputs from OEM engineering centers and tier-1 supplier facilities were available through the study window; gaps in proprietary alloy formulation roadmaps and unannounced platform specifications introduce uncertainty bands around extrusion-grade adoption curves. Forecasts reflect documented assumptions regarding regulatory harmonization and technology cost curves. Material deviation in NHTSA thermal barrier rulemaking, ECHA REACH authorization timelines, or Chinese NEV mandate enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Hoverboard Scooter Market