
 Malaysia Refrigerated Trailer Market | 2026-2036
Malaysia Refrigerated Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Refrigerated Trailer Market Insights
Aluminum is consolidating its position as the dominant panel material in Malaysia refrigerated trailers, displacing traditional steel constructions through superior thermal efficiency and payload optimization. Poh Wah Trailer leverages its domestic fabrication footprint to anchor supply for local fleet operators. Hargon Engineering competes through specialized multi-axle configurations designed for palm oil and seafood export lanes. MSG Trailers sustains regional distribution reach across Peninsular Malaysia's east-west highway corridors.
A refrigerated trailer is an insulated, temperature-controlled semi-trailer engineered with polyurethane foam-cored sandwich panels and integrated refrigeration units maintaining cargo environments between minus 30 degrees Celsius and plus 20 degrees Celsius for perishable goods transport. The trailer serves Malaysia's agricultural export economy by preserving commodity quality across tropical humidity and extended highway transit durations. Double-axle units dominate current fleet composition due to balanced payload capacity and toll-road compatibility across Malaysian expressways. Active temperature control systems command premium positioning as pharmaceutical cold-chain requirements intensify under Malaysia's National Pharmaceutical Regulatory Agency guidelines. Composite material adoption represents the fastest-growing segment as operators seek corrosion resistance in coastal port-to-depot routes.
Malaysia's Department of Standards (Standards Malaysia) mandates MS 2408 thermal performance certification for insulated transport equipment, while the Road Transport Department enforces annual refrigeration unit inspection protocols. These frameworks elevate capital requirements for fleet entrants and accelerate replacement cycles among non-compliant operators. Stakeholders must monitor impending carbon-emission benchmarks from the Malaysia Green Technology and Climate Change Corporation that will reshape unit specifications and refrigerant selection across the national trailer fleet.
Market Dynamics
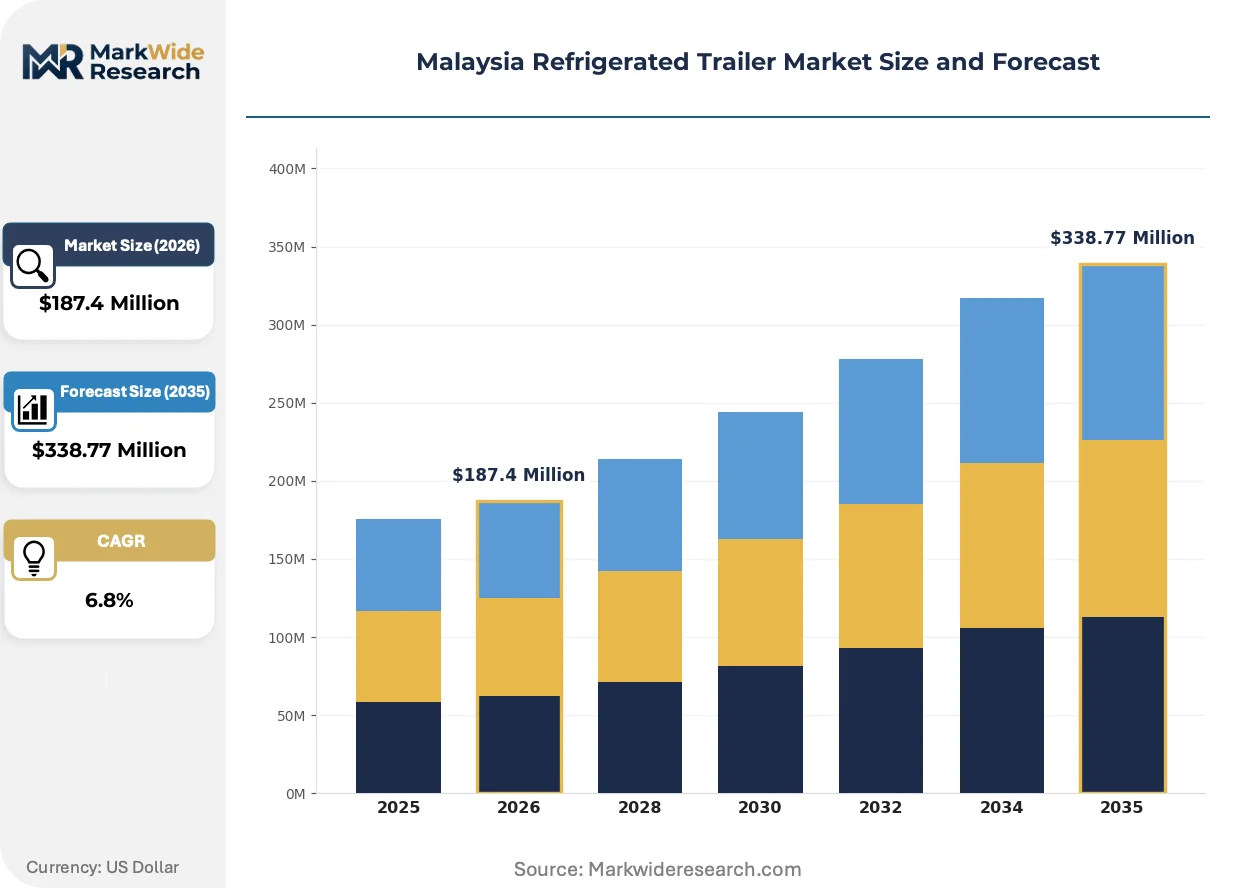
Malaysia's Road Transport Department enforcement of MS 2408 thermal performance certification is compressing replacement cycles and elevating capital barriers for fleet operators across Peninsular Malaysia's cold-chain corridors.
Growth Catalysts
- Fresh Produce Export Lanes:Cold-chain logistics for palm oil and seafood shipments to Singapore and Thailand is pulling refrigerated trailer demand through Port Klang's expansion corridors.
- MS 2408 Certification Mandate:Standards Malaysia's thermal performance requirements are accelerating fleet modernization among non-compliant operators in the Klang Valley distribution hub.
- Pharmaceutical Cold-Chain:Malaysia's National Pharmaceutical Regulatory Agency guidelines for temperature-sensitive drug transport are expanding active refrigeration unit deployment.
Market Restraints
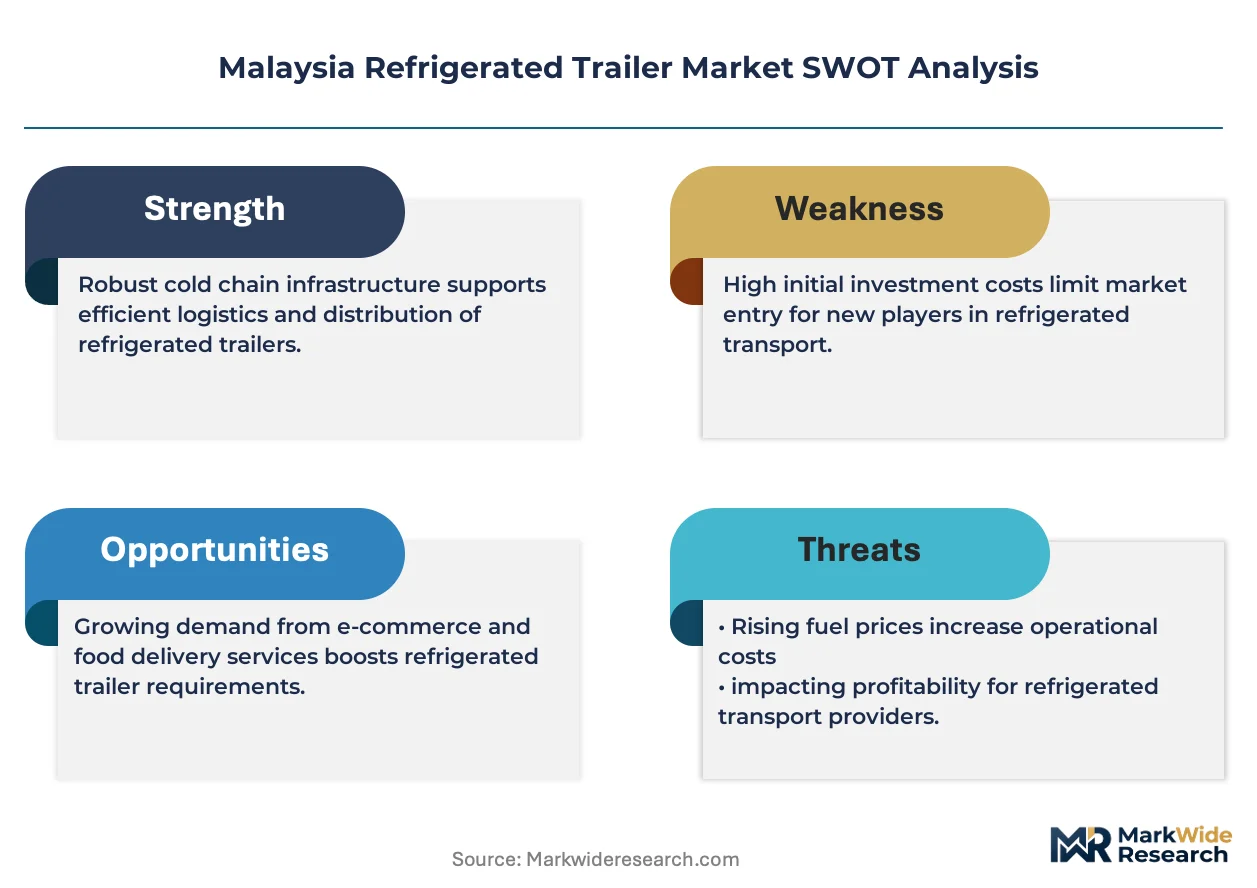
- Aluminum Panel Cost Volatility:Raw material price swings for thermal-efficient sandwich panel cores are squeezing fabrication margins at domestic trailer builders.
- Refrigerant Supply Concentration:Dependence on imported compressor units and cooling system components creates vulnerability in coastal port-to-depot route servicing.
- Tropical Humidity Degradation:Corrosion acceleration in insulated panel joints limits operational lifespan versus temperate-climate equipment benchmarks.
Strategic Opportunities
- East Malaysia Penetration:Sabah and Sarawak's underdeveloped cold-chain infrastructure presents white-space demand for multi-axle units serving seafood export consolidation points.
- Composite Material Adoption:Fiberglass-reinforced panel systems are capturing replacement demand from operators seeking coastal corrosion resistance.
- Carbon Benchmark Preparation:Malaysia Green Technology and Climate Change Corporation emission standards will favor early refrigerant transition to low-GWP alternatives.
Industry Challenges
- Refrigeration Technician Scarcity:Specialized servicing capability for integrated cooling units is concentrated in Greater Kuala Lumpur, creating maintenance backlogs for east-coast fleet operators.
- Dual Certification Timelines:JPJ weight compliance inspections layered with MS 2408 thermal audits extend new-unit deployment cycles for fleet expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Refrigerated Trailer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trailer Type: Single Axle, Double Axle, Tri-Axel, Multi-Axle Temperature Control: Active, Passive, Hybrid, Dynamic Material Used: Aluminum, Steel, Fiberglass, Composite End User: Food and Beverage, Pharmaceutical, Chemical, Agricultural |
| Companies Covered | Poh Wah Trailer, Hargon Engineering, MSG Trailers, BMI Engineering, Heil Trailer, Utility Trailer Manufacturing Company, Polar Tank Trailer, Fontaine Trailer, Ifor Williams Trailers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Refrigerated Trailer Market Trends and Innovations
Material substitution and regulatory tightening are restructuring competitive positioning across Malaysia's refrigerated trailer fabrication base, with technology convergence accelerating in coastal logistics corridors.
Polyurethane foam-cored aluminum sandwich panels are overtaking traditional steel constructions in new fleet procurement. Pharmaceutical distributors and premium seafood exporters are specifying these units for tropical humidity resistance. The shift is compressing steel-fabrication capacity utilization at legacy builders while rewarding thermal-engineering specialization.
Malaysia's National Pharmaceutical Regulatory Agency cold-chain guidelines are mandating continuous temperature monitoring and redundant cooling backup systems. This regulatory pressure is elevating capital requirements for fleet entrants serving pharmaceutical distribution. Active refrigeration units with integrated data-logging capability are capturing preference share in Klang Valley pharmaceutical corridors.
Fleet operators are consolidating procurement around full-service leasing models that bundle unit maintenance and regulatory compliance auditing. This behavioral shift is displacing outright purchase arrangements among mid-sized logistics providers. The transformation is most visible in Peninsular Malaysia's east-west highway corridors where toll-road compatibility and payload optimization drive total-cost-of-ownership calculations.
Malaysia Refrigerated Trailer Market Segmentation
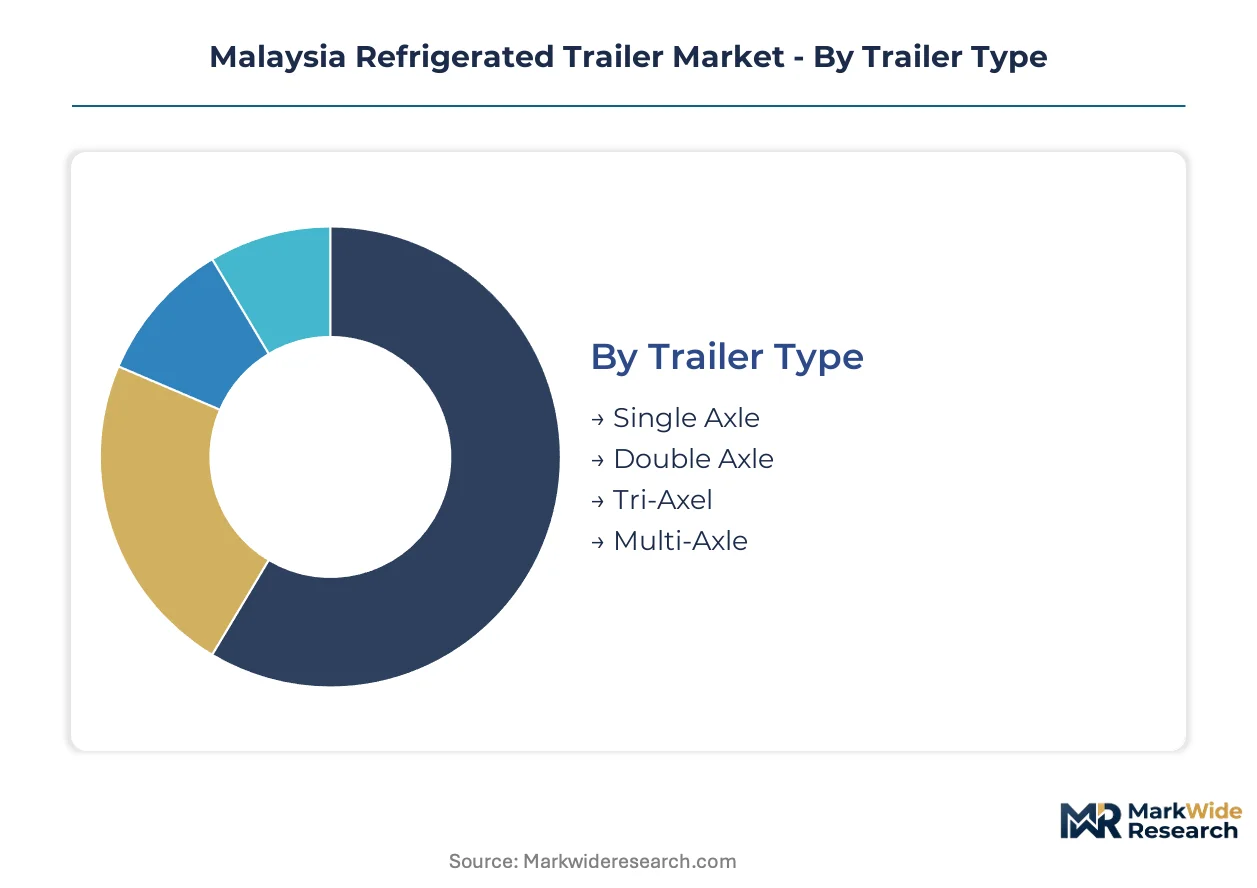
Malaysia's refrigerated trailer market fragments across axle configurations, thermal management systems, panel materials, and end-use verticals. Each dimension carries distinct regulatory implications under JPJ weight enforcement and Standards Malaysia certification protocols.
Trailer Type:
Axle configuration supply concentrates around toll-road compatibility and payload optimization across Peninsular Malaysia's expressway network.
- Double Axle:Balanced weight distribution and toll-classification efficiency make this the dominant fleet standard. Klang Valley distribution operators favor these units for Port Klang-to-Kuala Lumpur corridors where bridge tolls penalize heavier configurations.
- Multi-Axle:Specialized configurations serve East Malaysia's undeveloped road infrastructure and palm oil export consolidation points. Sabah and Sarawak seafood exporters specify these for rough-terrain durability despite higher capital outlay.
- Single Axle:Limited urban delivery applications in Greater Kuala Lumpur's last-mile pharmaceutical distribution.
- Tri-Axle:Mid-tier payload capacity fills gaps between standard double-axle and heavy multi-axle specifications.
Today's leader: Double Axle. Tomorrow's challenger: Multi-Axle.
Temperature Control:
Cost tiers separate basic insulation from precision-engineered active systems as pharmaceutical cold-chain requirements intensify.
- Active:Integrated compressor units with redundant cooling backup satisfy National Pharmaceutical Regulatory Agency guidelines for temperature-sensitive drug transport. Premium pricing reflects continuous monitoring capability and data-logging integration demanded by Klang Valley pharmaceutical distributors.
- Passive:Insulated panels without mechanical refrigeration serve short-haul agricultural routes where ambient thermal mass suffices. Lower capital barriers attract mid-sized fresh produce operators in Peninsular Malaysia's east-west corridors.
- Hybrid:Dual-mode systems switching between active and passive operation optimize fuel consumption on variable-route deployments.
- Dynamic:Adaptive temperature modulation responding to cargo load and ambient conditions represents the steepest expansion trajectory as fleet telematics mature.
Active systems command premium positioning. Hybrid configurations are climbing the fastest.
Material Used:
Volume concentration favors thermal-efficient aluminum as coastal corrosion accelerates replacement cycles.
- Aluminum:Polyurethane foam-cored sandwich panels dominate new procurement through superior thermal efficiency and payload optimization. Poh Wah Trailer and domestic fabricators anchor supply for operators displacing legacy steel constructions.
- Composite:Fiberglass-reinforced systems capture replacement demand from seafood exporters seeking coastal corrosion resistance in port-to-depot routes. Malaysia Green Technology and Climate Change Corporation emission benchmarks will favor these lightweight specifications.
- Steel:Traditional construction faces compression as thermal performance gaps widen against aluminum benchmarks.
- Fiberglass:Niche applications in chemical transport where material inertness outweighs structural limitations.
Aluminum owns current procurement. Composite materials are gaining share fastest.
End User:
Customer type maturity separates regulated pharmaceutical channels from fragmented agricultural logistics.
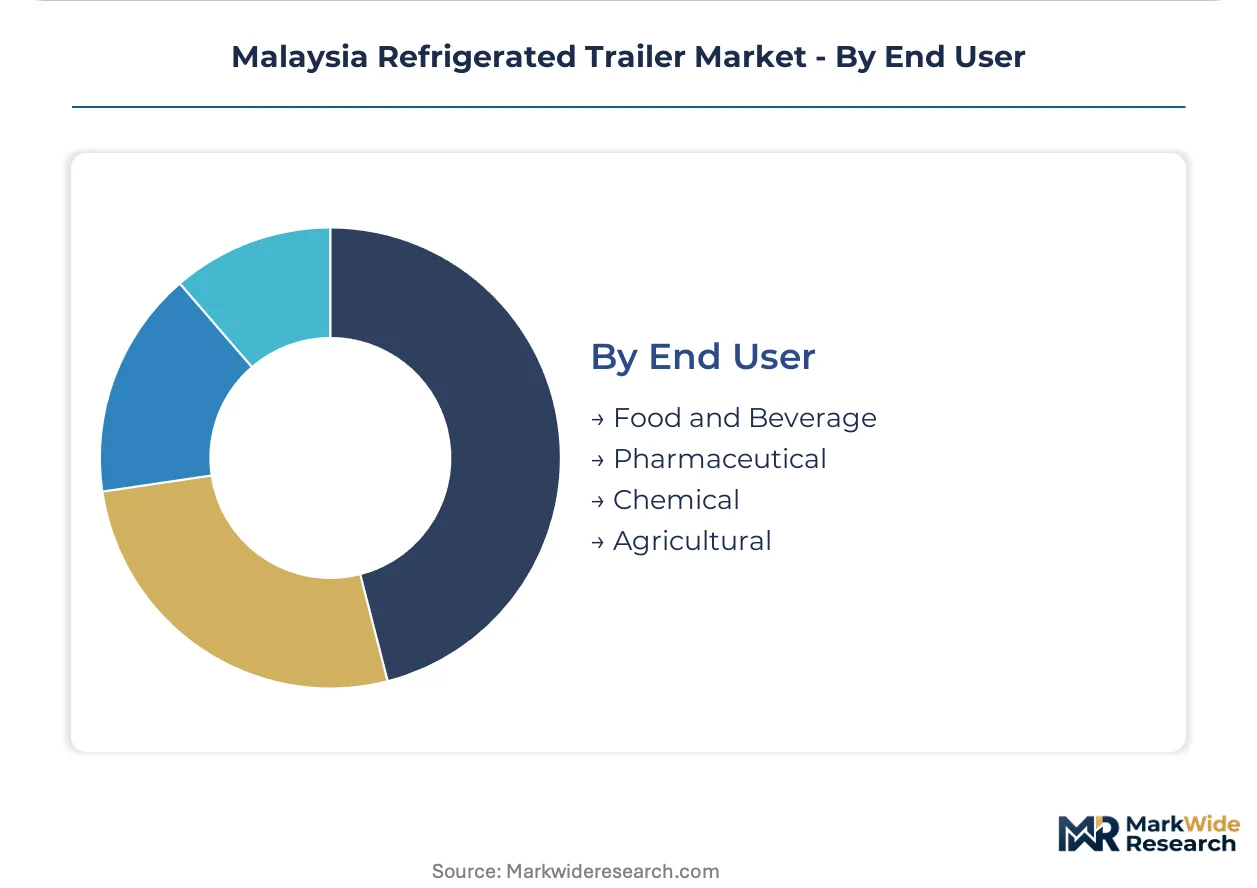
- Food and Beverage:Palm oil and seafood export lanes through Port Klang drive baseline demand. MS 2408 thermal certification mandates compress replacement cycles among non-compliant frozen food distributors.
- Pharmaceutical:National Pharmaceutical Regulatory Agency cold-chain guidelines elevate capital requirements and specify active refrigeration with continuous monitoring. This vertical commands highest unit pricing and tightest vendor qualification.
- Agricultural:Fresh produce consolidation points across Peninsular Malaysia's Cameron Highlands and Johor growing regions favor passive systems for cost-sensitive operators.
- Chemical:Temperature-sensitive industrial materials transport represents specialized niche with material compatibility constraints.
Food and Beverage anchors volume. Pharmaceutical commands margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Klang Valley's distribution density anchors Malaysia's refrigerated trailer deployment, with Port Klang's cargo throughput pulling fleet concentration into Greater Kuala Lumpur's cold-chain corridors.
Peninsular Malaysia West Coast
Port Klang-to-Kuala Lumpur logistics lanes drive double-axle unit procurement for toll-road efficiency. JPJ weight compliance inspections concentrate enforcement capacity along this corridor. Shah Alam industrial zones host domestic fabrication facilities serving frozen food distributors.
East Coast Peninsula
Kuantan and Kota Bharu seafood consolidation points generate multi-axle demand for rough-terrain durability. Standards Malaysia MS 2408 thermal audits accelerate replacement cycles among non-compliant operators. Kemaman port facilities are expanding cold-storage anchorage for regional seafood exports.
Sabah
Kota Kinabalu and Sandakan seafood export lanes pull refrigerated trailer demand through underdeveloped road infrastructure. The state's national pharmaceutical regulator guidelines extend cold-chain requirements to vaccine distribution networks. Tawau's palm oil consolidation points are emerging as multi-axle specification anchors.
Sarawak
Kuching and Miri serve as seafood export consolidation hubs with limited servicing infrastructure for integrated refrigeration units. The Road Transport Department's annual refrigeration inspection protocols create maintenance backlogs for remote fleet operators. Bintulu's industrial port complex is attracting composite-material trailer deployment for coastal corrosion resistance.
Johor-Singapore Corridor
Iskandar Malaysia's logistics parks channel fresh produce exports to Singapore through specialized cold-chain infrastructure. Malaysia Green Technology and Climate Change Corporation emission benchmarks are reshaping refrigerant selection for cross-border fleet operators. Pasir Gudang port facilities are integrating temperature-controlled cargo handling for pharmaceutical transit.
Malaysia Refrigerated Trailer Market Competitive Landscape
Global majors compete with regional champions across fabrication specialization and regulatory compliance capability. Market structure fragments between domestic panel fabricators serving Klang Valley fleet operators and multinational equipment suppliers penetrating East Malaysia's underdeveloped corridors. Three archetypes dominate: domestic aluminum-panel specialists, multi-axle rough-terrain engineers, and integrated refrigeration system bundlers. Capacity expansion and compliance certification partnerships represent the dominant competitive vectors as MS 2408 thermal mandates compress replacement timelines.
Among Malaysia-based fabricators, Poh Wah Trailer anchors domestic aluminum-panel supply for Klang Valley distribution operators. Hargon Engineering exemplifies the multi-axle specialization archetype serving Sabah and Sarawak seafood export lanes. MSG Trailers occupies a position spanning Peninsular Malaysia's east-west highway corridors through regional distribution reach. These three represent distinct competitive positioning vectors: fabrication footprint depth, terrain-specific engineering, and geographic coverage density.
| Leading Market Players |
|---|
| Poh Wah Trailer |
| Hargon Engineering |
| MSG Trailers |
| BMI Engineering |
| Heil Trailer |
| Utility Trailer Manufacturing Company |
| Polar Tank Trailer |
| Fontaine Trailer |
| Ifor Williams Trailers |
| Others |
Pricing and Supply Chain Analysis
Captive fabrication networks at domestic aluminum-panel specialists anchor both supply security and pricing power for Klang Valley fleet operators serving Port Klang corridors. This integration pattern insulates procurement costs from imported compressor volatility while compressing margins for non-integrated assemblers competing on MS 2408 compliance timelines.
Pricing Analysis
Aluminum sheet and polyurethane foam core pass-through costs dominate unit pricing fluctuations for domestic fabricators serving Malaysian cold-chain operators. Three-tier pricing structure across active refrigeration, passive insulation, and hybrid thermal systems separates pharmaceutical distributors from fresh produce consolidators. Cost compression in steel-fabrication legacy capacity is intensifying because aluminum thermal-efficiency gaps widen against MS 2408 benchmarks. Mid-sized logistics providers in Peninsular Malaysia's east-west corridors exhibit highest price sensitivity, while pharmaceutical cold-chain specifications command premium-mid-economy pricing differentiation with minimal elasticity.
Supply Chain Analysis
Domestic-content thresholds under Malaysia's industrial development frameworks are reshaping sourcing patterns for insulated panel cores and refrigeration compressor assemblies. Manufacturing concentration centers on Malaysia, China, and Thailand for aluminum sandwich panels, polyurethane foam systems, and integrated cooling units. The supply chain rests on imported compressor units from Japanese and German OEMs, creating single-source vulnerability for active refrigeration deployment. Distribution runs through Port Klang consolidation hubs into Klang Valley fleet yards, with aftermarket parts flowing through Shah Alam industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's refrigerated trailer market functions as a stable compounder anchored by regulatory-driven replacement cycles under JPJ enforcement and MS 2408 thermal mandates.
For Market Incumbents: Deepen captive control over aluminum panel fabrication to defend margin position against raw material volatility squeezing non-integrated competitors. Expand MS 2408 certification auditing services into bundled leasing offerings that lock in fleet operator relationships before replacement cycle peaks. The threat of composite material substitution from coastal corrosion-resistant specifications demands pre-emptive R&D investment in fiberglass-reinforced hybrid constructions. For New Entrants and Emerging Players: Capture white-space demand in Sabah and Sarawak multi-axle segments where rough-terrain durability specifications outrun incumbent service reach. Target seafood export consolidation points at Kota Kinabalu, Sandakan, and Tawau with maintenance-forward leasing models that address technician scarcity in East Malaysia. The most penetrable entry angle combines composite material differentiation with embedded refrigeration servicing capability bypassing Greater Kuala Lumpur's concentrated technical labor pool. For Investors and Strategic Acquirers: Roll-up economics work for domestic aluminum-panel fabricators with JPJ compliance certification infrastructure because regulatory barriers prevent rapid entrant scaling and fragment vendor qualification across pharmaceutical and food verticals. Long-term viability frames around carbon benchmark preparation as Malaysia Green Technology and Climate Change Corporation emission standards reshape refrigerant selection. The signal to watch is composite material adoption velocity at Bintulu and Kemaman port facilities as coastal corrosion resistance transitions from niche to mainstream specification.| Strategic Initiative | Industry Significance |
|---|---|
| MS 2408 Certification Investment | Accelerates fleet modernization timelines among non-compliant Klang Valley operators. |
| Composite Material R&D Partnership | Positions fabricators for coastal corrosion resistance demand at East Malaysia ports. |
| Full-Service Leasing Model Expansion | Bundles maintenance and compliance auditing for mid-sized logistics providers. |
| East Malaysia Distribution Buildout | Addresses technician scarcity servicing remote seafood export consolidation points. |
| Low-GWP Refrigerant Transition | Aligns product portfolios with Malaysia Green Technology and Climate Change Corporation benchmarks. |
Research Methodology
Coverage spans Peninsular Malaysia West Coast, East Coast Peninsula, Sabah, and Sarawak, with primary inputs from each region's cold-chain corridor operators. The research combines interviews with fleet maintenance directors, trailer procurement managers at logistics providers, JPJ compliance officers, and Standards Malaysia certification auditors with secondary validation from customs trade records, Road Transport Department enforcement bulletins, and pharmaceutical regulatory guidance documents. Bottom-up unit deployment estimates triangulate against top-down cold-chain infrastructure investment flows.
Rate-of-change decomposition separates volume growth into replacement cycle compression, fleet expansion in underpenetrated corridors, and specification upgrade premiums across the projection horizon. Segmentation modeling incorporates axle configuration, thermal management system tier, panel material grade, and end-use vertical regulatory intensity. CAGRs derive from unit shipment trajectories weighted by average selling price evolution as aluminum thermal-efficiency specifications displace legacy steel constructions. Industry-specific forecast inputs include Port Klang cargo throughput correlations and pharmaceutical cold-chain guideline implementation timelines.
Aluminum price volatility, refrigerant import restriction escalations, and tropical humidity degradation acceleration are the dominant revision risks that could compress or extend replacement cycle assumptions. Forecasts reflect documented regulatory enforcement intensity and infrastructure investment commitment levels without projecting policy discontinuities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
North America Long-Haul Transport Market