
 Global Transparent Quartz Tube Market | 2026-2036
Global Transparent Quartz Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transparent Quartz Tube Market Intelligence
Synthetic fused silica is recalibrating cost structures across high-purity transparent quartz tube applications, displacing natural quartz in semiconductor diffusion processes where metal contamination thresholds now sit below ten parts per billion. Heraeus Quarzglas leverages captive synthetic feedstock production to anchor premium wafer-furnace supply contracts in Germany and Japan. Momentive Performance Materials competes through vertical integration into silane chemistry, sustaining margins on chemical vapor deposition-grade tubing for epitaxy reactors. Donghai Alfa Quartz dominates volume production of hydrothermal-process tubes, positioning its Jiangsu facilities as the default source for domestic Chinese solar ingot pullers.
Transparent quartz tube denotes a high-purity silicon dioxide cylinder manufactured by flame fusion, electric fusion, or chemical vapor deposition, with optical transmission exceeding eighty-five percent in the ultraviolet to near-infrared range and thermal stability surpassing one thousand degrees Celsius; its primary purpose is to contain reactive processes, transmit UV radiation, or maintain dimensional precision under thermal shock in industrial and scientific equipment. Hydrothermal-process single-wall tubes lead volume shipments for solar polysilicon production, though chemical vapor deposition variants command the deepest margin pools in semiconductor epitaxy. Flame-fusion double-wall configurations serve mature UV lamp markets where price competition compresses returns, while custom-shape electric-fusion products for photonics companies represent the fastest-expanding category as fiber-optic network builds accelerate.
China's NMPA and GB standards enforce escalating purity certifications on imported quartz tubing, restricting market access for uncertified foreign suppliers while MIIT dual carbon goals redirect domestic capacity toward renewable energy applications. REACH and RoHS frameworks in Europe impose heavy metal and halogen restrictions on quartz components destined for laboratory and electronics end uses, compelling reformulation of doped tubing for UV lamp manufacturers. Stakeholders must monitor divergence between China's GB standards and ISO/IEC purity benchmarks, as misalignment threatens to fragment qualification protocols and strand inventory across semiconductor supply chains.
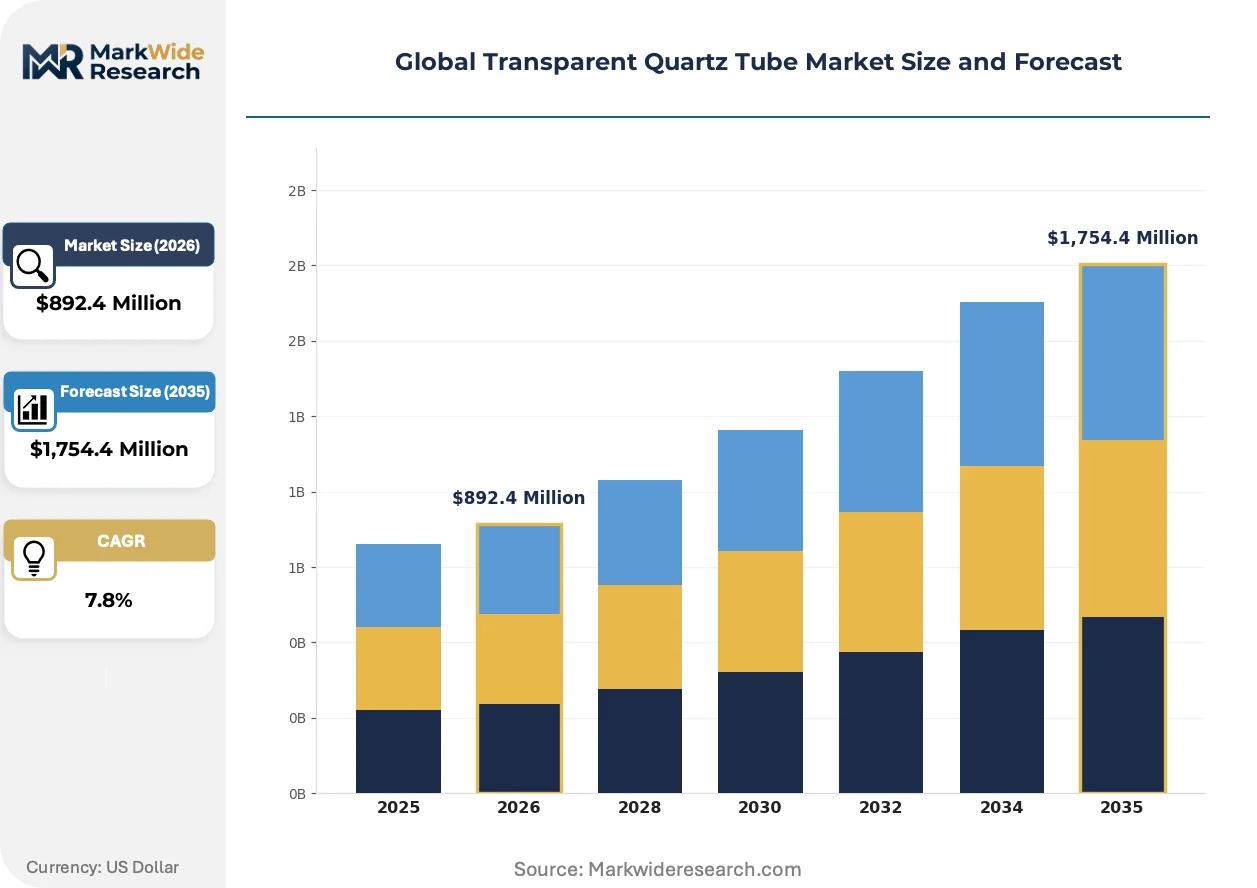
Market Dynamics
Synthetic fused silica is absorbing procurement volume from natural quartz as semiconductor diffusion furnaces tighten metal contamination thresholds below ten parts per billion, forcing feedstock substitution across wafer-processing supply chains.
Growth Catalysts
- Silicon carbide substrate expansion:Wide-bandgap semiconductor manufacturers are scaling quartz tube orders for high-temperature epitaxy reactors, pulling chemical vapor deposition-grade tubing into automotive power electronics.
- China's dual carbon mandate:MIIT production quotas redirect domestic quartz capacity toward solar ingot pullers and fiber-optic preform manufacturing, concentrating investment in Jiangsu and Zhejiang provinces.
- REACH and RoHS alignment:European heavy metal restrictions on laboratory equipment are filtering uncertified Asian suppliers from photonics-grade tubing tenders, consolidating qualified vendor pools.
Market Restraints
- High-purity feedstock concentration:Synthetic fused silica precursor supply clusters in Germany and Japan, exposing buyers to geopolitical friction and freight cost volatility.
- GB-NMPA certification lag:China's import purity protocols now exceed ISO/IEC baselines, stranding non-compliant inventory and forcing dual-qualification investments.
- Alumina ceramic substitution:Cost-sensitive UV lamp manufacturers are trialing aluminum oxide liners for mature arc tube applications, compressing flame-fusion quartz margins.
Strategic Opportunities
- India's PLI scheme for solar:Domestic content requirements for photovoltaic manufacturing are creating first-mover openings for quartz tube suppliers near Gujarat and Tamil Nadu polysilicon plants.
- Photonics custom shaping:Electric-fusion specialty geometries for fiber-optic network builds command premium positioning as 5G backhaul and submarine cable deployments accelerate.
- EU F-Gas Regulation phase-down:Mercury-free UV lamp mandates are stimulating demand for high-transmission synthetic tubing in water sterilization and semiconductor lithography.
Industry Challenges
- Epitaxy-grade certification timelines:Semiconductor OEM qualification cycles for chemical vapor deposition tubing extend eighteen to twenty-four months, freezing supplier switching.
- Flame-fusion skilled operator scarcity:Master glassblowers capable of maintaining dimensional tolerance below fifty microns are retiring faster than apprenticeship programs replace them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transparent Quartz Tube Market |
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,754.4 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Tubular, Custom Shape Technology: Flame Fusion, Hydrothermal, Chemical Vapor Deposition, Electric Fusion Application: Semiconductor Manufacturing, UV Lighting, Laboratory Equipment, Solar Power, Optical Instruments End User: Electronics Producers, Research Institutions, Renewable Energy Firms, Photonics Companies, Scientific Laboratories |
| Companies Covered | Heraeus Quarzglas, Momentive Performance Materials, Donghai Alfa Quartz, Xinyi Quartz Glass, Jiurui Quartz, GLASHern, Tosoh Quartz, Technical Glass Products, Vitro Quartz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transparent Quartz Tube Market Strategic Shifts & Innovations
Process control digitization and feedstock chemistry advances are compressing purity variance and enabling real-time contamination monitoring across quartz tube production lines.
Plasma-enhanced chemical vapor deposition is absorbing development investment from traditional flame fusion for semiconductor epitaxy applications. Foundry process engineers at leading-edge logic and memory fabs are specifying synthetic tubing with sub-ppb alkali content. This technology is absorbing margin from natural quartz suppliers unable to guarantee equivalent metal contamination profiles.
REACH authorization requirements for persistent organic pollutants are extending disclosure obligations to quartz component importers serving European laboratory markets. ECHA substance evaluation is forcing reformulation of doped tubing for analytical instrumentation. Photonics OEMs in Germany and France are accelerating supplier audits to preempt compliance gaps.
Direct mill-to-furnace contracting is displacing distributor intermediation for high-volume solar ingot manufacturers. Polysilicon producers in East China are negotiating multi-year offtake agreements with Jiangsu-based tube fabricators. This channel compression is most visible where domestic supply clusters within two hundred kilometers of puller operations.
Global Transparent Quartz Tube Market Segmentation
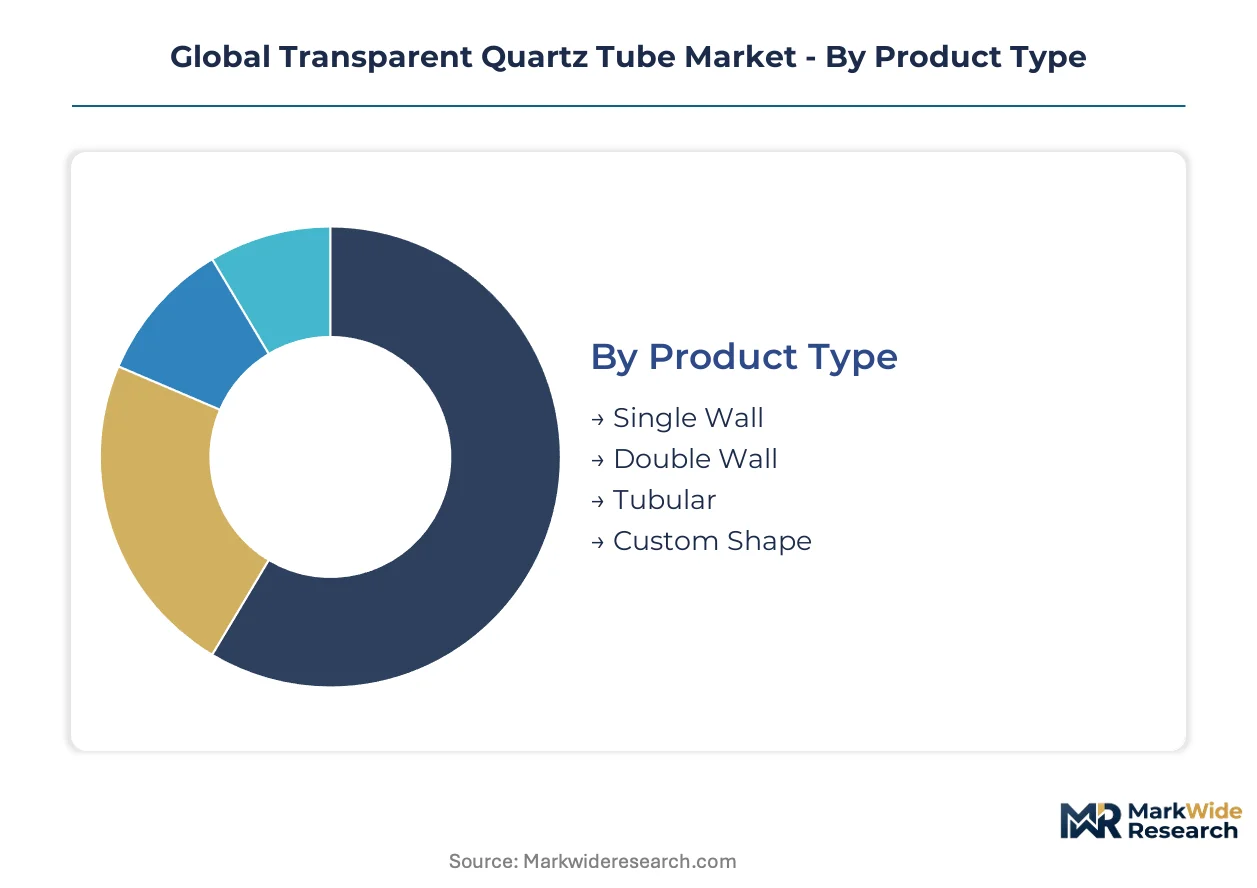
Transparent quartz tube procurement splits across four dimensions where technical specifications, purity grades, and thermal tolerance thresholds dictate supplier selection. Buyers weight flame-fusion cost efficiency against chemical vapor deposition purity premiums, while custom geometries command extended lead times. Understanding these trade-offs clarifies why semiconductor OEMs, solar ingot pullers, and photonics assemblers rarely source from overlapping supplier pools.
Product Type:
Wall configuration and dimensional flexibility determine thermal shock resistance and installation compatibility across furnace architectures.
- Single Wall:Monolithic silica construction withstands thermal gradients exceeding 1000°C without delamination. Solar polysilicon producers in Jiangsu province specify hydrothermal-process single-wall tubes for ingot pullers, prioritizing unit cost over optical transmission precision.
- Double Wall:Concentric silica cylinders create annular insulation zones that reduce heat loss in UV lamp arc chambers. Mature mercury-vapor sterilization equipment in European municipal water systems sustains procurement volumes despite REACH-driven mercury phase-down timelines.
- Tubular:Standardized outer diameters from 10mm to 300mm serve laboratory distillation and chemical vapor deposition reactor linings.
- Custom Shape:Non-cylindrical profiles including elliptical cross-sections and tapered bores accommodate fiber-optic preform manufacturing.
Volume sits with Single Wall; growth tilts toward Custom Shape.
Technology:
Feedstock chemistry and energy intensity separate premium semiconductor-grade supply from commodity solar and lighting applications.
- Flame Fusion:Hydrogen-oxygen torch melting of natural quartz sand yields economical tubing with 99.9% SiO₂ purity. UV lamp manufacturers facing alumina ceramic substitution trials in cost-sensitive arc tube segments.
- Hydrothermal:High-pressure aqueous synthesis from seed crystals produces single-wall tubes with controlled bubble content. Jiangsu-based fabricators anchor supply contracts for domestic Chinese solar ingot pullers within 200km of polysilicon plants.
- Chemical Vapor Deposition:Silane pyrolysis builds synthetic fused silica layer-by-layer, achieving sub-ppb metal contamination. Automotive silicon carbide epitaxy reactors specify CVD-grade tubing as wide-bandgap substrate production scales.
- Electric Fusion:Plasma arc melting enables precise dimensional control for photonics-grade geometries. Fiber-optic network builds accelerate demand for electric-fusion specialty shapes in 5G backhaul and submarine cable deployments.
Revenue concentrates in Chemical Vapor Deposition; expansion is steepest in Electric Fusion.
Application:
Process temperature and contamination sensitivity stratify end-use requirements from laboratory benchtops to semiconductor cleanrooms.
- Semiconductor Manufacturing:Diffusion furnaces and epitaxy reactors demand synthetic fused silica with alkali content below ten parts per billion. Wafer-processing OEMs enforce eighteen-to-twenty-four-month qualification cycles that freeze supplier switching.
- Solar Power:Polysilicon ingot pullers consume hydrothermal single-wall tubes in volumes that dominate global quartz consumption. China's MIIT dual carbon quotas redirect domestic capacity toward photovoltaic manufacturing clusters.
- UV Lighting:Mercury-arc and excimer lamp envelopes require high ultraviolet transmission above 85% in the 200-400nm range. EU F-Gas Regulation phase-down stimulates synthetic tubing demand for mercury-free water sterilization systems.
- Laboratory Equipment:Distillation columns and analytical instrument housings face REACH heavy metal disclosure obligations extending to quartz component importers.
- Optical Instruments:Spectrophotometer cuvettes and laser cavity tubes specify bubble-free electric-fusion material.
Shipment volume favors Solar Power; value capture peaks in Semiconductor Manufacturing.
End User:
Procurement scale and technical specification authority vary sharply between multinational electronics assemblers and distributed research facilities.
- Electronics Producers:Integrated device manufacturers and foundries negotiate multi-year offtake agreements for epitaxy-grade tubing. Direct mill-to-furnace contracting displaces distributor intermediation for high-volume consumers.
- Renewable Energy Firms:Polysilicon producers and solar cell manufacturers cluster procurement near Jiangsu and Zhejiang supply bases to minimize freight exposure.
- Photonics Companies:Fiber-optic cable and preform manufacturers specify custom electric-fusion geometries with dimensional tolerance below fifty microns.
- Research Institutions:University and national laboratory buyers face budget constraints that favor flame-fusion standard products over synthetic alternatives.
- Scientific Laboratories:Commercial analytical services and pharmaceutical testing facilities require REACH-compliant doped tubing reformulations.
Contract value aggregates with Electronics Producers; specification complexity concentrates with Photonics Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quartz tube procurement concentrates in manufacturing corridors where semiconductor fabrication, solar ingot pulling, and fiber-optic cable production cluster within tight geographic radii. China's Jiangsu and Zhejiang provinces anchor the largest volume flows, while Germany and Japan retain premium-grade supply dominance.
China
Polysilicon ingot pullers and fiber-optic preform manufacturers drive procurement volume across the Yangtze River Delta. MIIT dual carbon quotas redirect domestic quartz capacity toward photovoltaic manufacturing, tightening supply for export markets. Lianyungang and Donghai in Jiangsu province host hydrothermal-process tube fabricators serving solar cell factories within 200-kilometer delivery zones.
United States
Silicon carbide substrate manufacturers and advanced logic foundries specify chemical vapor deposition-grade tubing for epitaxy reactors. EPA and OSHA frameworks govern emissions and workplace exposure in quartz processing facilities. Arizona and Texas semiconductor corridors negotiate direct mill-to-furnace contracts to bypass distributor markups on high-purity feedstock.
Germany
Automotive power electronics and industrial UV lamp OEMs anchor demand for synthetic fused silica with sub-ppb metal contamination. REACH authorization requirements for persistent organic pollutants extend disclosure obligations to quartz component importers. Heraeus Quarzglas leverages captive synthetic feedstock production from Hanau to anchor wafer-furnace supply contracts across Europe and Asia.
Japan
Memory foundries and photonics equipment manufacturers specify electric-fusion specialty geometries for lithography and fiber-optic applications. METI industrial standards enforce purity benchmarks that exceed ISO/IEC baselines for semiconductor-grade materials. Kyushu and Chubu manufacturing belts concentrate quartz tube consumption near Tosoh Quartz and domestic epitaxy equipment assemblers.
India
Photovoltaic cell manufacturers under the PLI scheme are scaling polysilicon ingot capacity, creating first-mover openings for quartz tube suppliers. BIS certification requirements for high-purity materials are tightening import specifications. Gujarat and Tamil Nadu solar manufacturing clusters are negotiating multi-year offtake agreements with prospective domestic and foreign tube fabricators.
Global Transparent Quartz Tube Market Key Industry Players
Capacity expansion dominates the current landscape as synthetic fused silica producers scale chemical vapor deposition reactors to capture semiconductor epitaxy demand. The vendor base stratifies into three tiers: integrated materials conglomerates with captive feedstock, regional volume fabricators serving solar and lighting markets, and specialty electric-fusion shops for photonics custom work. Strategic archetypes include backward-integrated silane chemistry specialists, hydrothermal-process regional champions, and flame-fusion cost leaders facing alumina substitution pressure. Geographic expansion and technology licensing are the dominant competitive moves, with European and Japanese players extending qualification support into Asian foundry markets.
Among Germany-based materials conglomerates, Heraeus Quarzglas occupies a position exemplifying captive synthetic feedstock control. Momentive Performance Materials represents the silane-chemistry-integrated archetype. Donghai Alfa Quartz anchors the hydrothermal-process volume tier from its Jiangsu facilities. These three sit within distinct competitive vectors—premium semiconductor-grade supply, chemical synthesis integration, and solar-scale manufacturing—rather than direct overlap.
| Leading Market Players |
|---|
| Heraeus Quarzglas |
| Momentive Performance Materials |
| Donghai Alfa Quartz |
| Xinyi Quartz Glass |
| Jiurui Quartz |
| GLASHern |
| Tosoh Quartz |
| Technical Glass Products |
| Vitro Quartz |
| Others |
Cost & Logistics Intelligence
Silane precursor costs cascade through three pricing tiers as synthetic fused silica feedstock moves from German and Japanese chemical plants to semiconductor epitaxy reactor contracts. High-purity chemical vapor deposition-grade tubing commands premiums calibrated to sub-ppb metal certification thresholds, while hydrothermal-process single-wall tubes for solar ingot pullers trade on volume scale within Jiangsu province delivery zones.
Pricing Analysis
Volume shipments cluster in economy-tier hydrothermal-process tubes for solar polysilicon production, while margin capture concentrates in premium chemical vapor deposition-grade products for silicon carbide epitaxy. Price differentiation rests on certification grade—GB-NMPA compliance for China-bound semiconductor tubing versus ISO/IEC baselines for other markets—and volume scale with multi-year offtake discounts. Cost compression in flame-fusion UV lamp segments is intensifying because alumina ceramic substitution trials are forcing quartz suppliers to absorb freight differentials. Solar ingot pullers in East China exhibit highest price sensitivity; automotive power electronics OEMs sourcing epitaxy-grade tubing show least.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are redirecting procurement negotiations toward Gujarat and Tamil Nadu solar manufacturing clusters, fragmenting traditional China-centric sourcing patterns. Synthetic fused silica precursor supply draws from Germany and Japan, hydrothermal-process tube fabrication centers on Jiangsu province, and specialty electric-fusion shaping concentrates in Japanese photonics corridors. Single-source vulnerability in silane chemistry feedstock exposes buyers to geopolitical friction and freight cost volatility. Distribution runs through direct mill-to-furnace contracting for high-volume solar and semiconductor consumers, compressing distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic fused silica reactor capacity expansion lags silicon carbide substrate demand growth, propping pricing power for qualified suppliers. This supply-constrained dynamic favors incumbents with captive feedstock and long-tenured OEM qualifications.
For Market Incumbents: Deploy silane chemistry backward integration to secure precursor supply against German and Japanese feedstock concentration. Add electric-fusion capacity in Zhejiang province to capture fiber-optic preform demand acceleration. Alumina ceramic substitution in mature UV lamp segments threatens flame-fusion margins; redirect those fabrication lines toward hydrothermal-process solar tube volume. For New Entrants and Emerging Players: Enter via India's PLI scheme solar corridor, where domestic content requirements and nascent polysilicon capacity create first-mover openings before incumbent China suppliers establish local fabrication. Photonics custom shaping for 5G backhaul and submarine cable deployments offers penetrable white space with premium positioning. Lead with technical qualification support to accelerate eighteen-to-twenty-four-month semiconductor OEM approval cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydrothermal-process regional champions in Jiangsu province with established solar offtake relationships and undervalued GB-NMPA certification assets. Long-term viability hinges on synthetic fused silica technology migration and electric-fusion capability buildout. Watch silicon carbide substrate capacity announcements from automotive power electronics OEMs as inflection indicator for epitaxy-grade tubing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Chemistry | Heraeus Quarzglas and Momentive Performance Materials anchor semiconductor-grade supply through captive precursor production in Hanau and New York. |
| Electric-Fusion Capacity Expansion | Japanese and German photonics specialists capture fiber-optic preform demand from 5G backhaul and submarine cable deployments. |
| GB-NMPA Certification Investment | Foreign suppliers overcome China's escalating import purity protocols to access Jiangsu and Zhejiang semiconductor and solar clusters. |
| Direct Mill-to-Furnace Contracting | Polysilicon producers in East China negotiate multi-year offtake agreements that displace distributor intermediation. |
| Plasma-Enhanced Chemical Vapor Deposition Adoption | Leading-edge logic and memory foundries specify sub-ppb alkali content synthetic tubing for epitaxy reactor applications. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this transparent quartz tube market assessment. Primary interviews with semiconductor process engineers, solar ingot puller procurement leads, photonics OEM supply chain managers, and quartz fabrication plant directors combined with SEC 10-K disclosures, MIIT production quota publications, and ECHA REACH authorization databases. Bottom-up shipment tallies by product type and technology triangulated against top-down end-use demand estimates from polysilicon and fiber-optic cable production statistics.
Granularity-level modeling tracked chemical vapor deposition, electric fusion, flame fusion, and hydrothermal-process technologies across single-wall, double-wall, and custom-shape configurations. Semiconductor manufacturing, solar power, UV lighting, laboratory equipment, and optical instrument applications were projected across the analysis window with CAGRs derived from wafer-processing furnace installation forecasts and photovoltaic capacity expansion trajectories. Silane precursor supply constraints and GB-NMPA certification timelines informed supply-side elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt silicon carbide substrate demand deceleration or sudden relaxation of China's dual carbon production quotas. Epitaxy-grade qualification cycle extensions and master glassblower retirement rates represent specific revision triggers for capacity and pricing assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Polarizer Film Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Optical Interconnect Market
Optical Components
Optical Modulators Market
Optical Components
Global Adaptive Optics Market
Optical Components
Photosensitive Glass Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
US Optical Sensors Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Optical Waveguide Market
Optical Components
Global Optical Imaging System Market