
 Photosensitive Glass Market | 2026-2036
Photosensitive Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Photosensitive Glass Market Outlook
Chinese specialty glass foundries is decoupling from legacy borosilicate supply chains as domestic precision optics demand surges. Corning Incorporated leverages its fused silica expertise to anchor North American capacity for semiconductor-grade photosensitive substrates. SCHOTT AG competes through vertical control over rare-earth dopant sourcing, while HOYA Corporation specializes in ultraviolet-curable formulations for East Asian lithography tool builders.
Photosensitive glass refers to alkali-aluminosilicate compositions containing trace silver, cerium, or copper ions that nucleate crystalline phases upon controlled ultraviolet exposure and subsequent heat treatment, enabling sub-micron patterning for integrated optical circuits. The material's primary commercial purpose centers on fabricating permanent volume Bragg gratings, micro-lens arrays, and waveguide structures without subtractive etching. Optical glass variants command premium positioning due to stringent homogeneity specifications and low birefringence requirements for laser-based systems, whereas specialty glass grades for photovoltaic encapsulation are gaining volume traction as bifacial panel architectures proliferate. Display technology applications remain mature with consolidated procurement patterns, while sensors represent the fastest-expanding application segment driven by lidar and biomedical imaging adoption.
EPA hazardous waste rules govern silver-bearing effluent from U.S. photosensitive glass processing facilities, elevating capital requirements for domestic manufacturers. EU REACH restrictions on cadmium and lead content are forcing reformulation of certain high-refractive-index glass compositions, with ECHA compliance audits intensifying across German and French supply bases. China's GB standards for optical material emissions are tightening under MEE oversight, reshaping import eligibility for foreign substrate suppliers. Stakeholders must monitor divergence between regional chemical restriction schedules to avoid stranded inventory in cross-border optical component supply chains.
Market Dynamics
Photosensitive glass supply chains are reorganizing around rare-earth dopant security as aerospace and semiconductor buyers demand certified provenance for silver and cerium feedstocks. This concentration pressure is forcing foundries to backward integrate into raw material refining or lock multi-year offtake agreements with Australian and Canadian mining operations.
Growth Catalysts
- Aerospace sensor miniaturization:Lidar and star-tracker manufacturers are specifying photosensitive glass substrates to reduce optical payload mass. German precision optics clusters in Jena and Mainz are scaling dedicated production lines for this segment.
- REACH compliance deadlines:EU ECHA audits are accelerating reformulation of lead-free high-index compositions. Suppliers achieving certification ahead of enforcement windows are capturing displaced volume from non-compliant competitors.
- Semiconductor lithography expansion:East Asian tool builders are qualifying ultraviolet-curable photosensitive formulations for next-generation mask aligners. This is pulling substrate demand toward sub-50ppm homogeneity specifications.
Market Restraints
- Silver price volatility:The primary nucleating agent in photosensitive compositions fluctuates with precious metals markets. Foundries without hedging programs absorb margin compression during supply squeezes.
- Optical-grade fused silica substitution:Corning's semiconductor-grade fused silica capacity is capturing volume in waveguide applications where thermal stability exceeds patterning flexibility requirements.
- EPA hazardous waste governance:Silver-bearing effluent processing adds capital intensity for U.S. facilities. Domestic manufacturers face higher fixed costs versus Asian competitors with less stringent discharge protocols.
Strategic Opportunities
- India precision optics emergence:BIS standards alignment with ISO 10110 is creating import substitution potential for domestic foundries. PLI scheme incentives for specialty materials could accelerate local photosensitive glass capacity.
- Bifacial photovoltaic encapsulation:Specialty glass grades with UV-patternable anti-reflective surfaces are penetrating solar module architectures. This application bypasses the certification barriers of semiconductor-grade supply chains.
- Digital twin integration:Convergence of computational lithography simulation with heat-treatment process control is unifying design and manufacturing workflows. Early adopters are compressing prototyping cycles from months to weeks.
Industry Challenges
- Rare-earth metallurgy expertise scarcity:Cerium and europium dopant optimization requires specialized glass scientists. Foundries compete for talent against battery and magnet material sectors with deeper compensation pools.
- MEE emissions compliance timelines:China's tightening GB standards for optical material processing demand capital upgrades with uncertain enforcement schedules. Foreign suppliers risk stranded inventory at port if certification lags implementation.
- Cross-border chemical restriction divergence:EU REACH, EPA RCRA, and China MEE maintain non-synchronized hazardous substance lists. Multi-regional suppliers must maintain parallel formulation inventories to avoid customs detention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photosensitive Glass Market |
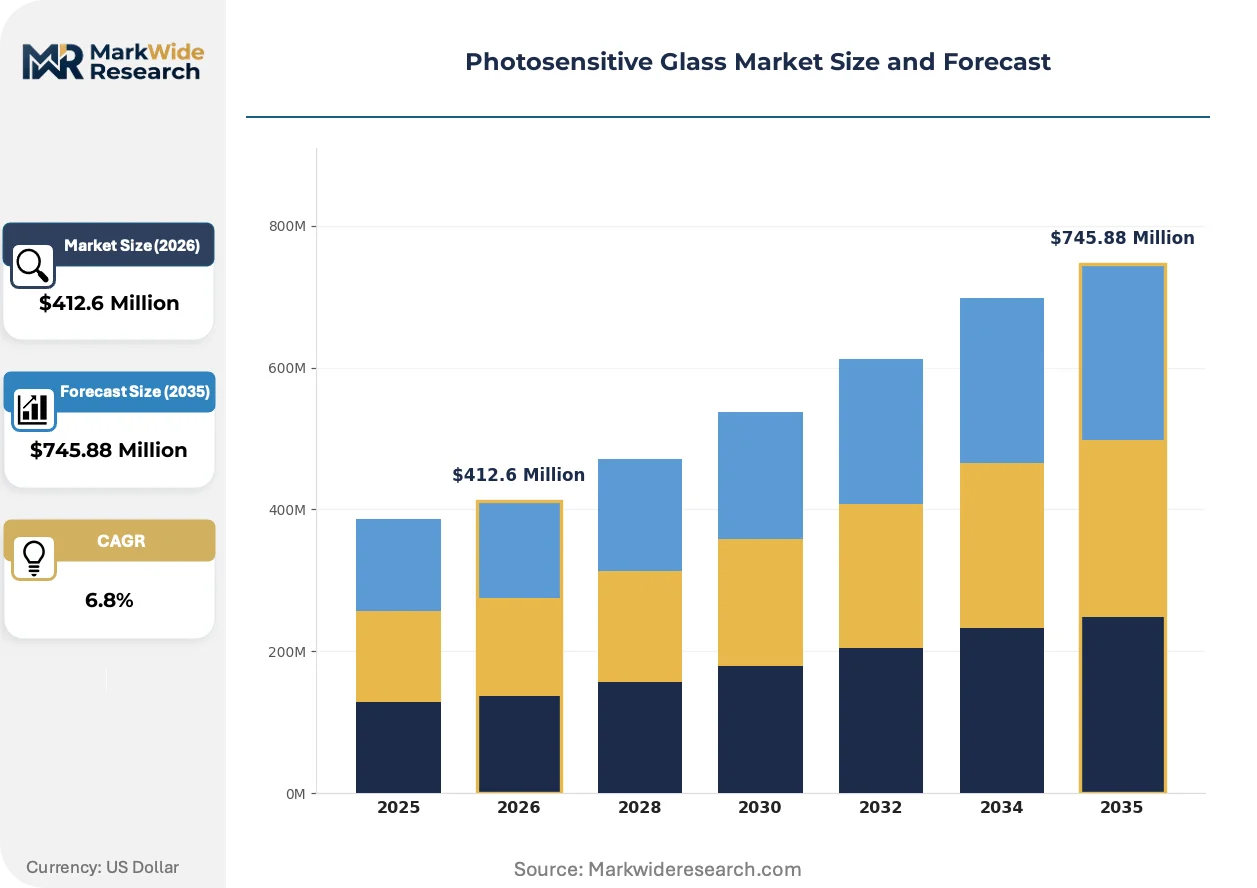
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Glass, Optical Glass, Specialty Glass, Fiberglass Application: Display Technology, Photovoltaics, Sensors, Coatings End User: Electronics, Automotive, Aerospace, Healthcare Manufacturing Stage: Raw Material Processing, Forming, Surface Treatment, Finishing |
| Companies Covered | Corning Incorporated, SCHOTT AG, AGC Inc., HOYA Corporation, Nippon Electric Glass Co., Ltd., IPG Photonics Corporation, OptiGrate Corporation, Sumita Optical Glass Co., Ltd., 3D Glass Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photosensitive Glass Market Strategic Shifts
Patterning precision requirements are compressing process windows across aerospace, semiconductor, and biomedical imaging end-uses. Foundries are responding with unified control architectures that link ultraviolet exposure systems to thermal processing furnaces in closed-loop configurations.
Femtosecond laser direct-write patterning is unifying grayscale lithography with volume Bragg grating fabrication in single processing sequences. Aerospace sensor manufacturers are adopting this for conformal optical surfaces that would require multiple masking steps under traditional protocols. The technology is compressing lead times for prototype micro-lens arrays from twelve weeks to under four.
EU F-Gas Regulation phase-down schedules are pressuring refrigerant-dependent polishing processes in German and French optical clusters. Foundries are retrofitting aqueous chemo-mechanical planarization systems to maintain surface figure specifications without fluorinated compounds. Semiconductor-grade substrate suppliers face the steepest compliance costs due to sub-nanometer roughness requirements.
Consolidated procurement by lidar system integrators is concentrating volume with qualified Tier-1 substrate suppliers. Tier-2 foundries without automotive IATF 16949 certification are losing access to high-volume programs. This preference shift is most visible in North American and German automotive supply chains where OEMs mandate full material traceability from mine to module.
Photosensitive Glass Market Segmentation
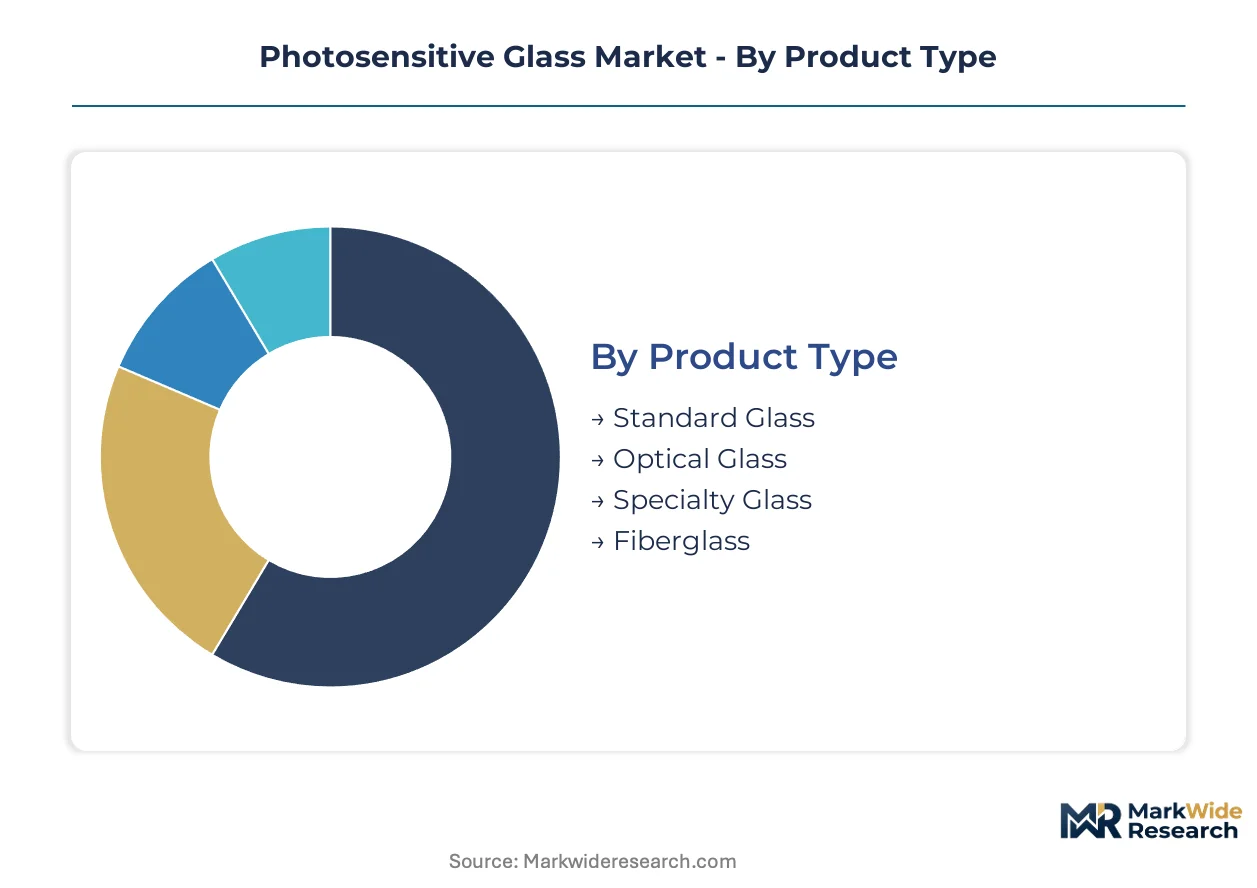
Photosensitive glass markets fragment across technical specifications, application environments, and regulatory compliance tiers. Buyers prioritize homogeneity grades, thermal stability thresholds, and certification requirements differently depending on end-use criticality.
Product Type:
Cost tier separates procurement behavior, with premium grades commanding multi-year qualification cycles and economy variants competing on volume scale.
- Optical Glass:Stringent homogeneity specifications below 50ppm and low birefringence requirements define this grade. Demand concentrates in German precision optics clusters around Jena and Mainz, where SCHOTT AG and specialized foundries serve lidar and biomedical imaging OEMs with laser-grade substrates.
- Specialty Glass:UV-patternable anti-reflective surfaces and tailored thermal expansion coefficients characterize this segment. Photovoltaic encapsulation for bifacial panel architectures is expanding most quickly, bypassing semiconductor-grade certification barriers while capturing solar module integration demand.
- Standard Glass:General-purpose alkali-aluminosilicate compositions with broader tolerance bands serve cost-sensitive display applications.
- Fiberglass:Reinforced photosensitive matrices for structural optical components in aerospace sensor housings.
Optical Glass leads volumes today; Specialty Glass is climbing the fastest.
Application:
Volume maturity varies sharply, with established display procurement patterns contrasting against emerging sensor specifications.
- Sensors:Permanent volume Bragg gratings and micro-lens arrays for lidar and star-tracker miniaturization dominate this segment. Aerospace manufacturers in Germany and North America specify these substrates to reduce optical payload mass, with IATF 16949 certification becoming mandatory for automotive lidar programs.
- Photovoltaics:Bifacial panel architectures with UV-patternable encapsulation layers are gaining traction. This application sidesteps the rare-earth dopant traceability requirements that constrain semiconductor supply chains.
- Display Technology:Mature procurement patterns consolidate volume with qualified Tier-1 substrate suppliers serving consolidated panel manufacturers.
- Coatings:Anti-reflective and protective layers deposited on photosensitive glass substrates for harsh-environment optical systems.
Display Technology maintains the largest installed base; Sensors show the steepest expansion trajectory.
End User:
Certification intensity distinguishes buyer categories, with aerospace and automotive demanding full material provenance versus electronics' focus on cost optimization.
- Aerospace:Star-tracker and lidar payload manufacturers drive specifications for lightweight optical components. EU REACH compliance on hazardous substance restrictions tightens material purity requirements, with ECHA audits accelerating across German and French supply bases.
- Automotive:Lidar system integrators concentrate procurement with IATF 16949-certified Tier-1 suppliers, excluding Tier-2 foundries from high-volume programs.
- Electronics:Semiconductor lithography tool builders in East Asia qualify ultraviolet-curable formulations for next-generation mask aligners.
- Healthcare:Biomedical imaging equipment manufacturers specify low-birefringence substrates for precision diagnostic systems.
Electronics dominates current procurement volumes; Aerospace is expanding most quickly.
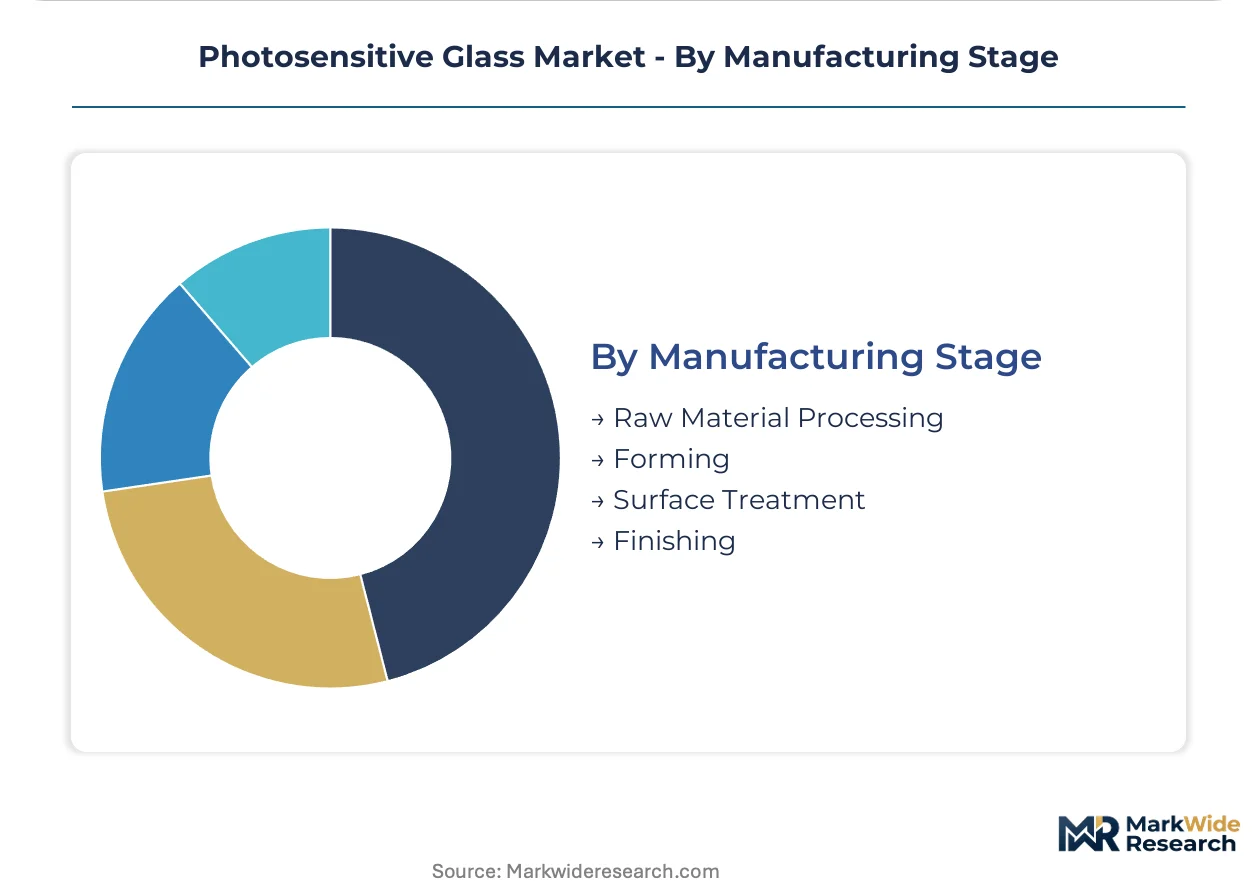
Manufacturing Stage:
Capital intensity and regulatory exposure vary across the value chain, with raw material processing facing the steepest environmental compliance costs.
- Raw Material Processing:Silver and cerium dopant refining faces EPA hazardous waste rules in the U.S. and tightening China GB standards under MEE oversight. Foundries backward integrate into Australian and Canadian mining operations to secure certified provenance.
- Surface Treatment:EU F-Gas Regulation phase-down pressures refrigerant-dependent polishing processes in German and French optical clusters, driving aqueous chemo-mechanical planarization retrofits.
- Forming:Precision molding and drawing operations for substrate blank production.
- Finishing:Final dimensional calibration and quality verification for optical-grade specifications.
Raw Material Processing anchors value capture; Surface Treatment faces the most acute regulatory transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping photosensitive glass manufacturing geography as EPA hazardous waste rules elevate U.S. processing costs while Asian competitors operate under less stringent discharge protocols. This compliance-cost gap is pulling volume toward jurisdictions with lighter environmental enforcement, though EU REACH restrictions create countervailing pressure for European purity standards.
United States
Domestic lidar and aerospace sensor manufacturers drive demand for lightweight optical substrates. EPA RCRA governance of silver-bearing effluent elevates capital intensity for foundries without hedged waste processing contracts. California's precision optics corridor around San Jose hosts qualified suppliers serving automotive Tier-1 programs requiring IATF 16949 certification.
Germany
EU ECHA audits are accelerating lead-free high-index glass reformulation ahead of REACH enforcement windows. Jena and Mainz anchor continental production capacity for laser-grade substrates with sub-50ppm homogeneity specifications. Bavarian foundries are retrofitting aqueous chemo-mechanical planarization systems to maintain surface figure under F-Gas Regulation phase-down schedules.
China
Domestic precision optics demand is decoupling from legacy borosilicate supply chains as semiconductor lithography expansion accelerates. MEE oversight is tightening GB standards for optical material emissions, reshaping import eligibility for foreign substrate suppliers. Yangtze River Delta foundries are scaling dedicated production lines for ultraviolet-curable formulations serving mask aligner builders.
Japan
East Asian lithography tool qualification programs are pulling substrate demand toward ultraviolet-curable photosensitive formulations. METI industrial standards govern rare-earth dopant traceability for semiconductor-grade supply chains. Osaka-based optical glass specialists occupy positions in biomedical imaging substrate procurement where low-birefringence specifications dominate buyer priorities.
India
BIS standards alignment with ISO 10110 is creating import substitution potential for domestic precision optics foundries. PLI scheme incentives for specialty materials could accelerate local photosensitive glass capacity expansion. Maharashtra and Gujarat industrial corridors are attracting technical talent from battery and magnet material sectors for cerium dopant optimization roles.
Photosensitive Glass Market Competitive Environment
German producers anchor the premium-tier certification vector; Japanese specialists hold positions in ultraviolet-curable formulations for lithography applications. The vendor base concentrates around rare-earth dopant security as buyers demand certified provenance, forcing foundries toward backward integration or multi-year offtake agreements. Three archetypes dominate: vertically integrated conglomerates with captive mining relationships, mid-cap specialists with regional cluster proximity, and technology licensors with digital twin integration capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified positions in automotive lidar supply chains.
Among German fabricators, SCHOTT AG exemplifies the vertically integrated archetype through upstream control over rare-earth dopant sourcing. Corning Incorporated represents North American capacity for semiconductor-grade fused silica substrates. HOYA Corporation occupies a specialist position within East Asian ultraviolet-curable formulation supply chains. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning in a market where certification intensity separates premium from economy procurement tiers.
| Leading Market Players |
|---|
| Corning Incorporated |
| SCHOTT AG |
| AGC Inc. |
| HOYA Corporation |
| Nippon Electric Glass Co., Ltd. |
| IPG Photonics Corporation |
| OptiGrate Corporation |
| Sumita Optical Glass Co., Ltd. |
| 3D Glass Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Silver spot price volatility cascades through photosensitive glass supply chains into three distinct procurement tiers, with aerospace and semiconductor buyers absorbing premium markups for certified provenance while photovoltaic encapsulation customers negotiate volume-driven standard-grade contracts.
Pricing Analysis
Distributor margins compress most acutely in the standard glass tier, where direct-to-OEM contracts bypass intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels separates laser-grade optical substrates certified to sub-50ppm homogeneity from display-grade alternatives. Price differentiation hinges on rare-earth dopant traceability documentation and IATF 16949 automotive certification status. Cost compression in the standard tier is intensifying because Chinese foundries are absorbing silver price spikes to capture photovoltaic volume. Automotive lidar integrators show lowest price sensitivity due to qualification lock-in, while display panel manufacturers negotiate aggressively on volume commitments.
Supply Chain Analysis
Workforce scarcity for cerium dopant optimization specialists constrains expansion in German and Japanese optical clusters, forcing foundries to compete against battery and magnet material sectors for talent. Supply concentrates in Germany, China, and Japan, with Jena and Mainz anchoring European laser-grade capacity while Yangtze River Delta foundries scale ultraviolet-curable formulations. Raw material dependencies center on Australian and Canadian silver mining operations, Malaysian rare-earth refining nodes, and Japanese high-purity chemical feedstocks. Single-source vulnerability around cerium supply creates structural exposure for non-integrated foundries. Distribution runs through qualified Tier-1 substrate suppliers serving consolidated lidar system integrators, with Tier-2 foundries increasingly excluded from high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage returns for players positioning between EPA-governed U.S. processing costs and MEE-regulated Chinese discharge protocols, with margin capture available to multi-regional suppliers maintaining parallel formulation inventories.
For Market Incumbents: To counter optical-grade fused silica substitution in waveguide applications, SCHOTT AG and Corning must deepen upstream control over rare-earth dopant refining while accelerating aqueous chemo-mechanical planarization retrofits ahead of EU F-Gas Regulation enforcement. Certification investment in IATF 16949 automotive standards represents the critical lever for defending qualified supplier status against emerging Asian competitors. For New Entrants and Emerging Players: Enter via India's precision optics corridor, where BIS standards alignment with ISO 10110 creates import substitution headroom without semiconductor-grade certification barriers. Maharashtra and Gujarat industrial corridors offer the most penetrable geography, with PLI scheme incentives reducing capital intensity for specialty materials capacity. A technical-licensing go-to-market angle partnering with Yangtze River Delta mask aligner builders bypasses direct competition with entrenched German and Japanese suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing regional cluster proximity and digital twin integration capabilities, as computational lithography convergence compresses prototyping cycles and rewards agile foundries. Long-term viability over a multi-year horizon favors players with captive Australian or Canadian mining relationships securing certified silver and cerium provenance. Watch for ECHA REACH enforcement acceleration as the inflection signal separating compliant from stranded inventory holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Captive cerium supply from Australian mining operations insulates against ECHA provenance audits. |
| Aqueous Chemo-Mechanical Planarization Retrofit | German foundries eliminate F-Gas dependent polishing to maintain sub-nanometer surface specifications. |
| IATF 16949 Certification Investment | Automotive lidar Tier-1 qualification unlocks high-volume procurement from consolidated system integrators. |
| Digital Twin Process Control Deployment | Unified ultraviolet exposure-to-furnace architectures compress prototype micro-lens array lead times. |
| India PLI Scheme Capacity Expansion | Maharashtra corridor localization captures import substitution demand from precision optics OEMs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with optical glass plant managers, procurement leads at lidar system integrators, rare-earth refining specialists, and semiconductor lithography tool builders with secondary validation against SEC 10-K filings, EU ECHA substance restriction databases, Chinese customs trade records, and Japanese METI industrial standards documentation. Bottom-up substrate volume estimates triangulated against top-down end-use demand projections from aerospace payload manufacturers and photovoltaic module assemblers.
Segment-weighting approaches distributed value and volume across optical glass, specialty glass, and standard glass product tiers, further disaggregated by sensor, photovoltaics, display technology, and coatings applications, with end-user splits across aerospace, automotive, electronics, and healthcare procurement channels. CAGRs were derived from fitted growth curves calibrated to qualification cycle durations and regulatory enforcement timelines, incorporating silver price volatility indices and rare-earth supply disruption scenarios as industry-specific sensitivity inputs across the projection horizon.
The model holds under stable EPA RCRA and EU REACH enforcement schedules; deviation in MEE GB standards implementation timelines or precious metals market dislocation would shift volume assumptions materially. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Component Tester Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
North America Laser Diode Market
Optical Components
Optical Isolator Market
Optical Components
Prism Coupler Market
Optical Components
Optical Fiber Array Market
Optical Components
Europe Optical Imaging Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Global Optical Imaging System Market