
 Lighting Management System Market | 2026-2036
Lighting Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Management System Market Analysis
LED phosphor substrates is hardening cost structures across luminaire manufacturing as rare-earth alternatives gain traction. Signify leverages in-house LED component sourcing to protect margin pools against material volatility. Schneider Electric anchors its portfolio on building-management software integration, while Acuity Brands specializes in architectural-grade control systems for premium commercial installations.
A lighting management system orchestrates illumination levels, color temperature, and energy consumption across networked fixtures through sensors, controllers, and centralized software platforms operating on 0-10V, DALI, or wireless protocols. These systems primarily reduce operational expenditure in commercial and institutional facilities by automating daylight harvesting, occupancy response, and demand-based dimming. Smart lighting and control systems now command the dominant share of product value as retrofit activity accelerates, while wireless technology segments built on Bluetooth and Zigbee protocols are expanding fastest due to reduced installation labor and infrastructure flexibility. Wired installations retain primacy in new development where conduit access permits permanent low-latency connectivity.
The EU Ecodesign Directive and F-Gas Regulation shape product design requirements across European markets, while the U.S. Department of Energy enforces minimum efficacy standards through federal appliance rules and ASHRAE 90.1 governs commercial building energy performance at state levels. China's GB standards and MIIT circular economy mandates are tightening domestic manufacturing compliance thresholds. Stakeholders must weigh interoperability investments against the risk of stranded assets as regulatory thresholds tighten and wireless protocol standards consolidate.
Market Dynamics
The transition from standalone lighting controls to fully integrated building energy management platforms is compressing vendor margins while expanding addressable system value per square foot across commercial real estate portfolios.
Growth Catalysts
- ASHRAE 90.1 stringency:US state-level adoption of updated commercial building energy codes is mandating networked lighting controls in new construction and major renovations, triggering wholesale specification upgrades.
- Healthcare facility retrofit cycles:Hospital and long-term care operators are replacing legacy fluorescent systems with tunable LED networks to support circadian rhythm protocols and reduce energy expenditure.
- Bluetooth mesh maturation:The protocol's self-healing network topology is eliminating gateway hardware requirements in mid-scale commercial deployments, cutting commissioning costs.
Market Restraints
- Rare-earth phosphor volatility:Yttrium and europium price swings are destabilizing LED component costs, squeezing luminaire manufacturers without captive material sourcing.
- Wireless spectrum congestion:Dense urban environments in Germany and the Netherlands are experiencing Bluetooth and Zigbee interference, degrading control reliability in high-rise commercial towers.
- Qualified commissioning technician scarcity:DALI-2 and wireless mesh configuration requires certified specialists, creating installation bottlenecks in secondary US metropolitan markets.
Strategic Opportunities
- India commercial real estate buildout:Green building certification mandates under CEA efficiency guidelines are creating first-mover advantage for networked lighting providers in Bengaluru and Mumbai office developments.
- LiDAR-sensor convergence:Spatial analytics providers are embedding occupancy detection into lighting fixtures, enabling new revenue streams from workplace utilization data.
- EU Green Deal renovation wave:The building efficiency financing mechanism is unlocking public sector retrofit budgets across municipal infrastructure in France, Italy, and Poland.
Industry Challenges
- Interoperability certification lag:DALI-2 and Zigbee 3.0 device certification backlogs at testing laboratories are delaying product launches by 4-8 months.
- Legacy 0-10V infrastructure stranding:Building owners with recent analog dimming investments face sunk-cost resistance when evaluating full digital control upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Management System Market |
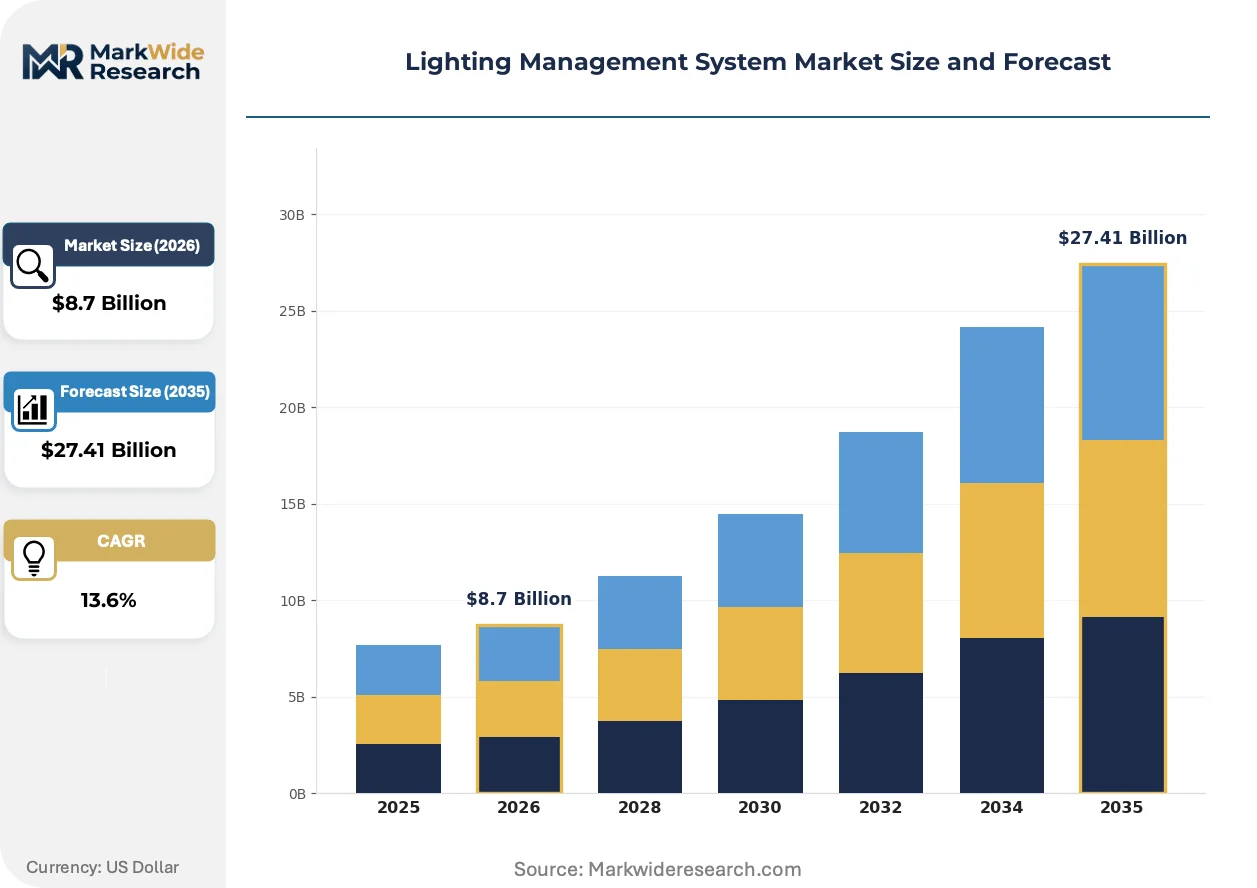
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Conventional Lighting, LED Fixtures, Control Systems Technology: Wired, Wireless, Bluetooth, Zigbee End User: Commercial, Residential, Industrial, Educational Installation: On-site, Off-site, Retrofits, New Development |
| Companies Covered | Lutron Electronics, Schneider Electric, Signify, Siemens, Honeywell International, Acuity Brands, ams OSRAM, Hubbell Incorporated, Legrand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Management System Market Emerging Trajectories
Human-centric lighting specifications are migrating from healthcare niche to mainstream commercial office design, rewiring procurement criteria around biological impact rather than illuminance metrics alone.
Power-over-Ethernet (PoE) lighting is electrifying building infrastructure economics by consolidating data and electrical distribution into single cable plant. Corporate headquarters and higher-education campuses with structured cabling refresh cycles are specifying PoE for new construction at accelerating rates. This convergence is compressing traditional electrical contractor scopes while elevating IT infrastructure vendors into lighting decision chains.
The EU F-Gas Regulation phase-down is forcing refrigerant-dependent luminaire cooling designs toward passive thermal management alternatives. Luminaire manufacturers serving the European market are redesigning high-bay industrial fixtures to eliminate fan-based cooling systems. Germany's industrial logistics sector is experiencing the most acute specification turbulence as warehouse operators reconcile efficiency targets with thermal performance guarantees.
Facility managers are unbundling lighting maintenance from comprehensive mechanical service contracts, creating standalone procurement categories for control system updates and sensor recalibration. This fragmentation is displacing traditional bundled facility management relationships in US commercial office portfolios. The shift is most pronounced in Class A assets managed by institutional real estate investment trusts seeking granular operational data visibility.
Lighting Management System Market Segmentation
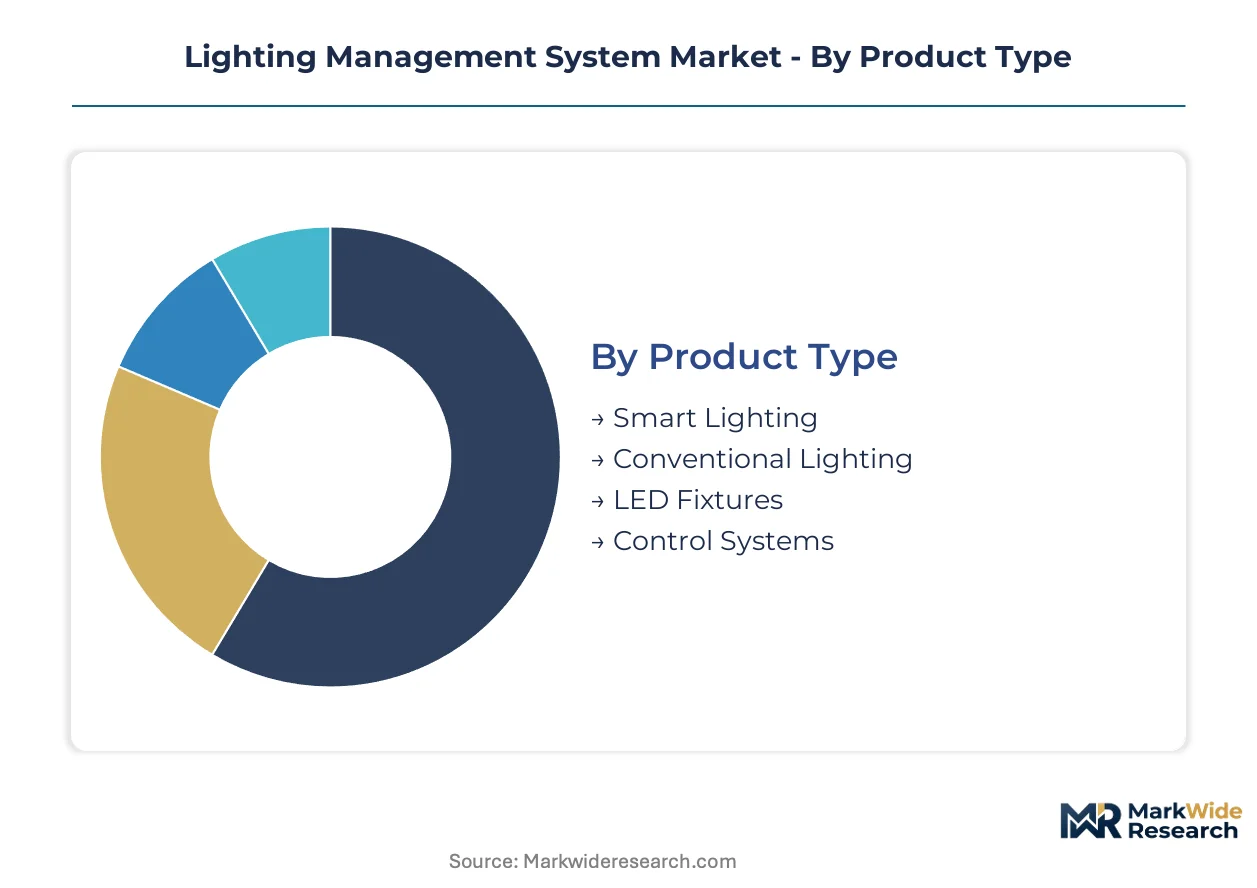
Lighting management systems fragment across four critical dimensions that determine procurement priorities, installation economics, and vendor competitive positioning. Product architecture, connectivity protocols, end-use requirements, and deployment context each reshape specification criteria and margin structures differently across commercial, institutional, and industrial settings.
Product Type:
Supply concentration in LED component sourcing hardens cost structures and vendor margin profiles across luminaire categories.
- Smart Lighting:Networked fixtures with embedded sensors and programmable drivers enable daylight harvesting, occupancy response, and circadian tuning through centralized software platforms. Demand concentrates in US healthcare facilities and German commercial offices where ASHRAE 90.1 and EU Ecodesign Directive compliance trigger specification upgrades. Bluetooth mesh and DALI-2 protocol wars are fragmenting vendor interoperability claims.
- Control Systems:Hardware-software combinations spanning wall stations, sensors, gateways, and cloud dashboards orchestrate multi-fixture networks across 0-10V, DALI, and wireless protocols. Germany's municipal infrastructure and US Class A office REITs are unbundling these from mechanical service contracts, creating standalone procurement categories with granular data visibility requirements.
- LED Fixtures:Solid-state luminaires with integrated drivers and thermal management systems serve as the physical foundation for retrofit and new construction projects.
- Conventional Lighting:Legacy fluorescent and HID systems persist in industrial lagging regions and budget-constrained secondary markets.
Today's leader: Smart Lighting. Tomorrow's challenger: Control Systems.
Technology:
Installation labor costs and infrastructure flexibility are rotating procurement criteria between wired permanence and wireless adaptability.
- Wireless:Self-healing mesh topologies eliminate conduit requirements and reduce commissioning labor in mid-scale commercial retrofits. Bluetooth protocol maturation is cutting gateway hardware costs in US office renovations and Netherlands high-rise towers, though spectrum congestion in dense urban clusters degrades reliability.
- Wired:Permanent low-latency connectivity through dedicated cable plant dominates new construction where conduit access permits infrastructure longevity. Germany's industrial logistics sector and US hospital new builds specify wired DALI-2 for guaranteed control reliability.
- Bluetooth:Mesh networking standard with native smartphone compatibility simplifies commissioning and end-user control interfaces.
- Zigbee:Proprietary mesh protocol with established building automation integration, prevalent in legacy smart building deployments.
Wireless installations are climbing the fastest as retrofit activity accelerates; wired retains primacy in new development pipelines.
End User:
Regulatory compliance thresholds and operational expenditure pressures concentrate demand differently across facility types.
- Commercial:Office towers, retail centers, and hospitality properties drive volume through ASHRAE 90.1 code mandates and utility rebate capture. US state-level energy code adoption and EU Green Deal renovation financing are triggering wholesale specification upgrades in Class A assets.
- Industrial:Manufacturing floors and warehouse facilities prioritize high-bay efficacy and thermal performance under EU F-Gas Regulation phase-down pressures.
- Residential:Single-family and multi-family dwellings represent fragmented demand with price-sensitive procurement and limited professional specification influence.
- Educational:K-12 and higher-education campuses specify tunable systems for learning environment optimization, with PoE convergence accelerating in structured cabling refresh cycles.
Commercial commands current value concentration; industrial applications are gaining share fastest under efficiency mandate pressure.
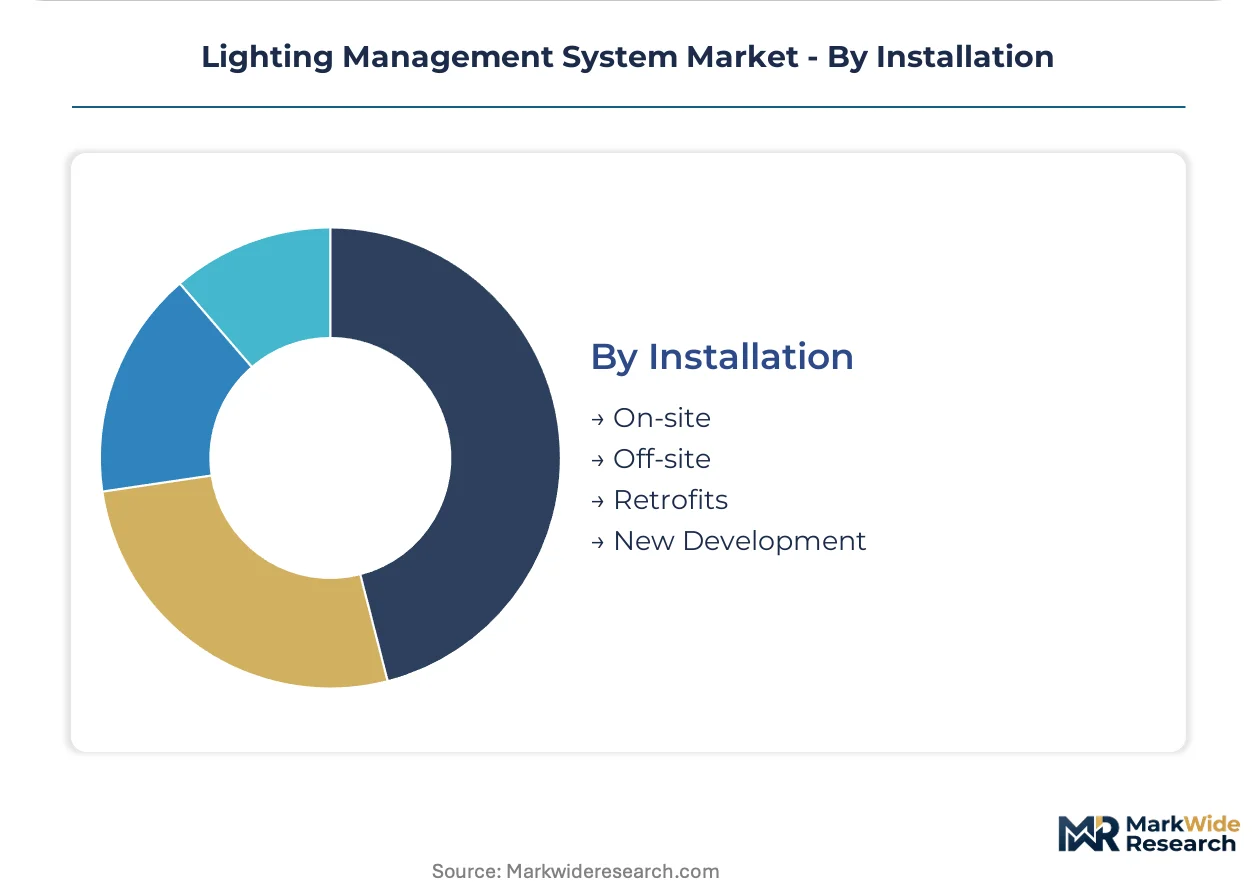
Installation:
Building lifecycle stage and capital availability determine deployment economics and vendor engagement models.
- Retrofits:Replacement of legacy fluorescent and early LED systems with networked controls dominates current activity. US healthcare facility replacement cycles and EU municipal building renovation waves are unlocking project finance for tunable LED networks with circadian protocol support.
- New Development:Greenfield construction permits integrated design of PoE infrastructure and permanent wired connectivity. Corporate headquarters and US higher-education campuses with structured cabling refresh cycles are specifying converged data-electrical distribution.
- On-site:Traditional installation with local commissioning and calibration services.
- Off-site:Prefabricated and pre-commissioned system delivery for accelerated deployment.
Retrofits anchor near-term revenue; new development secures longer-dated platform relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial logistics clusters anchor demand concentration for networked lighting controls, with municipal infrastructure retrofits and commercial office buildouts across multiple geographies reshaping procurement patterns.
Germany
Industrial warehouse operators and municipal building managers drive specification upgrades. The EU Ecodesign Directive and F-Gas Regulation mandate thermal management redesigns in high-bay fixtures. The Rhine-Ruhr logistics corridor experiences acute demand pressure as operators reconcile efficiency targets with passive cooling requirements.
United States
Class A office REITs and healthcare facility operators accelerate retrofit cycles. ASHRAE 90.1 state-level adoption triggers networked control mandates in new construction and major renovations. Secondary metropolitan markets face commissioning technician scarcity that bottlenecks installation timelines.
India
Bengaluru and Mumbai commercial developments create first-mover opportunities for networked lighting providers. CEA efficiency guidelines under green building certification mandates reshape procurement criteria. Western and Southern state buildouts concentrate demand in IT park and corporate campus developments.
Netherlands
High-rise commercial towers in dense urban cores experience Bluetooth and Zigbee spectrum congestion. National building efficiency standards drive control system upgrades across existing stock. Amsterdam and Rotterdam office clusters test protocol reliability under interference conditions.
China
GB standards and MIIT circular economy mandates tighten manufacturing compliance thresholds for export-oriented producers. Yangtze River Delta industrial zones integrate lighting management into smart factory platforms. Domestic commercial real estate developers specify converged building automation systems.
Lighting Management System Market Vendor Landscape
Global majors compete with regional champions across protocol standardization and software integration dimensions, producing a tiered structure where electrical conglomerates, lighting specialists, and building automation providers occupy distinct strategic positions. Consolidation pressure intensifies as building energy management platforms subsume standalone lighting controls. Three archetypes dominate: integrated electrical-industrial conglomerates with captive component sourcing, pure-play lighting technology specialists, and building automation software providers. Competitive moves center on interoperability certification acceleration and strategic partnerships with spatial analytics providers.
Among diversified electrical-industrial conglomerates, Schneider Electric and Siemens exemplify the building-management software integration archetype, while Signify occupies a position representing in-house LED component sourcing capabilities. Legrand and Acuity Brands sit within the architectural-grade control systems tier, with the latter specializing in premium commercial installation specifications. These named entities anchor industry-level commentary without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Lutron Electronics |
| Schneider Electric |
| Signify |
| Siemens |
| Honeywell International |
| Acuity Brands |
| ams OSRAM |
| Hubbell Incorporated |
| Legrand |
| Others |
Supply Flow & Price Mechanics
Power-over-Ethernet deployment in US higher-education campuses and corporate headquarters is compressing electrical contractor scopes while elevating IT infrastructure vendors into lighting procurement chains, simultaneously redistributing margin pools and rewiring supplier-buyer power dynamics across the value chain.
Pricing Analysis
Rare-earth phosphor cost pass-through from yttrium and europium volatility destabilizes LED component pricing, squeezing luminaire manufacturers without captive material sourcing. Three-tier pricing structure across premium, standard, and economy levels separates architectural-grade DALI-2 systems from Bluetooth mesh mid-market offerings and basic 0-10V retrofits. Cost compression in economy tiers is intensifying because of analog infrastructure stranding and buyer hesitation. Municipal infrastructure operators in Germany exhibit highest price sensitivity due to public procurement constraints, while US Class A office REITs prioritize data visibility over unit economics.
Supply Chain Analysis
Container freight rate normalization from Asia-Pacific manufacturing hubs to North American distribution centers is restoring margin stability for luminaire importers after pandemic-era volatility. Component sourcing concentrates in China for LED emitters and drivers, Germany for precision control hardware, and Mexico for final assembly serving US markets. Manufacturing rests on rare-earth phosphor substrates, copper thermal management materials, and silicon-based sensor modules. Single-source vulnerability in Bluetooth chipset supply creates bottleneck risk for wireless control vendors. Distribution runs through electrical wholesale distributors and direct specification sales to large commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lighting Management System Market functions as a stable compounder anchored by regulatory ratchet effects—ASHRAE 90.1, EU Ecodesign Directive, and national building efficiency codes that tighten predictably and trigger replacement cycles.
For Market Incumbents: Deepen backward integration into LED component sourcing to insulate margin pools against rare-earth phosphor volatility. Prioritize DALI-2 and Bluetooth mesh certification acceleration to clear testing laboratory backlogs that delay product launches by 4-8 months. Defend against building automation software providers subsuming standalone lighting controls by embedding spatial analytics partnerships. For New Entrants and Emerging Players: Launch via wireless-first specification in India commercial real estate buildout, where CEA efficiency guidelines create first-mover advantage in Bengaluru and Mumbai IT park developments. Target healthcare facility retrofit cycles with tunable LED networks supporting circadian rhythm protocols. Penetrate through commissioning technician training partnerships that address scarcity bottlenecks in secondary US metropolitan markets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale wireless control specialists with Bluetooth mesh expertise but limited building management software integration. Long-term viability centers on protocol standardization winners as DALI-2 and Zigbee 3.0 consolidate. Watch for inflection when EU Green Deal renovation wave financing unlocks public sector retrofit budgets across municipal infrastructure in France, Italy, and Poland.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Acceleration | DALI-2 and Bluetooth mesh testing laboratory partnerships compress 4-8 month product launch delays. |
| Spatial Analytics Integration | LiDAR-sensor convergence into lighting fixtures enables workplace utilization data revenue streams. |
| PoE Infrastructure Convergence | Corporate headquarters specify single-cable data-electrical distribution in structured cabling refresh cycles. |
| Commissioning Technician Training Programs | Certified specialist pipelines address installation bottlenecks in secondary US metropolitan markets. |
| Rare-Earth Alternative Sourcing | Non-europium phosphor R&D protects margin pools against yttrium price volatility in LED manufacturing. |
Methodological Framework
Multiple input streams — facility manager interviews, electrical contractor field assessments, and regulatory filing analysis — were reconciled to construct demand estimates. Primary conversations with building automation specifiers, lighting controls procurement officers, and municipal infrastructure planners informed installation economics and adoption timelines. Secondary validation drew from ASHRAE code adoption databases, EU Ecodesign Directive implementation reports, and utility rebate program disclosures. Bottom-up project pipeline enumeration and top-down building stock penetration modeling were cross-checked for convergence.
Data-stream reconciliation across product architecture, connectivity protocol, and end-use dimensions produced volume and value estimates across the projection horizon. Segmentation modeling captured smart lighting, control systems, LED fixtures, and conventional lighting categories crossed with wireless, wired, Bluetooth, and Zigbee technology tiers. CAGRs were derived from replacement cycle analysis and regulatory mandate phase-in schedules. Forecast inputs included healthcare facility retrofit cycle timing, EU F-Gas Regulation thermal management redesign requirements, and PoE infrastructure refresh patterns in higher education.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare-earth phosphor price spike scenarios or wireless spectrum congestion degradation in dense urban clusters. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Lighting Control System Market
Lighting
Europe Decorative Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Intelligent Lighting Controls Market
Lighting
Inspection Lighting Fixture Market
Lighting
Human Centric Lighting Market
Lighting
Lighting Market
Lighting
Ambient Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Directional Luminaire Market
Lighting
Hazardous Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Flexible Lighting Foils Market
Lighting
GCC Smart Lighting Market
Lighting
COB Photo Light Market
Lighting
Wireless Lighting Market