
 Fiber-Optic Attenuator Market | 2026-2036
Fiber-Optic Attenuator Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber-Optic Attenuator Market Foresight
Distributor networks serving telecom contractors is fragmenting as direct procurement from attenuator manufacturers gains share. Finisar Corporation leverages its vertically integrated optical component platform to control pricing on programmable attenuator lines. Corning Incorporated anchors North American supply through captive fiber cable distribution that bundles attenuators with connectivity solutions. TE Connectivity Ltd. competes on connector interoperability across LC and SC formats in enterprise cabling.
A fiber-optic attenuator is a passive optical device that reduces signal power by a specified decibel value, typically manufactured with doped fiber, thin-film metal coatings, or air-gap architectures to achieve precision losses from 1 dB to 30 dB. Its primary purpose is preventing receiver overload and maintaining optimal optical signal-to-noise ratios in high-speed transmission systems. Fixed attenuators dominate volume in legacy telecommunications outside plant installations where standardized loss values suffice. Variable attenuators capture expanding margin pools in laboratory and test environments where technicians require real-time power adjustment across 1310 nm and 1550 nm wavelengths.
The FCC's broadband equity programs shape product specifications for US-deployed attenuators, while China's MIIT enforces GB standards on connector interoperability that influence export manufacturing. REACH compliance in Europe restricts certain metal-doping materials used in thin-film attenuator production, pushing suppliers toward all-fiber designs. Stakeholders must monitor evolving connector density requirements in hyperscale data centers, where the transition from 40G to 400G optical links redefines attenuator form factors and insertion loss tolerances.
Market Dynamics
Wavelength-division multiplexing deployments are forcing precision optical power management into every network layer, while hyperscale data center operators in China and the United States compress procurement cycles and demand connector-format standardization.
Growth Catalysts
- FCC broadband equity programs:Infrastructure subsidies accelerate fiber-to-the-home rollouts across the United States, consuming fixed and variable attenuators in outside plant installations.
- Hyperscale data center buildouts:Operators around Beijing, Shanghai, and Shenzhen standardize on MTP/MPO connector formats, driving volume demand for high-density attenuator configurations.
- Telecommunications carrier expansion:Carriers deploy wavelength-division multiplexing systems that require precise optical power balancing to prevent receiver overload.
Market Restraints
- REACH compliance in Europe:Restrictions on metal-doping materials used in thin-film attenuator production push suppliers toward costlier all-fiber designs.
- Supply concentration in China:Connector manufacturing clusters around Shenzhen create single-source risk for MTP/MPO-compatible attenuator supply chains.
- Substitution by active components:Erbium-doped fiber amplifiers with integrated gain control reduce attenuator count in some long-haul links.
Strategic Opportunities
- Underpenetrated India market:TRAI-mandated broadband expansion creates first-wave fiber deployment demand in tier-two cities.
- 400G optical link transition:Hyperscale facilities require redesigned attenuator form factors with tighter insertion loss tolerances.
- Laboratory and test environments:Variable attenuators capture margin pools where technicians require real-time power adjustment across 1310 nm and 1550 nm wavelengths.
Industry Challenges
- Connector interoperability certification:China's MIIT enforces GB standards that delay export manufacturing timelines for foreign suppliers.
- Legacy system integration:Outside plant technicians face compatibility gaps when mating new attenuators with aged SC and FC connector infrastructure.
- Skill gaps in optical testing:Field technicians lack training on variable attenuator calibration procedures for DWDM system commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber-Optic Attenuator Market |
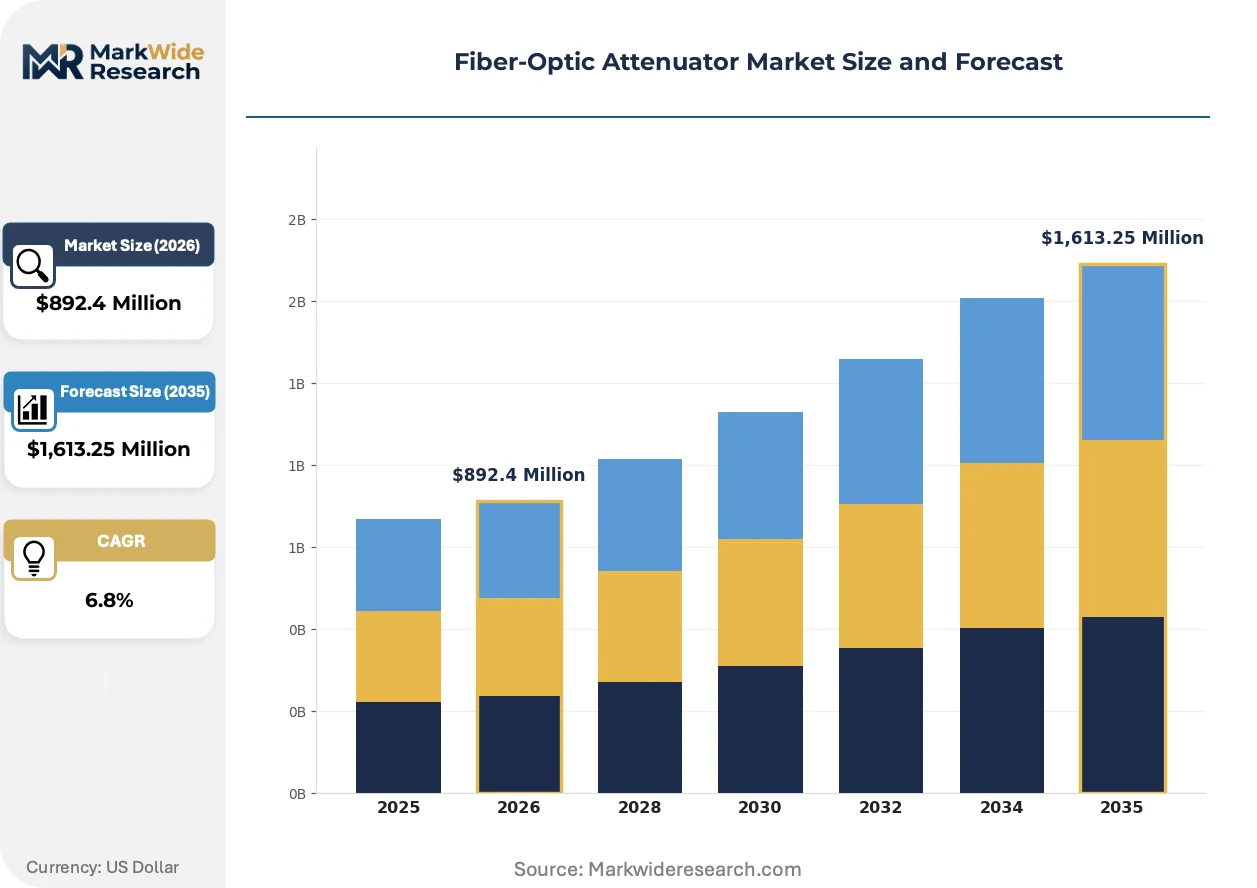
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Attenuators, Variable Attenuators, Programmable Attenuators, Inline Attenuators Technology: LC Connectors, SC Connectors, ST Connectors, MTP/MPO Connectors End User: Telecommunications, Data Centers, Enterprises, Research Institutions Application: Network Infrastructure, Signal Conditioning, Fiber Testing, Optical Communication |
| Companies Covered | Finisar Corporation, Corning Incorporated, TE Connectivity Ltd., CommScope Holding Company, Inc., Nexans S.A., Sumitomo Electric Industries, Ltd., 3M Company, Optical Cable Corporation, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber-Optic Attenuator Market Shifts & Advancements
Optical power management architectures are fragmenting as passive attenuation converges with active monitoring, while procurement patterns compress traditional distributor margins.
Thin-film metal coating technology dominates fixed attenuator manufacturing, delivering precise loss values from 1 dB to 30 dB through controlled deposition processes. Hyperscale operators and telecommunications carriers specify these devices for standardized outside plant installations. The technology is migrating from legacy single-mode applications toward polarization-maintaining fiber configurations in coherent optical systems.
REACH restrictions on hazardous substances are eliminating cadmium and lead-based dopants from European-sourced attenuator production. Manufacturers reformulate thin-film layers or switch entirely to doped-fiber architectures to maintain market access. Laboratory and test equipment suppliers face the steepest cost adjustments, as their low-volume, high-precision product lines absorb material substitution premiums.
Direct procurement from attenuator manufacturers is displacing traditional distributor networks serving telecom contractors. Contractors in the United States and China now negotiate volume agreements that bundle attenuators with connectivity solutions, eroding middle-tier distributor margins. Enterprise cabling installers in Europe retain distributor relationships for LC and SC format interoperability support, slowing channel consolidation there.
Fiber-Optic Attenuator Market Segmentation
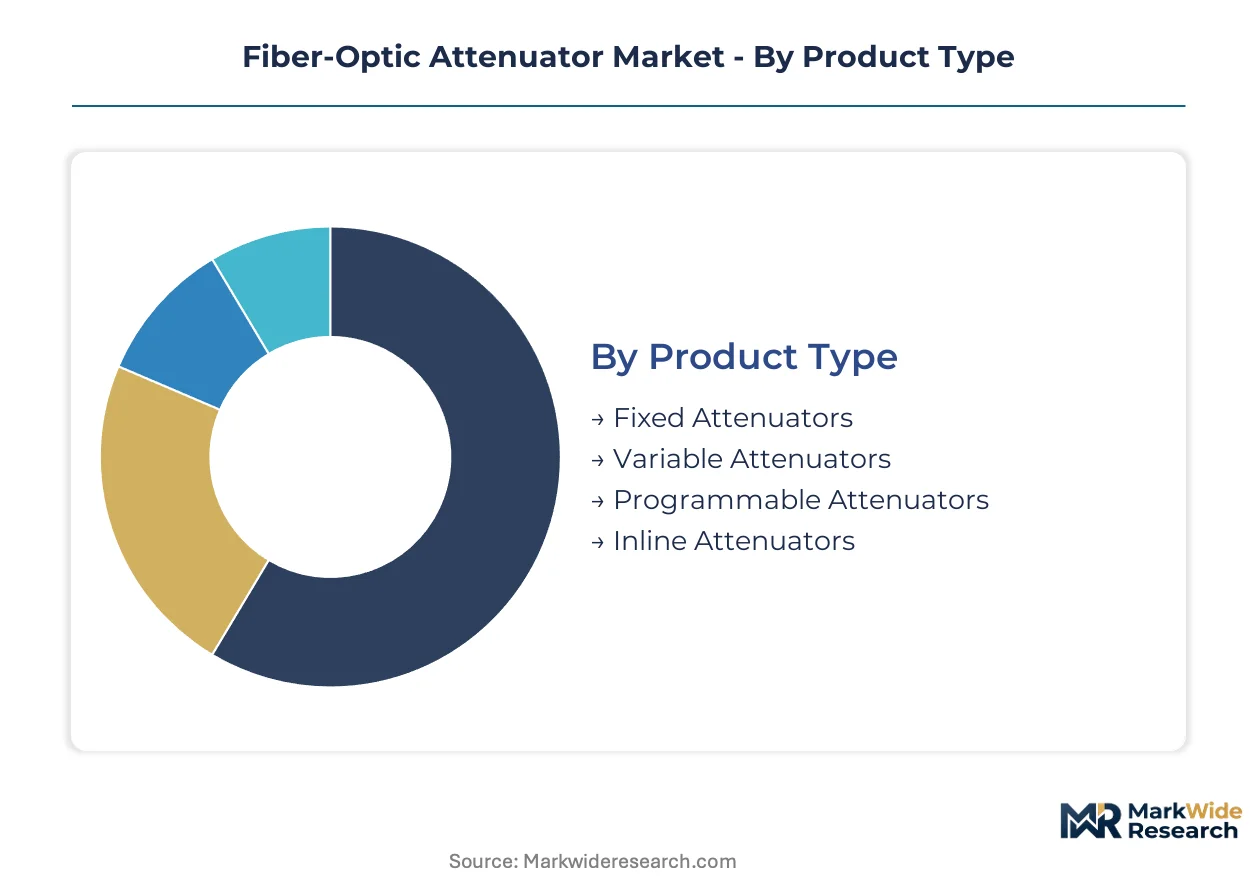
Segmentation in the fiber-optic attenuator market reveals distinct procurement cycles across product categories. Fixed attenuators turn over rapidly in outside plant rollouts, while programmable variants face elongated qualification timelines in laboratory environments.
Product Type:
Replacement cycles vary dramatically across this category, with fixed units cycling every 18-24 months in carrier networks versus 5-7 year lifespans for programmable systems in test labs.
- Fixed Attenuators:Passive devices delivering precise loss values from 1 dB to 30 dB through doped fiber or thin-film metal coatings. Telecommunications carriers in the United States deploy these in FCC-subsidized fiber-to-the-home rollouts where standardized loss values suffice for outside plant installations.
- Variable Attenuators:Mechanically or electrically adjustable devices enabling real-time power adjustment across 1310 nm and 1550 nm wavelengths. Research institutions and telecommunications laboratories in China specify these for DWDM system commissioning where technicians require dynamic optical power balancing.
- Programmable Attenuators:Software-controlled units with automated calibration routines for high-throughput testing environments.
- Inline Attenuators:Compact form-factor devices integrated directly into patch cords for space-constrained data center deployments.
Fixed attenuators anchor the volume base while variable attenuators gain share at the steepest rate.
Technology:
Cost tiers stratify sharply across connector formats, with legacy SC and ST interfaces commanding commodity pricing while MTP/MPO configurations capture premium positioning in hyperscale facilities.
- LC Connectors:Small-form-factor push-pull interfaces dominating enterprise cabling installations. European data centers standardize on LC formats for 10G and 25G optical links, though interoperability certification delays from ECHA REACH compliance inflate procurement costs for thin-film variants.
- SC Connectors:Square-bodied push-pull connectors retaining installed base in legacy telecommunications infrastructure. Outside plant technicians in the United States face compatibility gaps when mating new attenuators with aged SC connector infrastructure in rural FCC-funded deployments.
- ST Connectors:Bayonet-mount interfaces persisting in industrial and military fiber installations.
- MTP/MPO Connectors:Multi-fiber push-on formats enabling high-density parallel optics in 400G applications.
SC connectors retain the largest installed base while MTP/MPO configurations expand most quickly in hyperscale buildouts.
End User:
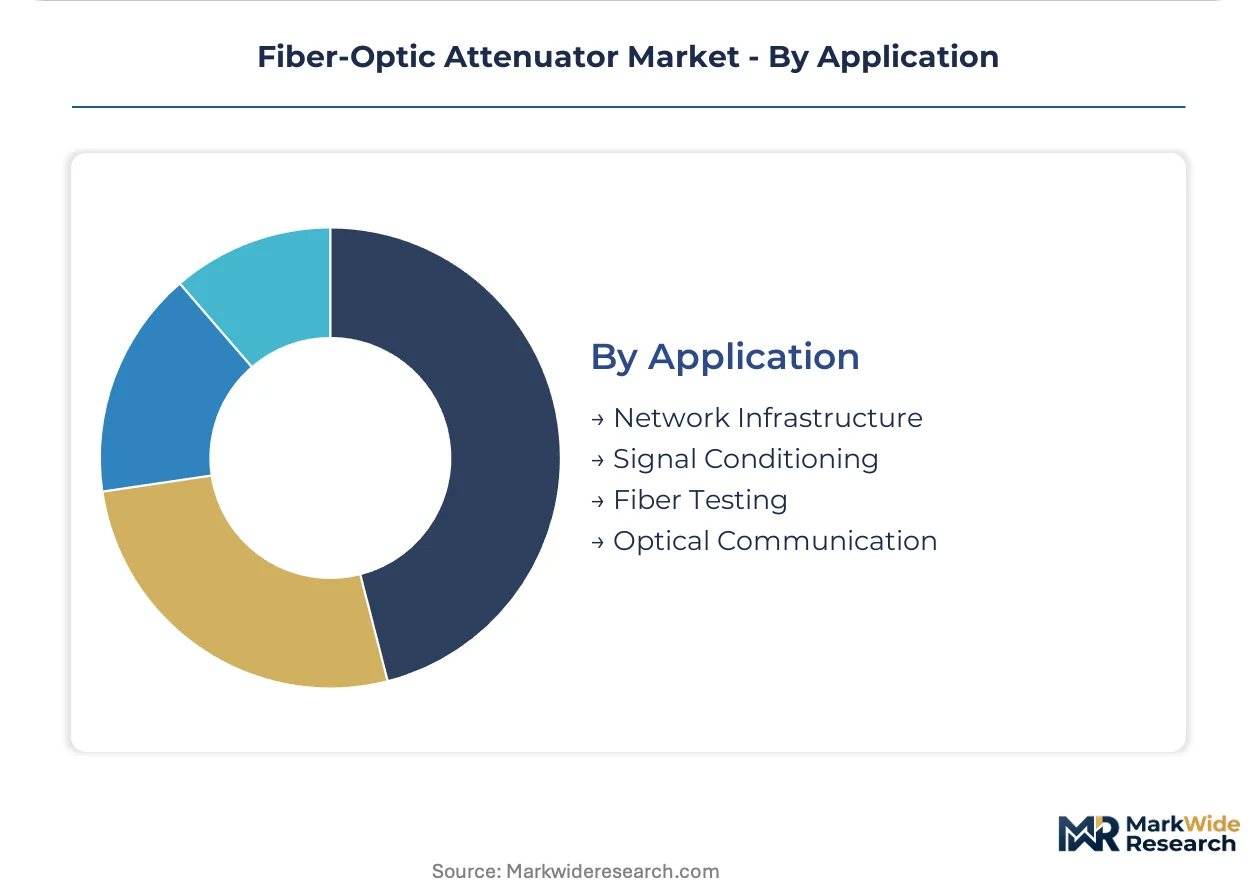
Application intensity diverges across customer types, with telecommunications carriers consuming attenuators in volume for wavelength-division multiplexing while research institutions prioritize precision over scale.
- Telecommunications:Carriers deploying wavelength-division multiplexing systems requiring precise optical power management at every network layer. China's MIIT-mandated broadband expansion drives concentrated demand around Beijing, Shanghai, and Shenzhen manufacturing clusters.
- Data Centers:Hyperscale operators compressing procurement cycles and demanding connector-format standardization across 40G to 400G transitions. United States-based cloud providers specify MTP/MPO-compatible attenuators with tightened insertion loss tolerances for new construction.
- Enterprises:Corporate IT departments upgrading structured cabling for higher-speed optical links.
- Research Institutions:Universities and national laboratories requiring calibration-grade variable attenuators for coherent optical system development.
Telecommunications anchors procurement volume while data centers drive the steepest specification escalation.
Application:
Margin structures invert across use cases, with fiber testing commanding premium pricing for laboratory-grade precision while network infrastructure operates on volume-driven cost models.
- Network Infrastructure:Outside plant and data center installations requiring reliable passive optical power reduction. Fixed attenuators dominate this segment in fiber-to-the-home deployments subsidized by United States FCC broadband equity programs.
- Signal Conditioning:Optical power balancing in wavelength-division multiplexing systems to prevent receiver overload. Variable and programmable attenuators capture expanding margin pools here as carriers deploy increasingly dense DWDM configurations.
- Fiber Testing:Laboratory and field verification of optical link performance.
- Optical Communication:General-purpose transmission system integration.
Network infrastructure absorbs the highest unit volumes while signal conditioning commands the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suppliers in Germany command pricing premiums for REACH-compliant thin-film attenuators, while Chinese manufacturers absorb margin compression from MIIT-mandated GB standard certification costs. This asymmetry reshapes procurement flows across telecommunications infrastructure deployments.
United States
FCC broadband equity programs accelerate fiber-to-the-home rollouts across rural markets. Outside plant contractors consume fixed attenuators in standardized loss configurations. Deployment clusters concentrate in Texas, California, and Midwest states where carrier consolidation drives volume procurement.
China
Hyperscale data center buildouts around Beijing, Shanghai, and Shenzhen generate concentrated demand for MTP/MPO-compatible attenuators. MIIT enforces GB standards on connector interoperability that delay export manufacturing timelines. Manufacturing gravity centers on Shenzhen connector clusters serving domestic cloud operators.
Germany
REACH restrictions on cadmium and lead-based dopants eliminate thin-film metal coating options for European-sourced production. Manufacturers reformulate toward all-fiber architectures to maintain market access. Industrial fiber installations in Bavaria and North Rhine-Westphalia retain bayonet-mount ST connector specifications.
India
TRAI-mandated broadband expansion creates first-wave fiber deployment demand in tier-two cities. Fixed attenuators dominate initial infrastructure builds where standardized loss values suffice. Procurement concentrates through telecommunications carriers rather than hyperscale data center operators.
Japan
METI standards on optical component reliability shape product specifications for telecommunications and industrial applications. Precision manufacturing traditions support laboratory-grade variable attenuator production. Industrial fiber installations maintain demand for polarization-maintaining fiber configurations in coherent optical systems.
Fiber-Optic Attenuator Market Competitive Landscape
Vertically integrated optical component platforms and specialized connectivity suppliers split the market between captive supply chains and open procurement channels. The vendor base organizes around three archetypes: integrated optical component manufacturers controlling pricing through backward integration, cable-centric suppliers bundling attenuators with fiber connectivity solutions, and connector specialists competing on format interoperability. Dominant competitive moves include direct procurement agreements that displace distributor networks, and portfolio diversification into programmable attenuator lines for laboratory environments.
Among North American-integrated suppliers, Finisar Corporation and Corning Incorporated exemplify the vertically integrated archetype, with the former representing software-controlled programmable attenuator positioning and the latter anchoring captive fiber cable distribution. TE Connectivity Ltd. occupies the connector-specialist tier, competing on LC and SC format interoperability across enterprise cabling installations. These three entities illustrate the strategic segmentation between component integration, bundled connectivity, and format specialization that defines competitive positioning in optical power management.
| Leading Market Players |
|---|
| Finisar Corporation |
| Corning Incorporated |
| TE Connectivity Ltd. |
| CommScope Holding Company, Inc. |
| Nexans S.A. |
| Sumitomo Electric Industries, Ltd. |
| 3M Company |
| Optical Cable Corporation |
| Amphenol Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in Shenzhen connector clusters is compressing margins for MTP/MPO-compatible attenuator suppliers while simultaneously accelerating direct procurement negotiations between manufacturers and hyperscale operators. This utilization dynamic forces suppliers to absorb GB standard certification costs from China's MIIT or cede volume to vertically integrated competitors with captive fiber platforms.
Pricing Analysis
Configured-to-order pricing for laboratory-grade variable attenuators commands substantial premiums over standard fixed attenuator configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with REACH-compliant thin-film variants from German suppliers capturing the top tier. Pricing pressure stems from direct procurement agreements that displace distributor markups in United States and Chinese markets. Telecommunications carriers exhibit the highest price sensitivity due to standardized loss requirements in FCC-subsidized fiber-to-the-home rollouts, while research institutions prioritize precision over cost.
Supply Chain Analysis
Extended payment terms from hyperscale data center operators are forcing attenuator manufacturers to utilize supply-chain finance facilities to bridge working capital gaps. Manufacturing concentrates in China, Japan, and Germany, with raw material dependencies on specialized optical fiber, thin-film metal deposition materials, and precision ceramic ferrules. Single-source vulnerability around Shenzhen connector clusters creates concentration risk for MTP/MPO-compatible supply chains. Distribution runs through direct manufacturer relationships with telecommunications carriers and cloud operators, bypassing traditional distributor networks in North America and Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber-optic attenuator market is recovering from a cyclical trough as FCC broadband equity programs and China's data center buildouts restock channel inventory. Carrier capital expenditure cycles and hyperscale facility commissioning timelines drive this recovery pattern.
For Market Incumbents: Harden supply chain resilience by qualifying secondary connector manufacturing sources outside Shenzhen to mitigate MIIT certification delays and single-source concentration. Deepen backward integration into doped-fiber architectures to offset REACH material restrictions and capture margin from thin-film substitution. Prioritize programmable attenuator R&D for laboratory environments where variable attenuators command pricing premiums.
For New Entrants and Emerging Players: India's tier-two cities under TRAI-mandated broadband expansion represent the most penetrable entry point for fixed attenuator volume plays. Laboratory and test equipment channels in Japan offer margin-rich positioning for calibration-grade variable attenuators with METI reliability certification. Partner with regional telecommunications distributors to bypass incumbent direct procurement relationships in underserved geographic clusters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among programmable attenuator suppliers serving test and measurement laboratories with multi-year calibration service contracts. Long-term viability favors targets with MIIT GB standard pre-certification and REACH-compliant all-fiber manufacturing capabilities. Monitor hyperscale data center capex announcements as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Doped-Fiber Production | REACH compliance in Europe eliminates thin-film alternatives, favoring captive fiber architectures. |
| MIIT GB Standard Pre-Certification | Chinese regulatory alignment accelerates export manufacturing timelines for foreign suppliers. |
| Programmable Attenuator Platform Launch | Software-controlled units capture laboratory margin pools with automated calibration routines. |
| Direct Procurement Agreement Expansion | Bypassing distributor networks aligns with hyperscale operator purchasing compression trends. |
| Polarization-Maintaining Fiber Configuration | Coherent optical system demand from Japan's METI-regulated telecommunications sector supports premium positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with optical network engineers at telecommunications carriers, procurement leads at hyperscale data center operators, laboratory managers at research institutions, and product directors at attenuator manufacturers. Secondary validation drew from FCC broadband infrastructure filings, MIIT GB standard documentation, ECHA REACH substance restrictions, and customs trade data for optical component flows. Bottom-up volume estimates from connector format shipments were triangulated against top-down telecommunications capex allocations.
Calibration against historical carrier spending cycles and data center construction timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connector format, end-user vertical, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across these segments, incorporating wavelength-division multiplexing deployment trajectories and 400G optical link transition timelines as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in carrier capital expenditure cycles, hyperscale facility commissioning rates, or optical component trade flows would shift the trajectory. Forecasts reflect documented assumptions regarding FCC program continuity, MIIT standard enforcement, and REACH material restriction scope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Global Adaptive Optics Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Electro-Optic Modulators Market
Optical Components
CMP Polishing Machine Market
Optical Components
Optical Cross Connect Market
Optical Components
Fogless Mirror Market
Optical Components
Liquid Lenses Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Europe Scintillator Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Optical Isolator Market
Optical Components
Laser Module Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Co-Packaged Optics Market
Optical Components
South Korea Optical Detector Market