
 Global Wavelength Division Multiplexing (WDM) Equipment Market | 2026-2036
Global Wavelength Division Multiplexing (WDM) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wavelength Division Multiplexing (WDM) Equipment Market Foresight
Buyer concentration among cloud service providers is shifting as hyperscalers consolidate procurement around fewer vendors with vertically integrated optical portfolios. Huawei Technologies Co. Ltd. dominates domestic supply chains across Asia while Cisco Systems Inc. leverages its routing-to-optical convergence strategy in enterprise and data center interconnect deployments. Ciena Corporation anchors transatlantic and submarine cable upgrade cycles with programmable coherent modem technology.
Wavelength Division Multiplexing (WDM) equipment combines multiple optical carrier signals onto a single fiber by assigning each data stream a unique wavelength, typically operating in the C-band and L-band windows to maximize fiber capacity. Dense WDM systems now support 96 channels at 100 GHz spacing or 128 channels at 75 GHz spacing, enabling petabit-class transmission per fiber pair. Metro Networks and Data Center Interconnect applications command premium pricing due to latency-sensitive traffic patterns, while Long-Haul Transmission remains the volume anchor driven by submarine and terrestrial backbone refreshes. Optical Amplifiers and Transponders capture disproportionate margin pools as coherent DSP complexity rises with each baud-rate generation.
FCC spectrum and equipment authorization rules govern WDM deployment in US terrestrial networks, while China's MIIT enforces domestic GB standards and dual carbon goals that favor energy-efficient optical transport over electronic regeneration. ETSI and ITU-T frameworks shape interoperability requirements across European and international carrier procurement. Stakeholders must monitor coherent DSP roadmaps and foundry capacity allocation as 1.6 Tbps per wavelength development determines next-generation competitive positioning.
Market Dynamics
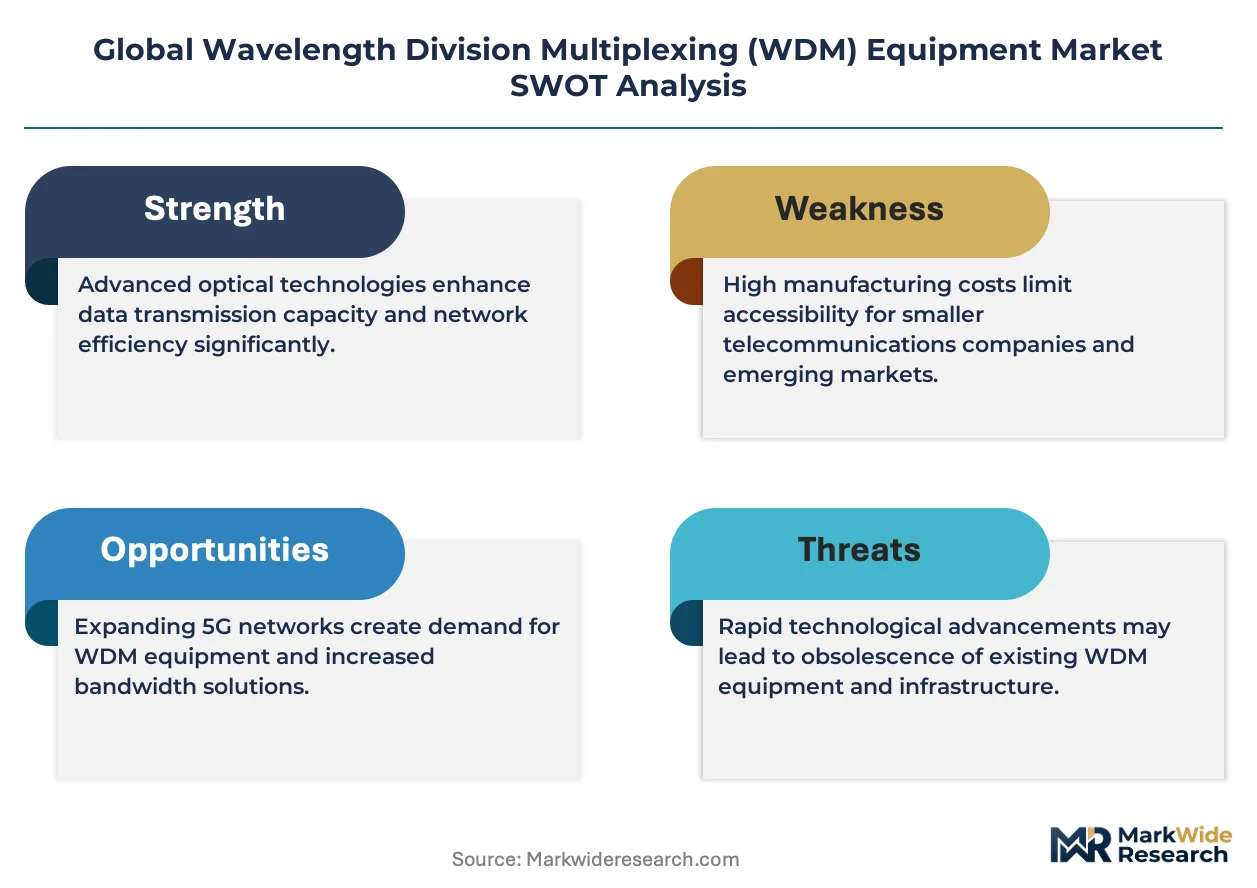
The migration from 100G to 400G/800G coherent transmission standards is compressing equipment refresh cycles and forcing DSP foundry capacity allocation battles among optical vendors.
Growth Catalysts
- AI Workload Expansion:Hyperscale data centers in the United States, China, and Germany are deploying dense wavelength infrastructure to support machine learning training clusters. Cloud service providers now mandate sub-millisecond latency for east-west traffic between facilities.
- MIIT Dual Carbon Mandates:China's Ministry of Industry and Information Technology enforcement favors all-optical switching over electronic regeneration. State-owned carriers must meet energy intensity targets that accelerate ROADM deployment.
- Submarine Cable Upgrades:Transatlantic and transpacific systems are replacing 10-year-old coherent terminals with programmable modems. Open cable specifications allow consortium members to source transponders independently from cable landing stations.
Market Restraints
- Indium Phosphide Wafer Constraints:Coherent DSP and laser chip production depends on limited III-V foundry capacity. Taiwan Semiconductor Manufacturing and GlobalFoundries dominate photonic integration runs.
- FCC Equipment Authorization Delays:Terrestrial WDM deployments in the United States face backlog at the Office of Engineering and Technology. New frequency bands for expanded C-band operation require extensive interference studies.
- Pluggable Module Substitution:400G ZR and ZR+ coherent pluggables are displacing chassis-based transponders in data center interconnect applications below 500 kilometers.
Strategic Opportunities
- India National Broadband Mission:BharatNet phase three targets 100 Mbps connectivity to 600,000 villages. Domestic equipment vendors gain preference under modified Preferential Market Access rules.
- L-band Amplification Expansion:Erbium-doped fiber amplifiers now cover both C-band and L-band windows. Metro networks can double fiber capacity without new cable deployment.
- Edge Computing Interconnect:5G radio access network fronthaul requires wavelength services to distributed edge data centers. Mobile network operators are procuring compact modular WDM systems for cell site aggregation.
Industry Challenges
- Coherent DSP Talent Scarcity:Algorithm design for higher-order modulation requires rare expertise in probabilistic constellation shaping. Foundries compete with system vendors for analog mixed-signal engineers.
- Multi-Vendor Interoperability Testing:Open Line Systems specifications from the Optical Internetworking Forum demand extensive validation cycles. Carriers report 12-18 month integration timelines for disaggregated terminal and line system combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wavelength Division Multiplexing (WDM) Equipment Market |
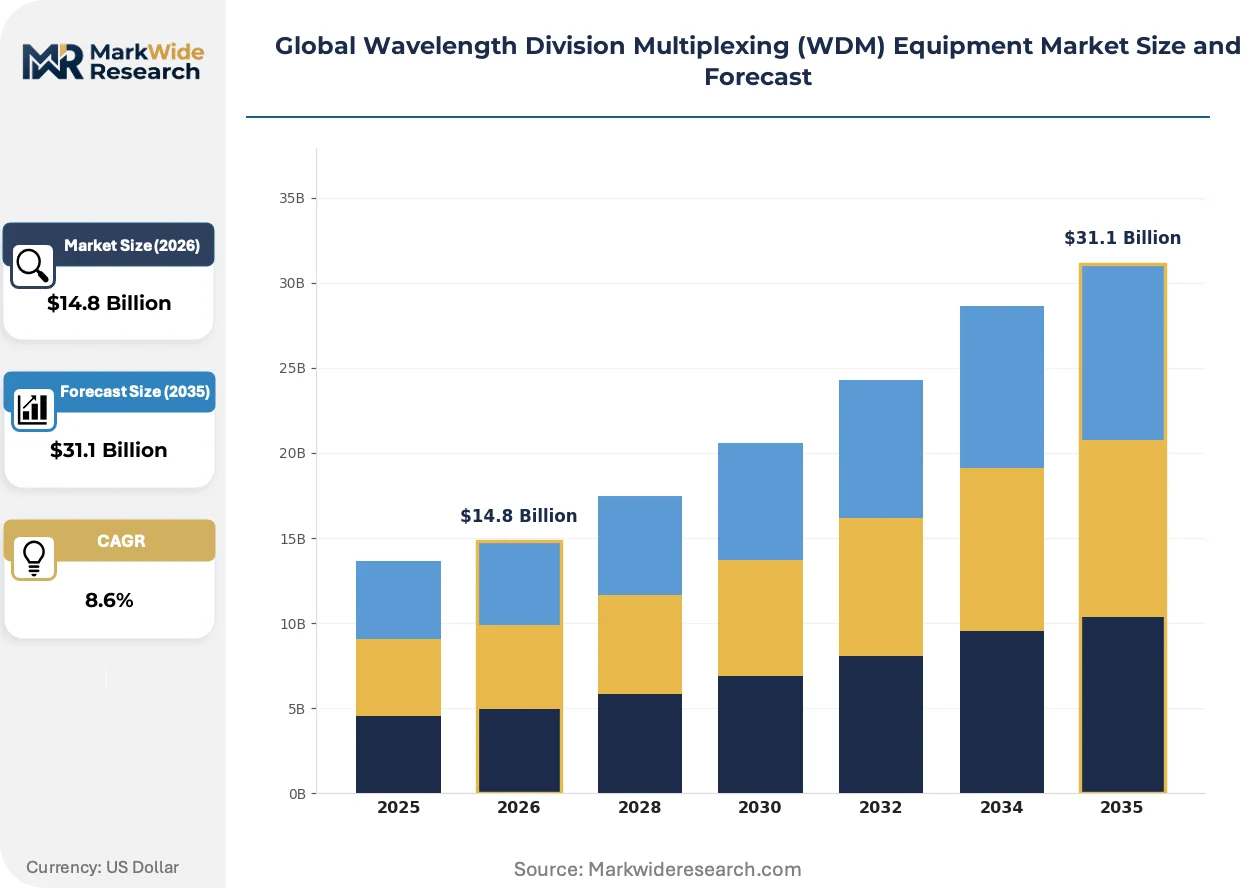
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiplexers, Optical Amplifiers, Transponders, Demultiplexers, Optical Switches Technology: Coarse WDM, Dense WDM, Optical Transport Network, Reconfigurable Optical Add-Drop Multiplexer, Optical Time Division Multiplexing Application: Long-Haul Transmission, Metro Networks, Data Center Interconnect, Access Networks, Enterprise Connectivity End User: Telecom Operators, Cloud Service Providers, Data Center Operators, Internet Service Companies, Managed Network Providers |
| Companies Covered | ZTE Corporation, Lumentum Holdings Inc., Huawei Technologies Co. Ltd., NEC Corporation, Fujitsu Limited, Cisco Systems Inc., Infinera Corporation, Sumitomo Electric Industries Ltd., Ciena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wavelength Division Multiplexing (WDM) Equipment Market Shifts & Advancements
Silicon photonics integration and programmable coherent modulation are collapsing cost-per-bit trajectories while regulatory energy mandates accelerate all-optical network architectures.
Third-generation silicon photonics platforms with integrated lasers and modulators are absorbing functions previously executed by discrete indium phosphide components. Cloud service providers are qualifying these designs for 400G data center interconnect transceivers at aggressive volume ramps. The technology is absorbing margin from traditional coherent subsystem suppliers by enabling direct supplier relationships between hyperscalers and semiconductor foundries.
ETSI standardization of optical transport network flexibility through the G.872 series revision is mandating hitless bandwidth adjustment capabilities. European incumbent carriers must demonstrate power-proportional operation to satisfy CSRD sustainability reporting requirements. Metro aggregation networks across Germany, France, and Italy are prioritizing vendors with demonstrated software-defined optical layer control.
Consolidated procurement desks at the largest cloud service providers now dictate multi-year volume commitments in exchange for roadmap influence. Equipment vendors are responding with captive supply arrangements for coherent DSP and optical engine production. This concentration is most visible in the United States, where Amazon Web Services, Microsoft Azure, and Google Cloud collectively account for the majority of 400G port shipments.
Global Wavelength Division Multiplexing (WDM) Equipment Market Segmentation
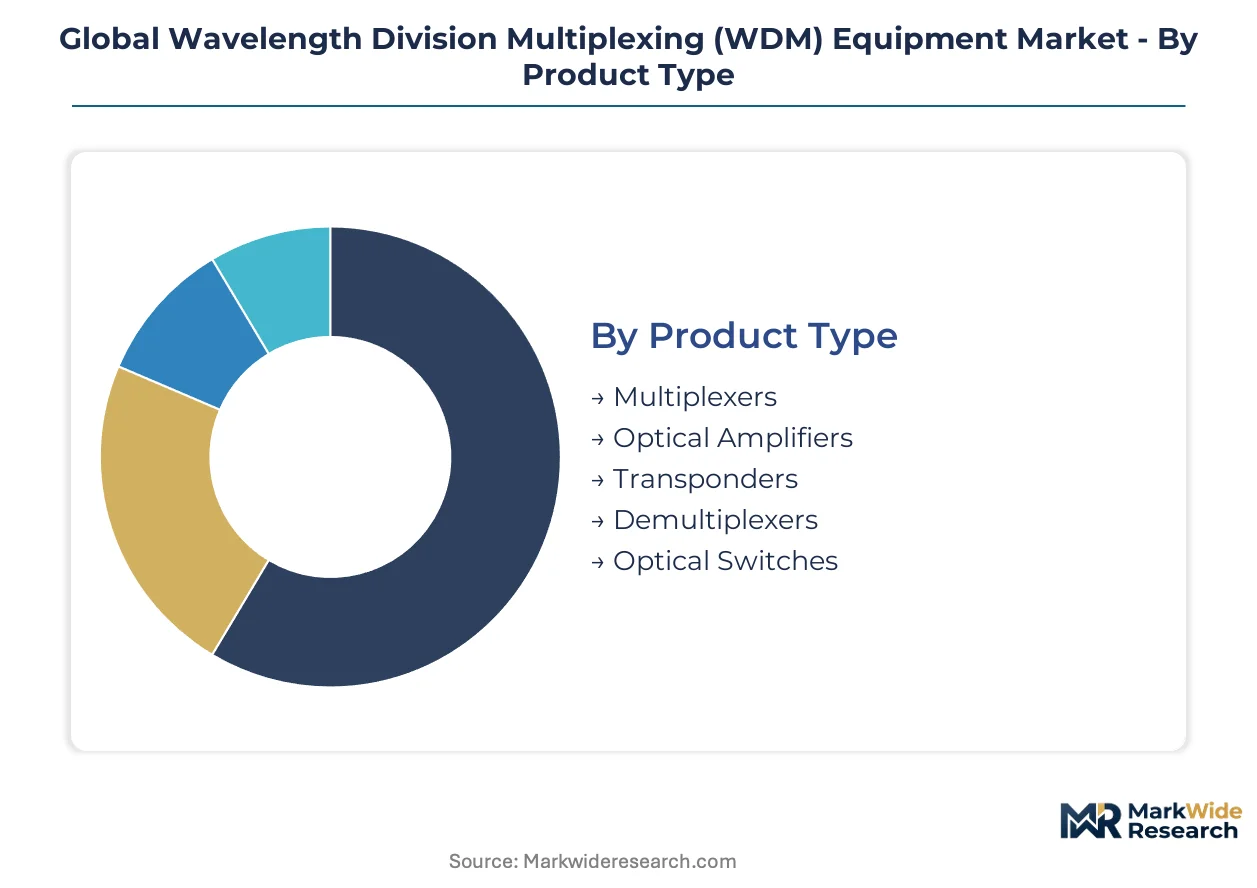
WDM equipment segmentation reveals how optical component specialization drives vendor margin capture. Each dimension—product, technology, application, and end user—exhibits distinct procurement patterns that reshape competitive positioning across fiber infrastructure buildouts.
Product Type:
Supply concentration clusters around coherent signal processing components where foundry capacity constraints create procurement bottlenecks for hyperscale buyers.
- Optical Amplifiers:Erbium-doped fiber amplifiers (EDFAs) and Raman amplifiers boost attenuated signals across C-band and L-band windows. China's state-owned carriers procure these aggressively under MIIT dual carbon mandates that favor all-optical amplification over electronic regeneration.
- Transponders:Coherent transponders integrate DSP, modulator, and receiver functions for wavelength conversion. Cloud service providers in the United States and Germany now mandate programmable modems supporting 400G/800G line rates with software-defined modulation formats.
- Multiplexers:Arrayed waveguide grating devices combine multiple wavelengths onto single fiber cores.
- Demultiplexers:Optical filters separate composite signals into constituent wavelengths at receiver terminals.
- Optical Switches:Micro-electro-mechanical systems (MEMS) and liquid crystal switches enable dynamic wavelength routing.
Today's leader: Transponders. Tomorrow's challenger: Optical Amplifiers.
Technology:
Cost tier stratification separates high-volume metro deployments from premium long-haul systems demanding maximum spectral efficiency.
- Dense WDM:DWDM systems pack 96 to 128 channels per fiber at 75-100 GHz spacing, enabling petabit-class transmission. Submarine cable consortia across transatlantic routes specify these systems for 10-year terminal refresh cycles.
- Reconfigurable Optical Add-Drop Multiplexer:ROADM nodes enable remote wavelength provisioning without manual fiber patching. European incumbent carriers in Germany, France, and Italy prioritize these for CSRD-mandated power-proportional network operations.
- Coarse WDM:CWDM offers lower channel density at reduced cost for access network applications.
- Optical Transport Network:OTN framing provides standardized multiplexing and forward error correction.
- Optical Time Division Multiplexing:OTDM interleaves optical pulses for ultra-high-speed serial transmission.
Volume concentrates in Dense WDM. Margin expansion favors Reconfigurable Optical Add-Drop Multiplexer.
Application:
Customer type differentiation separates latency-sensitive hyperscale interconnect from bandwidth-optimized backbone transmission.
- Data Center Interconnect:DCI links between hyperscale facilities demand sub-millisecond latency and rapid capacity scaling. Cloud service providers in the United States, China, and Germany drive procurement of compact modular systems for campus and metro-scale deployments.
- Long-Haul Transmission:Terrestrial and submarine backbone systems prioritize spectral efficiency over absolute latency. Transatlantic and transpacific cable upgrades anchor volume demand for programmable coherent terminals.
- Metro Networks:Urban aggregation rings require flexible wavelength provisioning for 5G fronthaul and enterprise VPN services.
- Access Networks:Fiber-to-the-home infrastructure uses simplified WDM for residential broadband delivery.
- Enterprise Connectivity:Private wavelength services support financial and healthcare verticals with dedicated optical paths.
Data Center Interconnect commands premium pricing. Long-Haul Transmission anchors volume scale.
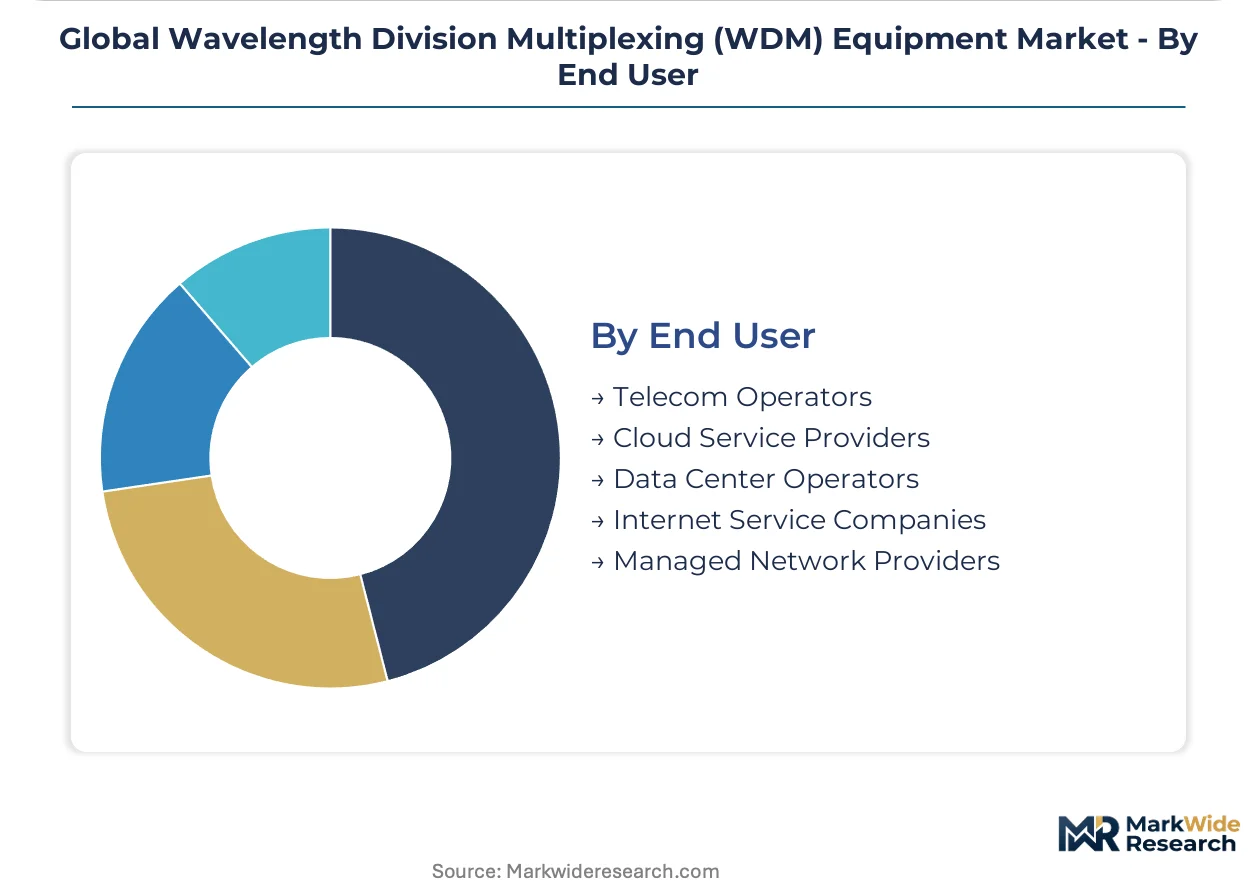
End User:
Procurement authority concentrates among consolidated buying desks that extract volume commitments in exchange for roadmap influence.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud collectively dictate 400G port specifications and multi-year supply agreements. These buyers bypass traditional system vendors to establish direct foundry relationships for silicon photonics components.
- Telecom Operators:Verizon, Deutsche Telekom, and China Mobile manage national backbone and access infrastructure with regulated procurement cycles. State-owned carriers in China face MIIT energy intensity targets that accelerate ROADM and all-optical switching deployment.
- Data Center Operators:Colocation providers procure WDM for inter-facility connectivity and cross-connect services.
- Internet Service Companies:Content delivery networks optimize wavelength utilization for video and software distribution.
- Managed Network Providers:Outsourced optical layer services address enterprise demand without capital-intensive infrastructure ownership.
Cloud Service Providers dominate technology roadmaps. Telecom Operators sustain replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys more DWDM line cards annually than Germany's entire installed base, yet both markets now prioritize energy-efficient coherent transmission under divergent regulatory frameworks. National procurement patterns diverge sharply between state-directed infrastructure programs and hyperscale-driven commercial specifications.
United States
Hyperscale data center operators in Northern Virginia, Dallas-Fort Worth, and Phoenix drive 400G port demand for AI training cluster interconnect. FCC equipment authorization backlogs delay terrestrial C-band expansion deployments. Cloud service providers in the Pacific Northwest negotiate direct silicon photonics foundry contracts bypassing traditional system vendors.
China
State-owned carriers accelerate ROADM deployment under MIIT dual carbon mandates favoring all-optical switching. Yangtze River Delta data center clusters demand 800G coherent terminals for east-west traffic between Shanghai, Hangzhou, and Suzhou facilities. GB standards enforcement restricts foreign equipment participation in core network tenders.
Germany
Deutsche Telekom and regional carriers prioritize programmable coherent modems for CSRD-mandated power-proportional operations. Frankfurt's internet exchange hub anchors dense wavelength infrastructure for European data center interconnect. Bavaria's industrial automation corridors require sub-millisecond latency wavelength services.
India
BharatNet phase three targets optical transport to 600,000 villages under modified Preferential Market Access rules favoring domestic vendors. Tamil Nadu and Karnataka data center clusters emerge as hyperscale landing points requiring metro WDM rings. TRAI spectrum allocation frameworks govern fiber backbone expansion timelines.
Japan
NTT and KDDI submarine cable consortia anchor trans-Pacific terminal refresh cycles with 800G programmable modems. Tokyo-Osaka corridor demands hitless bandwidth adjustment for financial services wavelength customers. METI standardization through ITU-T working groups shapes next-generation coherent DSP specifications.
Global Wavelength Division Multiplexing (WDM) Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coherent signal processing and optical transport layers. Market structure consolidates around three tiers: vertically integrated system vendors with captive DSP supply, optical component specialists supplying merchant modulators and amplifiers, and emerging silicon photonics players enabling direct hyperscaler-foundry relationships. Dominant competitive moves include captive semiconductor capacity allocation and multi-year volume commitments exchanged for roadmap influence.
Among Asia-Pacific headquartered conglomerates, Huawei Technologies Co. Ltd. and ZTE Corporation exemplify state-linked system vendors with integrated domestic supply chains. Cisco Systems Inc. represents North American diversified technology players pursuing routing-to-optical convergence strategies. Ciena Corporation occupies a specialist position in programmable coherent modem technology for submarine and long-haul applications. These three archetypes anchor distinct procurement channels: state-directed carrier tenders, hyperscale commercial negotiations, and consortium-governed cable system upgrades.
| Leading Market Players |
|---|
| ZTE Corporation |
| Lumentum Holdings Inc. |
| Huawei Technologies Co. Ltd. |
| NEC Corporation |
| Fujitsu Limited |
| Cisco Systems Inc. |
| Infinera Corporation |
| Sumitomo Electric Industries Ltd. |
| Ciena Corporation |
| Others |
Supply & Pricing Matrix
Analog mixed-signal engineering talent concentration in Taiwan and Silicon Valley generates labor-cost differentials that widen pricing-tier spreads between premium coherent DSP modules and standard optical amplifiers. Equipment vendors with captive foundry relationships capture margin premiums while merchant suppliers face cost compression from silicon photonics integration.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard WDM components as domestic vendors scale production. Three-tier pricing structure across premium programmable modems, standard fixed-configuration transponders, and economy passive multiplexers dominates procurement. Price differentiation hinges on coherent DSP complexity and MIIT GB certification tier. Cost compression in economy tiers is intensifying because silicon photonics enables direct hyperscaler-foundry relationships. Cloud service providers exhibit lowest price sensitivity; regional telecom operators in India show highest.
Supply Chain Analysis
Modified Preferential Market Access rules in India and domestic content mandates in China's core network tenders are reshaping sourcing patterns toward local assembly partners. Manufacturing concentrates in China, Taiwan, and the United States for coherent DSP fabrication. Raw material dependencies include indium phosphide wafers, erbium-doped fiber, and advanced packaging substrates. Single-source vulnerability rests on Taiwan Semiconductor Manufacturing and GlobalFoundries for photonic integration runs. Distribution runs through direct hyperscale procurement desks and state-owned carrier tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics integration functions as a structural margin-expansion driver, collapsing cost-per-bit trajectories while enabling premium pricing for programmable coherent modulation.
For Market Incumbents: Hedge against pluggable module substitution by securing captive DSP supply arrangements with named foundries. Accelerate ROADM portfolio expansion to capture MIIT dual carbon mandate-driven replacement cycles in China. Defensive consolidation around vertically integrated optical portfolios counters emerging silicon photonics specialists. For New Entrants and Emerging Players: Tier-2 data center operators in India's Tamil Nadu and Karnataka clusters represent an underserved buyer archetype with limited incumbent penetration. White-space targets include compact modular WDM systems for 5G fronthaul aggregation and L-band amplification upgrades for metro capacity doubling. Go-to-market through domestic system integrators under BharatNet phase three procurement rules offers fastest traction. For Investors and Strategic Acquirers: Cloud service provider infrastructure arms are the most active acquirer in this space, seeking coherent DSP capabilities and silicon photonics design teams. Long-term viability favors vendors with demonstrated programmable modem roadmaps and foundry capacity allocation agreements. Acquisition target archetype: pure-play coherent subsystem specialists with 800G+ development pipelines. Watch for inflection when 1.6 Tbps per wavelength samples reach carrier qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Captive DSP Foundry Arrangement | Secures Taiwan Semiconductor Manufacturing capacity allocation against hyperscaler competition. |
| Silicon Photonics Platform Launch | Enables direct cloud service provider relationships bypassing traditional system vendor channels. |
| ROADM Portfolio Expansion | Captures China Mobile and China Telecom procurement under MIIT energy intensity targets. |
| Submarine Cable Consortium Partnership | Positions programmable modems for transatlantic terminal refresh cycles with Ciena and NEC. |
| Edge Computing Interconnect Development | Addresses 5G fronthaul wavelength aggregation for Deutsche Telekom and Verizon metro rings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged optical network architects at hyperscale data center operators, procurement directors at state-owned carriers, coherent DSP engineering leads at semiconductor foundries, submarine cable consortium technical managers, and regulatory affairs specialists at equipment vendors. Secondary validation drew from FCC equipment authorization databases, MIIT GB standard filings, ITU-T recommendation drafts, ETSI technical specifications, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment models and top-down infrastructure investment forecasts were cross-triangulated.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application use case, end-user category, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting against installed base replacement cycles. Forecast inputs incorporated coherent DSP baud-rate roadmaps, foundry capacity allocation announcements, and national broadband mission procurement timelines.
Underlying measurement precision varies by segment; data center interconnect and cloud service provider categories carry tighter precision than enterprise connectivity and managed network services. Forecasts reflect documented assumptions regarding 400G/800G transition timing, silicon photonics yield ramp rates, and carrier energy mandate enforcement intensity. Foundry capacity constraints, FCC authorization backlogs, and geopolitical equipment tender restrictions constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Dome Market
Optical Components
Global Tunable Filter Market
Optical Components
Spatial Light Modulator Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
ROADM WSS Component Market
Optical Components
Portable Lenses Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
Europe Scintillator Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Transceiver Market
Optical Components
North America Tunable Laser Market
Optical Components
Photointerrupter Market