
 Optical Interconnect Market | 2026-2036
Optical Interconnect Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Interconnect Market Intelligence
The EU F-Gas Regulation is recalibrating thermal management requirements for data center interconnect hardware, pushing suppliers toward silicon photonics and lower-energy optical engines. Coherent Corp. leverages vertical integration across laser chip fabrication and module assembly to sustain cost leadership in 800G transceivers. Lumentum Operations LLC anchors its position through dominance in high-speed VCSEL arrays for short-reach data center links. NVIDIA Corporation differentiates by embedding optical I/O directly into AI accelerator architectures, reducing electrical signaling bottlenecks in large-scale GPU clusters.
Optical interconnect denotes high-speed data transmission systems that convert electrical signals into light pulses for propagation through fiber optic cables, waveguides, or free-space channels, typically operating at wavelengths near 1310 nm or 1550 nm with modulation rates exceeding 100 Gbps per lane. These systems serve the primary commercial purpose of eliminating bandwidth-distance limitations inherent in copper interconnects within data centers, telecommunications switches, and high-performance computing environments. Silicon photonics dominates module cost curves as CMOS-compatible foundry processes drive photonic integrated circuit yields upward. Fiber optic formats capture the largest volume share across active optical cables and transceivers, though free space optics is expanding fastest in satellite-to-ground and chip-to-chip applications where physical connectors impose unacceptable latency penalties.
The U.S. FCC governs spectrum allocation for free-space optical links, while the EPA enforces energy efficiency standards affecting data center power usage effectiveness and interconnect thermal loads. Japan's METI promotes domestic photonics manufacturing through JIS standards alignment and national semiconductor revitalization programs. Stakeholders must monitor evolving interoperability standards from the IEEE 802.3 working group and the OIF, as these specifications determine product roadmaps and competitive viability across next-generation 1.6T and 3.2T optical links.
Market Dynamics
Hyperscale data center operators are forcing a generational upgrade cycle in optical interconnect architectures as AI training clusters exhaust electrical I/O bandwidth at 100-meter distances. This demand compression is restructuring supplier relationships around photonic integration capabilities rather than discrete component sourcing.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based cooling systems is mandating lower-thermal-load optical engines, accelerating silicon photonics adoption in Frankfurt and Amsterdam data center clusters.
- AI accelerator architectures:GPU-to-GPU communication in large language model training is consuming 30-40% of cluster power in electrical signaling, creating immediate substitution demand for co-packaged optical I/O.
- Coherent DSP integration:800G ZR pluggable modules are collapsing the cost curve for metro data center interconnects, enabling router bypass architectures that bypass traditional transponder shelves.
Market Restraints
- Indium phosphide supply concentration:High-performance laser chips depend on III-V epitaxy capacity concentrated in Japanese and US foundries, creating 18-24 month qualification queues for new suppliers.
- Packaging yield fragility:Co-packaging photonics with CMOS logic at 2.5D/3D integration densities exhibits yield loss rates 3-5x higher than pure electrical packaging, inflating effective cost per gigabit.
- Copper passive DAC persistence:Short-reach links under 3 meters in spine-leaf architectures retain cost advantages below 400G, delaying optical penetration in top-of-rack switching layers.
Strategic Opportunities
- India data center buildout:The country's PLI scheme for semiconductor and photonics manufacturing is attracting module assembly investments to serve domestic cloud infrastructure expansion.
- Free-space optical satellite links:Low-earth orbit constellation operators are deploying laser terminals for inter-satellite backhaul, bypassing radio frequency spectrum congestion in space-to-ground applications.
- Co-packaged optics standardization:The OIF's 3.2T electrical-to-optical interface specifications are creating a vendor-neutral ecosystem for AI accelerator optical attachment, lowering switching costs for buyers.
Industry Challenges
- Photonics-IC design talent scarcity:The intersection of CMOS process engineering and waveguide physics requires specialists trained in foundry-specific PDKs, with fewer than 200 qualified designers globally.
- Legacy switch port compatibility:400G-to-800G migration cycles require backward-compatible form factors (QSFP-DD, OSFP) that constrain thermal and electrical design freedom, complicating mechanical integration.
- IEEE 802.3ck compliance timelines:112G electrical lane validation for 800G modules extends certification cycles to 14-18 months, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Interconnect Market |
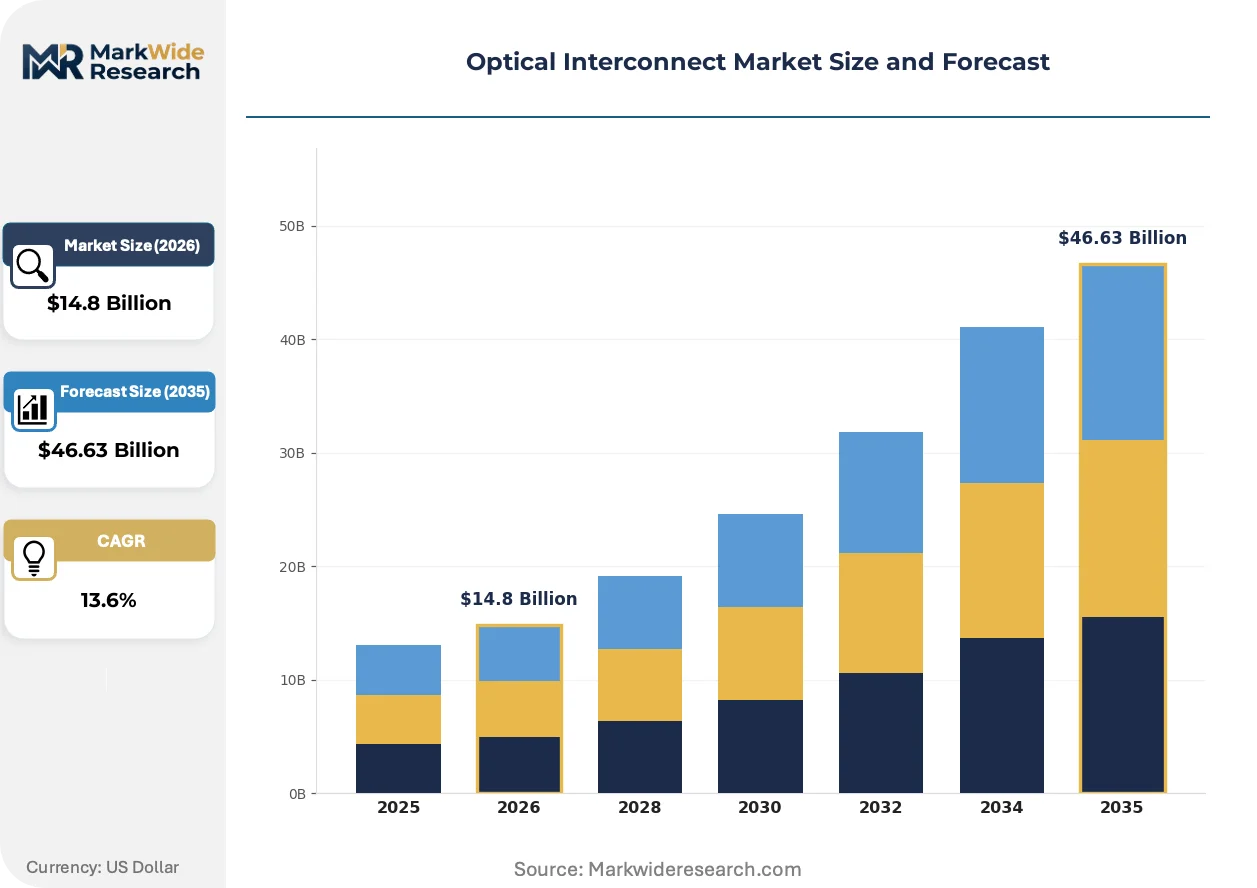
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Silicon Photonics, Optical Coherence Tomography, Free Space Optics, Fiber Optic Application: Data Center, Telecommunication, Aerospace, Military End User: Telecom Operators, Cloud Service Providers, Enterprises, Research Institutions Format: Active Optical Cable, Optical Transceivers, Connectors, Splitters |
| Companies Covered | Coherent Corp., InnoLight Technology (Suzhou) Ltd., Lumentum Operations LLC, Molex LLC, TE Connectivity, Broadcom Inc., Sumitomo Electric Industries, Ltd., Fujitsu Ltd., NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Interconnect Market Strategic Shifts & Innovations
Silicon photonics process maturity is collapsing the traditional boundary between semiconductor and optical component supply chains, enabling foundry-scale manufacturing economics in transceiver production.
Monolithic integration of lasers, modulators, and photodetectors on silicon substrates is unifying previously discrete packaging steps into single-die flows. Hyperscale operators in the United States are qualifying these devices for 800G DR8 applications at volumes exceeding 1 million units annually. This unification is compressing module BOM costs by eliminating wirebond assemblies and hermetic packages.
The EU F-Gas Regulation is forcing thermal design recalibration across optical interconnect hardware categories. Module suppliers must now demonstrate power dissipation below 15W per 800G port to qualify for green data center certifications in Germany and France. Datacenter operators are responding by specifying liquid-cooled optical line cards that accommodate higher-density silicon photonics engines.
Hyperscale procurement patterns are consolidating supplier relationships around vertically integrated photonics capabilities. Cloud infrastructure buyers are reducing qualified vendor lists from 12-15 to 4-6 per product category, favoring partners with captive laser fabrication. This concentration is most visible in the United States, where Microsoft, Amazon, and Google account for over 60% of 800G transceiver demand and negotiate multi-year supply agreements with volume commitments.
Optical Interconnect Market Segmentation
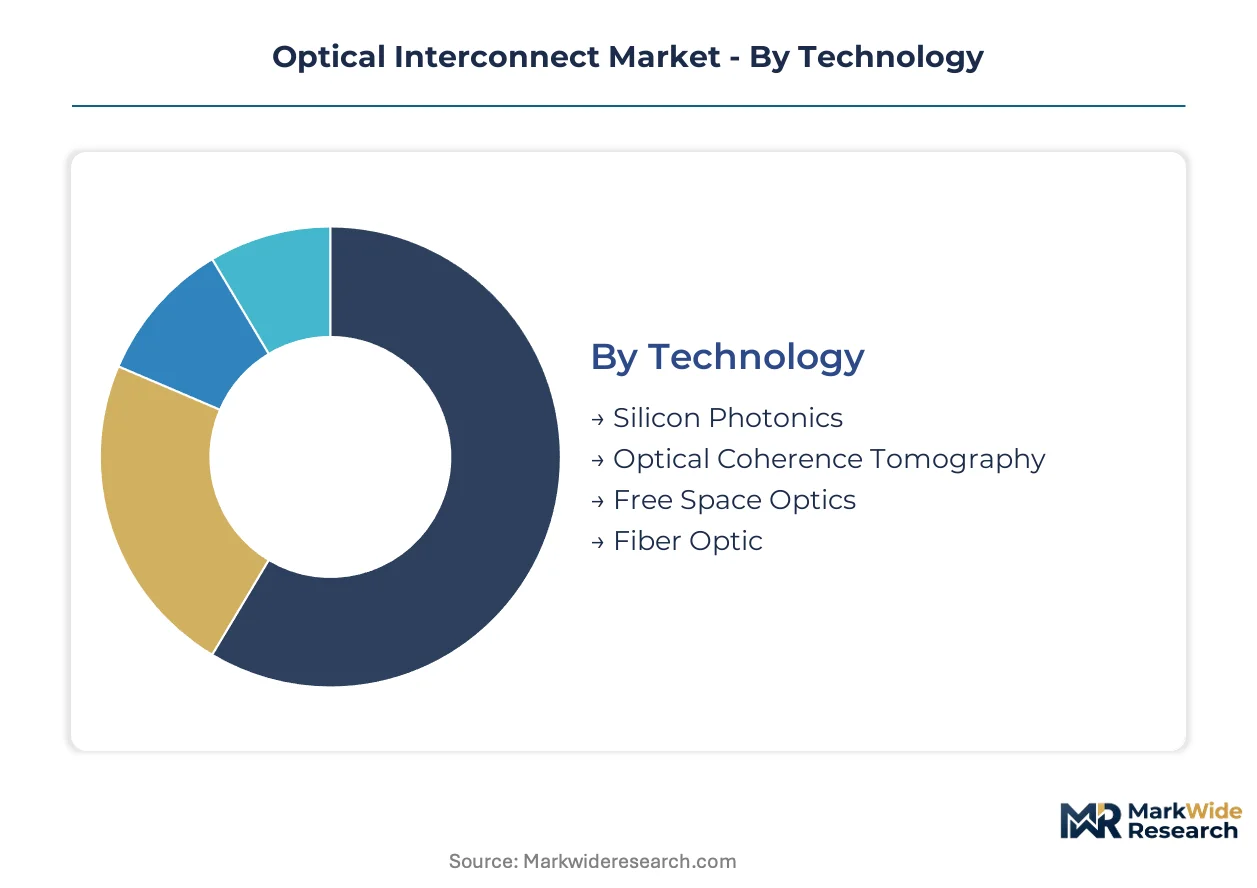
Optical interconnect architectures fragment across integration depths, from standalone pluggable modules to co-packaged photonic engines embedded within AI accelerators. Understanding these segment boundaries clarifies where silicon photonics displaces legacy discrete packaging and which procurement patterns dominate capital deployment cycles.
Technology:
Integration depth separates standalone transceiver solutions from embedded photonic subsystems, with silicon photonics collapsing this boundary through monolithic manufacturing approaches.
- Silicon Photonics:Lasers, modulators, and photodetectors fabricated on CMOS-compatible substrates enable foundry-scale production economics. Hyperscale data centers in the United States are qualifying these devices for 800G applications at volumes exceeding one million units annually, driven by thermal load constraints under Germany's green certification requirements.
- Fiber Optic:Conventional discrete component assemblies using III-V laser chips and separate modulator packages retain dominance in legacy telecom infrastructure. Japanese foundries concentrate epitaxy capacity for these devices, creating qualification queues that extend supplier lead times.
- Free Space Optics:Laser terminals bypass physical interconnects in satellite-to-ground and chip-to-chip applications where connector latency proves unacceptable.
- Optical Coherence Tomography:Interferometric detection schemes enable high-resolution biomedical imaging with specialized photonic integration requirements.
Volume placements concentrate in Fiber Optic; the faster expansion belongs to Silicon Photonics.
Application:
Power density thresholds and bandwidth-distance requirements determine whether electrical or optical signaling prevails across deployment environments.
- Data Center:AI training clusters exhaust electrical I/O bandwidth at 100-meter distances, forcing generational upgrades to 800G and 1.6T optical links. Cloud operators in Virginia and Oregon account for the majority of transceiver procurement volume.
- Telecommunication:Metro and long-haul networks deploy coherent pluggable modules for router bypass architectures. 800G ZR standards are collapsing traditional transponder shelf economics.
- Aerospace:Satellite constellations deploy laser terminals for inter-satellite backhaul, bypassing radio frequency spectrum congestion.
- Military:Secure free-space links and ruggedized fiber assemblies serve electronic warfare and command infrastructure with hardened thermal specifications.
Revenue concentration sits with Data Center; Telecommunication shows the steepest replacement cycle acceleration.
End User:
Procurement scale and technical specification authority fragment across buyer types with diverging integration strategies.
- Cloud Service Providers:Microsoft, Amazon, and Google negotiate multi-year supply agreements with volume commitments, consolidating qualified vendor lists from 12-15 to 4-6 per category. These buyers specify liquid-cooled optical line cards to accommodate higher-density silicon photonics engines.
- Telecom Operators:Incumbent carriers prioritize backward-compatible form factors and extended temperature specifications for outdoor plant deployment.
- Enterprises:Private data center operators follow hyperscale technology roadmaps with 18-24 month lag cycles, adopting proven 400G and 800G standards.
- Research Institutions:National laboratories and university consortia pilot co-packaged optics and 3.2T electrical-to-optical interfaces ahead of commercial qualification.
Capital deployment concentrates with Cloud Service Providers; Research Institutions drive the earliest technology validation.
Format:
Physical integration choices determine thermal dissipation limits and port density achievable within rack space constraints.
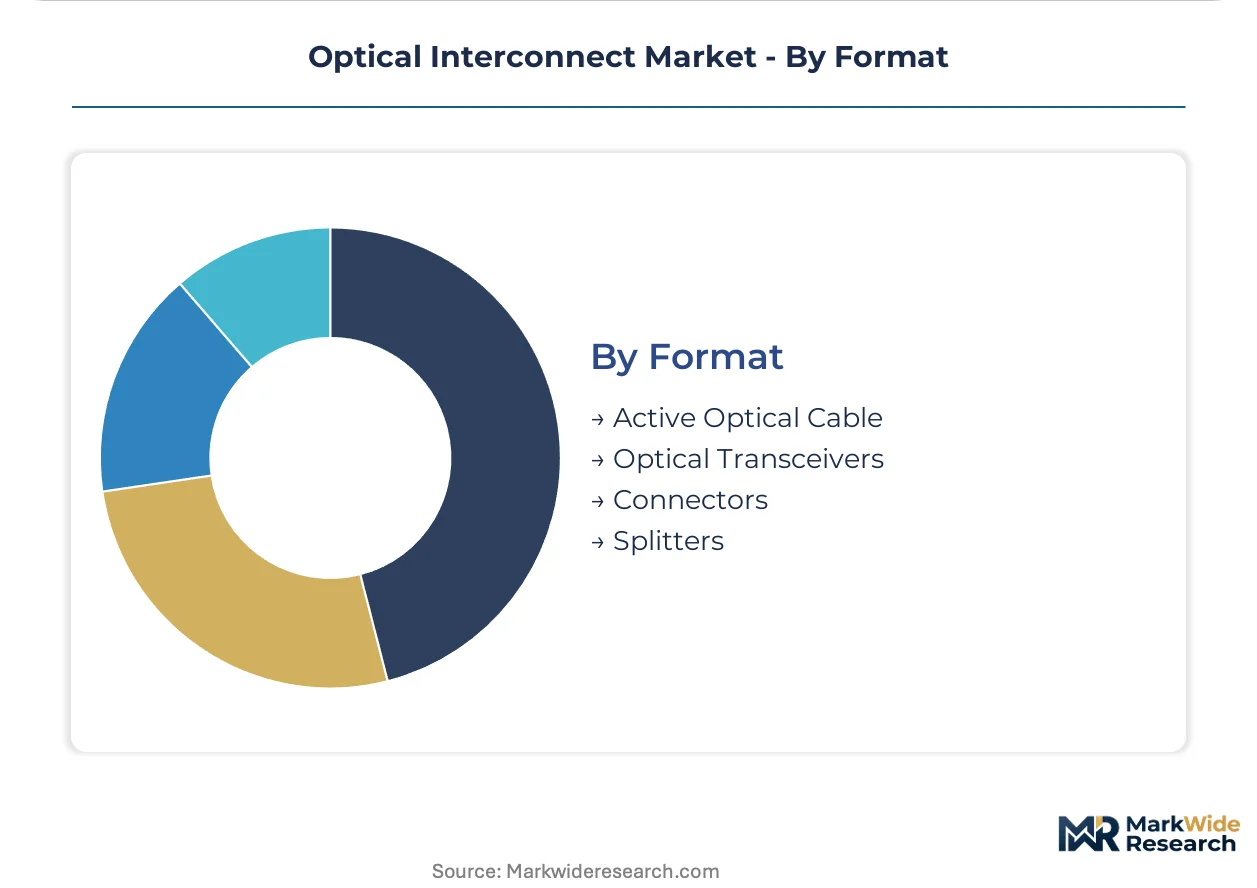
- Optical Transceivers:Pluggable modules in QSFP-DD and OSFP form factors dominate 400G-to-800G migration cycles. Backward compatibility requirements constrain mechanical design freedom and extend IEEE 802.3ck certification timelines to 14-18 months.
- Active Optical Cable:Integrated cable assemblies eliminate separate transceiver procurement for short-reach links under 10 meters in spine-leaf architectures.
- Connectors:MPO and duplex fiber connectors enable field-terminated installations in multi-tenant data center buildouts.
- Splitters:Passive optical power division supports point-to-multipoint architectures in fiber-to-the-home and enterprise access networks.
Shipment volumes concentrate in Optical Transceivers; Active Optical Cable demonstrates the most rapid penetration rate in top-of-rack switching layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Japanese and US foundries for III-V epitaxy capacity, while consumption tilts toward hyperscale data center clusters in the United States, Germany, and India where AI infrastructure buildouts absorb transceiver volumes.
United States
Cloud operators in Virginia and Oregon account for over 60% of 800G transceiver procurement volume, negotiating multi-year supply agreements with volume commitments. The FCC governs spectrum allocation for free-space optical links while the EPA enforces energy efficiency standards affecting data center power usage effectiveness. Microsoft, Amazon, and Google are consolidating qualified vendor lists from 12-15 to 4-6 per category, favoring partners with captive laser fabrication.
Germany
Frankfurt and Amsterdam data center clusters are mandating lower-thermal-load optical engines under the EU F-Gas Regulation phasedown of hydrofluorocarbon-based cooling systems. Module suppliers must demonstrate power dissipation below 15W per 800G port to qualify for green data center certifications. Datacenter operators in Frankfurt are specifying liquid-cooled optical line cards that accommodate higher-density silicon photonics engines.
Japan
METI promotes domestic photonics manufacturing through JIS standards alignment and national semiconductor revitalization programs. High-performance laser chips depend on III-V epitaxy capacity concentrated in Japanese foundries, creating 18-24 month qualification queues for new suppliers. Tokyo and Osaka industrial corridors anchor epitaxy capacity for telecom infrastructure components.
India
The country's PLI scheme for semiconductor and photonics manufacturing is attracting module assembly investments to serve domestic cloud infrastructure expansion. Cloud operators follow hyperscale technology roadmaps with 18-24 month lag cycles, adopting proven 400G and 800G standards. Mumbai and Bengaluru clusters are emerging as assembly hubs for regional data center buildouts.
China
MIIT governs domestic optical component manufacturing through GB standards alignment with dual carbon goals driving energy efficiency requirements. Yangtze River Delta foundries are expanding CMOS-compatible photonic integrated circuit capacity to serve domestic hyperscale demand. Shanghai and Suzhou industrial zones concentrate module assembly for both export and domestic cloud infrastructure.
Optical Interconnect Market Key Industry Players
The competitive structure tilts toward vertically integrated photonics specialists with captive laser fabrication capabilities. Hyperscale procurement patterns are consolidating supplier relationships around partners controlling epitaxy through module assembly. Three archetypes dominate: III-V epitaxy houses with module assembly arms, CMOS foundry-aligned silicon photonics players, and AI accelerator architects embedding optical I/O. Dominant competitive moves include capacity expansion in Japanese and US epitaxy foundries and strategic partnerships between cloud operators and module suppliers for multi-year volume commitments.
Among US-based optical component houses, Coherent Corp. and Lumentum Operations LLC occupy positions at the integrated-component end of the spectrum, while NVIDIA Corporation exemplifies the embedded-optics archetype within AI accelerator architectures. These three names represent the dominant competitive vectors: discrete module supply with upstream laser control, high-speed VCSEL specialization for short-reach links, and co-packaged optical I/O integration directly into compute silicon. The concentration of demand among four to six qualified vendors per category reinforces positioning for those with backward integration into laser chip fabrication.
| Leading Market Players |
|---|
| Coherent Corp. |
| InnoLight Technology (Suzhou) Ltd. |
| Lumentum Operations LLC |
| Molex LLC |
| TE Connectivity |
| Broadcom Inc. |
| Sumitomo Electric Industries, Ltd. |
| Fujitsu Ltd. |
| NVIDIA Corporation |
| Others |
Cost & Logistics Intelligence
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating sub-15W power dissipation per 800G port for green data center certifications in Germany and France. Hyperscale operators in Virginia and Oregon now require liquid-cooled optical line cards as a baseline qualification, compressing margins for module suppliers lacking silicon photonics integration.
Pricing Analysis
Throughput-per-watt metrics anchor value-based pricing for 800G and 1.6T optical interconnect modules. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled silicon photonics engines from air-cooled discrete assemblies and legacy fiber optic transceivers. Price differentiation hinges on thermal certification grade and captive laser fabrication. Cost compression in standard-tier modules is intensifying because hyperscale buyers are consolidating qualified vendor lists from 12-15 to 4-6 per category. Cloud service providers exhibit lowest price sensitivity due to power budget constraints, while enterprise data center operators lag hyperscale roadmaps by 18-24 months and demand proven 400G standards at economy pricing.
Supply Chain Analysis
Refurbishment flows for failed 800G modules are creating secondary supply channels as yield loss rates in co-packaged photonics run 3-5x above pure electrical packaging. III-V epitaxy capacity concentrates in Japan and the United States, with Tokyo and Osaka industrial corridors anchoring high-performance laser chip fabrication. Raw material dependencies include indium phosphide wafers, germanium photodetectors, and specialized hermetic ceramic packages. Single-source vulnerability in Japanese foundries creates 18-24 month qualification queues for new suppliers. Distribution runs through direct multi-year supply agreements with hyperscale operators rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play as packaging yield fragility and photonics-IC design talent scarcity force weaker module assemblers without captive laser fabrication into exit or acquisition.
For Market Incumbents: Lock in multi-year volume commitments with Microsoft, Amazon, and Google before 1.6T qualification cycles begin, while adding III-V epitaxy capacity in Japan or the United States to secure laser chip supply. Co-packaged optics standardization by the OIF threatens discrete module suppliers who delay silicon photonics transition. For New Entrants and Emerging Players: Cloud service provider procurement teams represent the most accessible channel partner type for qualifying novel thermal management solutions. Target India's PLI scheme for semiconductor and photonics manufacturing to serve Mumbai and Bengaluru data center buildouts with 400G and 800G module assembly. Position around liquid-cooled optical line cards as hyperscale operators specify these for Frankfurt and Amsterdam clusters. For Investors and Strategic Acquirers: OIF 3.2T electrical-to-optical interface specification publication is the leading indicator that co-packaged optics will displace pluggable modules in AI accelerator architectures. Long-term viability favors vertically integrated photonics specialists with captive laser fabrication spanning epitaxy through module assembly. Monitor IEEE 802.3ck certification timelines extending to 14-18 months as a signal of which suppliers can sustain revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | CMOS-compatible fabrication collapses module BOM costs by eliminating wirebond assemblies. |
| Co-Packaged Optics Partnership | NVIDIA's embedded optical I/O reduces electrical signaling bottlenecks in GPU clusters. |
| III-V Epitaxy Capacity Expansion | Japanese foundry additions shorten 18-24 month qualification queues for new suppliers. |
| Liquid-Cooled Line Card Development | Frankfurt operators specify these to meet EU F-Gas Regulation thermal thresholds. |
| India PLI Scheme Module Assembly | Mumbai and Bengaluru hubs serve domestic cloud infrastructure expansion. |
Research Approach
Independent corroboration across hyperscale data center procurement executives, optical module engineering directors, and III-V foundry operations managers underwrites the qualitative findings in this study. Primary interviews with cloud infrastructure planners, transceiver product managers, and thermal design specialists were validated against secondary sources including SEC 10-K filings, hyperscaler capex disclosures, and IEEE 802.3 working group specifications. Bottom-up unit economics for 800G and 1.6T modules were triangulated against top-down addressable market sizing across data center, telecommunication, and aerospace applications.
Comparable-period anchoring to historical 400G-to-800G migration cycles informed the projection horizon for 1.6T and 3.2T adoption curves. The analytical framework segments by integration depth, application environment, end-user procurement authority, and physical format across the modeling period. CAGRs were derived from shipment volume trajectories and average selling price erosion patterns in silicon photonics versus discrete fiber optic assemblies. Forecast inputs include hyperscale capital expenditure plans, OIF standardization timelines, and EU F-Gas Regulation compliance deadlines.
Caveats apply where III-V epitaxy capacity constraints, packaging yield fragility in co-packaged photonics, or IEEE 802.3ck certification delays could materially shift the outlook. Practitioners should monitor OIF 3.2T specification finalization and hyperscale vendor list consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Liquid Light Guides Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Silicon Focus Ring Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Optical Sensor Market
Optical Components
Europe Tunable Laser Market
Optical Components
Optical Position Sensors Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Optical Fiber Array Market
Optical Components
Global Adaptive Optics Market
Optical Components
Prism Coupler Market
Optical Components
Ellipsometer Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Integrated Quantum Optical Circuits Market