
 Global Adaptive Optics Market | 2026-2036
Global Adaptive Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Optics Market Foresight
High-resolution wavefront correction tier is rotating toward defense and medical imaging applications where nanometer-scale precision commands premium positioning. Northrop Grumman Corporation dominates military-grade deformable mirror supply for directed energy programs. Thorlabs, Inc. leverages modular Shack-Hartmann architectures to sustain broad research laboratory penetration. Boston Micromachines Corporation specializes in MEMS-based mirror arrays that anchor compact ophthalmology system designs.
Adaptive optics comprises integrated subsystems—deformable mirrors, wavefront sensors, control electronics, and laser guide stars—that measure and compensate optical aberrations in real time using closed-loop feedback at kilohertz refresh rates, primarily to restore diffraction-limited performance in turbulent or biological media. Deformable mirrors capture the largest value share due to manufacturing complexity in actuator density and coating durability. Wavefront sensors represent the fastest-expanding segment as pyramid and laser tomography variants displace legacy Shack-Hartmann configurations in next-generation telescope arrays. Control systems concentrate margin pools where proprietary algorithms and FPGA firmware create vendor lock-in.
FDA 510(k) pathways shape ophthalmology device commercialization timelines in the United States, while EMA MDR conformity and EU AI Act risk classification govern software-driven diagnostic modules in Europe. ISO 10110 optical surface specifications and IEC laser safety standards establish cross-border qualification thresholds for component suppliers. Stakeholders must monitor regulatory divergence between FDA software-as-medical-device guidance and EU AI Act conformity assessment timelines to avoid dual-track compliance costs.
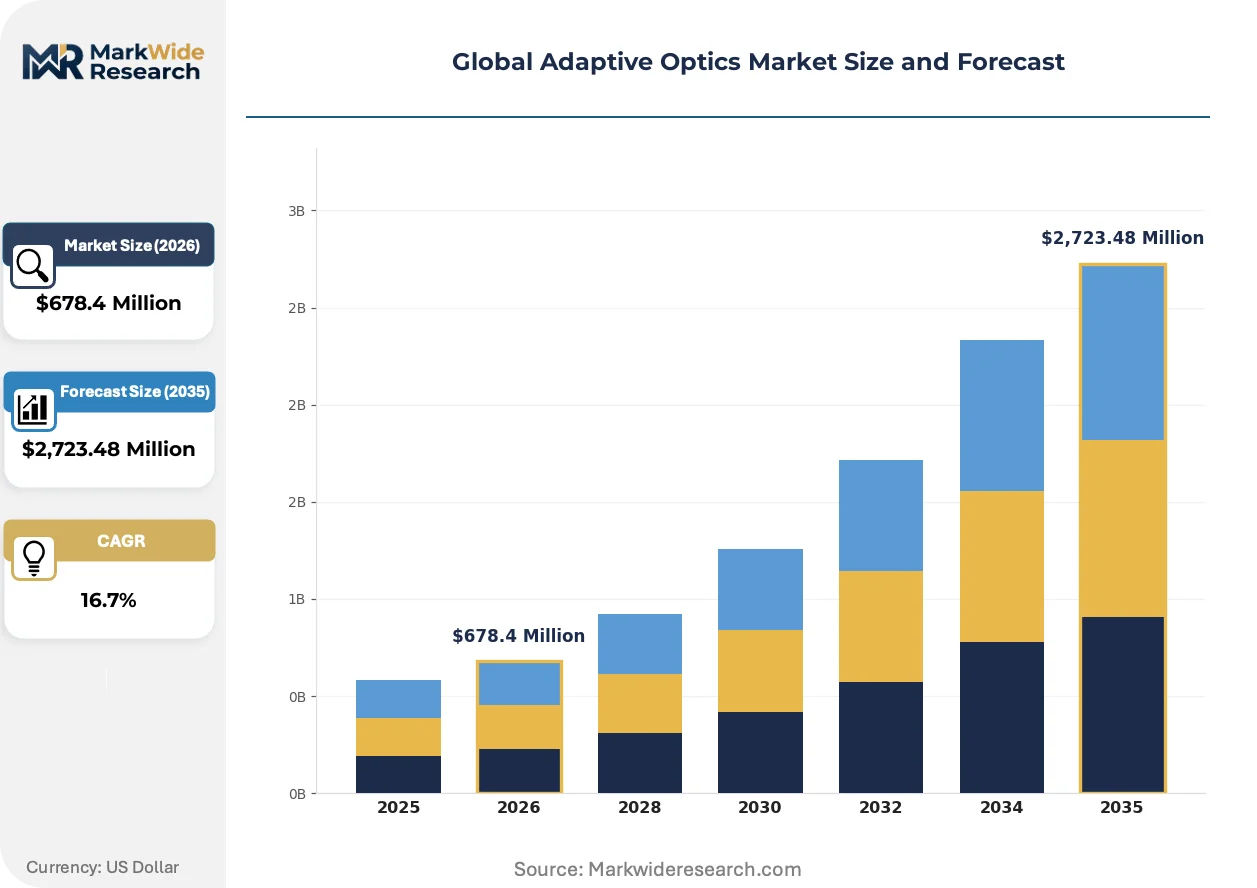
Market Dynamics
Wavefront sensor miniaturization is compressing unit economics across clinical ophthalmology while defense procurement concentrates actuator manufacturing in German and US facilities.
Growth Catalysts
- Directed energy modernization:US military procurement of deformable mirror arrays for laser weapon platforms sustains high-margin production lines at domestic precision optics foundries.
- EMA MDR pathway alignment:European ophthalmology device manufacturers accelerating software-as-medical-device submissions for AI-integrated diagnostic modules.
- MEMS fabrication scale-up:Semiconductor foundry capacity expansion in Taiwan and South Korea lowering per-actuator costs for compact mirror arrays.
Market Restraints
- Actuator coating supply concentration:Dielectric stack deposition equipment and specialty coating chemicals concentrate among German and Japanese suppliers, creating input vulnerability.
- FDA 510(k) timeline variability:Software-driven adaptive optics diagnostic systems face unpredictable review cycles for algorithm-enabled wavefront reconstruction claims.
- Liquid crystal modulator substitution:Programmable spatial light modulators from holographic display supply chains threaten entry-level deformable mirror applications in research settings.
Strategic Opportunities
- India clinical penetration:Underdeveloped corneal topography infrastructure in tier-2 cities creates first-mover positioning for Shack-Hartmann-based screening systems.
- EU AI Act conformity premium:High-risk medical device classification for autonomous diagnostic algorithms creates pricing power for vendors completing notified body assessments early.
- Multi-conjugate telescope integration:Convergence of laser guide star arrays with pyramid wavefront sensors opens architecture contracts for next-generation extremely large telescopes.
Industry Challenges
- Adaptive optics control firmware talent scarcity:Real-time wavefront reconstruction algorithm development requires rare combinations of optical physics and FPGA programming expertise concentrated in academic labs.
- ISO 10110 surface specification certification delays:Substrate qualification for high-actuator-count mirrors extends production timelines by 6-12 months for new supplier entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Optics Market |
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $2,723.48 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deformable Mirrors, Wavefront Sensors, Control Systems, Laser Guide Stars Technology: Shack-Hartmann, Pyramid, Curvature, Laser Tomography, Modal Control Application: Astronomy, Ophthalmology, Microscopy, Defense, Laser Communication End User: Research Laboratories, Medical Centers, Military Agencies, Telecommunications Firms |
| Companies Covered | Northrop Grumman Corporation, Thorlabs, Inc., Iris AO, Inc., Boston Micromachines Corporation, Teledyne Technologies, Inc., Adaptica S.r.l., Imagine Optic SA, ALPAO, Flexible Optical B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Optics Market Shifts & Advancements
Computational wavefront sensing architectures are displacing hardware-heavy approaches while regulatory frameworks for AI-enabled diagnostics crystallize across major jurisdictions.
Pyramid wavefront sensing is decomposing the Shack-Hartmann monopoly in ground-based astronomy. European Southern Observatory procurement specifications now prioritize pyramid architectures for planned extremely large telescope instrumentation. This shift is decomposing the installed base of lenslet array manufacturers and redistributing value toward CMOS detector suppliers and reconstruction algorithm licensors.
EU AI Act risk classification rules are reshaping ophthalmology software commercialization pathways. High-risk designation for autonomous diagnostic modules triggers mandatory notified body involvement and post-market performance monitoring. Device manufacturers with existing MDR quality management systems are adapting faster than software-native entrants lacking physical device regulatory experience.
Hospital procurement committees are consolidating adaptive optics capital equipment decisions under centralized radiology-ophthalmology joint review boards. Traditional distributor relationships with individual department heads are losing influence to value-analysis committees evaluating total cost of ownership across maintenance, training, and interoperability. This pattern concentrates most visibly in US academic medical centers restructuring capital allocation after IRA-mandated drug pricing transparency reforms.
Global Adaptive Optics Market Segmentation
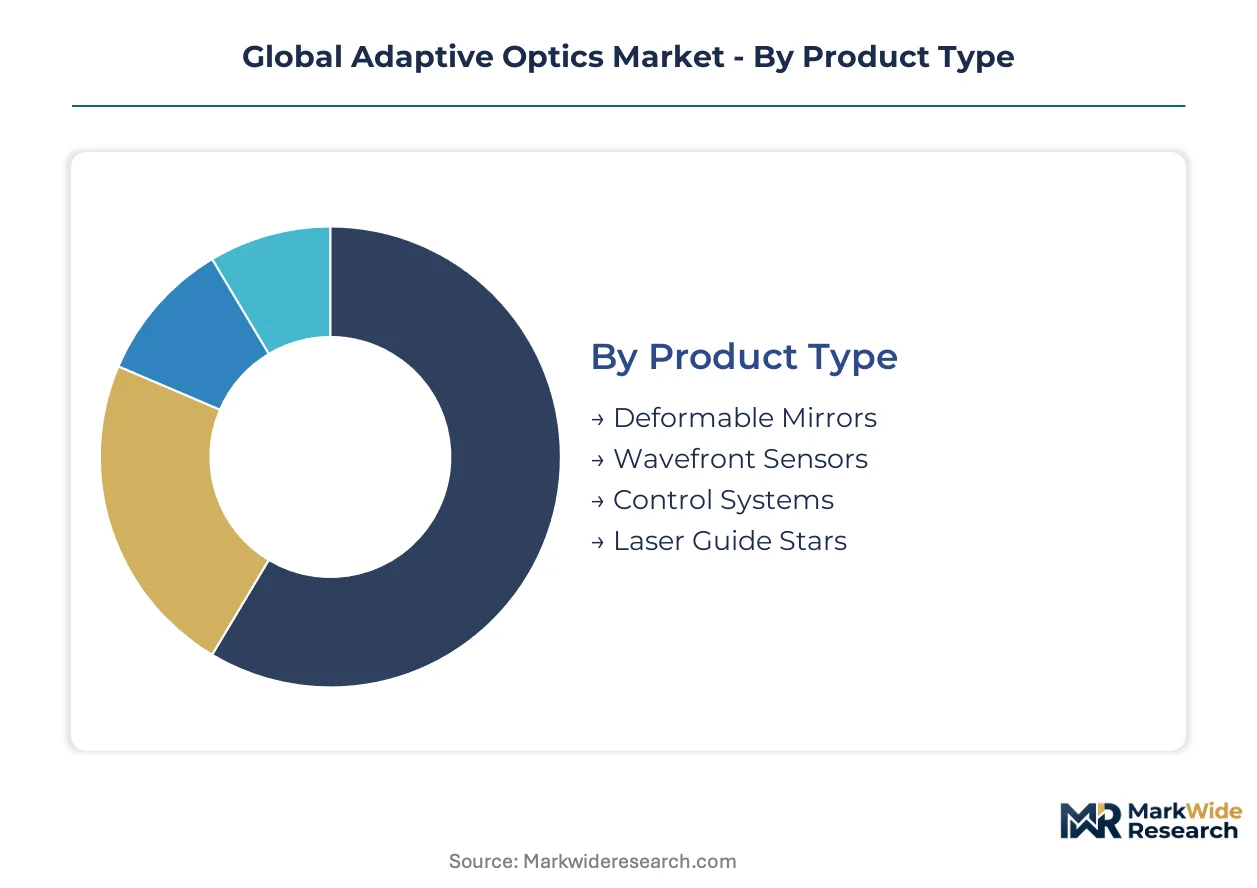
Adaptive optics market segmentation reveals how component value pools, technology maturity curves, and end-user procurement authority reshape competitive positioning across defense, medical, and scientific verticals. Structural differences in regulatory pathways and funding cycles create divergent margin profiles that vendors must navigate through targeted portfolio architecture.
Product Type:
FDA 510(k) clearance timelines and EMA MDR conformity assessments impose distinct commercialization burdens on hardware versus software-centric product categories, fragmenting vendor strategies across jurisdictions.
- Deformable Mirrors:Piezoelectric and electrostatic actuator arrays with dielectric coatings enable nanometer-scale surface deformation at kilohertz refresh rates. Military procurement in the United States and Germany concentrates demand for high-actuator-count configurations in directed energy platforms, where coating durability under thermal loading commands premium qualification protocols.
- Wavefront Sensors:CMOS-detector-based architectures measure optical aberrations through spot displacement or intensity pattern analysis. Shack-Hartmann variants dominate clinical ophthalmology in Germany and France, while pyramid architectures gain traction in European Southern Observatory procurement specifications for ground-based telescope instrumentation.
- Control Systems:FPGA-based real-time processors execute closed-loop wavefront reconstruction algorithms.
- Laser Guide Stars:Sodium-layer excitation modules generate artificial reference beacons for atmospheric tomography.
Deformable mirrors handle the majority of throughput; wavefront sensors are expanding most quickly on share.
Technology:
Cost tier stratification separates mature lenslet-based approaches from emerging computational architectures that displace hardware complexity with algorithmic reconstruction.
- Shack-Hartmann:Microlens array subdivides wavefront into focal spot arrays for slope measurement. Miniaturization trends in Taiwan and South Korean semiconductor foundries compress unit economics for clinical deployments in Indian tier-2 cities.
- Pyramid:Double-refraction prism generates four intensity quadrants encoding wavefront derivatives. European Southern Observatory procurement specifications now prioritize this architecture for planned extremely large telescope instrumentation, redistributing value toward CMOS detector suppliers.
- Curvature:Measures local wavefront curvature through intensity differences at defocused planes.
- Laser Tomography:Multi-layer atmospheric profiling enables multi-conjugate adaptive optics.
- Modal Control:Zernike polynomial decomposition reduces computational load for real-time correction.
Shack-Hartmann maintains installed base dominance; pyramid architectures are gaining share fastest in next-generation telescope contracts.
Application:
End-use concentration patterns reflect how defense procurement cycles, medical device reimbursement pathways, and research infrastructure funding create divergent demand volatility profiles across verticals.
- Astronomy:Ground-based telescope instrumentation requires multi-conjugate architectures with laser guide star arrays. Fraunhofer institutes and Max Planck facilities in Germany anchor European research infrastructure spending, while United States federally funded observatories sustain high-margin custom system procurement.
- Ophthalmology:Corneal topography and retinal imaging systems target FDA 510(k) pathways in the United States and EMA MDR conformity in Europe. EU AI Act high-risk classification for autonomous diagnostic algorithms triggers mandatory notified body involvement, favoring established device manufacturers over software-native entrants.
- Microscopy:Super-resolution imaging in biological specimens drives compact MEMS-based mirror integration.
- Defense:Directed energy weapon platforms and surveillance systems sustain actuator manufacturing in domestic precision optics foundries.
- Laser Communication:Free-space optical links for satellite and terrestrial networks demand atmospheric turbulence compensation.
Astronomy absorbs the largest capital equipment commitments; ophthalmology shows the steepest expansion trajectory as clinical penetration deepens.
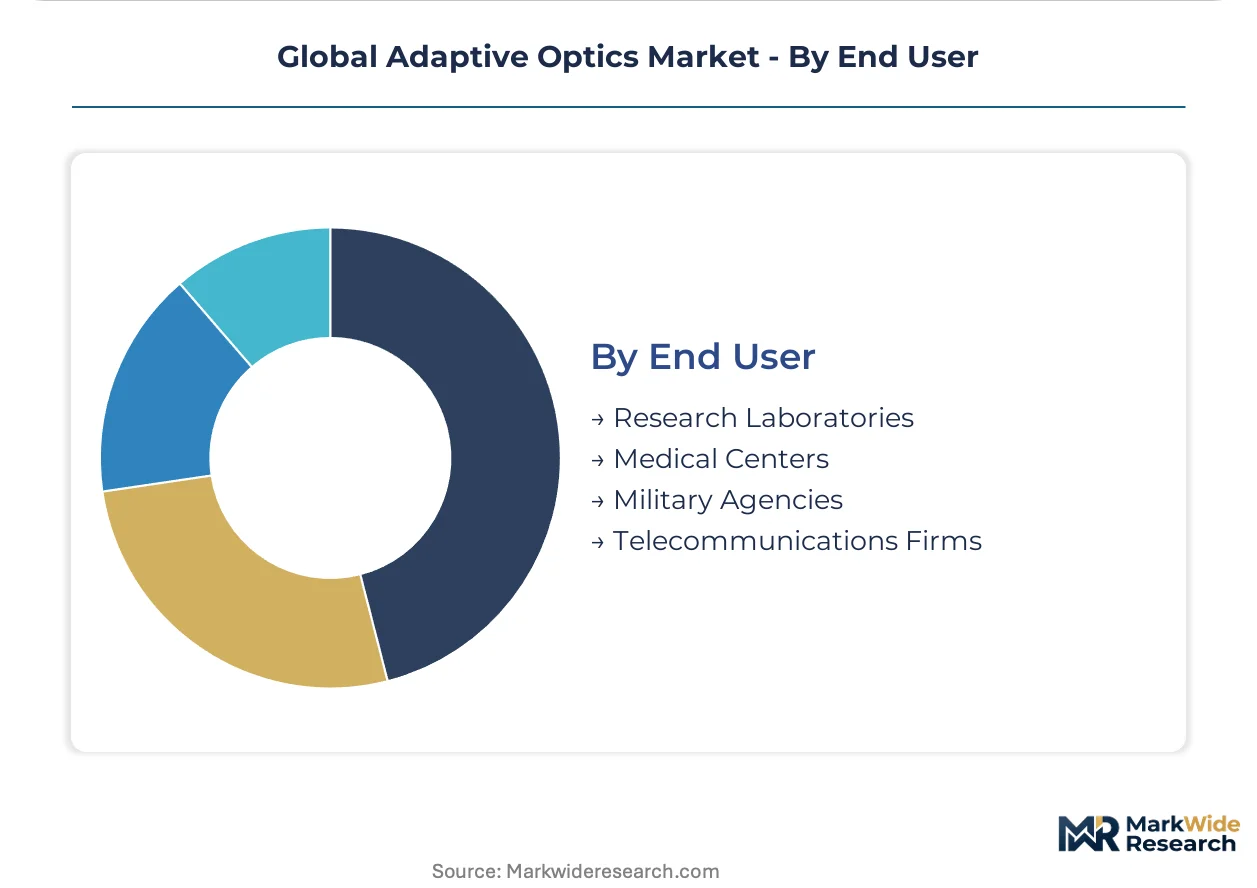
End User:
Customer procurement authority is consolidating under centralized value-analysis committees that evaluate total cost of ownership across maintenance, training, and interoperability rather than departmental distributor relationships.
- Research Laboratories:Academic and government facilities with multi-year capital cycles. United States National Science Foundation and European Research Council grant mechanisms sustain demand for custom-configured systems with extended service contracts.
- Medical Centers:Hospital procurement committees in US academic medical centers are restructuring capital allocation after IRA-mandated pricing transparency reforms, consolidating adaptive optics decisions under joint radiology-ophthalmology review boards.
- Military Agencies:United States Department of Defense and European defense ministries concentrate procurement of wavefront correction systems for directed energy and surveillance platforms.
- Telecommunications Firms:Satellite operators and terrestrial network providers evaluate laser communication terminals with integrated atmospheric compensation.
Research laboratories command the longest procurement cycles; medical centers are shifting fastest toward software-integrated diagnostic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in precision optics components tilt toward surplus economies with deep semiconductor foundry integration and defense procurement scale. Import dependency concentrates in clinical ophthalmology systems where wavefront sensor miniaturization drives finished device trade.
United States
Department of Defense directed energy programs sustain domestic deformable mirror production at precision optics foundries in California and Arizona. FDA 510(k) pathways govern ophthalmology device commercialization timelines, with software-as-medical-device guidance creating compliance complexity for algorithm-enabled diagnostics. Boston anchors MEMS-based mirror array development for compact clinical systems.
Germany
Fraunhofer institutes and Max Planck facilities concentrate European research infrastructure spending on ground-based telescope instrumentation in Munich and Garching. EMA MDR conformity assessments and EU AI Act risk classification govern software-driven diagnostic modules, favoring established device manufacturers. Jena and Oberkochen host precision optics clusters serving both astronomy and medical imaging verticals.
Japan
PMDA regulatory frameworks shape ophthalmology device approval pathways while METI industrial policy supports optical component manufacturing. Dielectric stack deposition equipment and specialty coating chemicals concentrate among domestic suppliers, creating input advantages for actuator production. Yokohama and Osaka house precision optics clusters integrating wavefront sensor fabrication with semiconductor equipment supply chains.
South Korea
Semiconductor foundry capacity expansion in Hsinchu-fed supply chains lowers per-actuator costs for compact mirror arrays deployed in clinical settings. Korean MFDS medical device regulations align with international standards, accelerating market entry for Shack-Hartmann-based screening systems. Seoul Capital Area clusters integrate CMOS detector fabrication with adaptive optics control electronics assembly.
India
Underdeveloped corneal topography infrastructure in tier-2 cities creates positioning opportunities for Shack-Hartmann-based screening systems as CDSCO streamlines medical device registration pathways. BIS standards adoption for optical components reduces import dependency for research laboratory procurement. Bengaluru and Hyderabad anchor emerging precision optics assembly operations serving domestic ophthalmology demand.
Global Adaptive Optics Market Competitive Landscape
Concentration sits with defense-electronics conglomerates and specialized precision optics fabricators serving divergent end-use qualification protocols. The vendor base spans three tiers: military-grade deformable mirror suppliers with captive coating capabilities, modular research-grade component providers leveraging semiconductor supply chains, and clinical ophthalmology system integrators navigating FDA and EMA pathways. Dominant competitive moves include MEMS fabrication partnerships with Taiwanese and South Korean foundries, and early EU AI Act conformity assessments to capture pricing premiums in European diagnostic markets.
Within the defense-tier segment, Northrop Grumman Corporation and Teledyne Technologies, Inc. occupy positions anchored by US military procurement relationships. Among precision optics specialists, Thorlabs, Inc. and Boston Micromachines Corporation exemplify divergent strategies—modular research laboratory penetration versus MEMS-based compact system design. Adaptica S.r.l. and ALPAO represent European archetypes navigating EMA MDR and EU AI Act compliance frameworks. These named entities serve as structural anchors for understanding how geographic regulatory exposure and end-use concentration shape competitive positioning across the analysis window.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thorlabs, Inc. |
| Iris AO, Inc. |
| Boston Micromachines Corporation |
| Teledyne Technologies, Inc. |
| Adaptica S.r.l. |
| Imagine Optic SA |
| ALPAO |
| Flexible Optical B.V. |
| Others |
Supply & Pricing Matrix
Liquid crystal modulator substitution for entry-level deformable mirrors simultaneously redistributes production toward holographic display supply chains in Taiwan and compresses pricing economics for research-grade wavefront correction hardware.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for custom deformable mirror arrays. Three-tier pricing structure across military-qualified, research-grade, and clinical-economy levels separates coating durability certification from Shack-Hartmann miniaturization scale. Cost compression in ophthalmology tiers intensifies because MEMS foundry capacity expansion in South Korea feeds oversupply into compact actuator markets. Hospital procurement committees exhibit lowest price sensitivity due to bundled service contracts, while Indian tier-2 clinic buyers drive hardest volume negotiations.
Supply Chain Analysis
Germany and Japan anchor dielectric stack deposition equipment and specialty coating chemical production for high-actuator-count mirrors. Taiwan and South Korea feed CMOS detector fabrication and MEMS wafer processing for wavefront sensor miniaturization. Raw material dependencies center on rare-earth-doped sodium excitation lasers, precision optical substrates, and FPGA control chipsets. Single-source vulnerability concentrates in German coating chemical suppliers subject to REACH regulatory restriction. Distribution runs through precision optics distributors with captive installation service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment in FDA 510(k) and EMA MDR pathways creates formidable defensive moats for established adaptive optics vendors, as algorithm-enabled diagnostic modules trigger multi-year approval timelines that software-native entrants cannot shortcut.
For Market Incumbents: Consolidate actuator coating capabilities through backward integration into German and Japanese chemical supply chains to neutralize input vulnerability. Lock in multi-year service contracts with US academic medical centers restructuring capital allocation after IRA-mandated pricing transparency reforms. Priority lever: captive supply of dielectric deposition equipment. For New Entrants and Emerging Players: Differentiate on EU AI Act high-risk conformity completion to capture pricing premiums in European ophthalmology markets before established device manufacturers adapt. Target India's tier-2 corneal topography infrastructure gap with Shack-Hartmann-based screening systems distributed through CDSCO-registered local assembly partnerships. Go-to-market angle: software-as-medical-device submissions with autonomous diagnostic algorithm modules. For Investors and Strategic Acquirers: EU AI Act notified body assessment timelines reshape the acquisition landscape toward established device manufacturers with existing MDR quality management systems. Long-term viability favors vendors controlling FPGA firmware talent pools for real-time wavefront reconstruction. Signal to watch: European Southern Observatory pyramid wavefront sensor procurement specifications for extremely large telescope instrumentation.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Taiwan and South Korean semiconductor capacity lowers per-actuator costs for compact ophthalmology systems. |
| EU AI Act Conformity Assessment | Early notified body completion creates pricing power in high-risk diagnostic algorithm classification. |
| Pyramid Wavefront Sensor Development | European Southern Observatory procurement specifications redistribute value toward CMOS detector suppliers. |
| India Clinical Distribution Network | CDSCO registration pathways and BIS standards adoption reduce import dependency for tier-2 city penetration. |
| Coating Chemical Backward Integration | German and Japanese dielectric stack deposition equipment supply secures input resilience against REACH restrictions. |
Research Methodology
Operator-level perspectives from deformable mirror design engineers, FDA regulatory affairs specialists, European research infrastructure procurement officers, and hospital biomedical engineering directors anchored the qualitative base. Primary interview data combined with secondary validation from EMA MDR submission databases, European Southern Observatory instrumentation specifications, FDA 510(k) clearance records, and semiconductor foundry capex disclosures. Bottom-up component demand modeling triangulated against top-down defense procurement budget analysis across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for MEMS fabrication cost curves and EU AI Act implementation timelines. Segmentation dimensions modeled include product type, technology architecture, application vertical, and end-user procurement authority. CAGRs derived from fitted growth curves applied to defense, medical, and scientific demand trajectories. Industry-specific inputs incorporated directed energy platform deployment schedules and ophthalmology reimbursement pathway evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained defense procurement and stable regulatory pathway timelines; material deviation in semiconductor foundry capacity or EU AI Act risk classification would warrant model refresh. Recalibration cycles align with material shifts in EMA MDR conformity assessment velocity and extremely large telescope construction milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Electro Optical System Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Objective Lens Market
Optical Components
Global Optical Measurement Market
Optical Components
Global Optical Diode Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Optical Sensor Market
Optical Components
Silicon Focus Ring Market
Optical Components
Optical Waveguide Market
Optical Components
Portable Lenses Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Liquid Light Guides Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Optical Cross Connect Market