
 Global Optical Imaging System Market | 2026-2036
Global Optical Imaging System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Imaging System Market Foresight
The EU Green Deal is consolidating sustainability requirements across medical device supply chains, compelling manufacturers to redesign optical imaging platforms for reduced hazardous material content and improved end-of-life recyclability. Carl Zeiss Meditec AG leverages its German manufacturing footprint to preempt REACH compliance costs across European sales channels. Topcon Corporation anchors its competitive position in ophthalmic diagnostics through deep specialization in swept-source optical coherence tomography. Koninklijke Philips N.V. competes by extending its software-integrated imaging ecosystems into ambulatory surgical centers.
An optical imaging system captures, processes, and visualizes light-based signals across ultraviolet, visible, and near-infrared spectra, typically achieving spatial resolutions from sub-micron to millimeter scales depending on the modality and detector array configuration. These systems enable non-invasive structural and functional analysis in biological tissues, semiconductor wafers, and pharmaceutical formulations. Optical coherence tomography dominates hospital procurement budgets due to its established reimbursement codes in retinal and coronary applications, while multispectral imaging represents the fastest-expanding segment as pharmaceutical companies adopt it for real-time quality control in biologics manufacturing. Fluorescence imaging maintains mature margins in research institutions where grant-funded replacement cycles sustain steady instrument demand.
The FDA enforces 510(k) premarket notification requirements for optical imaging devices used in diagnostic and surgical settings, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through EMA-coordinated notified bodies. ISO 13485 certification shapes supplier qualification for component vendors serving Tier-1 manufacturers. Japan's PMDA imposes additional QMS inspection protocols that filter market access for non-domestic entrants. Stakeholders must monitor evolving harmonization gaps between FDA breakthrough device designation pathways and EU MDR conformity assessment timelines to optimize regulatory sequencing for new platform launches.
Market Dynamics
The EU Medical Device Regulation is compressing product launch timelines while academic medical centers in the United States accelerate replacement cycles for pathology imaging suites, creating simultaneous pull and pressure on manufacturer R&D pipelines.
Growth Catalysts
- Swept-source OCT advancement:Ophthalmology departments in Japan are replacing time-domain systems with faster acquisition platforms, expanding diagnostic throughput per clinic day.
- REACH hazardous substance mandates:The EU Green Deal is forcing component suppliers to eliminate restricted materials from optical assemblies, creating first-mover advantage for compliant manufacturers.
- Biologics manufacturing quality control:Pharmaceutical facilities in Germany are installing multispectral imaging lines for real-time protein aggregate detection during fill-finish operations.
Market Restraints
- Detector array supply concentration:CMOS and CCD sensor fabrication concentrates among East Asian foundries, exposing instrument makers to single-source risk during geopolitical trade friction.
- 510(k) evidentiary burden:FDA premarket notification requirements for novel optical coherence tomography applications have lengthened submission preparation cycles by demanding predicate device equivalence demonstrations.
- Fluorescence dye cost volatility:Indocyanine green and near-infrared contrast agent prices fluctuate with pharmaceutical intermediate feedstock markets, squeezing gross margins on surgical navigation systems.
Strategic Opportunities
- Ambulatory surgical center penetration:Outpatient facilities in the United States lack capital budgets for full hospital-grade suites, creating demand for compact, software-integrated optical platforms.
- EU AI Act diagnostic imaging pathway:The regulation's risk-classification framework for AI-enabled image analysis is creating compliance templates that early certifiers can license to late entrants.
- Photoacoustic-optical convergence:Hybrid systems combining optical resolution with acoustic depth penetration are opening vascular imaging applications beyond retinal and coronary markets.
Industry Challenges
- ISO 13485 auditor capacity constraints:Notified body backlogs are delaying quality management system certifications for component vendors, throttling supply chain expansion.
- Legacy PACS integration complexity:New optical imaging platforms must interface with decade-old picture archiving systems in hospital IT environments, extending deployment timelines and service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Imaging System Market |
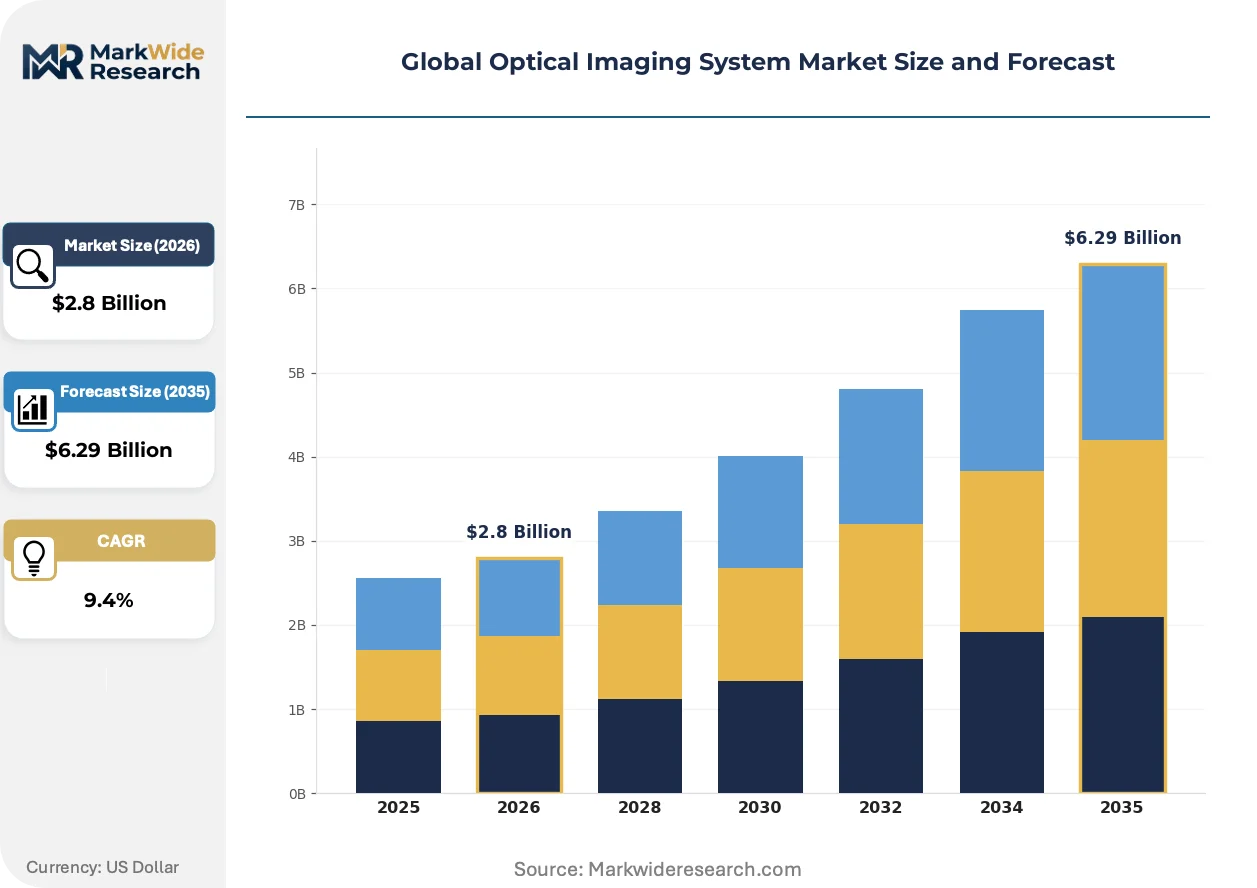
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Confocal Microscopy, Optical Coherence Tomography, Fluorescence Imaging, Multispectral Imaging Technology: Phase Shifting, Time Domain, Frequency Domain, Digital Holography End User: Research Institutions, Clinical Laboratories, Hospitals, Pharmaceutical Companies Application: Biomedical Research, Diagnostics, Drug Development, Material Science |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Canon Medical Systems Corporation, Leica Microsystems, Abbott Laboratories, PerkinElmer, Heidelberg Engineering GmbH, Nidek Co., Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Imaging System Market Shifts & Advancements
Computational imaging and miniaturized photonics are collapsing the performance gap between research-grade and clinical-deployable optical systems, enabling point-of-care migration that was technically infeasible five years ago.
Adaptive optics is rewriting retinal imaging capabilities by correcting wavefront aberrations in real time, achieving cellular-resolution visualization of photoreceptor mosaics. Academic ophthalmology departments in the United States and Germany are installing these platforms for inherited retinal disease research. The technology is compressing the diagnostic value chain by enabling direct visualization of previously subclinical pathology without invasive biopsy.
Japan's PMDA has tightened QMS inspection protocols for foreign manufacturers, adding unannounced facility audits to premarket approval requirements. This policy shift is raising compliance costs for non-domestic entrants while creating structural advantage for Japanese-headquartered suppliers with localized manufacturing. European and North American vendors are responding by establishing captive production facilities in Osaka and Tokyo prefectures.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing optical imaging vendors to compete on transparent service pricing rather than bundled lifetime cost models. This behavioral shift is most visible in German and Japanese hospital systems where centralized purchasing authorities mandate line-item contract separation. Independent service organizations are capturing maintenance revenue that previously flowed to original equipment manufacturers.
Global Optical Imaging System Market Segmentation
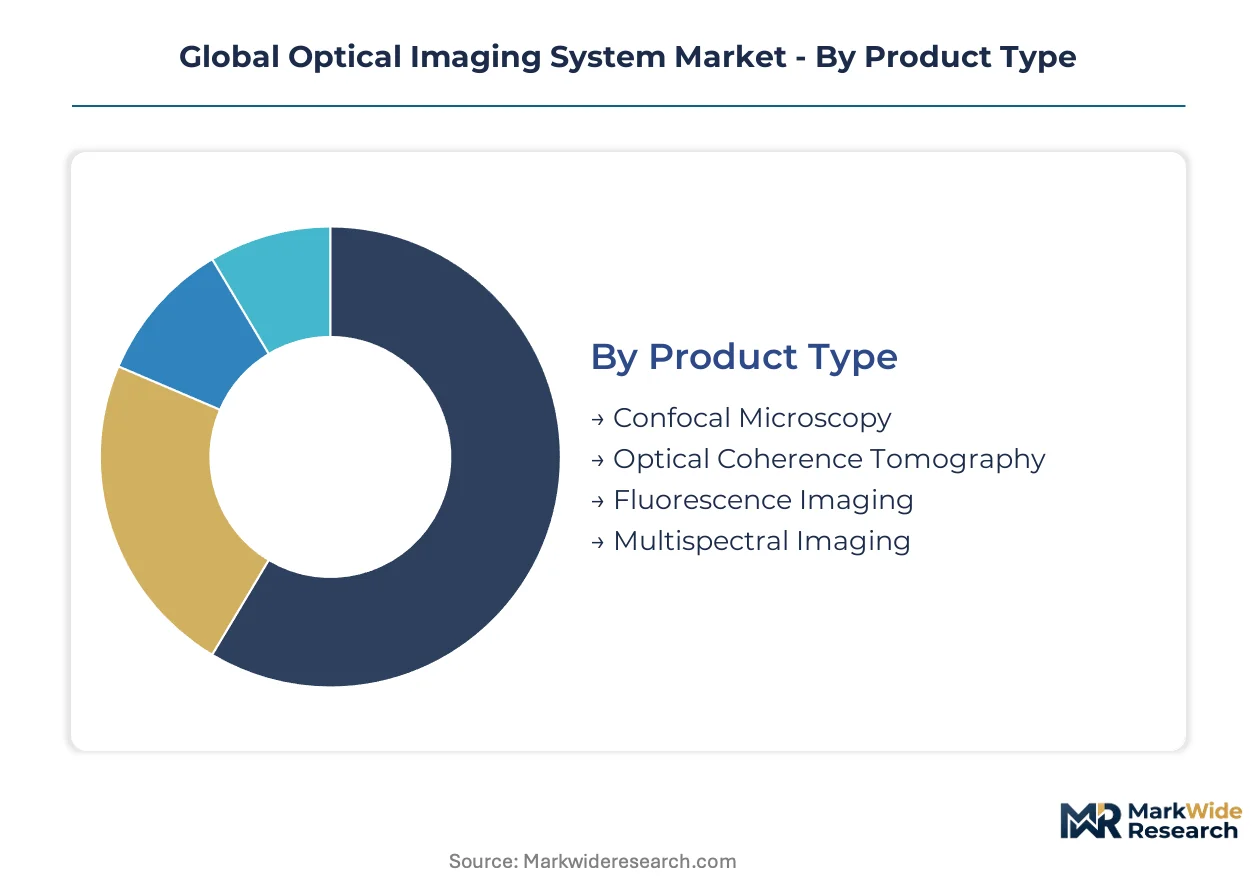
Optical imaging system procurement varies sharply across end-use contexts, with hospital capital committees prioritizing reimbursement alignment while pharmaceutical buyers emphasize throughput metrics. Technical specifications that dominate research grant applications often prove secondary to workflow integration in clinical settings.
Product Type:
Hospital procurement committees weight capital allocation against established reimbursement codes and service revenue potential.
- Optical Coherence Tomography:Interferometric imaging achieves micrometer-scale resolution at depths up to 2 millimeters in scattering tissue. Retinal and coronary applications in United States academic medical centers drive replacement cycles as swept-source platforms displace time-domain systems.
- Multispectral Imaging:Simultaneous capture across discrete wavelength bands enables spectral unmixing of chromophore distributions. Pharmaceutical manufacturing facilities in Germany adopt these lines for real-time protein aggregate detection during fill-finish operations, compressing quality control timelines.
- Confocal Microscopy:Pinhole aperture rejection of out-of-plane light delivers optical sectioning for fixed and live-cell imaging.
- Fluorescence Imaging:Excitation-emission spectral separation supports molecular probe visualization in surgical navigation and research microscopy.
Optical Coherence Tomography leads on scale; Multispectral Imaging leads on momentum.
Technology:
Detector array sophistication and computational reconstruction requirements stratify manufacturing cost structures across modalities.
- Frequency Domain:Fourier-transform detection of spectrally encoded interference enables single-shot depth profiling at acquisition speeds exceeding 100,000 A-scans per second. Ophthalmology departments in Japan specify these platforms for high-throughput glaucoma screening protocols.
- Digital Holography:Numerical reconstruction of object wavefronts from single interferograms permits post-capture focus adjustment and phase quantification. Semiconductor metrology labs in Germany deploy these systems for wafer defect inspection without mechanical scanning.
- Phase Shifting:Multiple interferogram acquisition with controlled phase increments enables sub-wavelength surface profiling for precision manufacturing quality control.
- Time Domain:Mechanical reference arm scanning provides depth-resolved reflectivity mapping at lower acquisition rates suitable for static sample characterization.
Frequency Domain dominates installed base; Digital Holography gains share fastest.
End User:
Budget authority and replacement cycle timing diverge between grant-funded research environments and revenue-generating clinical operations.
- Hospitals:Capital equipment committees prioritize platforms with established CPT reimbursement codes and ambulatory surgical center compatibility. United States health systems are retrofitting pathology departments with multispectral imaging suites as centralized purchasing authorities unbundle service contracts.
- Pharmaceutical Companies:Manufacturing quality control departments specify imaging systems for in-line process analytical technology. Facilities in Germany and Japan install fluorescence and multispectral platforms for biologics aggregate detection and container closure integrity verification.
- Research Institutions:Principal investigator grant funding sustains replacement cycles for advanced microscopy platforms without clinical revenue requirements.
- Clinical Laboratories:Reference lab networks deploy standardized imaging protocols for histopathology and cytology screening at scale.
Hospitals lead on scale; Pharmaceutical Companies lead on momentum.
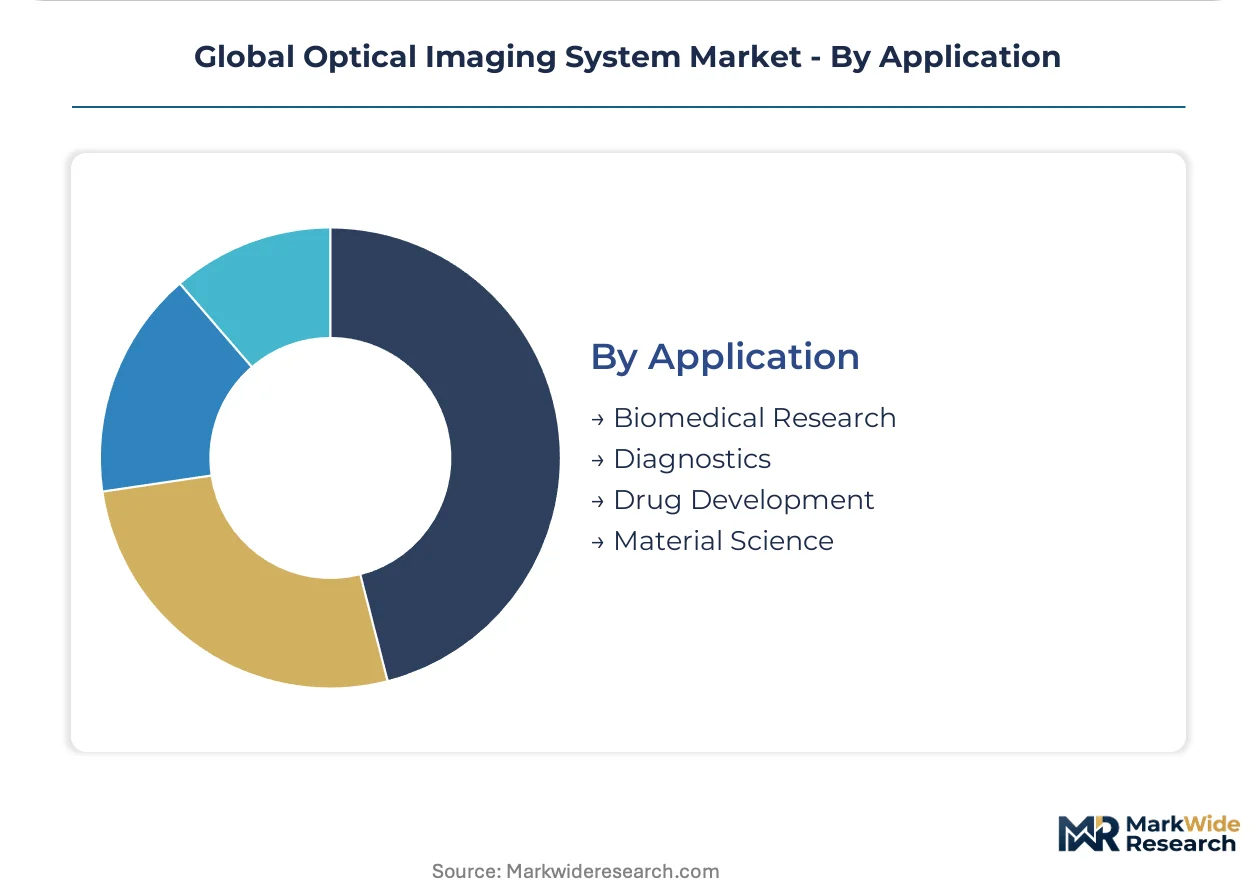
Application:
Regulatory pathway complexity and evidence requirements shape platform specification across use cases.
- Diagnostics:FDA 510(k) and EU MDR conformity assessment frameworks govern premarket authorization for clinical imaging devices. Retinal OCT and intraoperative fluorescence navigation systems in United States hospitals command premium pricing through established reimbursement.
- Drug Development:Preclinical imaging supports pharmacokinetic modeling and toxicity assessment in regulated laboratory environments. Contract research organizations in Germany integrate optical coherence tomography into ocular safety study protocols for biologic therapeutics.
- Biomedical Research:Grant-funded investigators pursue adaptive optics and computational imaging advances without immediate commercialization constraints.
- Material Science:Industrial quality control applications exploit sub-micron resolution for semiconductor and advanced materials characterization.
Diagnostics leads on scale; Drug Development leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision optics manufacturing in the late nineteenth century, establishing Jena and Oberkochen as foundational clusters for modern medical imaging instrumentation. This historical lineage shapes contemporary procurement patterns and regulatory frameworks across the industry's primary demand centers.
United States
Academic medical centers in Boston and the Research Triangle drive replacement cycles for pathology imaging suites. FDA 510(k) premarket notification requirements govern diagnostic device authorization, compressing product launch timelines for novel optical coherence tomography applications. The Mayo Clinic in Rochester anchors demand for intraoperative fluorescence navigation systems.
Germany
Pharmaceutical manufacturing facilities in Baden-Württemberg install multispectral imaging lines for biologics quality control. REACH hazardous substance mandates under the EU Green Deal compel component suppliers to eliminate restricted materials from optical assemblies. The Stuttgart-Oberkochen corridor concentrates swept-source OCT development for ophthalmic diagnostics.
Japan
Ophthalmology departments in Tokyo and Osaka specify frequency-domain platforms for high-throughput glaucoma screening protocols. PMDA QMS inspection protocols now include unannounced facility audits for foreign manufacturers, raising compliance costs for non-domestic entrants. Nagoya hosts captive production facilities established by European and North American vendors seeking market access.
China
Domestic hospital procurement committees prioritize platforms with NMPA registration and ambulatory surgical center compatibility. NMPA medical device classification rules govern premarket approval pathways for optical imaging equipment. Shanghai and Shenzhen clusters concentrate CMOS detector array integration for cost-competitive instrument manufacturing.
Switzerland
Precision manufacturing traditions in the Jura Arc support component supply for Tier-1 optical system vendors. Swissmedic conformity assessment procedures align with EU MDR timelines while maintaining distinct quality documentation requirements. Basel's pharmaceutical corridor generates demand for drug development imaging systems in contract research organizations.
Global Optical Imaging System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the optical imaging system value chain, creating a tiered competitive structure where foundry-dependent instrument makers vie against vertically integrated specialists. The vendor base concentrates around three strategic archetypes: German-Japanese precision optics conglomerates with captive manufacturing, diversified healthcare technology platforms extending software-integrated ecosystems, and specialized ophthalmic diagnostic firms with deep modality expertise. Dominant competitive moves include geographic expansion through captive production facilities in high-barrier markets and strategic partnerships to secure detector array supply.
Among German-origin precision optics groups, Carl Zeiss Meditec AG exemplifies the vertically integrated archetype with manufacturing anchored in Oberkochen. Japanese specialists Topcon Corporation and Nidek Co., Ltd. occupy positions within the ophthalmic diagnostic tier, reflecting deep specialization in swept-source optical coherence tomography. Koninklijke Philips N.V. represents the diversified healthcare platform model, extending imaging ecosystems into ambulatory surgical centers through software-integrated architectures.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Canon Medical Systems Corporation |
| Leica Microsystems |
| Abbott Laboratories |
| PerkinElmer |
| Heidelberg Engineering GmbH |
| Nidek Co., Ltd. |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Performance-grade bifurcation between FDA-cleared surgical platforms and research-grade microscopy systems manifests in both procurement economics and component sourcing strategies. Hospital capital committees in the United States pay premiums for 510(k)-cleared devices with established CPT reimbursement codes, while pharmaceutical buyers negotiate volume-based pricing for multispectral quality-control lines without clinical regulatory overhead. This tiered demand structure concentrates high-margin assembly in Germany and Japan while pushing cost-optimized manufacturing toward Chinese CMOS integration clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs optical imaging system transactions, with FDA breakthrough designation and ISO 13485 certification grade serving as primary price differentiation drivers. Cost compression in the economy tier is intensifying because Chinese instrument makers are capturing ambulatory surgical center contracts with NMPA-registered platforms. Research institutions demonstrate the least price sensitivity due to grant-funded replacement cycles, while outpatient facilities in the United States exhibit acute budget constraints.
Supply Chain Analysis
Precision optics manufacturing workforce availability in Oberkochen, Jena, and Nagoya anchors high-end instrument production, while CMOS and CCD detector fabrication concentrates in Taiwan, South Korea, and mainland China. Optical-grade glass, specialized interferometer components, and sapphire windows constitute critical input dependencies. Single-source vulnerability in East Asian foundry capacity exposes instrument makers to geopolitical trade friction. Distribution runs through hospital GPO contracts, pharmaceutical direct procurement, and research institution grant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Optical Imaging System Market compounds steadily as biologics manufacturing quality-control mandates expand addressable demand beyond clinical diagnostics. Replacement cycles in academic medical centers and pharmaceutical facilities generate predictable revenue visibility.
For Market Incumbents: Anticipate margin compression from software-integrated platform competition by deepening captive manufacturing control over swept-source OCT engines and securing exclusive detector array allocation agreements. Defend hospital installed base through preemptive adaptive optics upgrades before research-to-clinical translation accelerates. ISO 13485 certification investment represents the critical lever for supply chain qualification. For New Entrants and Emerging Players: Ambulatory surgical centers in the United States present the most penetrable buyer archetype due to unbundled service contract procurement and capital budget constraints that favor compact, software-integrated platforms. White-space targets include photoacoustic-optical hybrid systems for vascular imaging beyond retinal applications and EU AI Act compliance templates for late-entrant licensing. A direct-to-facility sales model bypassing traditional GPO channels offers viable go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where component vendor ISO 13485 certification backlogs throttle supply chain expansion and create acquisition targets with qualified quality management systems. Long-term viability favors vertically integrated precision optics specialists with captive manufacturing in high-barrier regulatory markets. The signal to watch is PMDA unannounced audit enforcement intensity as a proxy for Japanese market access difficulty.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Integrated analysis platforms differentiate hospital procurement decisions beyond hardware specifications. |
| Reimbursement Strategy | CPT code alignment determines capital committee prioritization in United States academic medical centers. |
| CE Marking Pathway | EU MDR clinical evidence requirements compress product launch timelines for novel optical coherence tomography applications. |
| Hospital System Partnership | Long-term service contracts with centralized purchasing authorities in Germany secure replacement cycle visibility. |
| Backward Integration into Detector Arrays | Captive CMOS supply mitigates single-source risk from East Asian foundry concentration. |
Research Methodology
Bottom-up hospital and pharmaceutical facility modeling reconciled against top-down component vendor and foundry tracking forms the analytical core. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and pharmaceutical quality-control directors combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and PMDA premarket approval records. Triangulation across these sources ensures segment-level accuracy.
Historical trendline analysis of replacement cycle timing and procurement budget allocation patterns informs the projection framework. The model segments by product type, technology, end user, application, and regional regulatory cluster across the analysis window. CAGRs derive from fitted growth curves adjusted for reimbursement code expansion, REACH compliance cost pass-through, and biologics manufacturing capacity buildout. Swept-source OCT displacement rates and multispectral imaging pharmaceutical adoption curves constitute key forecast inputs.
Inputs from hospital procurement databases and pharmaceutical capital expenditure disclosures were available through the study window; gaps in real-time foundry capacity utilization introduce uncertainty bands around detector supply assumptions. Forecasts reflect documented replacement cycle assumptions and regulatory timeline estimates. Material deviation in FDA breakthrough device designation velocity or EU MDR notified body capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Raman Amplifier Market
Optical Components
Microchannel Plates Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Silicon Photonics Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Optical Cross Connect Market
Optical Components
Optical Component Tester Market
Optical Components
North America Laser Diode Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Global Optical Coating Equipment Market